
 Virtual Reality Training Market | 2026-2036
Virtual Reality Training Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Training Market Outlook
Capability gaps between headset-integrated platform developers and content-only studios is unwinding competitive tiers across the Virtual Reality Training landscape. Strivr leverages its enterprise sports-training heritage to anchor high-fidelity simulation contracts with Fortune 500 corporations. Microsoft sustains infrastructure dominance through cloud-streamed mixed reality services that extend across military and medical verticals. EON Reality differentiates through geographic reach, operating localized content creation hubs that control regional deployment costs.
Virtual Reality Training denotes immersive, computer-generated environments that render stereoscopic visuals at 90 frames per second or higher to simulate physical tasks without material risk. These systems integrate head-mounted displays, spatial tracking sensors, and haptic feedback peripherals to replicate procedural, combat, or mechanical operations for skill acquisition and assessment. Medical Simulation leads technology investment as hospitals prioritize error-reduction protocols, while Cloud-Based delivery is expanding fastest among mid-market corporate buyers seeking scalable deployment without on-premise hardware. Wearable Devices command narrower margins due to component commoditization, though Immersive Environments retain pricing power through proprietary software licensing.
The FDA's digital health pre-certification program and the EU AI Act's risk-classification framework are reshaping product validation timelines for healthcare and defense applications. OSHA training-mandate equivalency rulings in the United States further determine whether VR modules substitute for live instruction hours. Stakeholders must monitor regulatory divergence between jurisdictions to decide whether to architect single-platform compliance or region-specific builds.
Market Dynamics
Cloud-streamed mixed reality services are compressing hardware ownership requirements while expanding addressable corporate training budgets beyond capital-intensive procurement cycles.
Growth Catalysts
- OSHA training-mandate equivalency rulings:United States employers substitute VR modules for live safety instruction hours, accelerating module procurement across manufacturing and logistics verticals.
- FDA digital health pre-certification:The streamlined validation pathway compresses surgical simulation software approval timelines, drawing healthcare systems toward certified immersive training platforms.
- Haptic feedback peripheral advances:Force-feedback gloves and exoskeleton controllers enable fine-motor skill replication, expanding addressable use cases from cognitive to psychomotor training domains.
Market Restraints
- Display panel supply concentration:Micro-OLED fabrication capacity concentrates among South Korean and Taiwanese foundries, creating input bottlenecks for headset-integrated platform developers.
- EU AI Act risk-classification friction:High-risk system designations for autonomous assessment algorithms extend compliance timelines and legal review costs for European healthcare deployments.
- Motion-to-photon latency thresholds:Sub-20 millisecond rendering requirements demand specialized GPU architectures, excluding mid-market buyers from self-hosted immersive environment deployments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Domestic assembly incentives for wearable devices reduce landed costs for regional training providers serving South Asian corporate and defense buyers.
- Generative AI content pipelines:Procedural scenario generation converges with real-time rendering engines, collapsing bespoke simulation development cycles from months to days.
- Saudi Vision 2032 healthcare infrastructure:Greenfield hospital construction creates first-mover advantages for immersive surgical training vendors establishing localized deployment partnerships.
Industry Challenges
- Immersive content developer scarcity:Unity and Unreal Engine specialists with procedural animation expertise command premium compensation, constraining studio scaling velocity.
- Legacy LMS integration complexity:Enterprise buyers demand SCORM and xAPI interoperability, forcing platform vendors to maintain backward-compatible middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Training Market |
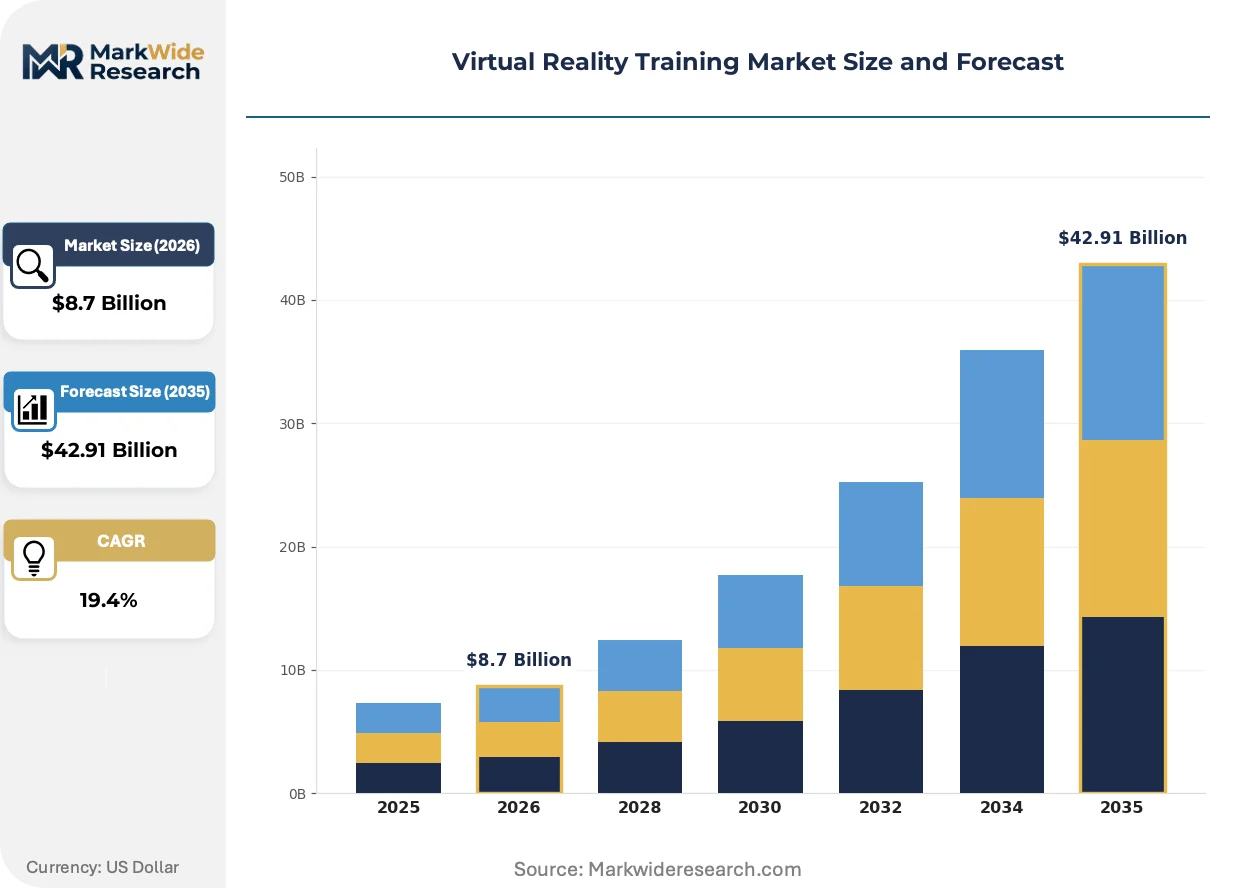
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Medical Simulation, Corporate Training, Military Exercises, Education Technology: Hardware, Software, Wearable Devices, Immersive Environments End User: Healthcare Institutions, Educational Organizations, Defense Agencies, Corporations Delivery Mode: On-Premise, Cloud-Based, Virtual Classrooms, Hybrid Solutions |
| Companies Covered | Strivr, Talespin Reality Labs, Inc., Mursion, Inc., EON Reality, Immerse Inc., Microsoft, Avantis Systems Ltd., Axon Park, Lumeto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Training Market Strategic Shifts
Real-time spatial computing architectures are dissolving boundaries between physical facility requirements and immersive training deployment, redistributing competitive advantage toward software-native vendors.
Foveated rendering with dynamic resolution scaling is fragmenting hardware performance requirements across the installed base. Healthcare simulation buyers adopt eye-tracked headsets to maintain visual fidelity while reducing GPU load. This compression of minimum viable specifications is fragmenting procurement tiers, enabling mid-market hospital networks to access surgical training fidelity previously reserved for academic medical centers.
The EU AI Act's risk-classification framework is resequencing product development roadmaps for autonomous assessment algorithms. Vendors now front-load conformity documentation and human-in-the-loop validation protocols. European healthcare and defense applications face the steepest compliance gradients, prompting region-specific architectural forks rather than unified global platforms.
Subscription-based content licensing is displacing perpetual software purchases across corporate training procurement. Mid-market buyers favor per-seat monthly arrangements that bundle hardware refresh cycles and content updates. This preference shift is most pronounced in United States Fortune 500 manufacturing and logistics verticals, where training budgets align with operational expenditure accounting rather than capital allocation cycles.
Virtual Reality Training Market Segmentation
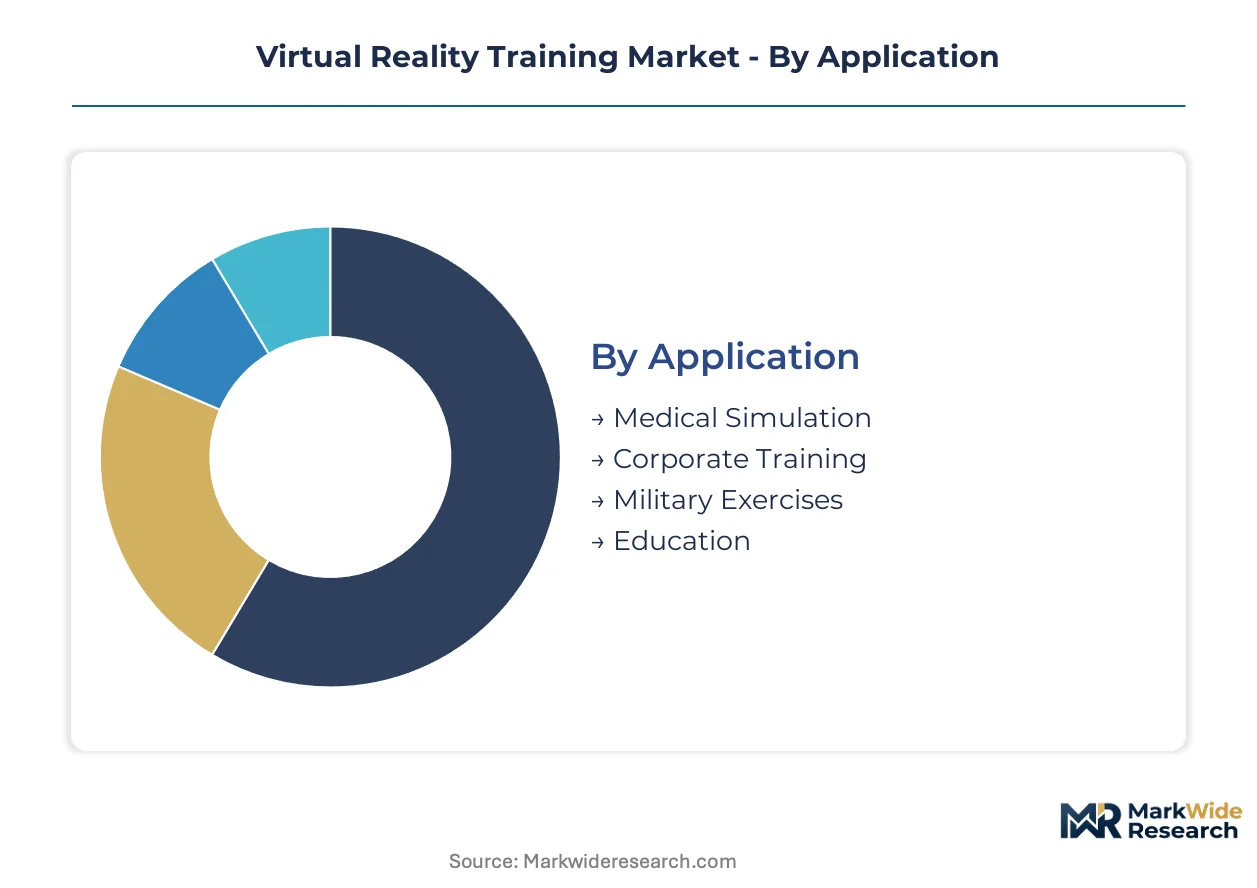
Segmentation in Virtual Reality Training reveals how procurement authority, technical requirements, and budget cycles diverge across buyer types. Understanding these fault lines enables vendors to align product architecture with specific channel economics rather than forcing uniform platforms across incompatible use cases.
Application:
Channel mix varies sharply by application, with direct enterprise sales dominating corporate and military contracts while medical simulation flows through specialized healthcare distributors and GPOs.
- Medical Simulation:Surgical modules integrate haptic peripherals and patient-specific anatomical models derived from CT/MRI datasets. Demand clusters at academic medical centers in the United States and Germany where malpractice liability costs drive error-reduction investment. FDA pre-certification pathways compress validation timelines for software-native vendors.
- Corporate Training:Safety compliance and soft-skills modules deploy through HR technology marketplaces and direct SaaS sales. United States manufacturing and logistics buyers substitute VR hours for live OSHA instruction, accelerating procurement cycles beyond traditional capital budgeting.
- Military Exercises:Combat rehearsal and vehicle operation simulators require air-gapped networks and ITAR compliance, restricting vendor pools to cleared defense contractors.
- Education:K-12 and higher education institutions purchase through state procurement frameworks and educational technology cooperatives, prioritizing multi-seat licensing over fidelity.
Medical Simulation dominates installed base. Corporate Training is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive hardware bundles from recurring software subscriptions, with margin profiles inverting across the stack.
- Hardware:Head-mounted displays, base stations, and compute modules constitute the upfront procurement threshold. Micro-OLED panel supply concentrates among South Korean and Taiwanese foundries, creating input bottlenecks for headset-integrated platform developers.
- Software:Simulation engines, content authoring tools, and assessment analytics generate recurring revenue streams. Cloud-streamed delivery is expanding most quickly among mid-market corporate buyers seeking scalable deployment without on-premise infrastructure.
- Wearable Devices:Force-feedback gloves and biometric sensors command narrower margins due to component commoditization, though integration with proprietary platforms sustains differentiation.
- Immersive Environments:CAVE systems and projection-based installations retain pricing power through custom engineering and site-specific calibration requirements.
Software claims the steepest expansion trajectory. Hardware maintains revenue concentration in defense and medical verticals.
End User:
Customer type determines contract structure, with defense agencies demanding multi-year performance-based agreements and healthcare institutions preferring pilot-to-scale arrangements.
- Healthcare Institutions:Hospital networks and surgical training centers prioritize error-reduction protocols and resident assessment integration. EU AI Act risk-classification friction extends compliance timelines for European deployments.
- Defense Agencies:United States military branches and NATO allies anchor procurement volumes through joint simulation environment programs requiring cross-platform interoperability.
- Corporations:Fortune 500 manufacturing and logistics buyers align training budgets with operational expenditure accounting, favoring subscription bundles over capital allocation cycles.
- Educational Organizations:Universities and vocational institutes demand SCORM and xAPI interoperability, forcing backward-compatible middleware layers.
Defense Agencies anchor aggregate contract value. Corporations represent the volume growth engine.
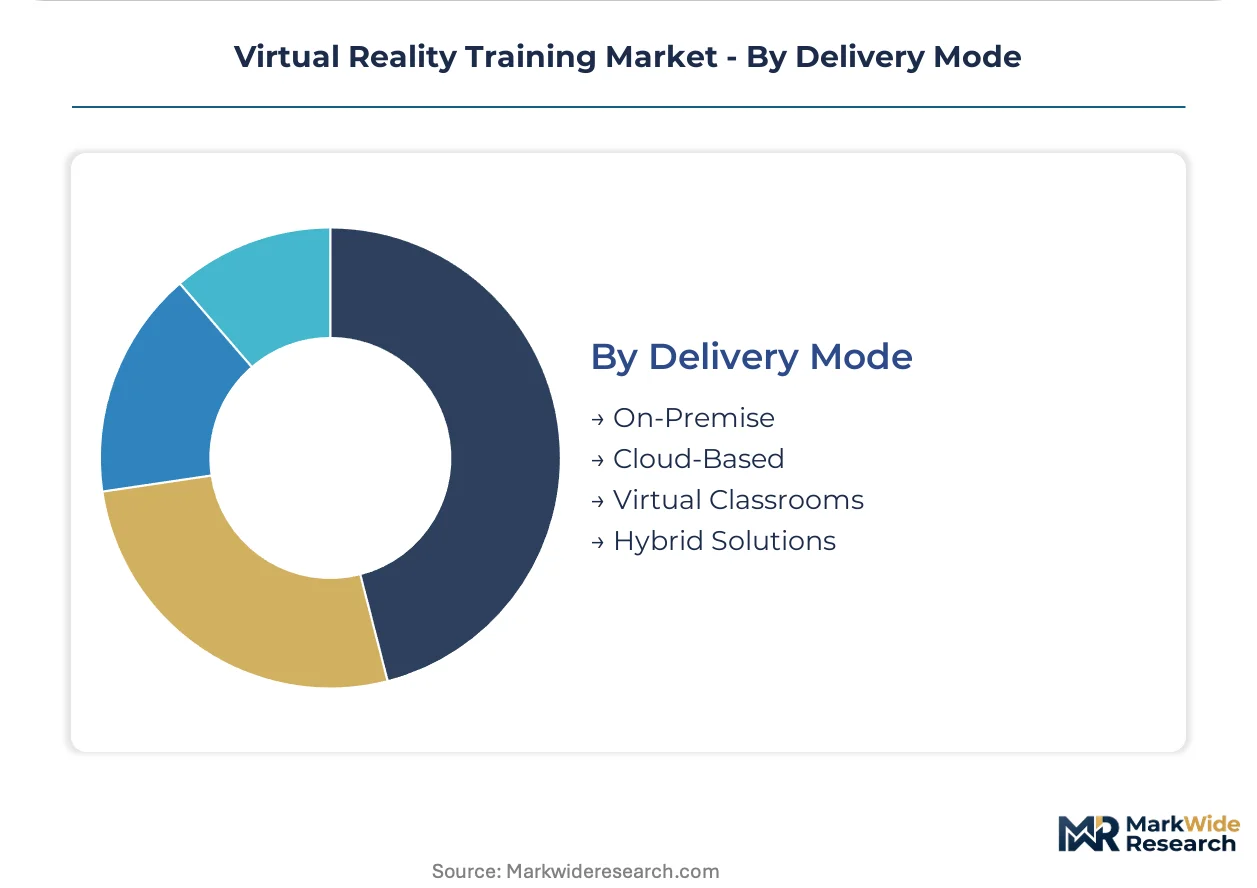
Delivery Mode:
Maturity gradients separate established on-premise deployments from emerging cloud-native architectures, with hybrid solutions capturing transition-phase budgets.
- Cloud-Based:Streamed rendering and centralized content management eliminate hardware ownership requirements. Mid-market buyers in United States manufacturing verticals favor per-seat monthly arrangements that bundle refresh cycles and updates.
- Hybrid Solutions:Edge-rendered graphics with cloud-synced progress tracking balance fidelity with deployment flexibility. This architecture gains share fastest among hospital networks with distributed training facilities.
- On-Premise:Self-hosted installations persist in defense and classified research environments where data sovereignty mandates air-gapped operation.
- Virtual Classrooms:Multi-user synchronous sessions with instructor oversight serve distributed workforce training at logistics and retail enterprises.
On-Premise retains installed base dominance. Cloud-Based is climbing the fastest as procurement shifts from capital to operational expenditure accounting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in VR training services, exporting cloud-streamed simulation platforms to allied defense and healthcare systems while importing specialized haptic hardware components from Asian manufacturing centers. Germany and China follow as net importers of immersive training software, though each cultivates distinct domestic hardware assembly capabilities. Export growth concentrates in subscription-based enterprise modules rather than capital-intensive hardware bundles.
United States
Defense agencies and hospital networks jointly anchor procurement volumes through multi-year performance contracts. OSHA training-mandate equivalency rulings accelerate substitution of VR modules for live safety instruction across manufacturing and logistics verticals. Greater Boston and Seattle metropolitan clusters host concentrated development of surgical simulation software seeking FDA pre-certification pathways.
Germany
Automotive OEMs and industrial machinery producers deploy immersive training for assembly-line error reduction and hazardous equipment operation. The EU AI Act's risk-classification framework extends compliance timelines for autonomous assessment algorithms deployed in healthcare settings. Bavaria's Munich-Stuttgart corridor concentrates medical simulation vendors establishing localized deployment partnerships with university hospitals.
China
Domestic electronics assembly incentives under industrial policy reduce landed costs for regional training providers serving corporate and defense buyers. NMPA digital health guidance accelerates product validation timelines for surgical simulation software. Shenzhen and Shanghai metropolitan clusters concentrate headset-integrated platform developers securing component supply from Taiwanese and South Korean foundries.
India
PLI scheme incentives for electronics manufacturing attract domestic assembly of wearable devices for regional training providers. CDSCO regulatory frameworks for digital health software create structured validation pathways for immersive medical training platforms. Karnataka's Bengaluru-Telangana's Hyderabad corridor concentrates content creation studios serving South Asian corporate and educational buyers.
Saudi Arabia
Vision 2032 healthcare infrastructure investment creates first-mover advantages for immersive surgical training vendors establishing localized partnerships. SFDA digital health guidance streamlines product validation for imported simulation platforms. Riyadh and Jeddah metropolitan clusters anchor greenfield hospital construction specifying integrated immersive training facilities.
Virtual Reality Training Market Competitive Environment
Concentration sits with headset-integrated platform developers possessing captive cloud infrastructure and direct enterprise sales channels. The vendor base stratifies across three tiers: infrastructure-dominant technology conglomerates, specialized immersive content studios, and regional hardware assemblers. Strategic differentiation converges on subscription-based content licensing displacing perpetual software purchases, and geographic expansion through localized content creation hubs controlling regional deployment costs.
Within the enterprise sports-training heritage tier, Strivr occupies a position exemplifying high-fidelity simulation contracts with Fortune 500 corporations. Microsoft sits within the infrastructure-dominant archetype, anchoring cloud-streamed mixed reality services across military and medical verticals. EON Reality represents geographic reach specialization, operating localized content creation hubs that control regional deployment costs in multiple jurisdictions.
| Leading Market Players |
|---|
| Strivr |
| Talespin Reality Labs, Inc. |
| Mursion, Inc. |
| EON Reality |
| Immerse Inc. |
| Microsoft |
| Avantis Systems Ltd. |
| Axon Park |
| Lumeto |
| Others |
Value Chain & Pricing Dynamics
Ninety-day panel allocation lead times for Micro-OLED displays concentrate pricing power among South Korean and Taiwanese foundries, while headset-integrated platform developers absorb inventory carrying costs to secure component allocation against cloud-streamed service competitors.
Pricing Analysis
The customization-premium spread between patient-specific surgical modules and standardized safety training packages spans threefold differentials. Subscription-based SaaS licensing dominates corporate procurement, with per-seat monthly arrangements bundling hardware refresh cycles. Price differentiation hinges on FDA pre-certification tier and haptic peripheral integration depth. Pricing pressure stems from component commoditization in wearable devices, squeezing margins for peripheral specialists while software-native vendors retain pricing power. Fortune 500 manufacturing buyers exhibit highest price sensitivity, negotiating volume discounts against operational expenditure budgets; academic medical centers show lowest sensitivity, prioritizing error-reduction fidelity over unit cost.
Supply Chain Analysis
Strategic stockpiling of Micro-OLED panels and force-feedback actuators characterizes procurement behavior among defense contractors facing ITAR compliance timelines, while mid-market corporate buyers favor just-in-time cloud delivery eliminating hardware ownership. Geographic supply concentration centers on South Korea and Taiwan for display fabrication, China for electronics assembly, and the United States for cloud infrastructure. Raw material dependencies span rare-earth magnets for haptic actuators, high-purity silicon for sensor arrays, and specialized polymers for headset housings. Single-source vulnerability in Micro-OLED fabrication creates structural risk exposure. Distribution runs through direct enterprise sales for defense and healthcare, HR technology marketplaces for corporate training, and educational cooperatives for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA pre-certification and ITAR compliance creates substantial switching costs for institutional buyers.
For Market Incumbents: Secure captive cloud infrastructure capacity to defend against hyperscaler encroachment into mixed reality services. Deepen haptic peripheral integration to raise substitution barriers for software-only entrants. Prioritize OSHA equivalency certification maintenance as regulatory leverage against unvalidated training alternatives. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for surgical simulation software offer the most penetrable entry vector into healthcare verticals. Target mid-market hospital networks in India and Saudi Arabia where greenfield infrastructure lacks incumbent lock-in. Pursue generative AI content partnerships to collapse bespoke development cycles against established studios. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance moats deepen with each validation cycle and procurement framework lock-in. Acquisition targets should display concentrated healthcare or defense revenue, proprietary assessment algorithms, and established GPO or prime contractor relationships. Monitor OSHA equivalency ruling expansions beyond manufacturing into logistics and energy verticals as inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Expansion | Microsoft's Azure-anchored mixed reality services compress hardware requirements for mid-market buyers. |
| FDA Pre-Certification Investment | Streamlined validation pathways accelerate surgical simulation software approval timelines for healthcare entrants. |
| Generative AI Content Pipeline | Procedural scenario generation collapses bespoke simulation development from months to days. |
| Regional Content Hub Establishment | EON Reality's localized creation centers control deployment costs across European and Asian markets. |
| Haptic Peripheral Integration | Force-feedback glove advances expand addressable use cases from cognitive to psychomotor training domains. |
Study Parameters
Cross-validation between primary interviews with surgical training directors, defense procurement officers, corporate HR technology leads, and haptic hardware engineers anchors the qualitative findings against secondary sources including FDA 510(k) filings, OSHA training-equivalency determinations, hospital GPO contract databases, and hyperscaler capex disclosures. Bottom-up vendor revenue aggregation triangulates against top-down addressable market sizing.
Sensitivity analysis across deployment model, end-user vertical, and regional regulatory cluster dimensions structures the analytical framework over the projection horizon. CAGRs derive from segmented adoption curve modeling and replacement cycle analysis. Industry-specific inputs include surgical resident training hour mandates, defense joint simulation environment interoperability requirements, and OSHA live-instruction substitution rulings.
Decision-makers should treat outputs as directional under sustained FDA pre-certification pathway availability and cloud infrastructure cost trajectories; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act risk-classification enforcement crosses thresholds altering European healthcare deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market