
 Augmented Reality (AR) Glasses Market | 2026-2036
Augmented Reality (AR) Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality (AR) Glasses Market Insights
Chinese optical foundries is decoupling from legacy semiconductor lithography methods, enabling independent waveguide etching capacity that serves domestic AR hardware programs. Meta leverages captive silicon photonics R&D to sustain design-to-fab cycles for lightweight display engines. Vuzix anchors enterprise-grade monocular designs for industrial field service, while XREAL competes on consumer tethered glasses with aggressive price positioning in Asian retail channels.
Augmented Reality glasses overlay digital imagery onto physical environments through near-eye optical systems, typically employing waveguide combiners with sub-10-millimeter eye relief and field-of-view ranges between 30 and 50 degrees for commercial viability. Their primary purpose spans hands-free workflow guidance, spatial computing interfaces, and immersive training simulation across enterprise and consumer contexts. Smart glasses dominate current shipment volumes among product categories, though wearable displays capture disproportionate margin pools in medical and defense applications. Optical waveguide technology leads technology segmentation due to slim form-factor requirements, while marker-based tracking matures in education deployments where cost sensitivity overrides spatial fidelity demands.
FCC equipment authorization governs radio-frequency emissions for AR glasses sold in the United States, while FDA reviews software-as-medical-device claims for surgical visualization systems. ETSI standards in Europe address electromagnetic compatibility and optical safety thresholds for near-eye displays. Stakeholders must monitor how divergent electromagnetic and optical safety regimes fragment certification requirements across target markets.
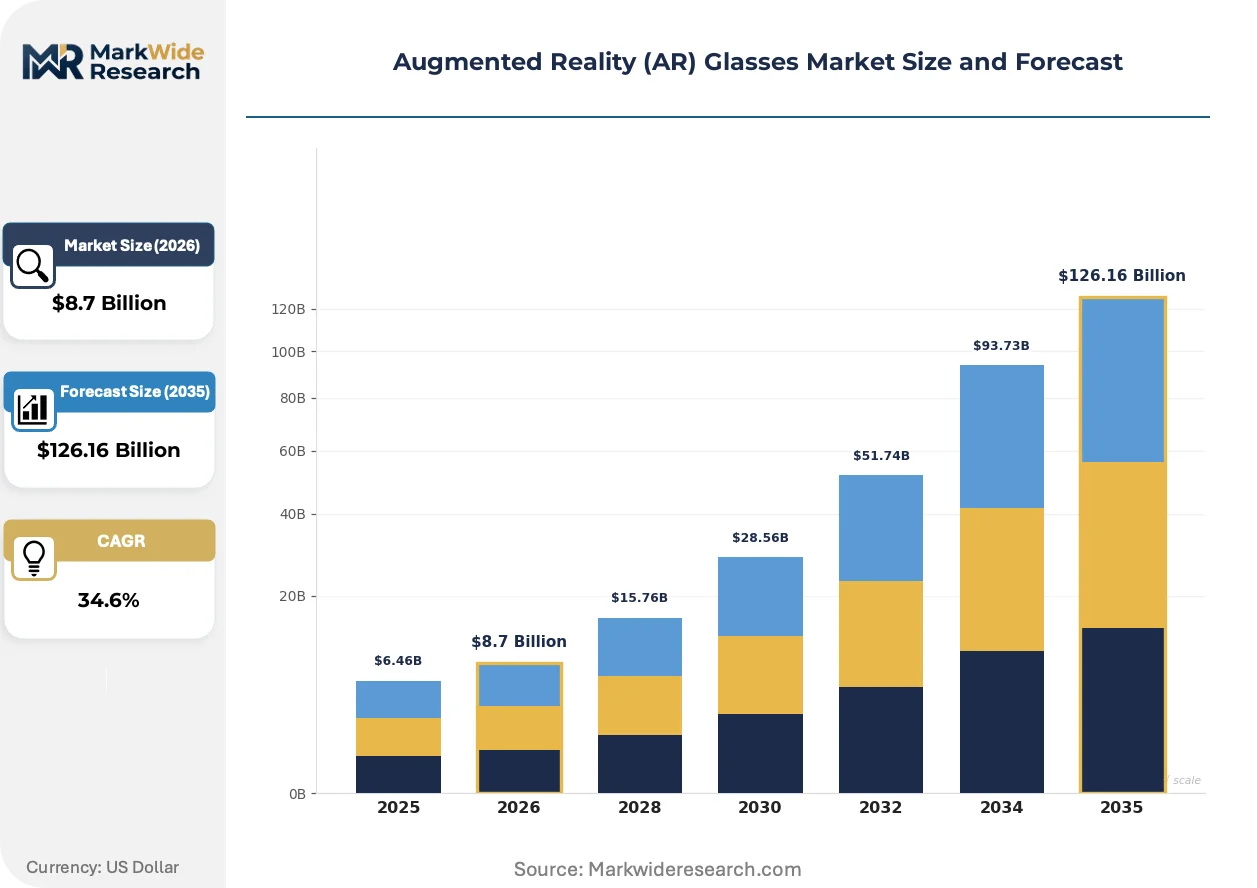
Market Dynamics
Optical waveguide manufacturing concentration in Chinese foundries is compressing component lead times and enabling faster design-to-ship cycles for AR hardware programs worldwide.
Growth Catalysts
- FDA software-as-medical-device pathway:Surgical visualization systems gain accelerated clearance timelines, expanding hospital procurement of AR glasses for operating room integration.
- Optical radiation safety standards:ETSI thresholds for near-eye displays in Europe reduce liability exposure for enterprise deployments, lowering buyer risk aversion.
- Silicon photonics R&D pipelines:Captive in-house development of lightweight display engines reduces dependence on external waveguide suppliers.
Market Restraints
- Rare earth element supply concentration:Neodymium and gallium sourcing bottlenecks from Chinese refiners create input cost volatility for laser diode manufacturers.
- Eye relief miniaturization limits:Sub-10-millimeter optical constraints prevent simultaneous field-of-view expansion and form-factor reduction in consumer-grade designs.
- Smartphone tethering dependency:Processing offload requirements limit standalone functionality, constraining addressable use cases for mobile-first buyers.
Strategic Opportunities
- Industrial field service penetration:Monocular enterprise designs for hands-free workflow guidance remain underdeployed in German automotive assembly plants.
- Spatial computing interface convergence:Integration of gesture recognition with SLAM tracking opens surgical training simulation markets.
- Retail channel disintermediation:Direct-to-consumer tethered glasses distribution bypasses traditional electronics distributors in Asian urban centers.
Industry Challenges
- Optical engineer talent scarcity:Waveguide design expertise concentrates in legacy semiconductor lithography firms, creating recruitment friction for AR-native startups.
- FCC equipment authorization timelines:Radio-frequency emission testing for Wi-Fi and Bluetooth modules extends product launch schedules by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality (AR) Glasses Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Wearable Displays, Heads-Up Displays, Augmented Displays Technology: Optical Waveguide, Plane-Reflecting, Projection-Based, Marker-Based End User: Retail, Healthcare, Military, Education Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Vuzix, Google, Meta, RayNeo, RealWear, Snap Inc., Magic Leap, HTC VIVE, XREAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality (AR) Glasses Market Trends and Innovations
Diffractive waveguide architectures are compressing optical engine thickness while expanding eyebox uniformity, fundamentally altering competitive positioning between consumer and enterprise product tiers.
Surface-relief grating waveguides is overtaking holographic optical elements as the dominant combiner technology for sub-3-millimeter display stacks. Enterprise buyers in logistics and field service are adopting these thinner modules for all-day wear comfort. The shift is overtaking incumbent prism-based optics in price-sensitive education deployments where bulk tolerance is lowest.
EU MDR classification for AR-assisted surgical navigation systems is tightening clinical evidence requirements for software-as-medical-device claims. European notified bodies now demand prospective validation studies for optical overlay accuracy in spine and orthopedic procedures. German hospital procurement committees are delaying pilot programs pending harmonized CE marking interpretations across member states.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software platforms rather than sourcing displays and tracking systems separately. Industrial maintenance divisions now specify bundled AR glasses with pre-loaded workflow guidance applications. This concentration is most visible in Japanese automotive manufacturing where plant managers prioritize single-source accountability for downtime-critical deployments.
Augmented Reality (AR) Glasses Market Segmentation
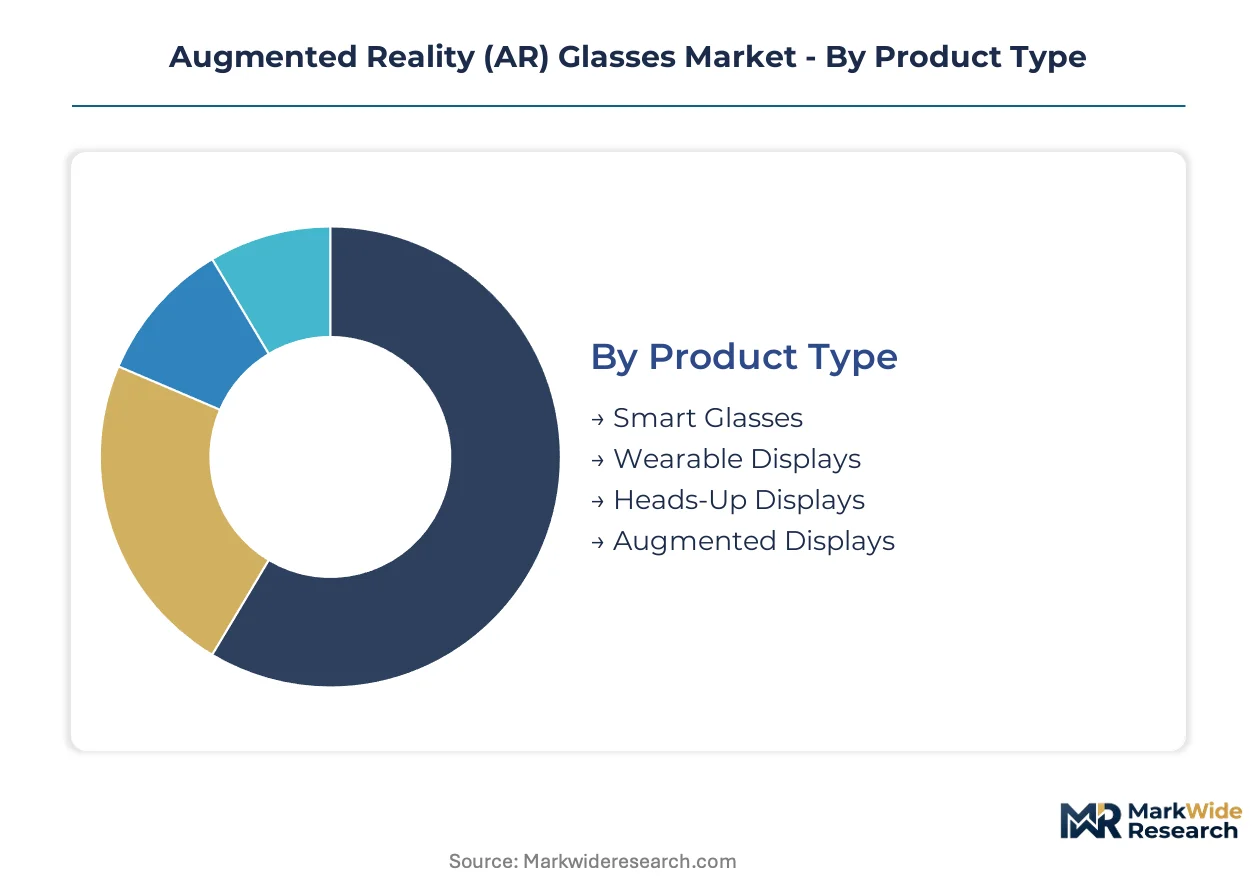
AR glasses segmentation reveals divergent certification burdens across product tiers. FDA software-as-medical-device pathways constrain surgical visualization systems, while FCC equipment authorization governs consumer tethered designs. Enterprise buyers prioritize optical radiation safety compliance under ETSI thresholds for near-eye displays.
Product Type:
FDA 510(k) clearance requirements apply to surgical visualization systems, while FCC Part 15 governs radio-frequency emissions for consumer tethered devices. Military procurement specifications impose additional optical performance standards.
- Smart Glasses:Monocular and binocular designs with sub-50-degree field-of-view dominate current shipment volumes. Demand concentrates in German automotive assembly plants for hands-free workflow guidance, driven by ETSI electromagnetic compatibility thresholds that reduce liability exposure. Leading the category by volume: Smart Glasses. Growing fastest: Wearable Displays.
- Wearable Displays:Near-eye optical systems with waveguide combiners and sub-10-millimeter eye relief command disproportionate margin pools. Medical and defense applications in the United States drive procurement, constrained by FDA device classification timelines and ITAR export controls.
- Heads-Up Displays:Projection-based overlay systems for vehicle and aviation integration.
- Augmented Displays:Full-field immersive overlays requiring SLAM tracking and gesture recognition.
Smart Glasses lead by shipment volume. Wearable Displays expand most quickly in medical applications.
Technology:
Cost tiers separate premium waveguide architectures from projection-based education deployments. Surface-relief grating waveguides command manufacturing premiums while marker-based systems compete on entry-level pricing.
- Optical Waveguide:Diffractive architectures with surface-relief gratings compress optical engine thickness below 3 millimeters. Chinese optical foundries accelerate design-to-ship cycles through independent etching capacity, serving domestic hardware programs and export markets simultaneously.
- Plane-Reflecting:Prism-based combiners retain cost advantages in price-sensitive education deployments where bulk tolerance is lowest. Schools in India and Southeast Asia source these modules for classroom AR integration, prioritizing unit economics over form-factor miniaturization.
- Projection-Based:Micro-display projection systems for heads-up automotive and aviation applications.
- Marker-Based:Camera-dependent tracking for controlled indoor environments with fixed reference points.
Optical Waveguide captures the steepest expansion trajectory. Plane-Reflecting holds the largest installed base in education.
End User:
Application-specific requirements dictate hardware specifications. Surgical navigation demands sub-millimeter overlay accuracy, while military procurement prioritizes all-weather durability.
- Healthcare:Surgical visualization and remote consultation systems require FDA software-as-medical-device validation. United States hospitals expand operating room integration, though EU MDR classification tightens clinical evidence requirements for spine and orthopedic procedures.
- Military:Ruggedized monocular designs with night-vision compatibility and secure radio links. Procurement concentrates in domestic defense programs with ITAR-controlled component sourcing.
- Retail:Consumer tethered glasses for virtual try-on and wayfinding applications.
- Education:Cost-optimized marker-based systems for classroom simulation and training.
Healthcare leads by average selling price. Retail scales fastest in Asian direct-to-consumer channels.
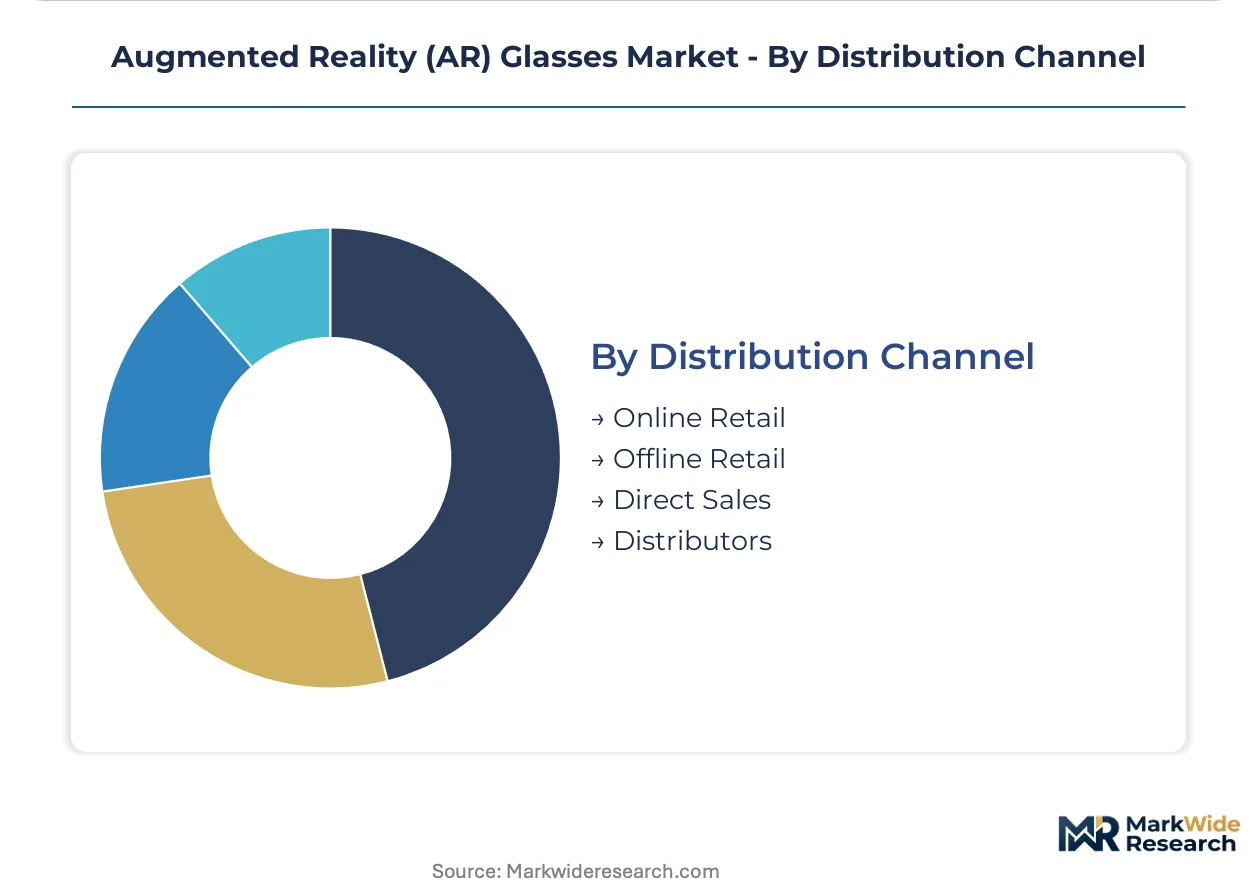
Distribution Channel:
Customer type separates enterprise consolidated procurement from consumer fragmented purchasing. Industrial buyers demand bundled hardware-software platforms with single-source accountability.
- Direct Sales:Enterprise contracts with pre-loaded workflow guidance applications dominate Japanese automotive manufacturing. Plant managers specify integrated platforms for downtime-critical deployments, consolidating vendor relationships around single-source accountability.
- Online Retail:Direct-to-consumer tethered glasses distribution bypasses traditional electronics distributors in Asian urban centers. XREAL and similar brands compete on aggressive price positioning through e-commerce channels.
- Offline Retail:Electronics distributors and carrier stores for consumer smart glasses.
- Distributors:Value-added resellers serving mid-market enterprise accounts with implementation support.
Direct Sales commands the highest contract values. Online Retail gains share fastest in consumer tethered segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth element refining capacity in China anchors upstream supply chains for laser diode manufacturing. Optical waveguide etching foundries cluster in Shenzhen and Suzhou, compressing component lead times for domestic hardware programs. These feedstock localities shape regional competitive positioning across the forecast window.
United States
FDA software-as-medical-device pathways accelerate surgical visualization clearances for hospital operating room integration. FCC equipment authorization governs radio-frequency emissions for Wi-Fi and Bluetooth modules in consumer tethered designs. Greater Boston hosts surgical navigation startups validating optical overlay accuracy for spine procedures.
China
Domestic optical waveguide manufacturing and consumer electronics supply chains accelerate local brand development in retail channels. MIIT standards for electromagnetic compatibility shape product certification timelines for tethered glasses. Shenzhen anchors design-to-ship cycles for export markets through independent etching capacity at optical foundries.
Germany
ETSI thresholds for near-eye displays reduce liability exposure for enterprise deployments in automotive assembly plants. EU MDR classification tightens clinical evidence requirements for AR-assisted surgical navigation systems. Bavaria concentrates industrial field service pilot programs pending harmonized CE marking interpretations.
Japan
METI procurement specifications prioritize integrated hardware-software platforms with single-source accountability for downtime-critical deployments. JIS standards address optical radiation safety for near-eye displays in manufacturing environments. Nagoya automotive manufacturing clusters specify bundled AR glasses with pre-loaded workflow guidance applications.
South Korea
MFDS reviews software-as-medical-device claims for remote consultation systems in hospital networks. Domestic silicon photonics R&D pipelines sustain captive design-to-fab cycles for lightweight display engines. Seoul Capital Area concentrates consumer electronics distribution for tethered glasses competing on aggressive price positioning.
Augmented Reality (AR) Glasses Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in consumer tethering and enterprise workflow guidance. The vendor base separates into three maturity tiers: captive silicon photonics developers, optical waveguide integrators, and software-platform bundlers. Strategic archetypes include display engine specialists, enterprise monocular designers, and direct-to-consumer price competitors. Dominant competitive moves center on backward integration into waveguide manufacturing and geographic expansion through Asian retail channel disintermediation.
Among Silicon Valley-based technology conglomerates, Meta and Google occupy positions representing captive R&D investment in lightweight optical engines. XREAL exemplifies the direct-to-consumer archetype through e-commerce distribution in Asian urban centers. Vuzix anchors the enterprise-grade tier for industrial field service deployments requiring single-source accountability.
| Leading Market Players |
|---|
| Vuzix |
| Meta |
| RayNeo |
| RealWear |
| Snap Inc. |
| Magic Leap |
| HTC VIVE |
| XREAL |
| Others |
Pricing and Supply Chain Analysis
Neodymium and gallium spot price volatility from Chinese refiners cascades through laser diode manufacturing into three-tier pricing structure across premium, standard, and economy levels for AR optical engines. Buyers in medical and defense segments absorb premium tier costs for FDA-validated waveguide modules, while education procurement committees in India and Southeast Asia select economy-tier prism-based alternatives where bulk tolerance outweighs form-factor demands.
Pricing Analysis
Warranty bundling separates enterprise-grade AR hardware from consumer tethered glasses, with industrial field service contracts including multi-year optical calibration service while Asian retail channels sell bare devices. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization level, with FDA 510(k) cleared surgical visualization systems commanding the highest tier. Cost compression in consumer tethered segments is intensifying because XREAL and similar brands compete on aggressive price positioning through direct-to-consumer distribution. Education buyers exhibit greatest price sensitivity, while United States hospital procurement committees show lowest sensitivity due to liability-driven quality requirements.
Supply Chain Analysis
Dual-sourcing requirements from Japanese automotive manufacturing clusters mandate qualification of at least two waveguide suppliers for downtime-critical deployments, forcing vendors to maintain relationships with both Chinese and South Korean optical foundries. Geographic supply concentration centers on China for rare earth refining and waveguide etching, South Korea for silicon photonics R&D, and Germany for precision optical assembly equipment. Raw material dependencies draw from neodymium and gallium for laser diodes, photoresist materials for grating fabrication, and high-index glass substrates for waveguide substrates. Single-source vulnerability concentrates in Chinese rare earth element refining capacity. Distribution runs through direct enterprise contracts for industrial applications and e-commerce platforms for consumer tethered glasses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR glasses market sits in a technology-transition phase where surface-relief grating waveguides displace holographic optical elements and prism-based legacy optics across commercial tiers.
For Market Incumbents: To counter aggressive price positioning from Asian direct-to-consumer entrants, Meta and Google should deepen backward integration into captive silicon photonics R&D for lightweight display engines while consolidating enterprise vendor relationships through bundled hardware-software platforms with single-source accountability clauses. FDA software-as-medical-device pathway investments will defend surgical visualization margins against emerging optical engine specialists. For New Entrants and Emerging Players: Begin with underpenetrated industrial field service segments in German automotive assembly plants, where ETSI electromagnetic compatibility thresholds have delayed pilot programs pending harmonized procurement interpretations. Target education deployments in India and Southeast Asia with cost-optimized marker-based systems, leveraging local distribution partnerships to bypass established electronics distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor optical waveguide integrators with existing Chinese foundry relationships during periods of rare earth price volatility. Long-term viability over the next decade hinges on acquisition targets possessing independent etching capacity or captive silicon photonics pipelines rather than pure software-platform bundlers. Watch FDA 510(k) clearance velocity for surgical navigation startups as the signal indicating inflection toward medical-grade margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waveguide Manufacturing | Captive etching capacity at Shenzhen optical foundries reduces neodymium cost exposure and compresses design-to-ship cycles. |
| FDA Software-as-Medical-Device Submission | Accelerated 510(k) clearance for surgical visualization systems opens hospital operating room procurement budgets in the United States. |
| Direct-to-Consumer Channel Launch | E-commerce distribution in Asian urban centers bypasses traditional electronics distributors and enables aggressive price positioning. |
| Enterprise Platform Bundling | Pre-loaded workflow guidance applications with hardware create single-source accountability valued by Japanese automotive plant managers. |
| Silicon Photonics R&D Partnership | Collaboration with South Korean display engine developers sustains captive design-to-fab cycles for sub-3-millimeter optical stacks. |
Research Methodology
Document review covered FDA 510(k) filings, FCC equipment authorization databases, ETSI electromagnetic compatibility standards, and MIIT certification records, complemented by interviews with optical design engineers at waveguide foundries, procurement managers at German automotive manufacturers, regulatory affairs specialists at surgical navigation startups, and channel partners in Asian consumer electronics distribution. Secondary validation drew from SEC filings of publicly traded AR hardware vendors, customs trade data for rare earth element imports, and hospital procurement database extracts. Bottom-up shipment estimates by product tier triangulated against top-down market sizing by end-use application.
Unit and revenue outputs across the projection horizon reflect segment-level modeling of product type, technology architecture, end-use vertical, and distribution channel dimensions. CAGRs were derived from regression analysis of historical shipment trajectories, adjusted for technology substitution rates from holographic optical elements to surface-relief grating waveguides and regulatory pathway timelines for software-as-medical-device classifications. Industry-specific forecast inputs included laser diode cost curves, optical foundry capacity expansion announcements, and enterprise pilot program conversion rates.
Underlying measurement precision varies by segment; smart glasses shipment volumes carry tighter precision than wearable displays given consolidated vendor reporting, while surgical visualization systems exhibit wider confidence intervals due to elongated FDA clearance timelines. Forecasts reflect assumptions regarding rare earth supply stability, ETSI optical radiation safety standard harmonization, and smartphone tethering dependency persistence. Deviation in Chinese export controls for neodymium and gallium would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Display Market