
 Metallocene Polyolefin Market | 2026-2036
Metallocene Polyolefin Market Size, Share, and Industry Trends Forecast 2026-2036
Metallocene Polyolefin Market Intelligence
Modular film-grade offerings is broadening buyer choice across converter tiers. ExxonMobil Corporation leverages its Baton Rouge catalyst technology platform to sustain premium positioning in metallocene LLDPE supply. Dow anchors North American supply through its integrated Gulf Coast polyethylene complexes. Borealis AG specializes in differentiated medical-grade formulations that command specification adherence in European healthcare procurement.
Metallocene polyolefins denote polyethylene and polypropylene resins polymerized using single-site metallocene catalysts with narrow molecular weight distribution, typically achieving polydispersity indices below 2.5 and superior optical clarity compared to Ziegler-Natta analogs. These materials serve primary industrial functions in precision packaging, automotive interior components, and sterile medical devices where mechanical consistency and low extractables prove critical. Metallocene LLDPE occupies the dominant volume position among product types due to its penetration in stretch and shrink film applications, while medical applications represent the fastest-expanding application segment as healthcare systems upgrade to lower-leachables packaging. Molded products retain mature margin pools in automotive underhood components where heat-aging resistance specifications favor established catalyst systems.
REACH registration requirements from ECHA govern catalyst residue thresholds for European resin imports, while FDA food-contact notifications shape compliance pathways for U.S. packaging applications. China's GB standards under SAMR jurisdiction are converging toward stricter extractables testing for domestic medical-grade polyethylene production. Stakeholders must monitor catalyst technology licensing costs against regional regulatory divergence to optimize manufacturing footprint decisions.
Market Dynamics
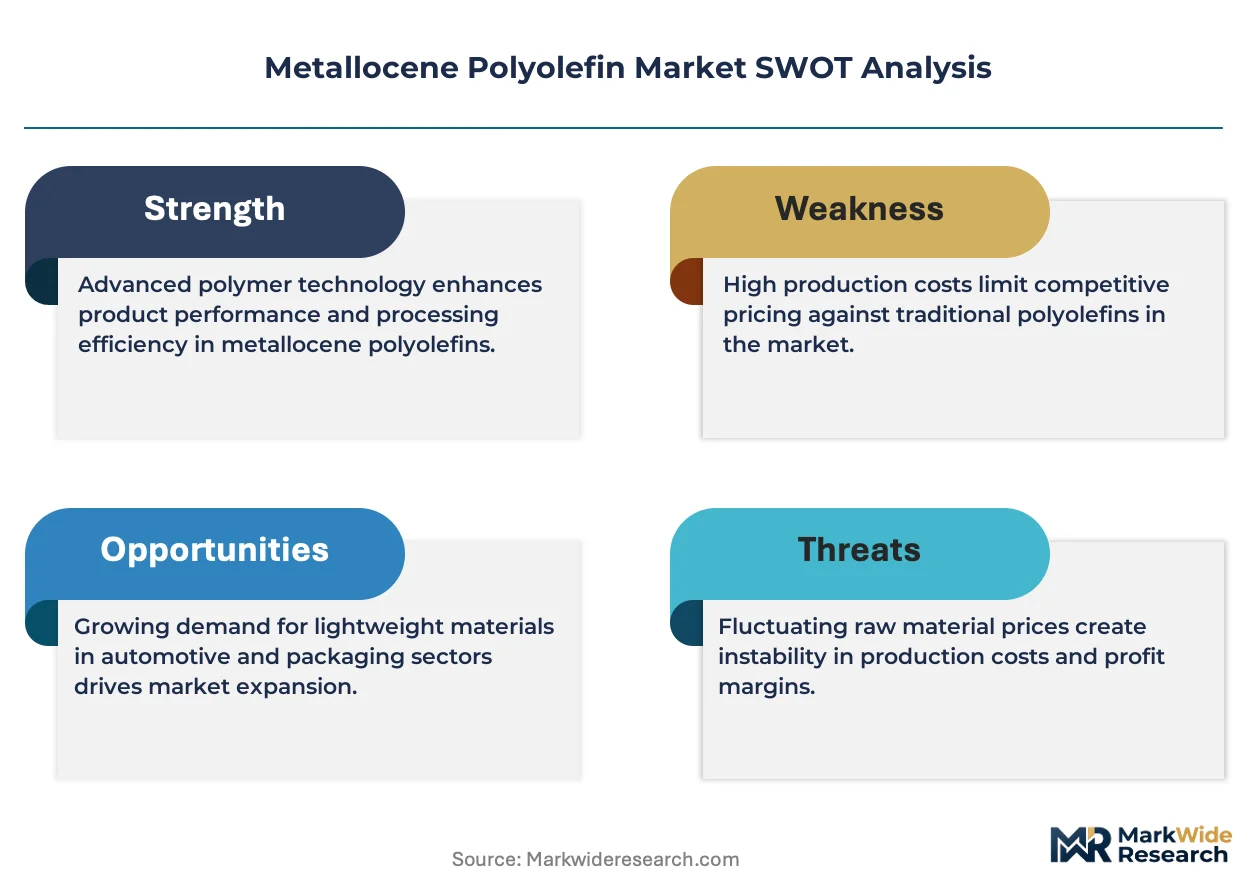
Catalyst technology licensing concentration among three dominant licensors constrains new entrant capacity expansion, while Chinese domestic producers accelerate backward integration into metallocene catalyst manufacturing to escape royalty burdens.
Growth Catalysts
- Single-site catalyst advances:Next-generation constrained-geometry catalysts enable multimodal molecular architectures, opening high-performance automotive underhood applications previously reserved for engineering thermoplastics.
- REACH Article 33 thresholds:ECHA-mandated catalyst residue limits below 0.1% by mass for food-contact articles are disqualifying Ziegler-Natta resins from premium European packaging tenders.
- China's specialty resin substitution:Domestic polymer producers under MIIT industrial upgrading directives are commissioning metallocene LLDPE lines to displace Korean and Thai specialty polyethylene imports.
Market Restraints
- Catalyst metal cost volatility:Organometallic precursors containing hafnium and zirconium face price swings tied to rare earth processing bottlenecks in Chinese refining complexes.
- Technical substitution ceiling:Metallocene polypropylenes cannot match the heat-distortion temperatures of polyphenylene sulfide in automotive thermal management components above 150°C continuous service.
- Licensing oligopoly friction:Three licensors control 90% of viable metallocene catalyst patents, extracting per-ton royalties that inflate resin costs 15-25% above commodity polyethylene.
Strategic Opportunities
- Medical device packaging white space:Sterile barrier films for Class III implantable devices represent an underpenetrated segment where extractables testing protocols favor metallocene LLDPE's narrow polydispersity.
- EU MDR migration timelines:Medical Device Regulation recertification deadlines are forcing healthcare converters to validate alternative resin systems, creating specification windows for medical-grade metallocene formulations.
- Circular feedstock convergence:Mass-balance certified recycled content is converging with metallocene catalyst systems, enabling premium pricing for food-contact films with verified post-consumer recycled content.
Industry Challenges
- Organometallic chemist scarcity:Industrial polymerization catalyst development requires PhD-level expertise in coordination chemistry that universities are producing at insufficient rates.
- Multimodal reactor commissioning delays:Gas-phase polyethylene plants with dual-reactor configurations for metallocene resin production face 18-24 month validation timelines before achieving nameplate capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallocene Polyolefin Market |
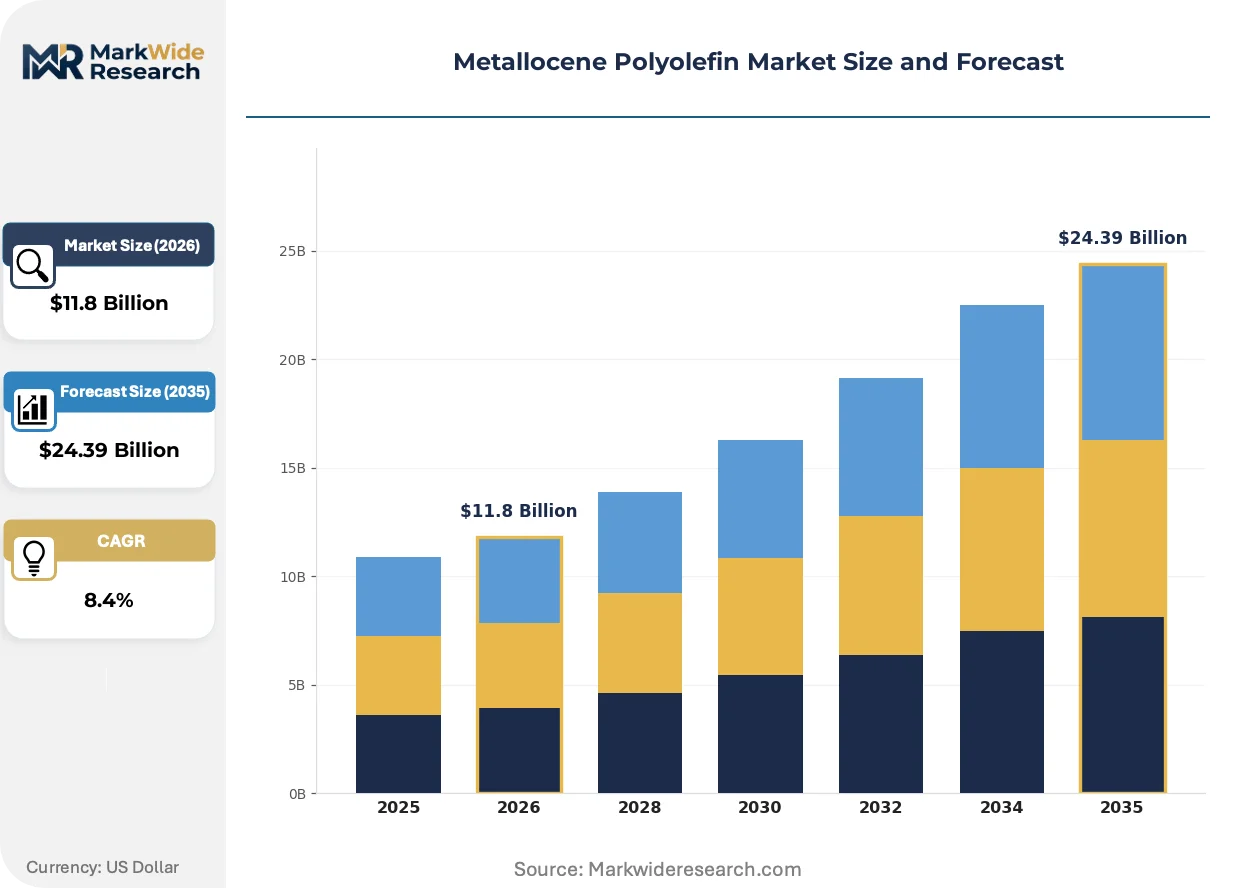
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallocene EPM, Metallocene LLDPE, Metallocene LDPE, Metallocene HDPE Application: Packaging, Molded Products, Automotive Components, Medical Applications End User: Consumer Goods, Healthcare, Automotive, Industrial Manufacturing Form: Granules, Pellets, Powders, Films |
| Companies Covered | SABIC, TotalEnergies, ExxonMobil Corporation, INEOS Group AG, Borealis AG, Dow, Chevron Phillips Chemical Company LLC, Nova Chemicals Ltd., LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallocene Polyolefin Market Strategic Shifts & Innovations
Process intensification and molecular architecture control are compressing development cycles for differentiated grades. Catalyst suppliers and resin producers are co-developing application-specific formulations that bypass traditional trial-and-error compounding.
Hybrid bimodal reactor designs is converging with advanced process control systems to enable real-time molecular weight distribution tuning. Automotive tier suppliers in Germany and Japan are qualifying these resins for interior trim applications demanding both scratch resistance and low VOC emissions. The technology is converging with predictive maintenance platforms to minimize off-spec production during grade transitions.
REACH SVHC candidate list expansions are tightening scrutiny on catalyst residue extractables in food-contact articles. ECHA's 2024-2025 substance evaluation work program specifically targets organometallic catalyst fragments. European flexible packaging converters are responding by demanding batch-level residue certificates from resin suppliers, shifting procurement criteria from price-per-ton to total compliance cost.
Specification-driven procurement consolidation is concentrating buyer power among mega-converters operating continent-scale film production networks. These buyers are unbundling technical service from resin supply contracts, engaging catalyst licensors directly for formulation support. The pattern is most pronounced in North American stretch film markets where three converters command 60% of metallocene LLDPE offtake.
Metallocene Polyolefin Market Segmentation
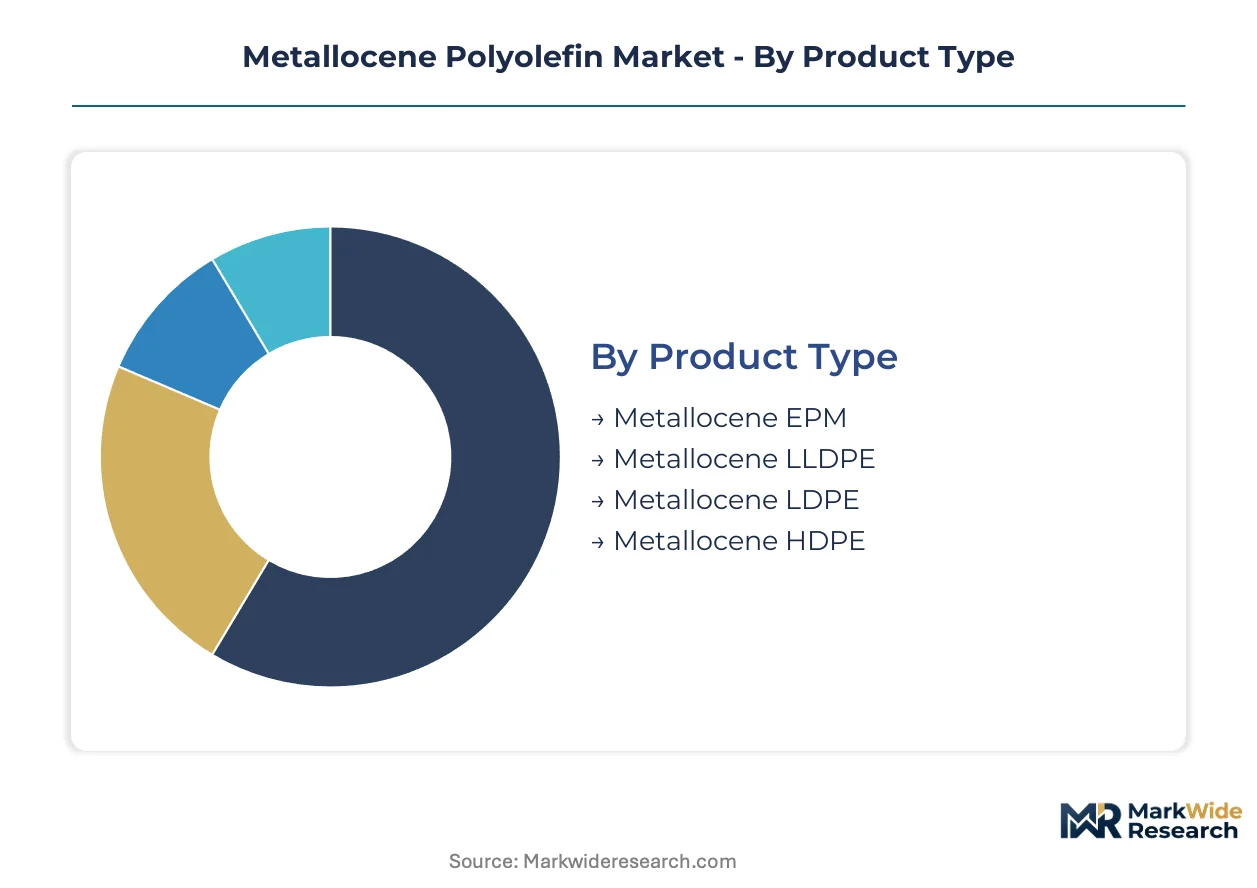
Metallocene polyolefin procurement decisions hinge on molecular architecture specifications that determine processing behavior and end-use performance. Catalyst geometry and comonomer distribution create distinct value tiers that converters navigate against application requirements and regulatory compliance burdens.
Product Type:
Single-site catalyst geometry governs molecular weight distribution breadth, optical clarity thresholds, and seal initiation temperatures across resin grades.
- Metallocene LLDPE:Narrow polydispersity indices below 2.5 deliver exceptional puncture resistance and optical clarity for stretch film applications. Chinese packaging converters under MIIT industrial upgrading directives are scaling procurement of these grades to displace Korean specialty polyethylene imports in food-contact films.
- Metallocene HDPE:Enhanced stiffness-to-toughness ratios suit thin-wall injection molding for rigid healthcare containers. FDA food-contact notification pathways for these resins are tightening extractables testing protocols, favoring suppliers with batch-level residue certification capabilities.
- Metallocene LDPE:Low-density variants with controlled long-chain branching optimize extrusion coating adhesion for multi-layer flexible packaging structures.
- Metallocene EPM:Ethylene-propylene elastomers provide compression set resistance for automotive weathersealing and underhood gaskets.
Metallocene LLDPE leads on scale; medical-grade HDPE formulations lead on momentum.
Application:
Performance specifications and regulatory exposure determine margin capture across end-use segments.
- Packaging:Sterile barrier films and high-clarity food wrapping dominate volume offtake. REACH Article 33 thresholds below 0.1% catalyst residue by mass are disqualifying Ziegler-Natta resins from premium European flexible packaging tenders.
- Medical Applications:Class III implantable device packaging demands extractables profiles that favor narrow polydispersity metallocene grades. EU MDR recertification timelines are forcing healthcare converters to validate alternative resin systems, accelerating specification windows for medical-grade formulations.
- Automotive Components:Interior trim applications in Germany and Japan are qualifying scratch-resistant, low-VOC emission grades for cabin air quality compliance.
- Molded Products:Heat-aging resistance specifications in underhood components favor established catalyst systems with proven long-term property retention.
Packaging commands volume concentration; medical applications exhibit the steepest expansion trajectory.
End User:
Procurement sophistication and compliance burden intensity vary sharply across buyer categories.
- Healthcare:Sterile barrier system manufacturers demand batch-level catalyst residue certificates and extractables documentation. ECHA substance evaluation work programs targeting organometallic catalyst fragments are intensifying supplier qualification requirements.
- Automotive:Tier suppliers coordinate directly with catalyst licensors for formulation support, unbundling technical service from resin supply contracts.
- Consumer Goods:Mega-converters operating continent-scale film production networks concentrate buyer power and drive specification consolidation.
- Industrial Manufacturing:General-purpose applications prioritize cost efficiency over premium performance specifications.
Healthcare leads on specification intensity; automotive leads on direct catalyst licensor engagement.
Form:
Physical presentation determines handling economics and processing equipment compatibility.
- Films:Cast and blown film structures for flexible packaging represent the dominant value capture mode, with real-time molecular weight distribution tuning enabled by hybrid bimodal reactor designs.
- Pellets:Standardized pellet geometry optimizes bulk handling and melt processing consistency for high-volume injection molding operations.
- Granules:Larger particle sizes suit specific compounding and masterbatch integration workflows.
- Powders:Fine particle distributions enable specialized coating and rotational molding applications with surface finish requirements.
Films lead on value concentration; pellets lead on processing standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallocene polyolefin production originated in the United States during the early commercialization of single-site catalyst technology in the 1990s. The industry subsequently diffused to Western Europe and East Asia as licensing networks expanded. Today, manufacturing concentrates in petrochemical corridors with access to ethane feedstock and specialized catalyst expertise.
United States
Gulf Coast ethane crackers supply cost-advantaged feedstock for metallocene LLDPE production. FDA food-contact notification pathways govern catalyst residue thresholds for domestic packaging applications. The Houston-Beaumont-Port Arthur corridor hosts integrated polyethylene complexes with dedicated metallocene-grade production lines.
Germany
Automotive interior trim applications in Bavaria and Baden-Württemberg drive demand for low-VOC emission grades. REACH Article 33 compliance mandates catalyst residue documentation for food-contact articles entering European supply chains. The Cologne-Leverkusen chemical cluster anchors medical-grade formulation development for healthcare converters.
China
Domestic polymer producers under MIIT industrial upgrading directives are commissioning metallocene LLDPE capacity to displace Korean and Thai specialty resin imports. GB standards under SAMR jurisdiction are converging toward stricter extractables testing for medical-grade polyethylene. The Yangtze River Delta petrochemical belt around Shanghai and Ningbo concentrates new catalyst technology licensing activity.
Saudi Arabia
Ethane availability from associated gas production supports cost-competitive polyethylene manufacturing for export markets. The country's national standards body is aligning domestic certification requirements with REACH-equivalent catalyst residue protocols. The Jubail Industrial City complex houses integrated metallocene-grade production targeting European and Asian flexible packaging demand.
Japan
Automotive tier suppliers in Aichi Prefecture and the Kanto region qualify scratch-resistant grades for cabin air quality compliance. METI industrial policy encourages domestic catalyst technology development to reduce royalty dependence on Western licensors. The Chiba-Kashima petrochemical corridor maintains specialized compounding capabilities for medical device packaging applications.
Metallocene Polyolefin Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology licensing and formulation specialization tiers. The market structure consolidates around integrated petrochemical majors with captive catalyst development capabilities and specialized compounders serving healthcare and automotive specification markets. Three archetypes dominate: Gulf Coast ethane-integrated producers, European medical-grade formulators, and Asian converters backward-integrating into resin production. Competitive moves concentrate on catalyst technology licensing negotiations and multimodal reactor capacity additions.
Within the integrated major tier, ExxonMobil Corporation and Dow exemplify Gulf Coast producers with catalyst technology platforms developed in-house. Borealis AG represents the European specialization archetype, with corporate structure indicating Austrian-German origins and focus on differentiated formulation segments. These three entities anchor distinct competitive vectors: ethane cost advantage, medical-grade specification adherence, and automotive application development respectively.
| Leading Market Players |
|---|
| SABIC |
| TotalEnergies |
| ExxonMobil Corporation |
| INEOS Group AG |
| Borealis AG |
| Dow |
| Chevron Phillips Chemical Company LLC |
| Nova Chemicals Ltd. |
| LyondellBasell Industries Holdings B.V. |
| Others |
Cost & Logistics Intelligence
Ethane feedstock indices at Gulf Coast hubs cascade through polyethylene production economics into three-tier pricing structure across premium, standard, and economy levels. Catalyst licensing royalties and regulatory compliance costs compound at each tier, concentrating margin capture among integrated producers with captive catalyst technology.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by catalyst residue certification grade and volume commitment scale. Premium tiers command substantial markups for REACH Article 33-compliant grades with batch-level documentation, while economy tiers face cost compression from Chinese domestic producers scaling metallocene LLDPE output. Healthcare converters demonstrate lowest price sensitivity due to extractables compliance requirements, whereas industrial manufacturing buyers prioritize per-ton economics.
Supply Chain Analysis
REACH and FDA qualification gating restricts viable supplier pools to producers with batch-level catalyst residue certification capabilities. Manufacturing concentrates in the United States, Germany, and China, with ethane feedstock from Gulf Coast crackers and specialized organometallic precursors containing hafnium and zirconium anchoring upstream dependencies. Single-source vulnerability around catalyst technology licensors extracting per-ton royalties feeds into margin pressure, while distribution runs through integrated petrochemical majors and specialized medical-grade compounders serving healthcare specification markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metallocene polyolefin market functions as a stable compounder underpinned by regulatory ratchets that continuously tighten purity specifications and disqualify legacy resin systems.
For Market Incumbents: Anchor market position through backward integration into metallocene catalyst manufacturing to escape royalty burdens from the three-licensor oligopoly, while expanding multimodal reactor capacity in the Gulf Coast corridor to capture ethane cost advantage. Prioritize medical-grade formulation development as EU MDR recertification deadlines force healthcare converters to validate alternative resin systems. For New Entrants and Emerging Players: EU MDR in Europe opens a window for medical device packaging white space where sterile barrier films for Class III implantable devices remain underpenetrated. Target this segment through direct engagement with catalyst licensors for formulation support, bypassing resin supply contract bundling that favors established integrated majors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compounders possessing medical-grade certification infrastructure and direct healthcare converter relationships. Long-term viability hinges on circular feedstock convergence capabilities enabling mass-balance certified recycled content. Watch for catalyst technology licensing renegotiations as Chinese domestic producers accelerate backward integration as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | Escapes per-ton royalty burdens from the three-licensor oligopoly controlling viable patents. |
| Multimodal Reactor Capacity Expansion | Enables real-time molecular weight distribution tuning for automotive interior trim qualifications. |
| Medical-Grade Formulation Development | Captures EU MDR recertification-driven specification windows for Class III device packaging. |
| Circular Feedstock Certification Program | Unlocks premium pricing for food-contact films with verified post-consumer recycled content. |
| Long-term Supply Agreement with Mega-Converters | Secures volume offtake from continent-scale film production networks concentrating buyer power. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with catalyst technology licensors, resin plant managers, healthcare procurement leads, and flexible packaging converters with secondary validation against SEC filings, ECHA substance evaluation programs, customs trade data, and MIIT industrial policy directives. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segment-weighting across product type, application, end user, and form dimensions fed into analytical framework development over the projection horizon. CAGRs derived from ethane feedstock cost trajectories, catalyst licensing fee structures, and regulatory compliance cost escalation curves modeled against regional production hub economics and medical-grade formulation premium capture rates.
Revisions become necessary when catalyst metal price volatility from rare earth processing bottlenecks, multimodal reactor commissioning delays, or organometallic chemist scarcity materially alter capacity expansion timelines. A model refresh is warranted upon material change in REACH SVHC candidate list expansions targeting organometallic catalyst fragments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market