
 H Beam Market | 2026-2036
H Beam Market Size, Share, and Industry Trends Forecast 2026-2036
H Beam Market Insights
Infrastructure developers are rotating away from traditional commercial building contractors as the dominant buyer archetype. POSCO sustains leadership through captive supply of specialized grades for seismic-resistant structures. ArcelorMittal anchors European demand with integrated production from ore to finished sections. Nucor competes aggressively on electric-arc furnace flexibility and regional distribution density across North American construction corridors.
An H beam is a rolled steel structural member with a cross-section resembling the letter H, featuring parallel flanges and a central web typically manufactured through continuous casting and universal mill rolling to achieve precise dimensional tolerances. Its primary purpose is to bear heavy loads across spans in buildings, bridges, and industrial frameworks while minimizing material weight. Wide flange beams dominate volume in North American commercial construction, where open-plan designs require longer unsupported spans. Heavy duty beams command premium positioning in seismic zones and heavy industrial applications where dynamic loading exceeds standard specifications. Pre-engineered beams are gaining traction in modular construction, compressing site installation schedules and reducing labor intensity for developers.
GB standards from China's SAMR govern flange thickness and web straightness for structural steel exports, while ASTM A992 in the United States mandates minimum yield strength for wide flange shapes used in building frames. The EU's Construction Products Regulation requires CE marking and declaration of performance for structural steel sections entering European projects. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules reshape sourcing decisions between integrated blast furnace mills and electric-arc furnace operators.
Market Dynamics
Seismic-resistant design mandates are compressing specification cycles for structural steel, forcing mills to certify specialized grades faster than traditional quality-assurance timelines permit. Infrastructure agencies now require documented ductility and weldability before procurement approval, elevating technical barriers for commodity producers.
Growth Catalysts
- India's National Infrastructure Pipeline:Metro rail and industrial corridor projects are absorbing heavy-duty H beam volumes at scale, with state-level urban development authorities accelerating tender awards.
- Automated submerged-arc welding:China's tightened GB standards for web straightness and flange thickness are pushing domestic mills toward robotic welding lines that reduce defect rates and inspection rework.
- CE marking under EU Construction Products Regulation:Declaration of performance requirements for structural steel sections entering European projects is filtering out uncertified imports and consolidating compliant supply.
Market Restraints
- Scrap price volatility:Electric-arc furnace operators face margin compression when ferrous scrap supply tightens in North American demolition cycles.
- Blast furnace concentration:Integrated steel capacity clusters in specific coastal Chinese provinces, creating geographic single-point vulnerability for wide flange supply chains.
- Cross-laminated timber substitution:Mid-rise commercial developers in Scandinavia and Pacific Northwest jurisdictions are specifying engineered wood for sub-ten-story structures.
Strategic Opportunities
- Vietnam infrastructure buildout:Transport ministry bridge programs remain undersupplied by domestic rolling capacity, creating import windows for certified foreign mills.
- Carbon-border adjustment mechanisms:EU phased implementation of embodied-carbon tariffs on steel imports favors electric-arc furnace producers with verified low-carbon credentials.
- Modular construction convergence:Pre-engineered beam fabrication paired with BIM-to-fabrication workflows is compressing site installation schedules for developer consortiums.
Industry Challenges
- Welding engineer scarcity:Certified inspectors for seismic-grade submerged-arc procedures command premium wages, extending project staffing timelines.
- Integrated mill conversion capex:Blast furnace operators face billion-dollar decarbonization investments to maintain access to EU and North American public procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H Beam Market |
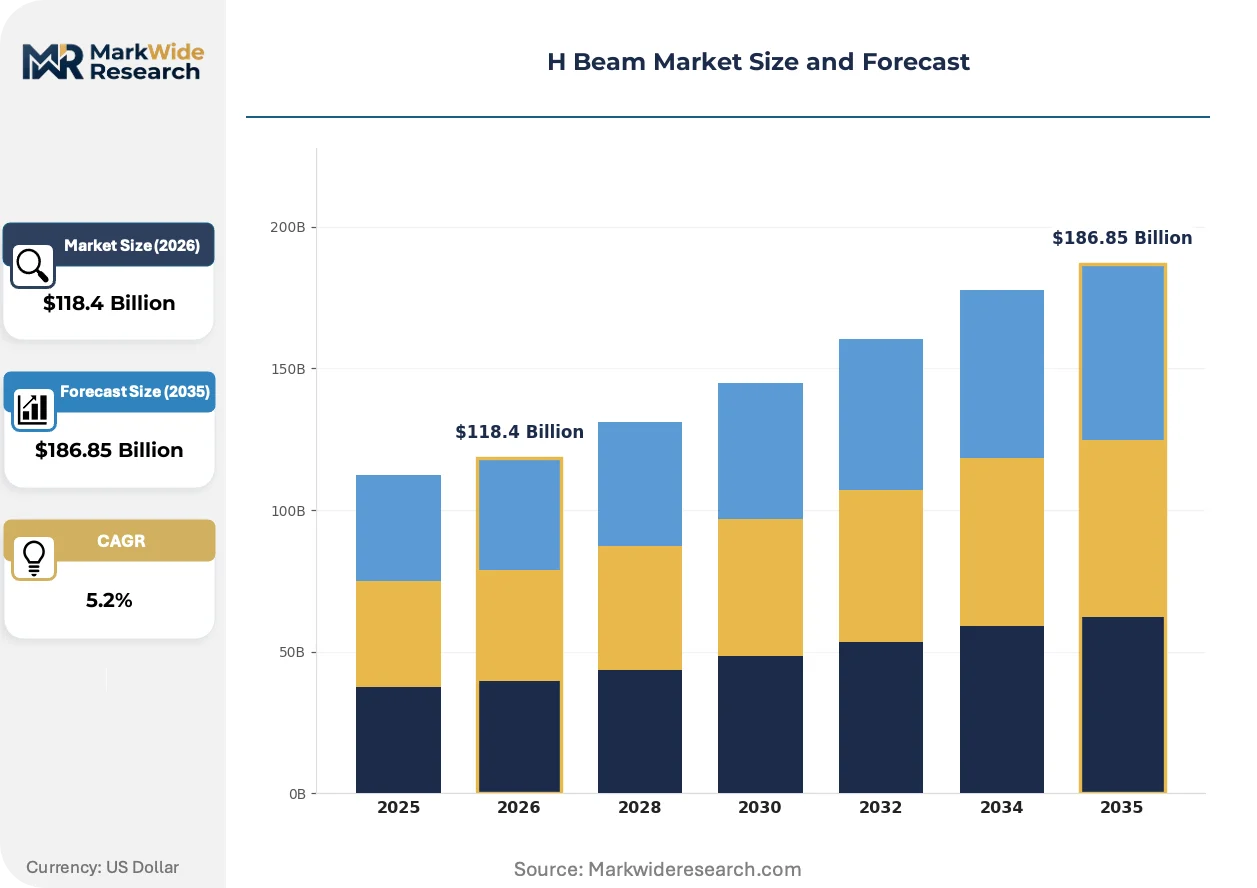
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $186.85 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard H Beam, Wide Flange Beam, Heavy Duty Beam, Pre-Engineered Beam Material: Steel, Aluminum, Composite, Others End User: Construction, Manufacturing, Shipbuilding, Infrastructure Installation Type: On-Site, Prefabricated, Modular, Steel Structures |
| Companies Covered | POSCO, Shougang, ArcelorMittal, China Steel Corporation, Tata Steel, China Baowu Steel Group, JFE Steel Corporation, Nucor, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H Beam Market Trends and Innovations
Digital thread technologies are collapsing the distance between structural design software and mill rolling schedules, enabling specification-to-delivery cycles that previously required months of manual coordination.
High-strength low-alloy (HSLA) microalloyed grades are displacing conventional carbon-manganese beams in seismic zones. Bridge authorities in Japan and California specify these grades for moment-resisting frames. The substitution is compressing tonnage requirements per project while elevating metallurgical complexity for rolling mills.
China's SAMR enforcement of revised GB/T 11263 flange thickness tolerances is disqualifying legacy universal mill output from export markets. Mills must recalibrate roll pass designs and install inline laser measurement systems. European importers now demand third-party GB compliance documentation alongside CE marking.
Developer consortiums are consolidating purchase orders through centralized procurement platforms that bypass traditional distributor networks. Large-scale infrastructure funds in Southeast Asia aggregate multi-project demand and negotiate direct mill contracts. Vietnam's transport ministry and Indonesia's state construction holding company have both established dedicated steel procurement desks.
H Beam Market Segmentation
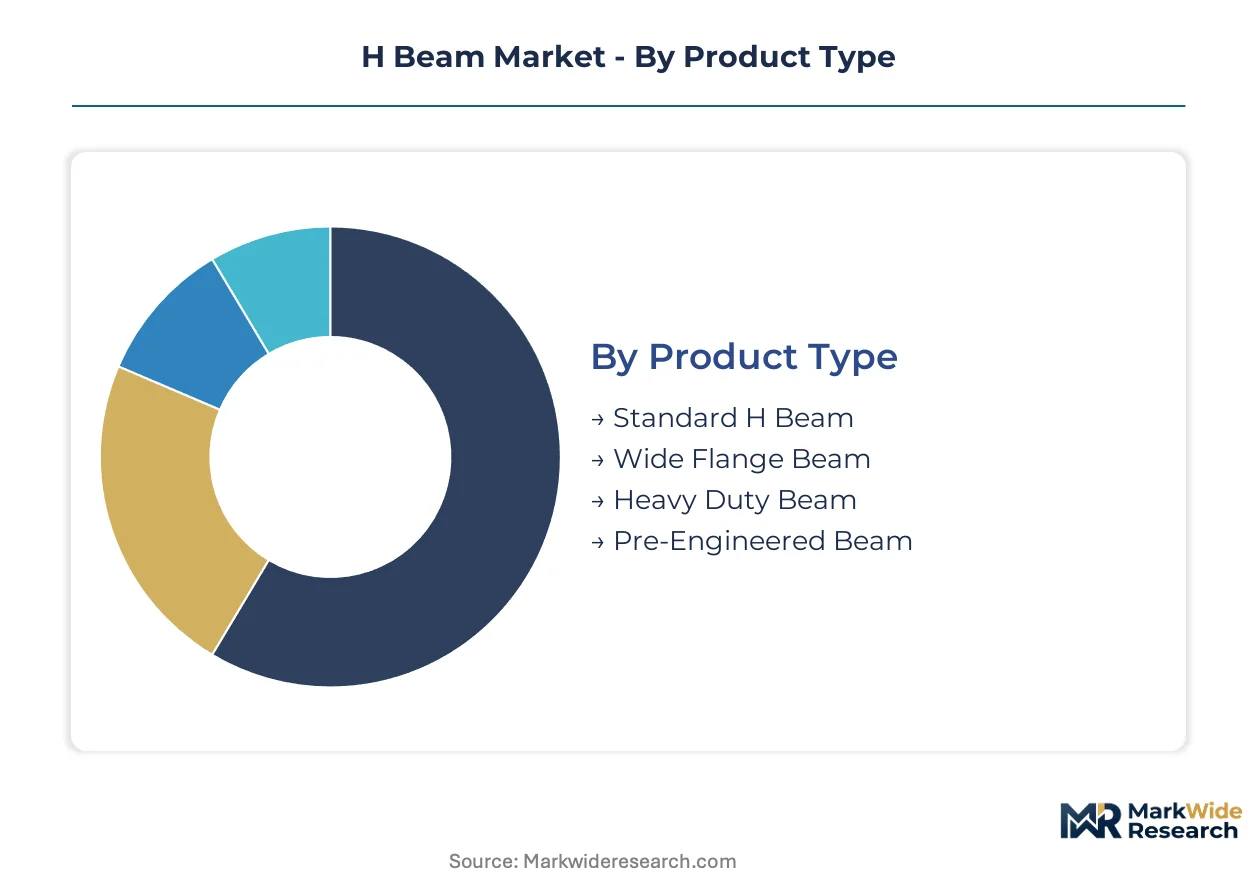
H Beam procurement patterns diverge sharply across specification tiers, with seismic codes and load-bearing requirements dictating grade selection more than price sensitivity. Regulatory fragmentation between ASTM, GB, and JIS standards forces project engineers to specify by certification territory rather than pure mechanical performance.
Product Type:
ASTM A992 governs wide flange shapes in US building frames, while China's SAMR enforces GB/T 11263 flange thickness tolerances that disqualify legacy mill output from export eligibility.
- Standard H Beam:Rolled carbon-manganese sections with parallel flanges and uniform web thickness serve conventional low-rise commercial and residential framing. Indian state urban development authorities specify these grades for National Infrastructure Pipeline housing clusters where seismic design remains secondary to cost containment.
- Wide Flange Beam:Optimized cross-sectional geometry maximizes moment of inertia per unit weight for longer unsupported spans. North American open-plan commercial construction absorbs disproportionate volumes, with developer consortiums in Texas and Florida consolidating multi-project orders through centralized procurement platforms.
- Heavy Duty Beam:Thicker flanges and enhanced web depth accommodate dynamic loading in industrial crane bays and bridge superstructures.
- Pre-Engineered Beam:Factory-cut lengths with pre-drilled connection plates compress site installation schedules for modular construction workflows.
Established volume favors wide flange configurations; emerging adoption favors pre-engineered fabrication.
Material:
Cost tier stratification separates commodity carbon steel from premium aluminum and engineered composite alternatives, with embodied-carbon disclosure rules reshaping specification authority.
- Steel:Conventional hot-rolled carbon and microalloyed grades dominate tonnage, though electric-arc furnace operators with verified low-carbon credentials gain preferential access to EU public procurement under phased carbon-border adjustment mechanisms.
- Aluminum:Lightweight extruded sections command premium positioning in coastal infrastructure and shipyard applications where corrosion resistance outweighs stiffness requirements. Norwegian bridge authorities specify aluminum for fjord-crossing superstructures to reduce seismic mass.
- Composite:Fiber-reinforced polymer and hybrid metal-composite beams serve specialized rehabilitation projects requiring electromagnetic transparency or extreme chemical resistance.
- Others:Emerging metallic and non-metallic alternatives occupy niche specification territory.
Steel retains structural cost advantage; aluminum gains share fastest in marine-exposed environments.
End User:
Customer type concentration shifts procurement leverage from distributor networks to direct mill relationships, with infrastructure funds aggregating demand across multi-year programs.
- Construction:Commercial and residential building contractors specify standard and wide flange grades for framing systems, with BIM-to-fabrication workflows collapsing traditional specification-to-delivery cycles.
- Manufacturing:Industrial facility developers demand heavy duty sections for crane-runway girders and equipment support structures where dynamic loading exceeds static design assumptions. German automotive plant construction drives premium tonnage requirements.
- Shipbuilding:Korean and Japanese yards specify high-strength low-alloy grades for hull girders and deck structures, with classification society rules governing weldability certification.
- Infrastructure:State transport ministries and rail authorities in India, Vietnam, and Indonesia absorb heavy-duty volumes for bridge and metro corridor construction, with tender awards accelerating through dedicated steel procurement desks.
Construction maintains volume dominance; infrastructure exhibits steepest expansion trajectory.
Installation Type:
Supply chain configuration determines margin capture, with prefabrication shifting value from field labor to controlled factory environments.
- On-Site:Traditional cut-and-bolt assembly persists in remote projects beyond modular logistics reach, though skilled welder scarcity extends staffing timelines for seismic-grade submerged-arc procedures.
- Prefabricated:Factory-welded subassemblies with pre-installed connection hardware reduce field labor intensity. Singapore's construction productivity mandate accelerates prefabrication adoption for public housing.
- Modular:Complete structural modules with integrated MEP systems enable parallel site preparation and factory production, compressing overall project duration for developer consortiums targeting rapid occupancy.
- Steel Structures:Turnkey engineered systems bundle design, fabrication, and erection under single-contractor responsibility.
On-site methods retain legacy project share; modular convergence gains developer preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor underwrites the country's emergence as the primary demand sink for heavy structural sections, with dedicated steel procurement desks accelerating tender awards for metro and bridge programs.
India
State urban development authorities in Maharashtra and Karnataka are absorbing wide flange volumes for National Infrastructure Pipeline housing clusters and industrial corridor construction. The Ministry of Housing and Urban Affairs mandates BIS-certified structural grades for all public projects, filtering out uncertified imports. The Delhi-Mumbai Industrial Corridor anchors concentrated demand, with dedicated steel procurement desks streamlining multi-project aggregation for infrastructure funds.
China
Provincial transport ministries in Jiangsu and Guangdong are expanding bridge procurement programs that specify tightened GB/T 11263 flange thickness tolerances. SAMR enforcement of revised weld-quality requirements is disqualifying legacy universal mill output from export eligibility. The Yangtze River Delta mill cluster is recalibrating roll pass designs and installing inline laser measurement systems to maintain overseas market access.
United States
Developer consortiums in Texas and Florida are consolidating multi-project orders for open-plan commercial construction through centralized procurement platforms. ASTM A992 mandates minimum yield strength for wide flange shapes used in building frames, elevating technical barriers for commodity producers. The Gulf Coast construction corridor exhibits disproportionate volume absorption, with electric-arc furnace operators competing on regional distribution density.
Vietnam
The transport ministry's bridge programs remain undersupplied by domestic rolling capacity, creating import windows for certified foreign mills. The country's national construction regulator requires documented ductility certification before procurement approval for seismic-zone infrastructure. The Red River Delta industrial zone is attracting prefabrication investments from regional steel fabricators targeting compressed site installation schedules.
Germany
Automotive plant construction in Bavaria and Baden-Württemberg drives premium tonnage requirements for heavy-duty crane-runway girders. The EU Construction Products Regulation mandates CE marking and declaration of performance for structural steel sections entering European projects. The Ruhr industrial cluster maintains integrated production from ore to finished sections, anchoring supply security for continental infrastructure programs.
H Beam Market Competitive Landscape
Listed leaders compete with private specialists across certification territory and metallurgical complexity, producing a tiered structure where scale-driven integrated mills anchor volume while electric-arc furnace operators capture flexibility premiums. The vendor base separates into three strategic archetypes: blast furnace operators with captive raw material access, regional minimills with distribution density advantages, and specialized producers of seismic-grade microalloyed sections. Dominant competitive moves include backward integration into scrap collection networks and technology licensing for automated submerged-arc welding lines.
Within the integrated mill tier, POSCO and ArcelorMittal exemplify archetypes of geographic specialization, with the former representing Korean production gravity for seismic-resistant grades and the latter anchoring European supply security through ore-to-section integration. Nucor occupies a position among North American electric-arc furnace operators competing on regional distribution density across construction corridors. These three names illustrate how competitive positioning separates by furnace technology and certification territory rather than pure scale.
| Leading Market Players |
|---|
| POSCO |
| Shougang |
| ArcelorMittal |
| China Steel Corporation |
| Tata Steel |
| China Baowu Steel Group |
| JFE Steel Corporation |
| Nucor |
| Nippon Steel Corporation |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Construction Products Regulation gates both supply qualification and price differentiation simultaneously, filtering uncertified imports from European projects while elevating compliant producers to premium positioning. Infrastructure funds in Southeast Asia exploit this bifurcation by aggregating multi-project demand and negotiating direct mill contracts that bypass traditional distributor markups.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates seismic-grade microalloyed beams from commodity carbon-manganese sections and uncertified legacy output. Price differentiation hinges on certification tier and volume scale, with state-level urban development authorities in India extracting discounts through consolidated National Infrastructure Pipeline tenders. Pricing pressure stems from scrap price volatility compressing electric-arc furnace margins during North American demolition cycle troughs. Standard-grade buyers exhibit highest price sensitivity, while seismic-zone infrastructure agencies prioritize documented ductility over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for mills serving Vietnamese bridge programs from Chinese rolling capacity. Supply concentrates in China, India, and South Korea, with the Yangtze River Delta mill cluster anchoring wide flange output for export markets. Raw material dependencies draw from iron ore, ferrous scrap, and alloying elements such as vanadium and niobium for microalloyed grades. Single-source vulnerability characterizes blast furnace concentration in specific coastal Chinese provinces. Distribution runs through centralized procurement platforms that disintermediate traditional steel distributors for large-scale infrastructure funds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through infrastructure fund consolidation and state-level procurement desk formation, fragmenting traditional distributor influence while elevating direct mill relationships. This shift rewards producers with certified capacity and punishes commodity traders lacking technical documentation capabilities.
For Market Incumbents: Consolidate certification territory by securing GB/T 11263 compliance documentation for Chinese export eligibility alongside CE marking for European access. Backward integration into scrap collection networks insulates margin compression from ferrous supply volatility. Cross-laminated timber substitution in mid-rise Scandinavian commercial construction threatens standard-grade beam volumes, demanding defensive positioning through seismic-grade specialization.
For New Entrants and Emerging Players: Lead with Vietnam's transport ministry bridge programs, where domestic rolling capacity undersupply creates import windows for certified foreign mills. Target pre-engineered beam fabrication for modular construction workflows, where BIM-to-fabrication integration compresses specification-to-delivery cycles. Pursue direct contracting relationships with Indonesia's state construction holding company, which has established dedicated steel procurement desks aggregating multi-project demand.
For Investors and Strategic Acquirers: EU phased implementation of carbon-border adjustment mechanisms reshapes the acquisition landscape, favoring electric-arc furnace operators with verified low-carbon credentials over blast furnace assets facing billion-dollar decarbonization capex. Long-term viability centers on producers with dual certification capability spanning ASTM, GB, and CE marking territories. Monitor welding engineer scarcity as an inflection signal, where certified inspector wage premiums indicate tightening quality-assurance capacity constraining seismic-grade output expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Submerged-Arc Welding Investment | Robotic welding lines reduce defect rates for SAMR-compliant GB/T 11263 exports. |
| Backward Integration into Scrap Networks | Captive ferrous supply stabilizes electric-arc furnace input costs against demolition cycle volatility. |
| Seismic-Grade Microalloyed Certification | HSLA grades command premium positioning in Japan and California moment-resisting frame specifications. |
| Centralized Procurement Platform Partnership | Direct contracts with Vietnam's transport ministry bypass distributor markups for bridge programs. |
| Carbon-Border Compliance Documentation | Verified low-carbon credentials secure preferential access to EU public procurement under phased adjustment mechanisms. |
Research Methodology
Desk research of customs trade data, mill production disclosures, and national infrastructure pipeline announcements preceded structured interviews with procurement directors at state urban development authorities, technical directors at rolling mills, and project engineers at EPC contractors specializing in bridge and metro construction. Secondary validation drew from BIS certification registries, SAMR GB standard enforcement bulletins, and EU Construction Products Regulation declaration of performance databases. Bottom-up project aggregation across India's National Infrastructure Pipeline and Vietnam's transport ministry programs was triangulated against top-down steel consumption forecasts by end-use sector.
Variance decomposition across product type, material grade, end-user segment, and installation configuration shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include beam specification tier, metallurgical complexity, certification territory, and regional production hub. CAGRs were derived from installed base growth and replacement demand curves, with specific inputs from metro rail extension timelines in Maharashtra and Karnataka and industrial corridor construction phasing along the Delhi-Mumbai corridor.
Forecasts assume regulatory continuity in BIS enforcement, SAMR GB standard tightening, and EU carbon-border phased implementation; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Bridge Bearings Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Canada Composite Repair Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market