
 Global Rebar Splice Market | 2026-2036
Global Rebar Splice Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rebar Splice Market Outlook
Construction supply distribution is rewriting how rebar splice manufacturers reach project sites across multiple continents. nVent leverages its electrical infrastructure footprint to cross-sell mechanical connection systems into contractor networks. Dextra Group anchors its position through specialized coupler engineering for high-rise and bridge applications. Tokyo Tekko competes with forged-thread technology that reduces field labor hours on Japanese megaprojects.
A rebar splice is a mechanical or welded connection joining two reinforcing steel bars to transfer tensile and compressive loads across a structural joint, typically achieving 125% or greater of specified yield strength per ACI 318 criteria. Its primary purpose is eliminating lap splice congestion in densely reinforced concrete elements such as columns, beams, and seismic moment frames. Mechanical couplers dominate specification in high-rise commercial construction where congestion penalties drive premium pricing. Field welding retains share in heavy infrastructure where inspection protocols favor fusion-bonded joints. Pre-assembly methods are gaining traction in modular construction programs seeking to compress critical-path schedules.
ACI 318 in the United States, Eurocode 2 across European Union member states, and China's GB 50010 collectively govern splice performance, testing protocols, and installation qualification requirements that manufacturers must satisfy for market access. These codes directly determine product development priorities, with seismic detailing provisions in high-risk zones demanding proprietary coupler systems capable of cyclic loading performance. Stakeholders must monitor evolving green building standards that may soon embed embodied carbon thresholds into structural connection specifications.
Market Dynamics
Mechanical coupler specification is concentrating around seismic-resistant detailing requirements as building codes tighten cyclic-loading performance thresholds across high-risk zones. Manufacturers must now engineer proprietary systems that satisfy ACI 318, Eurocode 2, and China's GB 50010 simultaneously to retain specification access on multinational projects.
Growth Catalysts
- Seismic code convergence:ACI 318 and Eurocode 2 provisions for ductile detailing are forcing adoption of high-performance couplers in moment-frame construction across California and Italy.
- India's western industrial corridor:Petrochemical and port infrastructure from Mumbai to Gujarat is generating concentrated demand for heavy-bar mechanical splicing in foundation systems.
- Modular construction acceleration:Pre-assembly of rebar cages with threaded couplers is compressing critical-path schedules on hospital and data center projects in Singapore and Australia.
Market Restraints
- Scrap steel price volatility:Input cost swings for 40-grade and 60-grade reinforcing bar directly compress coupler manufacturer margins on fixed-price contracts.
- Field welding substitution:Fusion-bonded joints retain specification share in heavy infrastructure where inspection protocols favor visual weld examination over mechanical testing.
- Certification fragmentation:Divergent testing protocols between ACI 318, Eurocode 2, and GB 50010 force redundant product qualification spending for multi-jurisdictional suppliers.
Strategic Opportunities
- Vietnam's infrastructure buildout:Transport and energy megaprojects present white-space demand for mechanical splicing systems as the country adopts ACI-derived seismic standards.
- Embodied carbon accounting:EU Green Deal and CSRD disclosure requirements will soon reward coupler systems that eliminate lap-splice steel overage in high-rise construction.
- Digital twin integration:BIM-to-fabrication workflows are creating openings for coupler suppliers to embed RFID traceability into pre-assembled rebar modules.
Industry Challenges
- Installation technician certification:Field torque-wrench calibration and inspector qualification shortages delay project acceptance in markets with sparse distributor networks.
- Legacy project specification lock-in:Existing lap-splice detailing in renovation and expansion contracts resists retrofit to mechanical systems despite congestion penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rebar Splice Market |
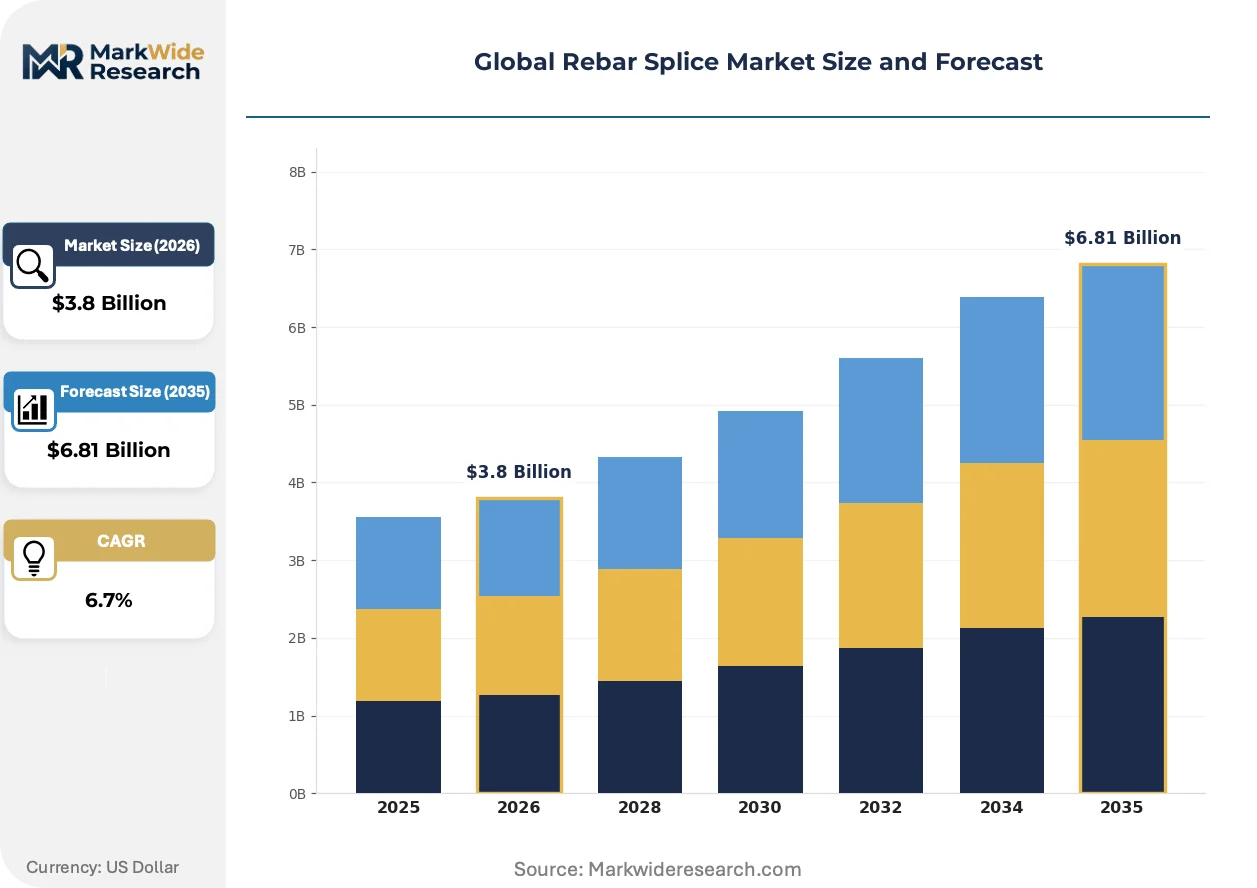
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Splices, Couplers, Welded Splices, Bar Ends Installation Method: On-Site, Pre-Assembly, Mechanical Connection, Field Welding End User: Construction, Infrastructure, Industrial, Residential Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | nVent, Dextra Group, Tokyo Tekko, Peikko Group, Terwa, CRH, Glus, BarSplice Products, Sida Jianmao, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rebar Splice Market Strategic Shifts
Forged-thread and roll-thread manufacturing processes are reshaping competitive positioning as labor-hour economics favor field-installed mechanical systems over welded alternatives. Three developments are compressing adoption timelines and reconfiguring supply relationships.
Roll-thread technology is migrating from Japanese megaproject applications toward Southeast Asian infrastructure specifications. Tokyo Tekko's forged-thread systems reduced field labor hours by eliminating end-preparation steps on the Kansai International Airport expansion. Contractors in Thailand and Indonesia now specify similar systems for bridge deck replacements where congestion penalties exceed material premiums.
China's GB 50010 seismic amendments are tightening material certification requirements for couplers used in moment-resisting frames. The Ministry of Housing and Urban-Rural Development now mandates third-party cyclic-loading test reports for projects in intensity-8 zones. Domestic manufacturers are consolidating testing laboratory partnerships while foreign suppliers face extended approval timelines.
Specification authority is consolidating within engineering-procurement-construction firms that self-perform rebar installation. Skanska and Bechtel now mandate preferred coupler brands across multiple project sites to standardize inventory and training. This concentration is visible most acutely in Middle Eastern hospital and airport contracts where single-source mechanical splicing reduces subcontractor coordination risk.
Global Rebar Splice Market Segmentation
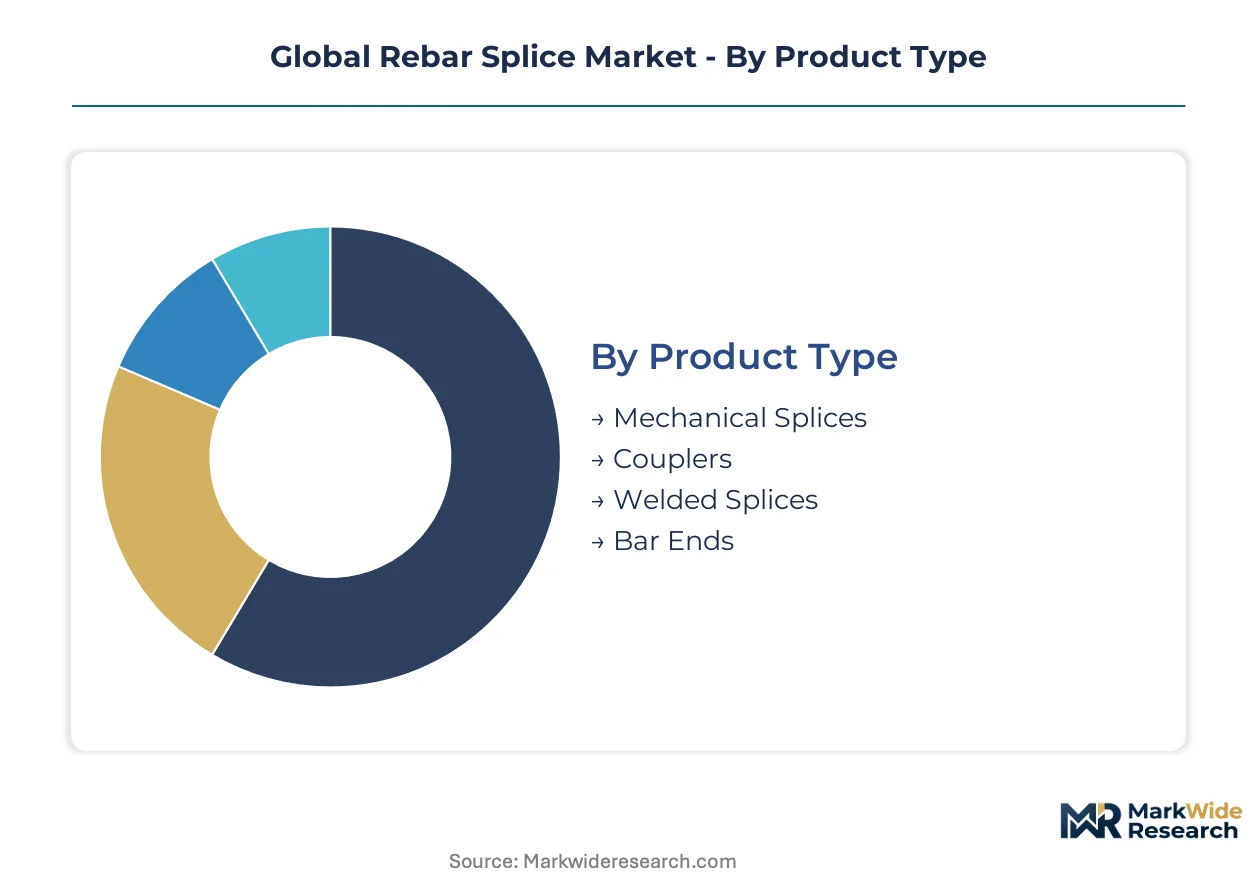
Rebar splice segmentation reveals divergent service intensity across product categories. Mechanical coupler systems demand extensive field technician training and calibration support, while welded alternatives require certified inspection protocols that reshape distributor compensation structures.
Product Type:
After-sales service intensity peaks with mechanical coupler systems requiring ongoing field calibration support and inspector certification programs.
- Mechanical Splices:Threaded and taper-threaded systems achieve 125% specified yield strength per ACI 318 criteria. Demand concentrates in California high-rise construction where seismic moment-frame detailing mandates cyclic-loading performance. Field torque-wrench calibration programs create recurring service revenue streams for distributors.
- Couplers:Proprietary forged-thread and roll-thread designs eliminate end-preparation labor on megaprojects. Mumbai-Gujarat industrial corridor petrochemical foundations specify heavy-bar couplers for congestion relief in densely reinforced pile caps. Manufacturers embed RFID traceability for BIM-to-fabrication workflow integration.
- Welded Splices:Fusion-bonded joints retain specification in heavy infrastructure where visual weld examination protocols dominate quality assurance.
- Bar Ends:Pre-fabricated terminal connections serve modular construction programs seeking pre-assembly of rebar cages off-site.
By volume, Couplers leads. By growth pace, Mechanical Splices is climbing the fastest.
Installation Method:
Cost tier stratification separates premium pre-assembly services from commoditized field welding contracts.
- On-Site:Traditional field-installed mechanical systems dominate mid-rise commercial construction across Italy and Spain. Contractors bear labor-hour penalties for end-preparation and torque calibration activities. Equipment rental for portable threading machines creates secondary revenue pools for regional distributors.
- Pre-Assembly:Rebar cage fabrication in controlled environments compresses critical-path schedules on Singapore hospital and Australia data center projects. Skanska and Bechtel mandate standardized coupler brands across self-performed sites to reduce subcontractor coordination risk. Premium pricing reflects schedule certainty value.
- Mechanical Connection:Roll-thread technology from Japanese applications migrates toward Thai and Indonesian bridge deck replacements.
- Field Welding:Retains share where inspection protocols favor certified welder qualification over mechanical testing documentation.
Pre-Assembly commands highest margin per connection. On-Site retains widest geographic penetration.
End User:
Application-specific performance thresholds segment customers by bar diameter range and cyclic-loading requirements.
- Construction:High-rise commercial towers in seismic zones drive specification of ductile detailing-compliant couplers. California and Italy moment-frame construction tightens cyclic-loading performance thresholds. ACI 318 and Eurocode 2 convergence accelerates proprietary system adoption.
- Infrastructure:Transport and energy megaprojects in Vietnam present white-space demand as ACI-derived seismic standards take hold. Heavy-bar mechanical splicing dominates foundation systems where congestion penalties exceed material premiums. Ministry-level certification requirements extend approval timelines for foreign suppliers.
- Industrial:Petrochemical and port infrastructure from Mumbai to Gujarat generates concentrated demand for corrosion-resistant coupler coatings.
- Residential:Lap splices retain cost advantage in low-rise construction with minimal congestion constraints.
Infrastructure shows steepest expansion trajectory. Construction maintains largest installed base.
Distribution Channel:
Supply concentration patterns favor direct relationships on megaprojects while distributors serve fragmented contractor bases.
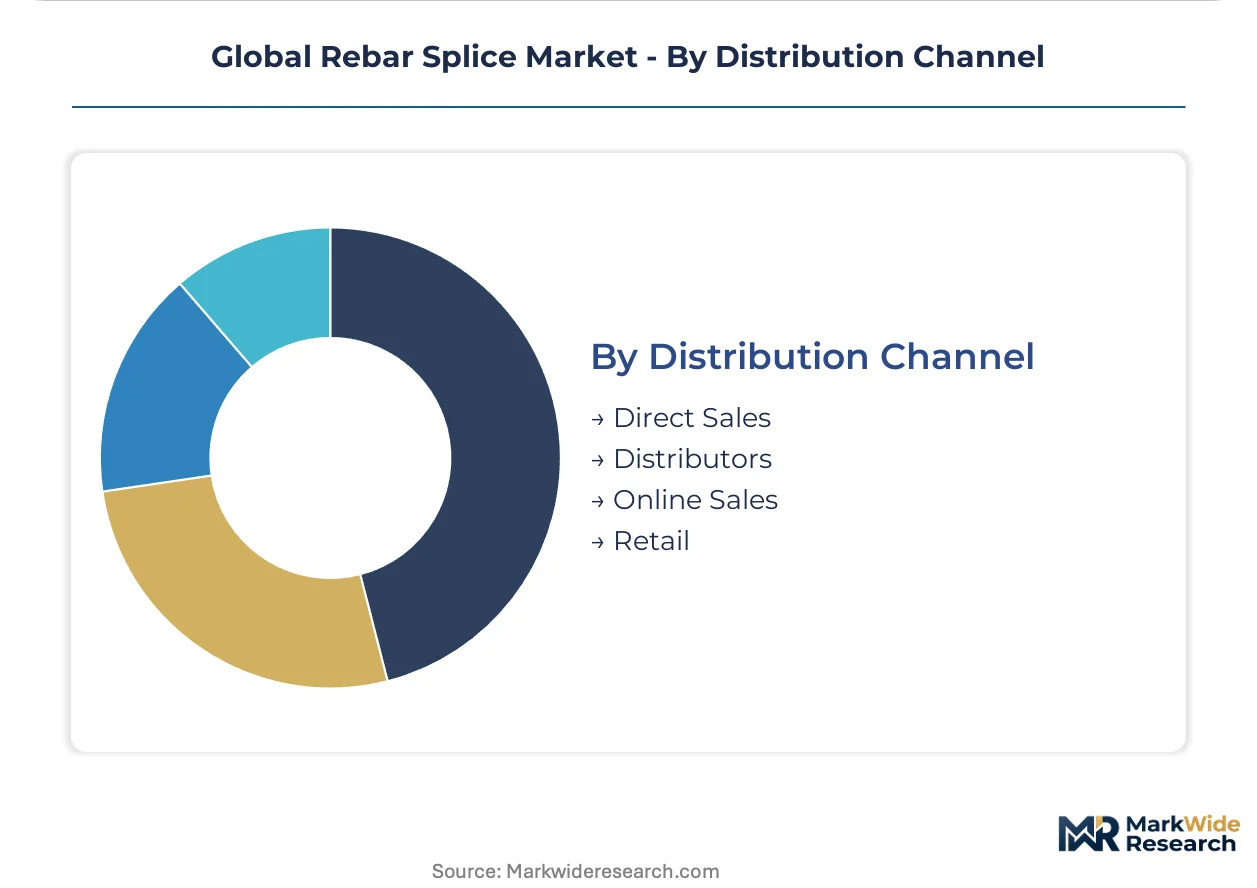
- Direct Sales:Engineering-procurement-construction firms self-performing rebar installation consolidate specification authority. Single-source mechanical splicing reduces inventory complexity on Middle Eastern hospital and airport contracts. nVent cross-sells connection systems through existing electrical infrastructure relationships.
- Distributors:Regional networks provide field technician certification and torque-wrench calibration in markets with sparse manufacturer presence. Dextra Group anchors position through specialized coupler engineering support for high-rise and bridge applications. Margin compression follows scrap steel price volatility on fixed-price contracts.
- Online Sales:Emerging channel for standard coupler specifications with documented test reports.
- Retail:Serves renovation and small-contractor segments with limited technical service requirements.
Direct Sales captures premium project value. Distributors scale geographic coverage most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Ahmedabad High-Speed Rail corridor anchors India's western infrastructure buildout, concentrating mechanical coupler demand across foundation systems and elevated viaducts. Mega-projects in Vietnam's transport and energy sectors are accelerating specification of ACI-derived seismic standards. Japan's forged-thread technology exports are reshaping Southeast Asian bridge construction protocols.
United States
California high-rise commercial towers drive specification of ductile detailing-compliant couplers for seismic moment-frame construction. ACI 318 provisions for cyclic-loading performance tighten approval thresholds for proprietary systems. Los Angeles and San Francisco construction clusters concentrate demand among engineering-procurement-construction firms self-performing rebar installation.
China
GB 50010 seismic amendments mandate third-party cyclic-loading test reports for couplers in intensity-8 zones. The Ministry of Housing and Urban-Rural Development extends approval timelines for foreign suppliers seeking certification. Yangtze River Delta megaprojects concentrate domestic manufacturer consolidation around testing laboratory partnerships.
India
Petrochemical and port infrastructure from Mumbai to Gujarat generates concentrated demand for heavy-bar mechanical splicing in densely reinforced pile caps. BIS certification requirements for seismic-resistant construction tighten material traceability protocols. The western industrial corridor anchors specification authority among contractor networks executing fixed-price foundation contracts.
Vietnam
Transport and energy megaprojects present white-space demand as ACI-derived seismic standards displace legacy lap-splice detailing. The country's national construction regulator mandates performance testing for mechanical connection systems in high-rise applications. Ho Chi Minh City and Hanoi construction clusters concentrate foreign supplier entry efforts around ministry-level certification timelines.
Japan
Forged-thread technology from Tokyo Tekko applications reduces field labor hours on domestic megaprojects and exports toward Southeast Asian bridge deck replacements. METI standards for construction material quality assurance shape regional specification protocols. Kansai and Kanto industrial corridors anchor roll-thread manufacturing capacity serving Thai and Indonesian infrastructure markets.
Global Rebar Splice Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: electrical infrastructure cross-sellers leveraging existing contractor networks, specialized coupler engineers focused on high-rise and bridge applications, and forged-thread technology specialists reducing field labor hours. Dominant competitive moves include strategic partnerships with testing laboratories for accelerated certification and geographic expansion through distributor network densification in markets with sparse manufacturer presence.
Among the named players, nVent represents the electrical infrastructure cross-seller archetype, Dextra Group exemplifies specialized coupler engineering for congestion-critical applications, and Tokyo Tekko anchors the forged-thread technology tier reducing end-preparation labor on megaprojects. These three occupy positions that collectively span the premium specification, technical service intensity, and labor-hour reduction vectors defining competitive differentiation in this market.
| Leading Market Players |
|---|
| nVent |
| Dextra Group |
| Tokyo Tekko |
| Peikko Group |
| Terwa |
| CRH |
| Glus |
| BarSplice Products |
| Sida Jianmao |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor anchors cost dynamics for forged-thread coupler exports from Shanghai to Southeast Asian infrastructure sites, compressing margins for European suppliers while amplifying price differentiation between certified and uncertified product tiers. Scrap steel volatility on the London Metal Exchange feeds directly into manufacturer pricing power, with concentrated billet sourcing in Hebei Province enabling Chinese producers to undercut ACI 318-certified alternatives on fixed-price contracts.
Pricing Analysis
Volume-discount tiering structures stratify across project-scale thresholds, with petrochemical foundation contractors in Gujarat commanding 15-20 point spreads over retail distributor channels. Price differentiation hinges on cyclic-loading certification grade and bundled field technician training programs, with ACI 318 Type 2 seismic couplers sustaining premium positioning against Eurocode 2-compliant alternatives. Cost compression in standard-grade mechanical splices is intensifying because of fixed-price contracting norms across India's western corridor. Residential contractors exhibit highest price sensitivity, while EPC firms self-performing rebar installation prioritize schedule certainty over unit cost.
Supply Chain Analysis
Export-control regimes on high-strength steel forging equipment limit technology transfer to Vietnamese and Indonesian manufacturers, preserving Japanese and Chinese dominance in roll-thread production capacity. Geographic supply concentration centers on China, Japan, and India, with forged-thread billet sourcing drawing from Hebei steel mills and specialty alloy feeds from Nippon Steel. Supply chain risk from single-source vulnerability in seismic-testing laboratory accreditation extends approval timelines for foreign entrants. Distribution runs through engineering-procurement-construction direct relationships on megaprojects, with regional distributors providing field calibration support in fragmented contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installation technician pools represent the binding constraint in this market, with torque-wrench calibration expertise and cyclic-loading inspection qualification gaps limiting expansion in Vietnam and Indonesia. The capability scarcity embedded in field-service infrastructure shapes competitive durability more than manufacturing scale alone.
For Market Incumbents: Build certification moats through exclusive testing laboratory partnerships that accelerate GB 50010 and ACI 318 approval timelines for multinational projects. Consolidate position by acquiring regional distributors with established technician training networks in India's western corridor. Field welding substitution in heavy infrastructure poses the primary technology threat; counter with embedded RFID traceability for BIM-to-fabrication workflow integration. Vertical integration into pre-assembly rebar cage fabrication offers the strongest margin defense against scrap steel price volatility. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's transport megaproject sector where ACI-derived seismic standards are displacing legacy lap-splice detailing but ministry-level certification timelines have delayed foreign supplier entry. Target petrochemical foundation contractors in the Mumbai-Gujarat corridor with corrosion-resistant coupler coatings as the most penetrable application segment. Partner with European engineering-procurement-construction firms on Middle Eastern hospital contracts to leverage their standardized coupler brand mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from electrical infrastructure conglomerates seeking to divest non-core mechanical connection divisions amid portfolio rationalization pressures. Long-term viability over the next decade rests on embedded carbon accounting integration as EU CSRD disclosure requirements reshape specification criteria. Monitor BIS certification timeline acceleration in India as the critical inflection signal for foreign supplier market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Testing Laboratory Partnership | Accelerates ACI 318 and GB 50010 cyclic-loading certification for seismic zone access. |
| Pre-Assembly Service Expansion | Captures premium pricing from Skanska and Bechtel on Singapore hospital contracts. |
| RFID Traceability Integration | Enables BIM-to-fabrication workflow embedding for modular construction programs. |
| Corrosion-Resistant Coating Development | Addresses petrochemical foundation demand in Mumbai-Gujarat industrial corridor. |
| Technician Certification Program | Resolves field torque-wrench calibration shortages delaying project acceptance. |
Study Parameters
Desk research of construction code filings, customs trade data, and steel billet price indices preceded structured interviews with rebar cage fabrication supervisors, EPC procurement directors, and seismic testing laboratory managers. Primary fieldwork with distributors in India and Vietnam validated secondary data on certification timeline variations. Bottom-up unit economics from project-level coupler consumption patterns triangulated against top-down market sizing from regional construction spend databases.
Assumption sets held scrap steel price volatility and regulatory certification timelines as fixed baseline conditions while varying modular construction adoption rates and EPC self-performance trends across scenarios. Segmentation modeling incorporated product type, installation method, end-use application, and regional regulatory cluster dimensions. CAGRs derived from weighted project pipeline analysis across the analysis window, with seismic code convergence velocity and infrastructure investment commitment levels as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese steel export policy or Indian rupee-denominated contract exposure would shift the trajectory. Forecasts reflect documented assumptions on code harmonization timing and technician certification pipeline development. Material shifts in EU embodied carbon threshold implementation or GB 50010 intensity-8 zone expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Sandwich Plate System Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
South Korea Construction Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Bridge Construction Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
H Beam Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market