
 United States less than-Truck-Load (LTL) Market | 2026-2036
United States less than-Truck-Load (LTL) Market Size, Share, and Industry Trends Forecast 2026-2036
United States less than-Truck-Load (LTL) Market Insights
FMCSA safety fitness determination and CSA scores are bifurcating the competitive landscape between compliant fleet operators and marginal carriers facing insurance and shipper exclusion. Old Dominion Freight Line leverages dense terminal networks and proprietary linehaul planning to sustain industry-leading operating ratios. XPO, Inc. competes through technology-heavy freight optimization platforms that integrate dynamic pricing with real-time visibility. Saia Inc. anchors its position in the less-than-truckload sector through disciplined geographic expansion and consistent service metrics.
Less-than-truck-load denotes freight shipments typically ranging from 150 to 15,000 pounds that do not require a full trailer, consolidated through hub-and-spoke terminal networks where multiple shippers share trailer capacity and costs. The primary commercial purpose involves cost-efficient transportation of palletized and loose freight for businesses lacking volume for full truckload economics. Express service commands premium pricing from time-sensitive manufacturing and healthcare supply chains, while standard LTL occupies the volume base among cost-conscious retailers and industrial distributors. Weight-based pricing models dominate transactional shipper relationships, though large enterprises increasingly negotiate flat-rate structures tied to committed volume tiers.
Federal Motor Carrier Safety Administration regulations govern driver qualification, vehicle inspection, and hours-of-service compliance that directly constrain network capacity and operating cost structures. Department of Transportation infrastructure funding programs and EPA emissions standards for medium- and heavy-duty trucks shape fleet replacement cycles and alternative fuel adoption timelines. State-level weight and dimension regulations vary across jurisdictions, complicating interstate routing and equipment specification decisions. Stakeholders must monitor how FMCSA's pending automatic emergency braking mandate and potential speed limiter rulemaking will alter equipment procurement strategies and carrier cost profiles.
Market Dynamics
The Federal Motor Carrier Safety Administration's electronic logging device mandate has permanently altered how United States LTL carriers schedule linehaul operations and price guaranteed service windows. Shippers now absorb the cost of stricter hours-of-service compliance through extended transit times or premium expedited rates.
Growth Catalysts
- E-commerce fulfillment density:Retailers operating regional distribution centers in Texas and the Southeast generate palletized replenishment flows that fill LTL trailers more efficiently than parcel networks. Third-party logistics providers contract directly with regional carriers for middle-mile injection.
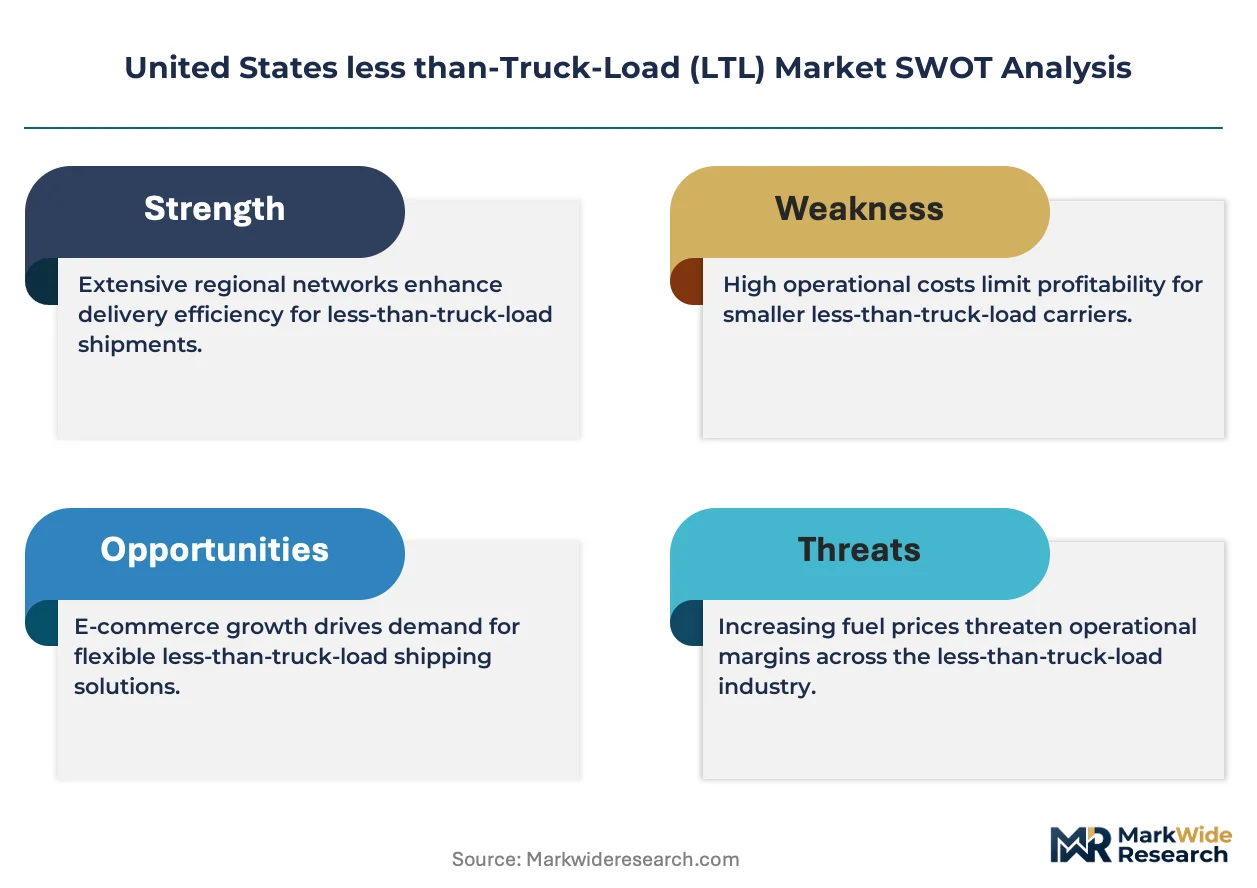
- FMCSA safety fitness determination:Compliant fleet operators gain preferred shipper status and lower insurance premiums, concentrating freight flows toward carriers with superior Compliance, Safety, Accountability scores. Marginal operators exit, tightening capacity and supporting rate discipline.
- Manufacturing reshoring:Industrial distributors serving automotive and machinery OEMs in Tennessee, South Carolina, and Ohio generate steady LTL demand for inbound parts and outbound finished goods.
Market Restraints
- Diesel price volatility:Fuel represents 20-25% of operating costs for United States LTL carriers, with limited pass-through elasticity on contracted lanes squeezing margins during price spikes.
- Driver shortage concentration:Long-haul linehaul positions face acute recruitment gaps in the Midwest and Mountain West, forcing wage inflation that regional carriers struggle to match against national networks.
- Trailer utilization ceiling:Hub-and-spoke terminal networks impose fixed handling costs and dwell time minimums that resist further productivity gains without network restructuring.
Strategic Opportunities
- Final-mile LTL convergence:Carriers with urban terminal density in Dallas-Fort Worth, Atlanta, and Phoenix can integrate LTL linehaul with last-mile delivery for bulky e-commerce goods, capturing share from parcel carriers at weight break points above 150 pounds.
- EPA emissions standards tailwind:Fleet replacement cycles accelerated by medium- and heavy-duty truck regulations create openings for carriers with capital access to deploy electric or natural gas tractors ahead of compliance deadlines.
- Healthcare supply chain specialization:Temperature-controlled LTL service for pharmaceutical distributors in New Jersey, Pennsylvania, and North Carolina commands rate premiums and multi-year contracts.
Industry Challenges
- Linehaul driver retention:Irregular schedules and overnight runs produce annual turnover exceeding 90% at some United States carriers, inflating recruitment and training expenditures.
- Terminal automation capex:Cross-dock sorting systems and dimensioning equipment require eight-figure investments per facility, disadvantaging mid-sized operators against scaled networks.
- Shipper TMS integration:Legacy electronic data interchange connections frustrate real-time visibility demands from enterprise logistics platforms, forcing parallel API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States less than-Truck-Load (LTL) Market |
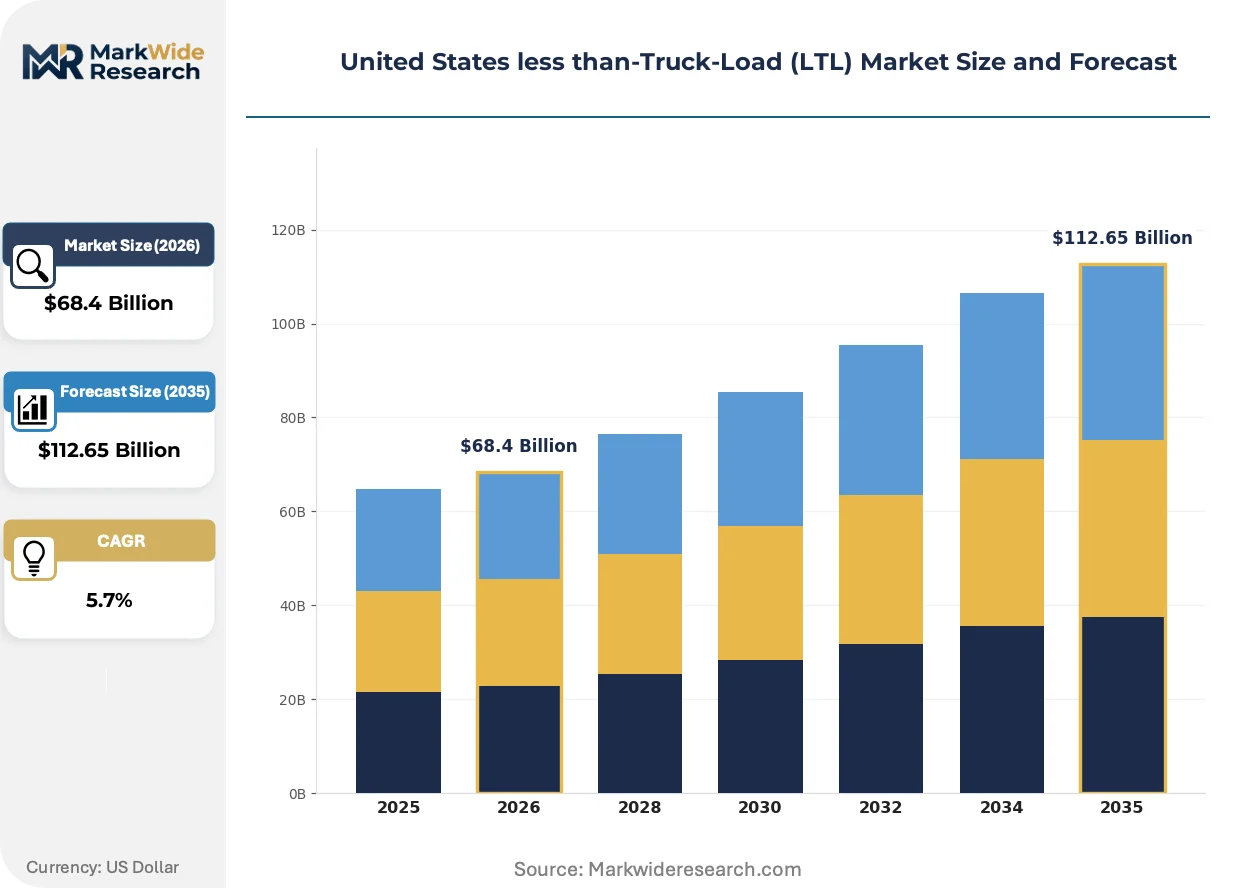
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard, Express, Freight, Expedited Pricing Model: Flat Rate, Weight-Based, Distance-Based, Accessorial Charges Customer Type: SMEs, Large Enterprises, Retailers, Manufacturers Delivery Mode: Dock-to-Dock, Curbside, Inside Delivery, Cross-Docking |
| Companies Covered | FedEx Freight, Old Dominion Freight Line, XPO, Inc., Saia Inc., ArcBest, Estes Express Lines, R+L Carriers, TFI International, Southeastern Freight Lines, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States less than-Truck-Load (LTL) Market Trends and Innovations
Digital freight matching platforms and dynamic pricing algorithms are compressing the information advantage historically held by incumbent carriers with dense terminal networks. Technology investment now separates margin performance more than physical asset scale alone.
Machine learning dispatch systems are fragmenting traditional LTL planning. These algorithms ingest real-time traffic, weather, and shipment data to resequence pickups and linehaul departures. Mid-sized carriers in the Southeast and Texas corridor adopt cloud-based versions to narrow service gaps against national operators. The technology is fragmenting carrier tier differentiation by democratizing optimization capabilities previously captive to proprietary systems.
FMCSA's pending automatic emergency braking mandate will accelerate equipment procurement cycles for United States LTL fleets. Carriers must retrofit or replace tractors lacking compliant systems, concentrating capital deployment in 2025-2027. The rule most affects smaller regional operators with older fleet age profiles, pressuring consolidation or exit.
Enterprise shippers are unbundling transportation management from freight payment, contracting separately with software vendors and executing carriers. This procurement pattern shifts negotiating leverage toward large retailers with data science capabilities. The behavior is most visible among omnichannel distributors in California and the Northeast seeking granular cost visibility by lane and service level.
United States less than-Truck-Load (LTL) Market Segmentation
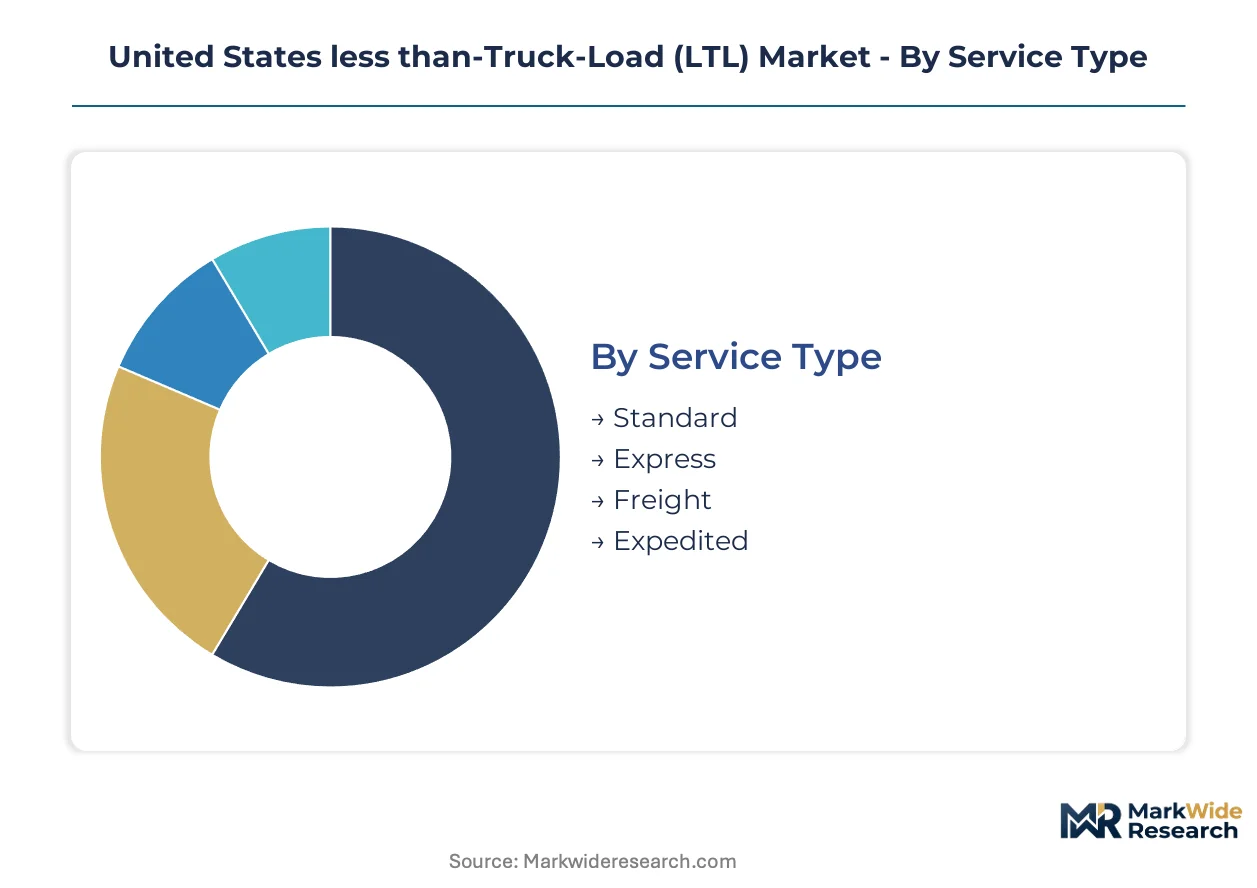
LTL segmentation reflects divergent cost-service tradeoffs across shipper profiles. Service tiers and pricing structures determine carrier network design and capital allocation priorities.
Service Type:
Express and expedited segments face acute substitution pressure from parcel carriers and dedicated final-mile platforms at weight break points below 300 pounds, forcing LTL operators to defend lane density through guaranteed transit windows.
- Standard:Consolidated freight moving through hub-and-spoke terminal networks with 2-5 day transit windows. Retailers in Texas and the Southeast corridor generate the densest volume flows, though margin compression intensifies during capacity gluts.
- Express:Accelerated service with next-day or second-day delivery commitments commanding 40-60% rate premiums. Manufacturing supply chains in Tennessee and Ohio absorb these costs to prevent production line stoppages.
- Freight:Heavier shipments approaching truckload thresholds that bypass standard sortation for direct linehaul injection. Industrial distributors leverage this tier for machinery components where full truckload economics remain elusive.
- Expedited:Time-critical shipments with dedicated equipment and team-driver configurations. Healthcare distributors in New Jersey and Pennsylvania contract for temperature-controlled expedited service during supply disruptions.
Standard service anchors the volume base while express gains share at the steepest rate.
Pricing Model:
Cost tier differentiation separates transactional shippers from enterprise accounts with committed volume tiers and multi-year contract structures.
- Weight-Based:Classification systems using NMFC density ratings to assign freight classes that determine base rates. Mid-sized manufacturers in the Midwest rely on this model for unpredictable shipment patterns.
- Flat Rate:Negotiated per-shipment or per-pallet pricing independent of weight fluctuations within agreed parameters. Large retailers with consistent lane volumes extract favorable terms through annual bids.
- Distance-Based:Zone-based pricing matrices that escalate with mileage bands. Regional carriers deploy this structure to capture intraregional freight against national networks.
- Accessorial Charges:Surcharges for liftgate service, residential delivery, and reclassification disputes. These fees represent 15-25% of invoice totals for e-commerce fulfillment flows.
Weight-based pricing dominates transactional relationships while flat-rate structures expand most quickly among enterprise accounts.
Customer Type:
Application concentration varies sharply between cost-sensitive commodity flows and specialized industrial requirements.
- Large Enterprises:National accounts with centralized procurement and TMS integration demanding granular visibility. Omnichannel retailers in California negotiate lane-specific rate cards with volume commitments.
- SMEs:Fragmented shippers lacking procurement leverage, typically served through 3PL aggregation or spot market platforms. Brokers consolidate this demand for regional carrier access.
- Retailers:Distribution center replenishment and store delivery networks with strict appointment scheduling requirements. Population migration to the Southeast intensifies freight density for this segment.
- Manufacturers:Inbound parts logistics and outbound finished goods distribution with just-in-time delivery constraints. Automotive suppliers in South Carolina generate consistent LTL demand.
Large enterprises anchor the volume base while SMEs climb the fastest through digital freight matching adoption.
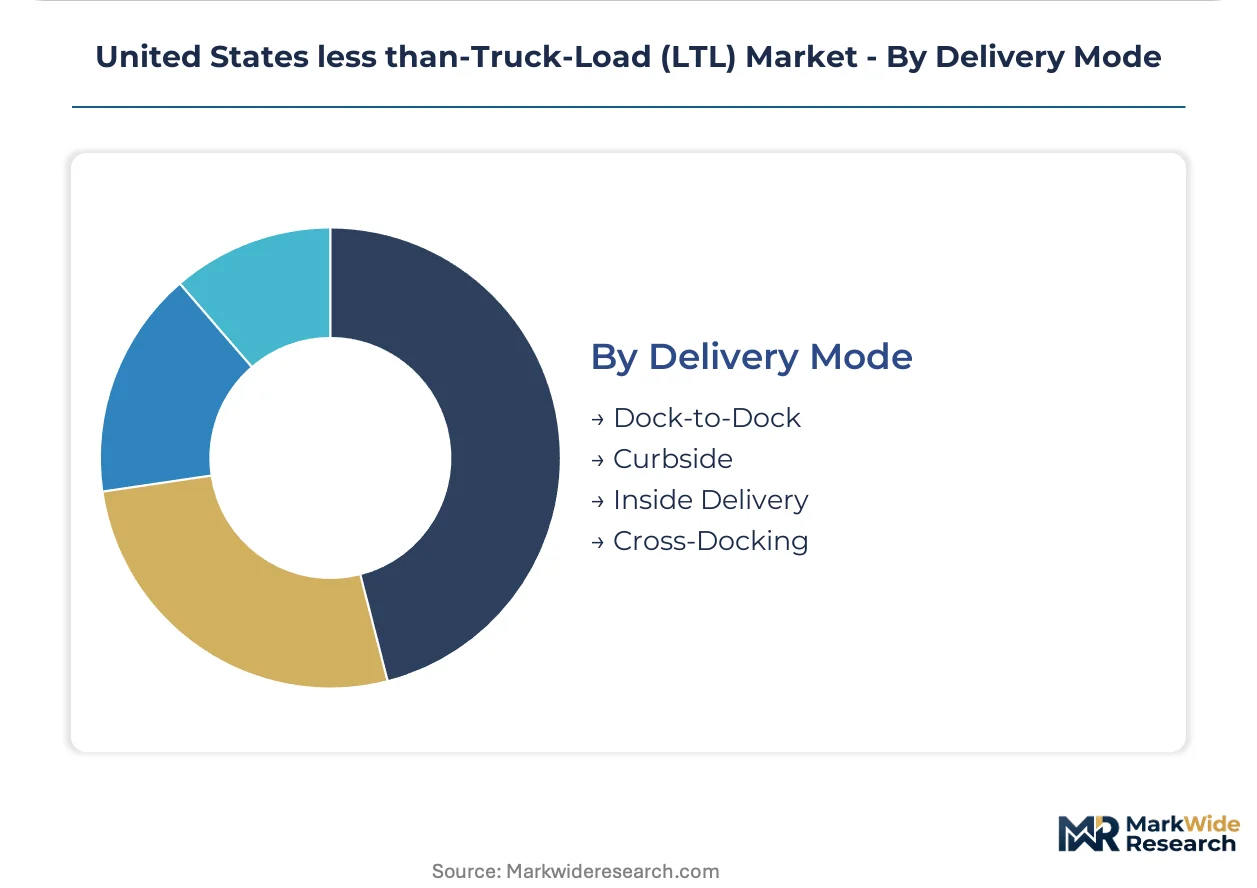
Delivery Mode:
Geographic concentration of terminal assets determines which delivery modes carriers can profitably offer.
- Dock-to-Dock:Terminal-to-terminal service excluding final-mile handling, preserving the highest trailer utilization rates. Industrial parks in Ohio and Michigan generate dense dock-to-dock flows.
- Curbside:Limited access delivery without inside handling, common for residential e-commerce shipments. Urban density in Dallas-Fort Worth and Atlanta supports this mode at scale.
- Inside Delivery:White-glove service with placement and debris removal for bulky goods. Furniture retailers absorb premium pricing for this capability.
- Cross-Docking:Direct trailer-to-trailer transfer bypassing warehouse storage for time-sensitive freight. Regional carriers in the Southeast leverage this mode for retail distribution center injection.
Dock-to-dock retains the highest volume share while inside delivery expands most quickly through e-commerce convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway system and Class I rail interchanges at Memphis, Chicago, and Dallas-Fort Worth anchor freight density across the United States LTL network. Terminal positioning along these corridors determines carrier operating economics and service coverage.
Southeast Corridor
Population migration to Florida and Georgia generates retail replenishment flows through Atlanta and Jacksonville distribution centers. The Federal Motor Carrier Safety Administration's Compliance, Safety, Accountability scoring system filters carrier access to major shippers in this region. Charlotte and Greenville-Spartanburg host automotive supplier clusters producing steady inbound parts demand.
Texas Triangle
Manufacturing reshoring along the Dallas-Houston-San Antonio axis drives machinery and equipment freight. EPA emissions standards for medium- and heavy-duty trucks accelerate fleet turnover among regional carriers operating here. The Port of Houston's container volume feeds cross-dock operations in the metro area.
Midwest Manufacturing Belt
Automotive and industrial machinery production in Ohio, Michigan, and Indiana sustains dock-to-dock LTL density. OSHA workplace safety regulations influence terminal automation investments at cross-dock facilities. Detroit and Cleveland serve as consolidation points for supplier networks serving the region.
Northeast Corridor
Pharmaceutical and healthcare distribution in New Jersey and Pennsylvania commands temperature-controlled service premiums. The Department of Transportation's infrastructure funding programs target bridge and highway maintenance along I-95. Philadelphia and Baltimore terminals handle significant import container drayage conversion to LTL.
Mountain West
E-commerce fulfillment centers in Phoenix and Salt Lake City create middle-mile injection demand from coastal ports. Driver shortage concentration in long-haul linehaul positions forces wage inflation here. Denver functions as a regional hub connecting Pacific Coast imports to interior markets.
United States less than-Truck-Load (LTL) Market Competitive Landscape
Listed leaders compete with private specialists across terminal network density and technology platforms. The market structure concentrates volume among national networks with hub-and-spoke scale, while regional operators defend lane-specific positions. Three archetypes dominate: asset-heavy national carriers with proprietary optimization systems, technology-forward challengers integrating dynamic pricing engines, and family-owned regional specialists with dense local terminal coverage. Consolidation through terminal network acquisitions and strategic partnerships with final-mile platforms represent the dominant competitive moves.
Within the national carrier tier, FedEx Freight and Old Dominion Freight Line occupy positions defined by terminal density and operating ratio discipline. XPO, Inc. exemplifies the technology-forward archetype through freight optimization platform investments. Among regional specialists, Southeastern Freight Lines represents the family-owned model with concentrated Southeast coverage. These three anchors illustrate how scale, technology, and geographic focus stratify competitive positioning.
| Leading Market Players |
|---|
| FedEx Freight |
| Old Dominion Freight Line |
| XPO, Inc. |
| Saia Inc. |
| ArcBest |
| Estes Express Lines |
| R+L Carriers |
| TFI International |
| Southeastern Freight Lines |
| Others |
Pricing and Supply Chain Analysis
Terminal density economies in the Southeast and Texas corridor simultaneously concentrate supply leverage and establish price floors that marginal carriers cannot undercut without sacrificing service integrity. Scale operators exploit this structural advantage through proprietary linehaul optimization that compresses cost per hundredweight while compliant fleet investments widen the gap between national networks and regional challengers.
Pricing Analysis
Volume-discount tiering structures separate large enterprise accounts with committed lane volumes from transactional shippers on spot-market platforms. Three-tier pricing stratifies across express, standard, and deferred service levels, with rate premiums of 40-60% separating express commitments from standard transit windows. Price differentiation hinges on FMCSA Compliance, Safety, Accountability scores and guaranteed delivery windows, with cost compression in standard service intensifying due to digital freight matching platform penetration. Small and medium enterprises exhibit the highest price sensitivity, while healthcare distributors absorb premium pricing for temperature-controlled expedited service.
Supply Chain Analysis
Inventory velocity and lead-time compression requirements in just-in-time manufacturing supply chains tether equipment procurement to terminal network positioning. Domestic production of linehaul tractors and trailers concentrates in Indiana, Ohio, and Michigan, while diesel engine components and telematics systems draw from Mexico and Canada. Single-source vulnerability in semiconductor-based electronic logging devices and automatic emergency braking systems creates procurement risk concentration. Distribution runs through hub-and-spoke terminal networks where Memphis, Chicago, and Dallas-Fort Worth function as primary consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States LTL market sits at a platform-economics inflection where freight optimization algorithms and API-based TMS interoperability are redistributing bargaining power toward data-rich shippers and technology-forward carriers.
For Market Incumbents: Shield terminal network density advantages through accelerated cross-dock automation investments that raise capital barriers for mid-sized competitors. Deepen backward integration into final-mile delivery capabilities in Dallas-Fort Worth, Atlanta, and Phoenix to capture e-commerce weight break migration above 150 pounds. Marginal carrier exits driven by FMCSA safety fitness determination tightening present acquisition opportunities for terminal footprint expansion. For New Entrants and Emerging Players: FMCSA safety certification fast-tracks for compliant fleet operators open preferred shipper status that national carriers have already captured. Target healthcare supply chain specialization in New Jersey and Pennsylvania, where temperature-controlled service commands rate premiums and multi-year contract structures reduce customer acquisition friction. Deploy cloud-based dispatch optimization to narrow service gaps against scaled networks without proprietary infrastructure investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carriers with dense Southeast and Texas corridor coverage where population migration sustains freight density growth. Long-term viability favors asset-heavy operators with sub-85 operating ratios and disciplined geographic expansion track records. Monitor digital freight matching platform adoption rates among small and medium enterprises as an inflection indicator for margin compression velocity in standard service tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Network Automation | Cross-dock sorting systems at Memphis and Dallas-Fort Worth facilities compress dwell time and labor cost per shipment. |
| Final-Mile Capability Integration | Urban terminal density in Atlanta and Phoenix captures e-commerce bulky goods above parcel weight thresholds. |
| Compliant Fleet Certification | Superior FMCSA CSA scores unlock preferred shipper contracts and lower insurance premium structures. |
| Healthcare Cold Chain Specialization | Temperature-controlled service for pharmaceutical distributors in New Jersey commands multi-year rate premiums. |
| Dynamic Pricing Platform Deployment | Real-time freight matching algorithms narrow information advantages historically held by dense terminal networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with carrier operations executives, shipper logistics directors, third-party logistics procurement managers, and freight brokerage principals. Secondary validation drew from FMCSA regulatory filings, Department of Transportation infrastructure funding disclosures, EPA emissions standards documentation, and carrier SEC 10-K operating ratio disclosures. Bottom-up shipment volume modeling and top-down macroeconomic freight demand indicators were triangulated to establish market sizing boundaries.
Across the analysis window, the forecasting framework modeled segmentation dimensions including service tier, pricing model structure, customer type, and delivery mode complexity. CAGRs were derived from regression analysis against industrial production indices, e-commerce penetration rates, and manufacturing reshoring announcements. Key inputs included diesel price volatility assumptions, driver wage inflation trajectories, and FMCSA equipment mandate compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained manufacturing reshoring momentum or accelerated EPA emissions compliance deadlines would require recalibration. Forecasts reflect documented assumptions regarding carrier consolidation velocity and shipper procurement centralization trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market