
 Indonesia Road Freight Transport Market | 2026-2036
Indonesia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Road Freight Transport Market Foresight
Modular fleet configurations combining dedicated and shared capacity is repositioning how shippers contract road transport. JNE Express leverages its last-mile density across Indonesian archipelago routes to sustain parcel volume leadership. GEODIS anchors European-Asia trade lane expertise into Indonesian contract logistics. Samudera Indonesia competes through intermodal port-to-warehouse integration spanning Tanjung Priok to hinterland distribution centers.
Indonesia road freight transport encompasses the movement of goods by commercial vehicles across national highway networks, involving payloads from light-duty urban delivery to heavy-duty long-haul operations with gross vehicle weights regulated under axle load limits. This sector serves as the dominant domestic cargo mode, connecting manufacturing zones, agricultural collection points, and maritime ports across the archipelago's fragmented geography. Full Truck Load services dominate margin pools on major corridors where manufacturing shippers seek direct point-to-point efficiency, while Less Than Truck Load networks capture fragmented SME demand through consolidation hubs near Jakarta and Surabaya. Refrigerated Trucks represent the fastest-expanding vehicle category as cold chain requirements intensify for Food & Beverage end users moving perishables from plantation regions to urban retail.
Indonesia's Ministry of Transportation enforces axle load regulations and mandatory weighbridge compliance that directly constrain fleet composition and route planning for operators. BIS-equivalent national standards for commercial vehicle safety certification shape procurement decisions for Heavy Duty Trucks entering the market. The National Logistics System roadmap coordinates port-to-road infrastructure investment that will determine future freight corridor competitiveness. Stakeholders must monitor toll road expansion timelines and fuel subsidy restructuring as these policy levers will alter operating cost structures and route economics across the archipelago.
Market Dynamics
The Ministry of Transportation's mandatory truck weight monitoring systems are compressing fleet economics and forcing rapid compliance investments across Indonesian road freight operators, fundamentally restructuring how capacity is contracted and deployed.
Growth Catalysts
- E-commerce logistics expansion:Digital retail platforms are scaling parcel volumes across Java and Sumatra, creating dedicated lane demand that absorbs excess truck capacity during off-peak manufacturing windows.
- National Logistics System roadmap:Port-to-road infrastructure coordination is unlocking hinterland distribution center connectivity, reducing dwell times at Tanjung Priok and accelerating container velocity.
- Refrigerated transport specialization:Food & Beverage cold chain requirements are intensifying fleet upgrade cycles as plantation-to-retail temperature integrity becomes non-negotiable for perishable cargo.
Market Restraints
- Fuel subsidy restructuring uncertainty:Diesel price volatility threatens operating cost predictability for long-haul operators running the Jakarta-Surabaya corridor.
- Axle load enforcement concentration:Weighbridge compliance investments fall disproportionately on small fleet owners, accelerating consolidation toward larger asset-holding groups.
- Intermodal substitution pressure:Rail freight improvements on Java's northern coast are capturing bulk commodity flows that previously moved exclusively by truck.
Strategic Opportunities
- Eastern Indonesia archipelago penetration:Sulawesi and Papua logistics corridors remain underserved by integrated road networks, rewarding first-movers with port feeder integration.
- Digital freight matching platforms:Real-time load-board systems are collapsing information asymmetry between shippers and owner-operators, enabling dynamic spot market liquidity.
- BIS-equivalent safety certification premium:Compliant heavy-duty truck fleets command rate premiums from multinational manufacturing shippers with zero-tolerance safety audits.
Industry Challenges
- Commercial driver certification bottlenecks:The Ministry of Transportation's competency testing backlog delays license issuance, constraining fleet expansion timelines regardless of vehicle availability.
- Toll road network fragmentation:Discontinuous highway coverage forces multi-modal transfers that erode transit time advantages and complicate liability handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Road Freight Transport Market |
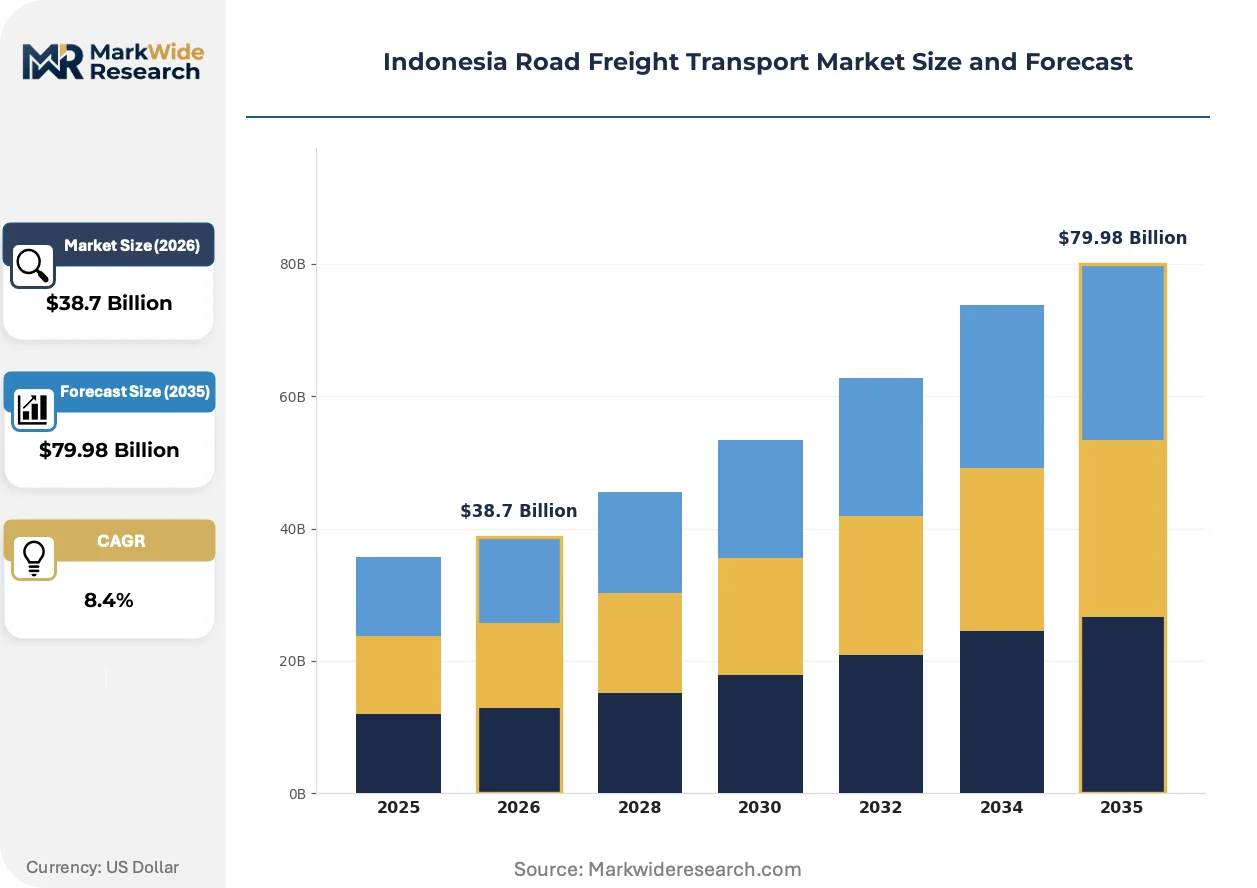
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Dedicated Freight, Intermodal Freight Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Refrigerated Trucks, Bulk Carriers End User: Retail, Manufacturing, Food & Beverage, Agriculture Load Type: Liquid Cargo, Dry Cargo, Hazardous Materials, General Cargo |
| Companies Covered | PT ABM Investama Tbk, JNE Express, NYK Line, GEODIS, DSV, Pancaran Group, PT Repex Wahana, Samudera Indonesia, PT Siba Surya, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Road Freight Transport Market Shifts & Advancements
Telematics integration and dynamic routing algorithms are compressing traditional dispatch hierarchies, while regulatory pressure on emissions and safety certification accelerates capital deployment toward compliant assets.
IoT-enabled fleet management systems are expanding into real-time cargo monitoring and predictive maintenance scheduling. Large manufacturing shippers with just-in-time production lines are mandating these systems as contract prerequisites. The technology is expanding into rate differentiation, with connected fleets commanding premiums over unmonitored competitors on the same lanes.
The Ministry of Transportation's mandatory weighbridge compliance regime is forcing hardware retrofits and route restructuring across heavy-duty operations. Fleet operators face capital outlays for onboard weight sensors and GPS tracking units to avoid penalties at enforcement checkpoints. Long-haul FTL providers serving manufacturing corridors are absorbing these costs fastest to maintain lane access.
Shippers are unbundling transport procurement from integrated logistics contracts, creating standalone freight tenders that pit specialized carriers against diversified 3PLs. Food & Beverage distributors with seasonal volume spikes are driving this shift, seeking rate transparency absent from bundled service agreements. The Jakarta-Bandung manufacturing belt exhibits the most aggressive tender unbundling as procurement teams centralize transport category management.
Indonesia Road Freight Transport Market Segmentation
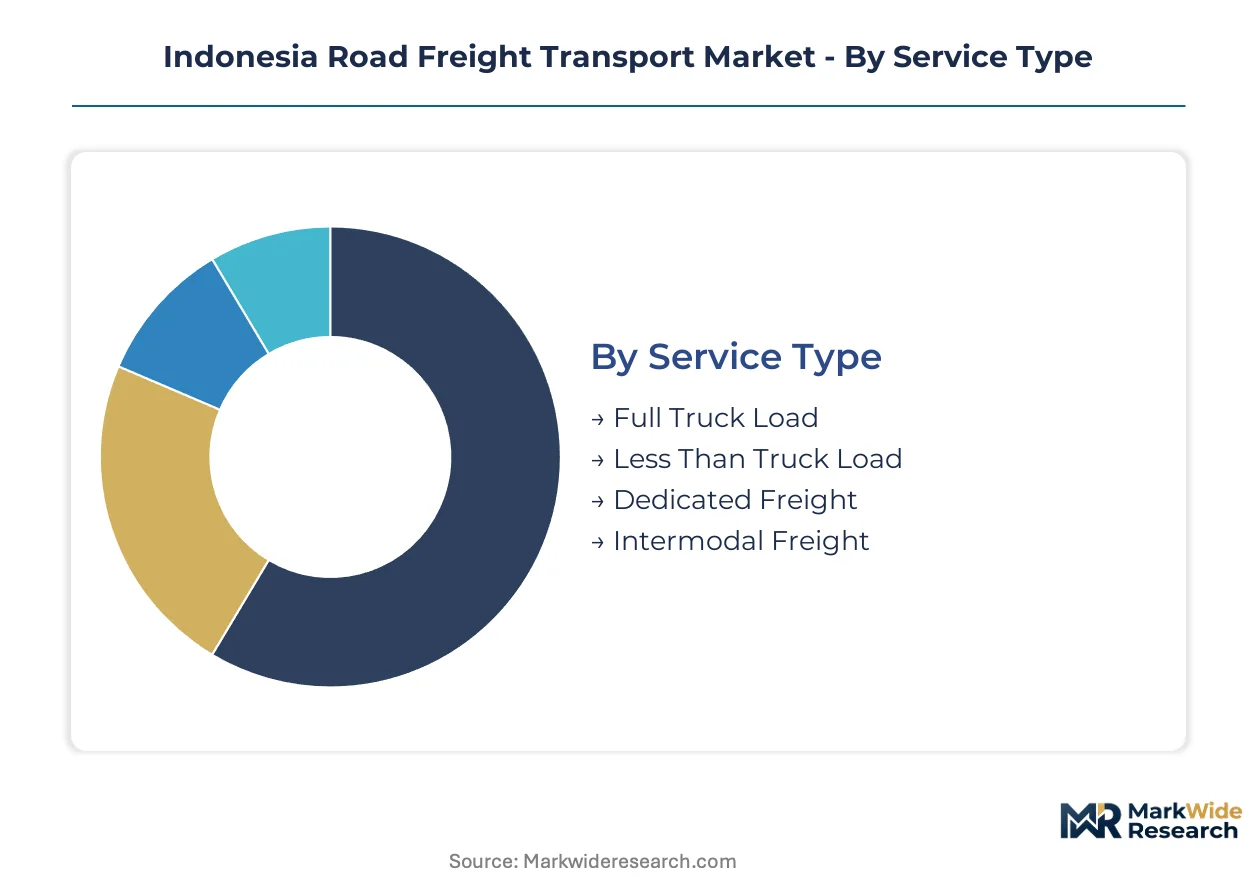
Road freight segmentation in Indonesia reveals how service specialization, vehicle configuration, and cargo characteristics determine competitive positioning across the archipelago's fragmented geography. Shippers match segment selection to corridor density, cargo value density, and regulatory compliance requirements.
Service Type:
Full Truck Load commands premium rates on dense corridors where manufacturing shippers prioritize point-to-point velocity, while Less Than Truck Load networks capture fragmented demand through consolidation economics.
- Full Truck Load:Direct vehicle allocation for single-shipper cargo dominates the Jakarta-Bandung-Surabaya manufacturing belt. Manufacturing clusters with just-in-time production lines mandate FTL for schedule reliability and liability clarity.
- Less Than Truck Load:Consolidation hub networks near Jakarta and Surabaya aggregate SME shipments into optimized lane density. E-commerce platforms with irregular parcel volumes drive hub-and-spoke infrastructure investment across Java.
- Dedicated Freight:Contracted fleet capacity reserved for specific shipper accounts reduces procurement friction for seasonal agricultural exporters.
- Intermodal Freight:Port-to-warehouse integration spanning Tanjung Priok to hinterland distribution centers accelerates container velocity.
Today's leader: Full Truck Load. Tomorrow's challenger: Less Than Truck Load.
Vehicle Type:
Axle load regulations and cargo temperature requirements split procurement between standardized heavy-duty platforms and specialized refrigerated units.
- Heavy Duty Trucks:Gross vehicle weights regulated under Ministry of Transportation axle load limits constrain fleet composition on long-haul corridors. BIS-equivalent safety certification shapes procurement decisions for manufacturing shipper contracts.
- Refrigerated Trucks:Temperature-controlled cargo compartments with integrated cooling systems serve plantation-to-retail cold chains. Food & Beverage distributors with perishable cargo mandates drive the steepest fleet upgrade cycles as compliance intensifies.
- Light Duty Trucks:Urban delivery configurations navigate Jakarta's congestion-charged zones for last-mile parcel distribution.
- Bulk Carriers:Open-bed designs with reinforced chassis handle agricultural commodities and construction materials across unpaved feeder roads.
Fleet investment gravity centers on Heavy Duty Trucks. Regulatory pressure is accelerating Refrigerated Trucks fastest.
End User:
Manufacturing volume concentration in Western Java contrasts with agricultural seasonality and retail fragmentation across the archipelago.
- Manufacturing:Electronics and automotive component producers in the Jakarta-Bandung corridor generate continuous lane demand with strict delivery windows. These shippers mandate telematics integration as contract prerequisites.
- Food & Beverage:Cold chain integrity requirements from plantation regions to urban retail drive specialized vehicle procurement and route planning.
- Retail:E-commerce logistics platforms absorb excess truck capacity during off-peak manufacturing windows.
- Agriculture:Palm oil and rubber exporters face seasonal volume spikes that strain dedicated contract coverage.
Contract value concentrates with Manufacturing. Service complexity escalates fastest for Food & Beverage.
Load Type:
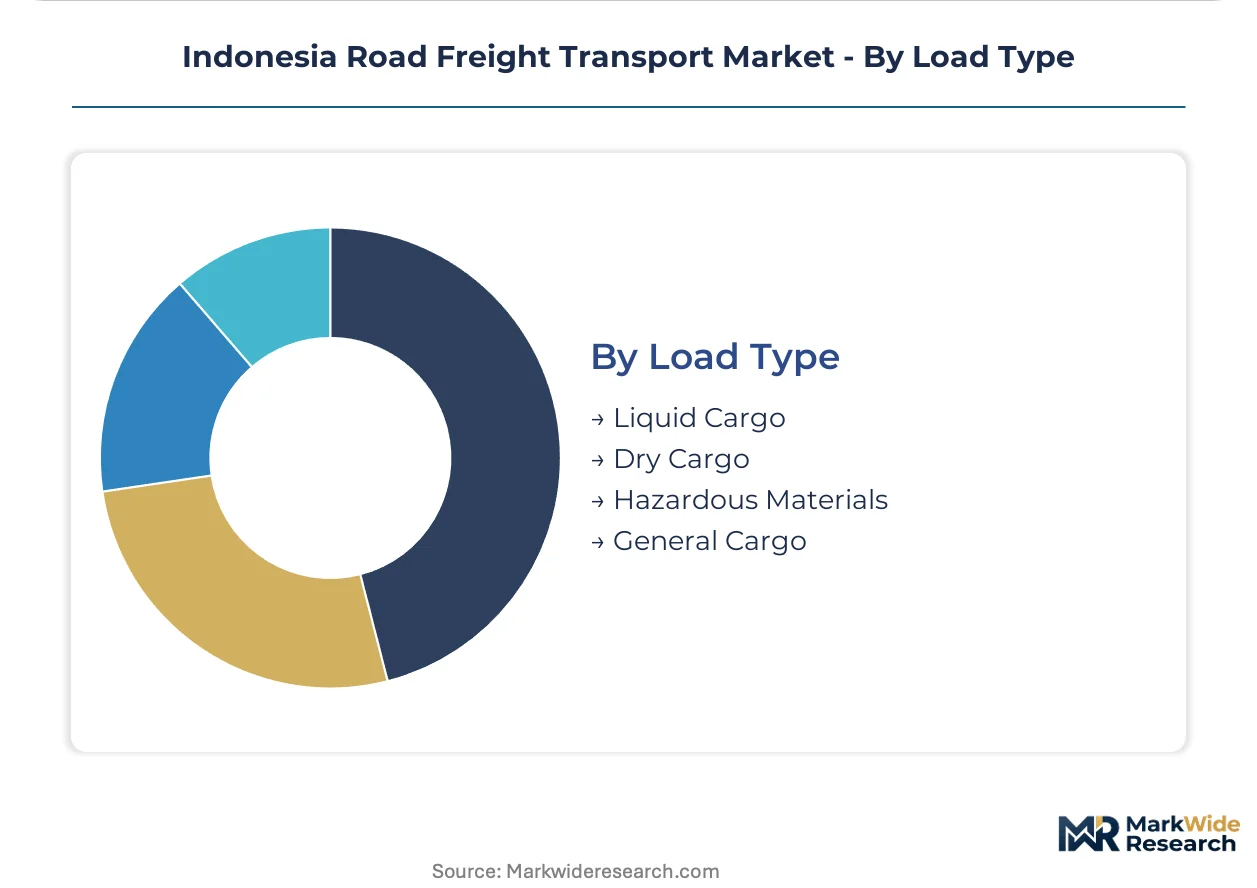
Cargo hazard classification and physical state determine vehicle specification, routing restrictions, and insurance layering.
- Dry Cargo:Packaged goods and palletized manufacturing outputs move through standard curtain-side or box configurations on all corridor types.
- Liquid Cargo:Tanker configurations with baffle systems transport palm oil derivatives and fuel products under hazardous materials protocols.
- General Cargo:Mixed commodity shipments without specialized handling requirements fill backhaul capacity on irregular lanes.
- Hazardous Materials:Chemical and flammable goods face route restrictions and mandatory escort requirements that compress operating flexibility.
Volume dominance sits with Dry Cargo. Compliance complexity peaks with Hazardous Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's road freight industry traces its modern lineage to the 1970s Trans-Java Highway construction, which established the Jakarta-Bandung-Surabaya corridor as the nation's commercial spine. This infrastructure legacy continues concentrating manufacturing investment and logistics demand across Western Java.
Java
Electronics assembly plants and automotive component factories generate continuous FTL demand along the northern coastal highway. The Ministry of Transportation's mandatory weighbridge compliance regime forces fleet retrofits at Tanjung Priok port gates. The Jakarta-Bandung manufacturing belt exhibits the most aggressive transport procurement centralization as shippers unbundle logistics contracts.
Sumatra
Palm oil plantation exports and rubber processing create seasonal volume spikes that strain dedicated contract coverage. The National Logistics System roadmap coordinates Belawan port feeder road upgrades with hinterland distribution center placement. Medan anchors northern Sumatra's consolidation hub network for LTL aggregation.
Sulawesi
Nickel mining corridors and agricultural collection points drive bulk carrier deployment across unpaved feeder roads. Limited integrated highway coverage rewards operators with port feeder integration capabilities. Makassar serves as the primary intermodal gateway connecting maritime routes to interior mining districts.
Kalimantan
Coal and palm oil exports dominate heavy-duty truck utilization on East Kalimantan's industrial roads. The Ministry of Transportation's axle load enforcement concentrates compliance investments among coal fleet operators serving Samarinda-Balikpapan routes. Pontianak in West Kalimantan handles cross-border trade flows with Malaysian Sarawak.
Papua
Isolated mining operations and government infrastructure projects absorb specialized project cargo capacity on limited road networks. Fuel subsidy restructuring uncertainty threatens operating cost predictability for long-haul operators serving Timika and Jayapura. The region remains underserved by integrated logistics networks despite resource extraction scale.
Indonesia Road Freight Transport Market Competitive Landscape
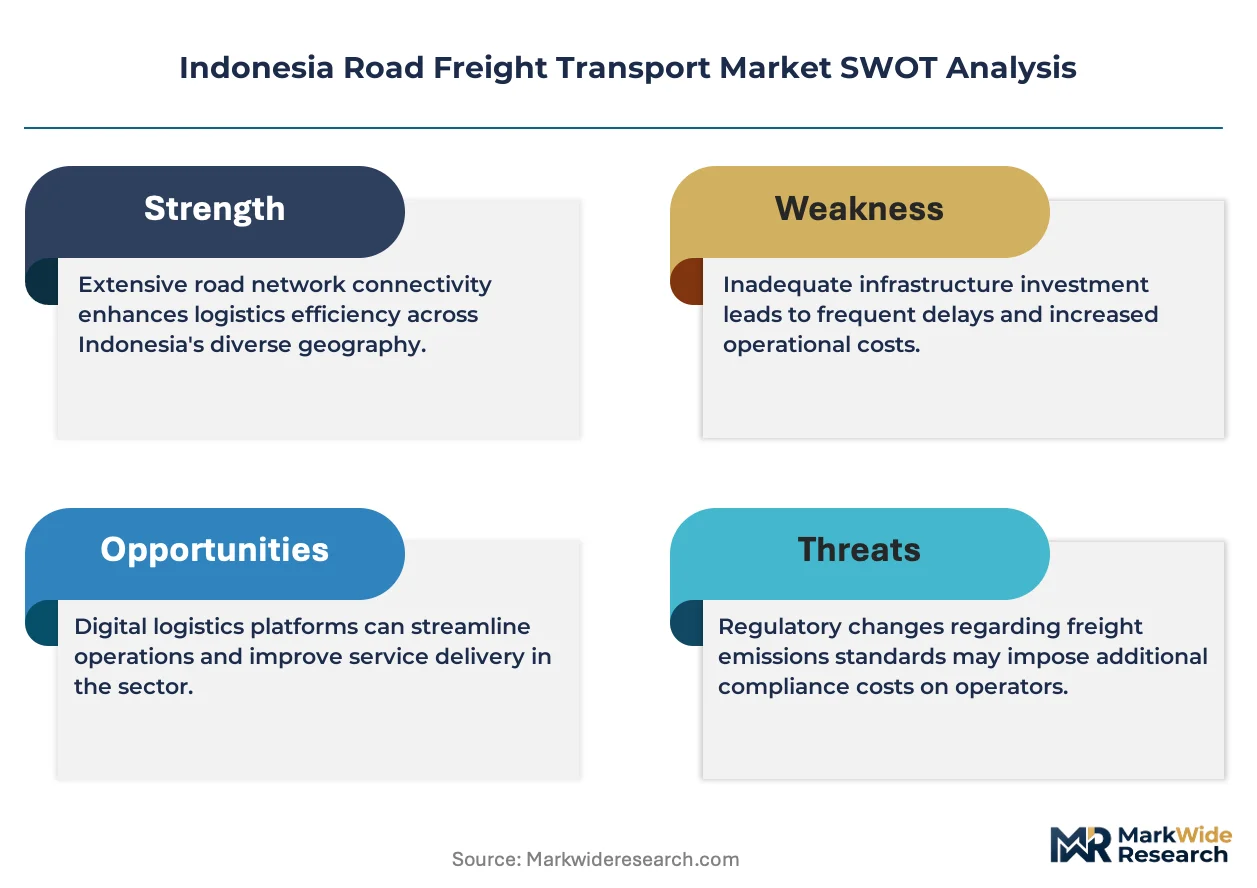
Premium-margin players sit above commodity-margin players across fleet compliance certification and telematics integration capabilities. The vendor base organizes into three tiers: multinational contract logistics operators with European trade lane expertise, domestic integrated port-to-warehouse specialists, and fragmented owner-operator networks serving spot markets. Strategic moves concentrate on weighbridge compliance hardware deployment and dynamic freight matching platform partnerships.
Among Indonesia-based integrated logistics operators, Samudera Indonesia and Pancaran Group exemplify the port-to-warehouse integration archetype. JNE Express anchors the domestic parcel density tier with archipelago-wide last-mile coverage. European contract logistics presence includes GEODIS, which occupies a position translating continental supply chain standards into Indonesian manufacturing shipper relationships.
| Leading Market Players |
|---|
| PT ABM Investama Tbk |
| JNE Express |
| NYK Line |
| GEODIS |
| DSV |
| Pancaran Group |
| PT Repex Wahana |
| Samudera Indonesia |
| PT Siba Surya |
| Others |
Supply & Pricing Matrix
Family-owned fleet operators with multi-generational route licenses anchor pricing discipline across Java's dense corridors, while their fragmented ownership structure limits consolidated bargaining power against fuel suppliers and toll road concessionaires. This ownership pattern concentrates supply-side responsiveness in the hands of operators who prioritize lane access over margin expansion, compressing rate premiums even for certified fleets.
Pricing Analysis
Contract-based long-term offtake agreements with manufacturing shippers dominate pricing structures on the Jakarta-Bandung-Surabaya corridor. Price differentiation separates BIS-equivalent certified fleets from unmonitored competitors, with telematics integration and weighbridge compliance serving as the primary tiering mechanisms. Pricing pressure stems from fuel subsidy restructuring uncertainty that erodes cost predictability for diesel-dependent long-haul operators. SME shippers in the LTL segment exhibit highest price sensitivity, while multinational manufacturing accounts with zero-tolerance safety audits accept certified-fleet premiums.
Supply Chain Analysis
Commercial vehicle manufacturing rests on Japanese and Chinese heavy-duty truck producers, with domestic assembly plants dependent on imported powertrain components and emissions control systems. Diesel fuel supply draws from state-owned Pertamina refineries and cross-border Singapore trading hubs, while telematics hardware feeds from Taiwanese semiconductor foundries and South Korean sensor specialists. Single-source vulnerability concentrates in onboard weight monitoring systems mandated by the Ministry of Transportation's compliance regime. Distribution runs through Tanjung Priok port gates and Tanjung Perak feeder networks into hinterland consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's road freight market functions as a geographic-arbitrage play between Java's infrastructure-saturated corridors and Eastern Indonesia's archipelago logistics gaps, where fuel cost differentials and toll road coverage gaps create divergent operating economics.
For Market Incumbents: Cement weighbridge compliance leadership by accelerating hardware retrofits ahead of enforcement checkpoint expansion, locking in lane access privileges that competitors forfeit. Deepen backward integration into fuel procurement through direct Pertamina supply contracts, insulating margin structures from subsidy volatility that threatens spot-market operators. For New Entrants and Emerging Players: Enter via digital freight matching platforms that collapse information asymmetry between Sulawesi mining shippers and underutilized bulk carrier capacity. Target Papua's isolated resource extraction corridors where project cargo demand outstrips integrated logistics supply, leveraging port feeder relationships as the primary go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned mid-cap fleet operators facing generational succession pressures and compliance capital demands. Long-term viability hinges on consolidation plays that aggregate route licenses and telematics-certified capacity across fragmented ownership. Watch fuel subsidy restructuring announcements as the inflection signal that re-rates operating cost structures industry-wide.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Connected fleets command rate premiums from multinational manufacturing shippers with zero-tolerance safety audits. |
| Weighbridge Compliance Hardware Deployment | Onboard weight sensors and GPS tracking units prevent penalties at Ministry of Transportation enforcement checkpoints. |
| Backward Integration into Fuel Procurement | Direct Pertamina supply contracts insulate margin structures from diesel price volatility threatening long-haul operators. |
| Eastern Indonesia Port Feeder Expansion | Sulawesi and Papua logistics corridors reward first-movers with underserved mining and agricultural collection point access. |
| Refrigerated Fleet Specialization | Temperature-controlled cargo compartments capture plantation-to-retail cold chain demand from Food & Beverage distributors. |
Research Methodology
Multiple input streams — fleet operator interviews, manufacturing shipper procurement panels, and Ministry of Transportation regulatory filings — were reconciled against customs trade data, toll road concessionaire disclosures, and commercial vehicle registration databases. Primary fieldwork engaged fleet managers at Jakarta and Surabaya consolidation hubs, logistics procurement leads at electronics and automotive OEMs, and weighbridge enforcement officers. Secondary validation drew from BIS-equivalent safety certification records, Pertamina fuel distribution reports, and National Logistics System roadmap documentation. Bottom-up capacity estimates and top-down corridor demand models were triangulated to constrain forecast variance.
Historical volume trajectories were cross-referenced against panel input from shipper procurement teams to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated service type, vehicle configuration, end-user industry, and regional corridor density as core dimensions. CAGRs were derived from elasticity-adjusted demand curves that weight manufacturing output forecasts, e-commerce parcel growth indices, and cold chain infrastructure investment pipelines. Forecast inputs specifically incorporated toll road expansion timelines and fuel subsidy restructuring scenarios as scenario-dependent variables.
Inputs from fleet operator interviews and regulatory enforcement data were available through the study window; gaps in Eastern Indonesia spot market transaction records introduce uncertainty bands around Sulawesi and Papua demand estimates. Forecasts reflect documented assumptions regarding infrastructure investment continuity and subsidy policy stability. Regulatory enforcement intensity, commodity export price volatility, and intermodal rail substitution rates warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
United States less than-Truck-Load (LTL) Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market