
 Slovakia Road Freight Transport Market | 2026-2036
Slovakia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Road Freight Transport Market Insights
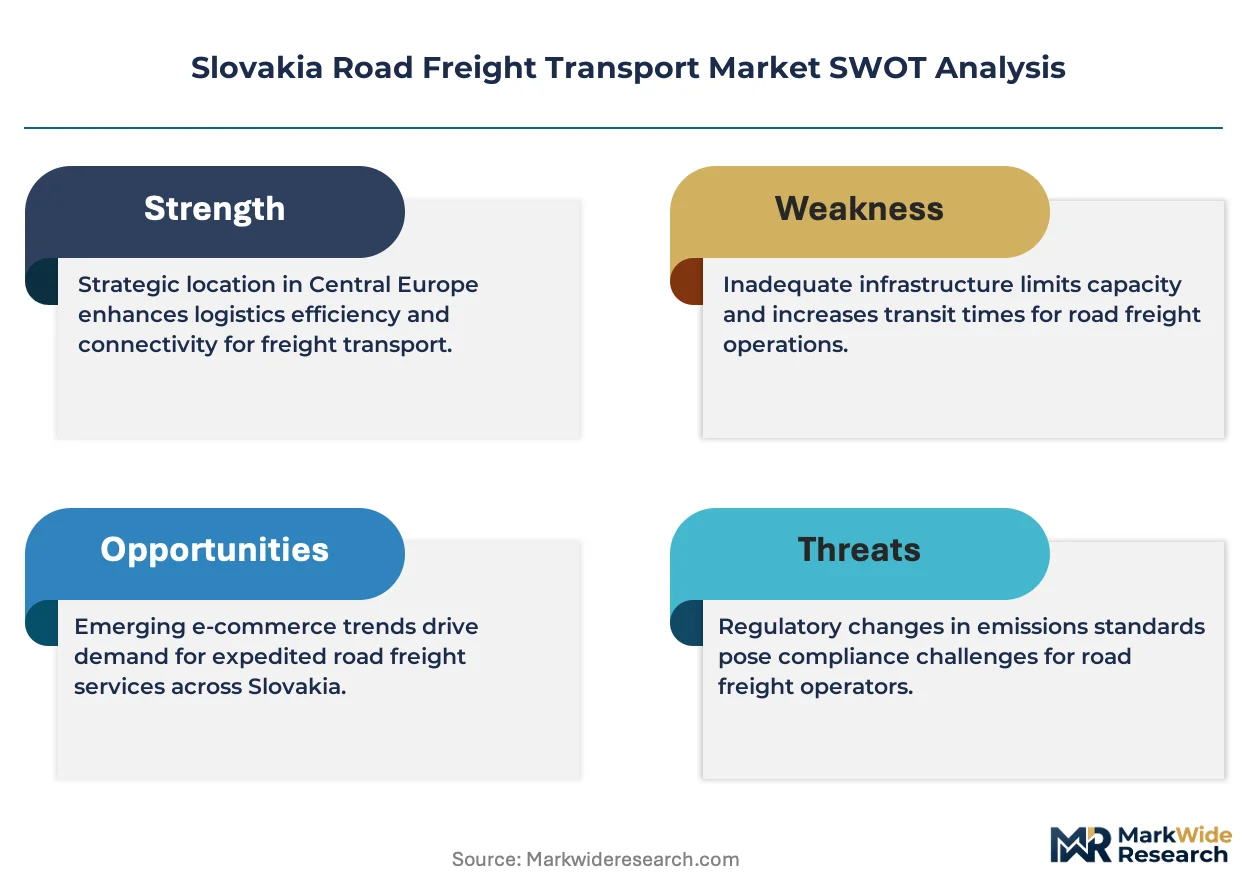
Automotive component logistics is rebalancing Slovakia's road freight demand as electric vehicle supply chains alter inbound material flows. DSV A/S leverages its European network density to capture cross-border assembly plant deliveries. Kuehne+Nagel sustains refrigerated and just-in-time contracts with precision scheduling systems. Budamar Logistics anchors domestic capacity through its Bratislava hub operations and regional fleet positioning.
Road freight transport encompasses the movement of goods via motor vehicles over public highway networks, utilizing trucks rated from light commercial vans to heavy-duty tractor-trailers with gross vehicle weights exceeding 40 tonnes. Full Truckload services dominate contract revenue streams for automotive and industrial clients requiring dedicated trailer capacity on fixed routes. Less Than Truckload operations compete through consolidation efficiency for mid-size manufacturers lacking volume for direct haulage. Intermodal Services extend reach by combining road legs with rail corridors through METRANS terminal infrastructure at Bratislava and Dunajska Streda.
The European Union Mobility Package enforces revised cabotage restrictions and driver posting rules that reshape cross-border fleet utilization for Slovak operators. National transport authorities align domestic tachograph enforcement with EU driving time regulations while the country's environmental ministry advances CO2 emission standards for commercial vehicle access to urban zones. Stakeholders must monitor alignment between EU Green Deal transport targets and Slovakia's charging infrastructure rollout for electric heavy-duty vehicles.
Market Dynamics
The EU Mobility Package's revised cabotage restrictions are restructuring fleet deployment patterns across Slovak road freight operators, forcing carriers to rebalance cross-border route assignments and driver posting compliance. Automotive assembly plants along the Bratislava-Zilina corridor are simultaneously demanding tighter just-in-time delivery windows, compressing carrier response capabilities.
Growth Catalysts
- EU Green Deal transport targets:Slovakia's environmental ministry is advancing CO2 emission standards for commercial vehicle access to urban zones, accelerating fleet renewal toward low-emission heavy-duty vehicles.
- Electric vehicle supply chain reconfiguration:Inbound material flows to battery and component plants are generating dedicated contract lanes requiring specialized temperature-controlled and high-security trailer capacity.
- Bratislava-Zilina industrial corridor:Concentrated demand from automotive clusters and electronics manufacturing is anchoring hub-and-spoke logistics infrastructure investments.
Market Restraints
- Driver availability constraints:EU posting rules under the Mobility Package limit flexible workforce deployment, tightening labor supply for cross-border operations.
- Diesel price volatility:Fuel cost fluctuations directly compress operating margins for asset-heavy carriers lacking fuel surcharge pass-through mechanisms.
- Rail corridor competition:METRANS terminal infrastructure at Bratislava and Dunajska Streda offers intermodal alternatives for containerized automotive parts, capping pure road freight pricing power.
Strategic Opportunities
- Eastern Slovakia manufacturing zones:Underpenetrated industrial parks near Kosice present greenfield contract opportunities as automotive suppliers diversify beyond the western corridor.
- Refrigerated pharmaceutical logistics:Cold chain requirements for temperature-sensitive biologics are expanding addressable market scope beyond traditional industrial freight.
- EU Alternative Fuels Infrastructure Regulation:Mandated charging and hydrogen refueling networks along Trans-European Transport corridors will enable electric heavy-duty vehicle deployment on international lanes.
Industry Challenges
- Tachograph compliance enforcement:National transport authorities' alignment with EU driving time regulations requires real-time digital monitoring system investments across fragmented carrier fleets.
- Legacy fleet electrification capex:Battery-electric and hydrogen fuel cell tractor units demand capital deployment timelines that strain mid-size operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Road Freight Transport Market |
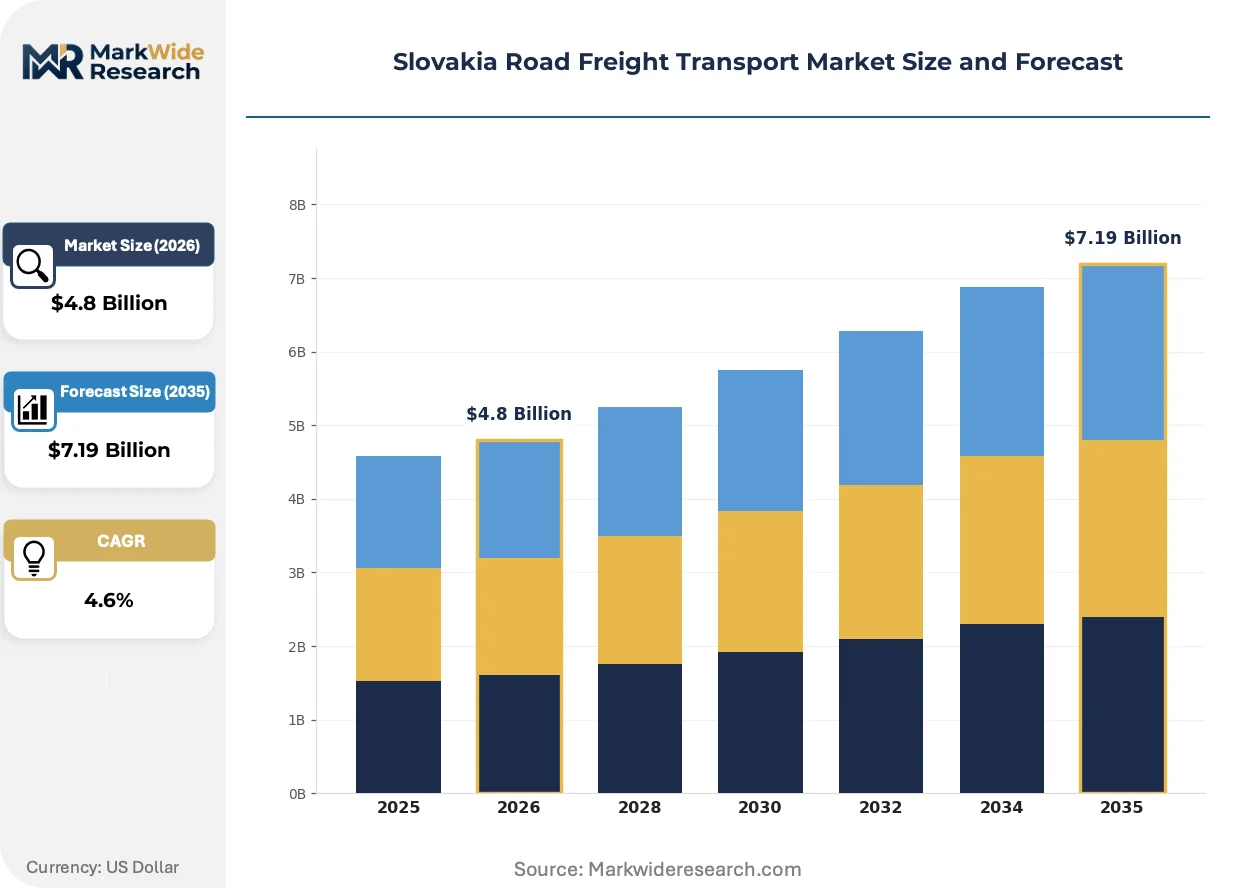
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Expedited Shipping, Intermodal Services Vehicle Type: Flatbed Trucks, Refrigerated Trucks, Tanker Trucks, Vans End User: Retailers, Manufacturers, E-commerce Companies, Wholesalers Delivery Model: Direct Delivery, Scheduled Delivery, Same-Day Delivery, Last-Mile Delivery |
| Companies Covered | DSV A/S, DHL Group, Kuehne+Nagel, Dachser, CEVA Logistics, Raben Group, GARTNER KG, Budamar Logistics, METRANS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Road Freight Transport Market Trends and Innovations
Digital freight platforms and alternative powertrain technologies are simultaneously compressing traditional brokerage margins and rewriting asset utilization economics across Slovak road transport. Carrier investment priorities are pivoting toward connected fleet management and emissions compliance infrastructure.
Telematics-integrated route optimization is rewriting dispatch efficiency for full truckload operators serving just-in-time automotive contracts. DSV A/S and Kuehne+Nagel are deploying predictive arrival systems across their Slovak fleets to compress dwell times at Bratislava assembly plant gates. The technology is enabling carriers to commit to tighter delivery windows without proportional fleet expansion.
EU Mobility Package cabotage rule revisions are forcing Slovak operators to restructure driver posting and vehicle registration configurations. The regulation compresses operational flexibility for carriers running triangular routes between Slovakia, Czech Republic, and Austria. Smaller domestic fleets are responding by concentrating capacity on dedicated contract lanes rather than spot market exposure.
Shippers are consolidating vendor relationships toward integrated logistics providers capable of bundling road, rail, and warehousing services. Automotive component manufacturers are displacing fragmented carrier portfolios with single-source contracts covering inbound material flows. This concentration is most visible among battery suppliers establishing Slovak manufacturing presence requiring multimodal coordination.
Slovakia Road Freight Transport Market Segmentation
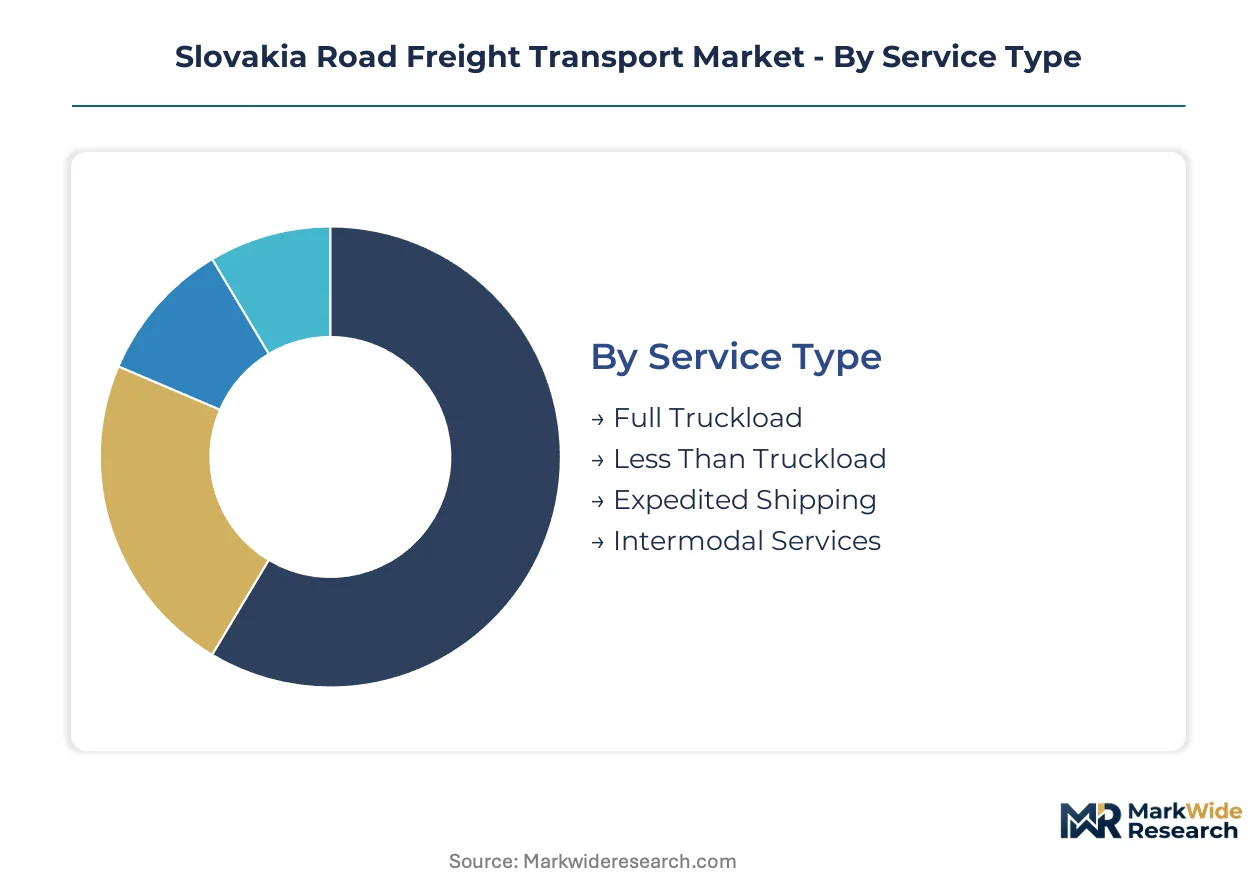
Slovakia's road freight market segments along service intensity, equipment specialization, and delivery velocity dimensions. Carrier portfolio decisions hinge on matching these segment profiles to the automotive-dominated cargo flows along the Bratislava-Zilina corridor.
Service Type:
Full Truckload and Less Than Truckload services dominate contract renewals as automotive manufacturers consolidate vendor relationships around dedicated capacity and scheduled consolidation efficiency.
- Full Truckload:Dedicated trailer capacity on fixed routes serves assembly plants requiring uninterrupted inbound material flows. Volkswagen Bratislava and Kia Zilina anchor demand for sealed dry van and flatbed units on contract lanes with penalty clauses for delivery window misses.
- Less Than Truckload:Consolidation networks aggregate shipments from mid-size suppliers lacking volume for direct haulage. Regional terminals in Nitra and Trnava sort freight for line-haul injection into Bratislava hub operations, compressing unit costs through density.
- Expedited Shipping:Emergency parts and production-critical components move via dedicated sprinter vans and small trucks outside scheduled networks. Premium pricing reflects driver standby availability and route flexibility.
- Intermodal Services:METRANS terminal infrastructure at Dunajska Streda enables rail-road combinations for containerized automotive parts bound for export markets.
Volume placements concentrate in Full Truckload; the faster expansion belongs to Intermodal Services as shippers seek rail alternatives for long-haul legs.
Vehicle Type:
Equipment specialization tracks cargo security requirements and temperature sensitivity across Slovakia's automotive and food processing corridors.
- Flatbed Trucks:Open-deck configurations handle oversized automotive tooling and machinery with crane-loading capability. Steel and aluminum coil shipments from Kosice mills demand side-kit and tarping systems for weather protection.
- Refrigerated Trucks:Temperature-controlled units serve dairy processors in central Slovakia and pharmaceutical distribution from Bratislava cold storage facilities. EU Good Distribution Practice compliance drives fleet renewal toward multi-zone refrigeration and real-time temperature logging.
- Tanker Trucks:Liquid bulk capacity moves fuels, chemicals, and food-grade oils between Bratislava refineries and regional distribution points.
- Vans:Light commercial vehicles dominate last-mile parcel delivery and urgent spare parts distribution within urban zones subject to emission access restrictions.
Flatbed placements anchor industrial corridor volumes; refrigerated capacity is gaining share fastest from pharmaceutical logistics expansion.
End User:
Customer type segmentation reveals concentration risk around automotive manufacturing clusters and emerging diversification into e-commerce fulfillment.
- Manufacturers:Tier-1 and Tier-2 automotive suppliers generate the highest contract values through just-in-time delivery requirements and vendor-managed inventory arrangements.
- E-commerce Companies:Cross-border parcel flows from Polish and Czech distribution centers drive demand for flexible van and small truck capacity.
- Retailers:Grocery and consumer goods chains require scheduled replenishment with refrigerated and dry van combinations.
- Wholesalers:Industrial distribution intermediaries aggregate fragmented demand for construction materials and agricultural inputs.
Manufacturer contracts dominate current revenue; e-commerce channels are expanding most quickly from Central European fulfillment network growth.
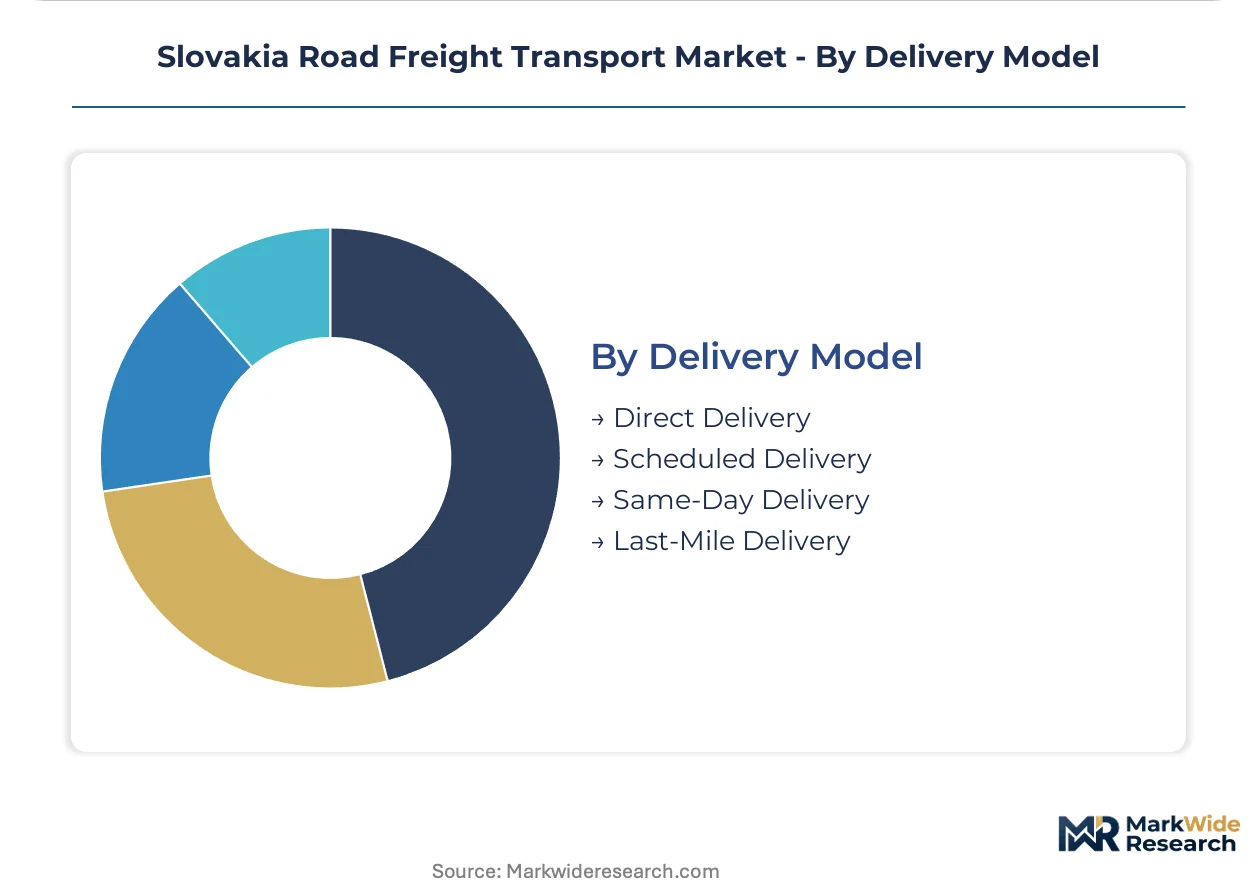
Delivery Model:
Speed tiers stratify pricing and asset utilization as shippers trade cost against production line downtime risk.
- Scheduled Delivery:Fixed-time window arrivals support lean manufacturing operations with predictable labor and dock scheduling. This model captures the majority of automotive inbound volume.
- Direct Delivery:Point-to-point haulage bypasses terminal handling for high-value or time-critical shipments requiring chain-of-custody documentation.
- Same-Day Delivery:Emergency response capacity commands premium rates for production line stoppage prevention and medical supply urgency.
- Last-Mile Delivery:Urban zone access restrictions and residential delivery complexity drive specialization in small vehicle fleets and locker network integration.
Scheduled Delivery holds the largest volume base; Last-Mile Delivery is climbing the fastest from e-commerce penetration and urban logistics restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bratislava-Zilina industrial corridor anchors Slovakia's road freight concentration, with special economic zone incentives drawing automotive logistics investment toward western border regions.
Bratislava Region
Volkswagen's assembly plant and inbound supplier parks generate dedicated contract lanes requiring sealed dry van capacity. The EU Mobility Package's cabotage restrictions force carriers to restructure driver posting for triangular routes into Austria and Czechia. METRANS terminal infrastructure at Bratislava harbor enables rail-road intermodal combinations for containerized automotive exports.
Zilina Region
Kia Motors' manufacturing complex and its supplier ecosystem demand just-in-time delivery windows with penalty clauses for delays. National transport authorities enforce tachograph compliance through digital monitoring systems at corridor checkpoints. The city's logistics parks concentrate refrigerated capacity for pharmaceutical distribution to central European markets.
Trnava Region
Stellantis operations and tier-1 component plants anchor full truckload demand on fixed routes. Slovakia's environmental ministry advances CO2 emission standards for commercial vehicle access to urban zones. Regional terminals sort less-than-truckload freight for line-haul injection into Bratislava hub operations.
Nitra Region
Jaguar Land Rover's assembly plant and battery supplier co-location generate specialized temperature-controlled and high-security trailer requirements. EU Green Deal transport targets accelerate fleet renewal toward low-emission heavy-duty vehicles. Industrial parks near the city attract consolidation network investments from integrated logistics providers.
Kosice Region
Underpenetrated manufacturing zones present greenfield contract opportunities as automotive suppliers diversify beyond western corridors. The country's national environmental regulator monitors commercial vehicle emissions for urban zone access permits. Steel and aluminum coil shipments from regional mills demand flatbed capacity with weather protection systems.
Slovakia Road Freight Transport Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers capturing automotive assembly plant contracts while domestic carriers anchor regional capacity. The market structure concentrates around pan-European networks and specialized domestic operators serving corridor demand. Three archetypes dominate: integrated logistics providers with multimodal coordination, regional specialists with hub-and-spoke density, and asset-heavy domestic fleets with fixed-route contracts. Competitive moves center on fleet electrification capex deployment and strategic partnerships for intermodal terminal access.
Among integrated logistics providers, DSV A/S and Kuehne+Nagel exemplify the pan-European network archetype, leveraging cross-border density to capture just-in-time automotive contracts. Budamar Logistics anchors the domestic specialist tier through Bratislava hub operations and regional fleet positioning. METRANS occupies the intermodal infrastructure position, enabling rail-road combinations through terminal control at Dunajska Streda and Bratislava.
| Leading Market Players |
|---|
| DSV A/S |
| DHL Group |
| Kuehne+Nagel |
| Dachser |
| CEVA Logistics |
| Raben Group |
| GARTNER KG |
| Budamar Logistics |
| METRANS |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive suppliers concentrated along the Bratislava-Zilina corridor command contract-based long-term offtake pricing with penalty clauses for delivery failures. Their procurement power compresses carrier margins while EU Mobility Package compliance costs force fleet operators to absorb regulatory overhead without proportional rate recovery.
Pricing Analysis
Short lead-time premiums dominate contract structures for just-in-time automotive deliveries, with expedited shipping rates scaling nonlinearly against standard scheduled windows. Three-tier pricing structure across premium, standard, and economy levels separates sealed dry van capacity for Volkswagen and Kia assembly plants from consolidation network rates and spot market brokerage. Price differentiation rests on delivery velocity guarantees and EU Good Distribution Practice certification tiers for pharmaceutical cargo. Cost compression in standard freight tiers is intensifying because diesel volatility outpaces fuel surcharge pass-through mechanisms. Mid-size manufacturers lacking volume for dedicated haulage exhibit highest price sensitivity, while battery suppliers establishing Slovak manufacturing presence show lowest sensitivity due to multimodal coordination requirements.
Supply Chain Analysis
EU Good Distribution Practice certification and ISO 9001 quality management standards gate access to pharmaceutical and automotive component logistics contracts, filtering carrier participation toward compliant fleets. Geographic supply concentration draws from Germany for precision automotive tooling, Czech Republic for cross-border fleet positioning, and Poland for e-commerce fulfillment capacity. Raw material dependencies center on steel and aluminum coil from Kosice mills, battery cell inputs for electric vehicle supply chains, and refined fuels from Bratislava refineries. Single-source vulnerability runs through METRANS terminal control at Dunajska Streda and Bratislava for rail-road intermodal combinations. Distribution runs through hub-and-spoke networks anchored at Bratislava logistics parks with regional terminal sorting at Nitra and Trnava.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovakia's road freight market operates as a vertical-integration race where control over intermodal terminal access and electric fleet charging infrastructure determines long-term contract capture. Players are pursuing upstream integration into METRANS rail partnerships and downstream integration into last-mile urban logistics networks.
For Market Incumbents: Deepen captive supply of electric heavy-duty tractor units through Bratislava-Zilina corridor charging infrastructure partnerships before EU Alternative Fuels Infrastructure Regulation mandates tighten. Consolidate position by acquiring regional LTL terminal networks in Nitra and Trnava to block new entrant density accumulation. The EU Mobility Package's cabotage restrictions threaten cross-border margin pools; respond by concentrating capacity on dedicated contract lanes with Volkswagen, Kia, and Jaguar Land Rover rather than spot market exposure. For New Entrants and Emerging Players: Telematics-integrated route optimization platforms offer a technology-first wedge into mid-tier automotive supplier contracts currently served by fragmented domestic fleets. White-space targets include refrigerated pharmaceutical logistics for Bratislava cold storage distribution and underpenetrated manufacturing zones near Kosice as automotive suppliers diversify beyond western corridors. The most penetrable segment is temperature-controlled biologics transport, where EU Good Distribution Practice compliance requirements filter incumbent participation. Go-to-market angle: outcome-based pricing tied to real-time temperature logging and predictive arrival systems. For Investors and Strategic Acquirers: The window for entry favors domestic specialists with fixed-route contracts and METRANS terminal access rights over asset-heavy pure-play road operators. Long-term viability over a multi-year horizon hinges on fleet electrification capex deployment timelines aligned with EU Green Deal transport targets. Acquisition target archetype: regional carriers with Bratislava hub operations and existing just-in-time automotive relationships. Signal to watch: Slovakia's environmental ministry acceleration of CO2 emission standards for commercial vehicle urban zone access, which will strand non-compliant legacy fleets and force distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Renewal | EU Green Deal compliance secures urban zone access permits from Slovakia's environmental ministry. |
| METRANS Terminal Partnership | Rail-road intermodal control at Dunajska Streda locks in automotive export corridor capacity. |
| Pharmaceutical Cold Chain Certification | EU Good Distribution Practice accreditation opens biologics distribution from Bratislava facilities. |
| Predictive Arrival System Deployment | Telematics integration compresses dwell times at Kia Zilina and Volkswagen Bratislava gates. |
| Eastern Slovakia Geographic Expansion | Kosice manufacturing zone positioning captures automotive supplier diversification beyond western corridor. |
Research Methodology
Independent corroboration across fleet operations directors, automotive procurement managers, and intermodal terminal operators underwrites the qualitative findings presented in this analysis. Primary interviews with logistics providers, regulatory compliance officers at Slovakia's transport authority, and pharmaceutical distribution executives combined with secondary validation. Secondary sources include EU Mobility Package regulatory filings, METRANS throughput disclosures, Slovakia's environmental ministry emission standard proposals, and automotive production databases tracking Volkswagen, Kia, and Jaguar Land Rover facility outputs. Bottom-up carrier capacity assessments and top-down corridor demand modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates baseline automotive production volumes from electric vehicle supply chain reconfiguration effects and EU regulatory compliance cost pass-through. Segmentation dimensions modeled include service type, vehicle specialization, end-user vertical, and delivery velocity tier. CAGRs were derived from corridor-specific demand projections and fleet utilization benchmarks. Industry-specific forecast inputs incorporate EU Alternative Fuels Infrastructure Regulation charging network rollout timelines and METRANS terminal capacity expansion plans at Bratislava and Dunajska Streda.
Several conditions sit outside the modeled scope, including unannounced EU Mobility Package enforcement variations, abrupt diesel price shocks exceeding historical volatility bands, and automotive OEM production reallocation decisions beyond Slovakia. Forecasts reflect assumptions regarding regulatory implementation pacing and infrastructure investment continuity. A model refresh is warranted upon material change in EU Green Deal transport target acceleration or Slovakia's environmental ministry urban emission access permit criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market