
 Latin America Cross Border Road Freight Market | 2026-2036
Latin America Cross Border Road Freight Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cross Border Road Freight Market Foresight
Cross-border freight corridors between Mercosur and Pacific Alliance members is tilting toward consolidated logistics networks. DHL Supply Chain leverages its bonded warehouse infrastructure to anchor north-south lanes across the Andes. Kuehne Nagel sustains temperature-controlled pharmaceutical flows through specialized reefer fleets. Ceva Logistics competes on automotive just-in-time delivery contracts linking São Paulo industrial parks to Buenos Aires assembly plants.
Latin America cross border road freight encompasses commercial cargo movement across sovereign borders by heavy-duty vehicles subject to bilateral weight limits, customs seals, and cabotage restrictions. Reefer trucks maintain cold chain integrity for perishables spanning tropical climates with ambient temperature differentials exceeding twenty degrees Celsius. Full truck load services dominate volume on high-frequency Brazil-Argentina routes where manufacturing supply chains demand dedicated capacity. Less than truck load segments capture margin from fragmented agricultural and e-commerce shippers lacking scale for direct contracting. Telematics adoption tracks vehicle location, fuel consumption, and driver hours across mountainous terrain where cellular coverage gaps persist.
Brazil's ANTT regulates interstate freight rates and driver rest mandates while Argentina's CNRT enforces axle-load controls at Andean border crossings. Mexico's SCT coordinates with Guatemala's Ministerio de Comunicaciones on harmonized overweight permits for the Tapachula-Ciudad Hidalgo commercial gateway. Stakeholders must weigh fleet electrification timelines against diesel subsidy phase-outs and bi-national carbon border adjustment proposals before committing capital to corridor-specific depot networks.
Market Dynamics
Regional trade corridor deepening is compressing transit times across the Andean spine while GPS-based fleet telematics is migrating from optional fleet management tools to mandatory customs compliance infrastructure. Brazil's ANTT rate regulations and Argentina's CNRT axle-load enforcement are forcing carriers to reconfigure trailer configurations at border crossings.
Growth Catalysts
- Mercosur-EU Agreement:The trade framework is expanding certificate-of-origin documentation requirements, pulling specialized customs brokerage services into core logistics offerings.
- Reefer Fleet Modernization:Temperature-controlled pharmaceutical flows are demanding real-time cold chain monitoring across tropical corridors with ambient differentials exceeding twenty degrees Celsius.
- Brazil-Argentina Manufacturing Integration:Automotive just-in-time contracts are dedicating capacity on São Paulo-Buenos Aires lanes, locking in high-frequency full truck load services.
Market Restraints
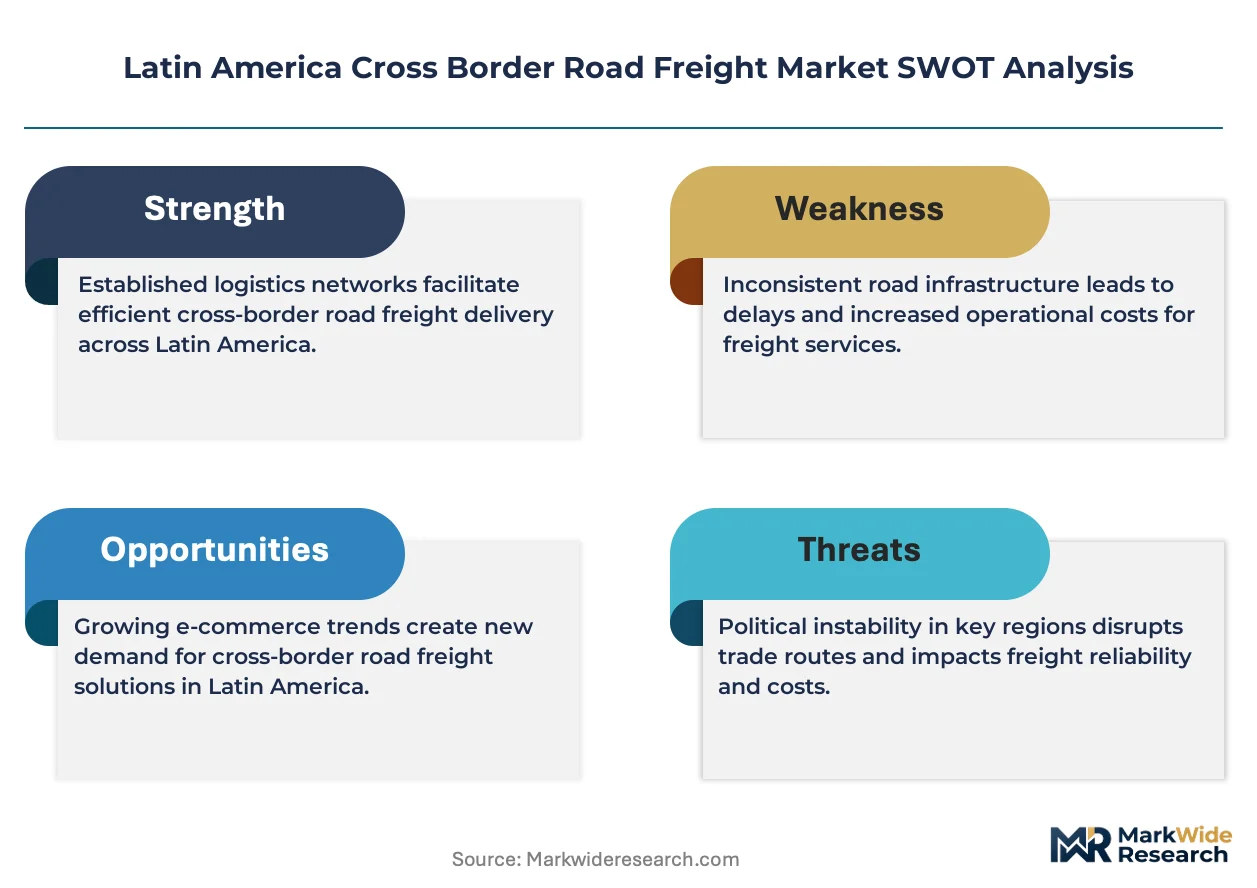
- Diesel Subsidy Phase-Outs:Brazil's fuel price liberalization is compressing margins on long-haul routes where fuel represents the dominant cost input.
- Cellular Coverage Gaps:Mountainous terrain across the Andean spine is fragmenting telematics continuity, forcing redundant satellite backup systems.
- Cabotage Restrictions:Bilateral weight limit mismatches between Paraguay and Argentina are creating deadheading inefficiencies at Ciudad del Este-Posadas crossings.
Strategic Opportunities
- Guatemala's Pacific Corridor:The Tapachula-Ciudad Hidalgo gateway is underpenetrated for consolidated agricultural exports seeking direct Mexico City access.
- Bi-National Carbon Border Adjustments:Proposed Mercosur emissions frameworks are creating first-mover advantage for fleet electrification pilot programs.
- E-Commerce Fragmentation:Less than truck load aggregators are capturing margin from small-scale agricultural shippers lacking direct contracting scale.
Industry Challenges
- Driver Rest Mandate Coordination:Brazil's ANTT hour limits and Argentina's CNRT enforcement protocols are misaligned, forcing dual-logbook compliance at tri-border clusters.
- Harmonized Overweight Permit Delays:Mexico's SCT and Guatemala's Ministerio de Comunicaciones are operating on incompatible processing timelines, stretching depot network planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cross Border Road Freight Market |
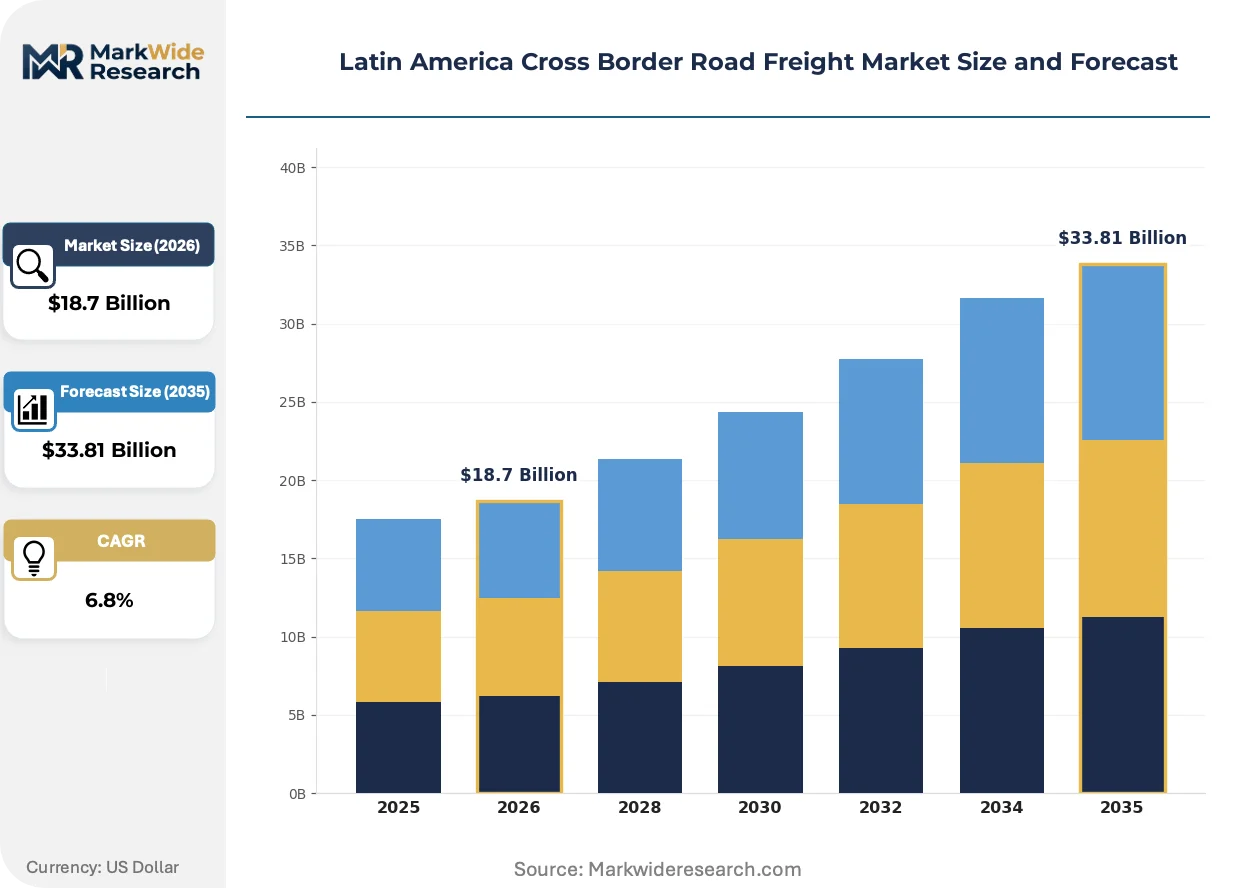
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Cross Docking, Warehousing Vehicle Type: Reefer Truck, Flatbed Truck, Box Truck, Cargo Van End User: Retail, E-commerce, Manufacturing, Agriculture Technology: Telematics, Routing Software, Freight Exchange, Mobile Tracking |
| Companies Covered | Atlasmex, DB Schenker, DHL Supply Chain, Rhenus Logistics, DSV, Ceva Logistics, XPO Logistics, OOCL Logistics, Kuehne Nagel, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cross Border Road Freight Market Shifts & Advancements
Telematics infrastructure is migrating from fleet optimization to customs pre-clearance systems, while regional regulators are hardening emissions and rest-mandate enforcement. Agricultural exporters are consolidating previously fragmented shipments into temperature-controlled consolidated networks.
GPS-based fleet telematics is migrating from basic location tracking to integrated customs seal verification systems. Large agricultural exporters in Brazil's Mato Grosso corridor are adopting these platforms to pre-clear loads before reaching Paraguayan border checkpoints. The technology is migrating from standalone hardware to embedded OEM dashboard systems, compressing aftermarket vendor margins while embedding compliance deeper into vehicle procurement decisions.
Brazil's ANTT is tightening interstate freight rate transparency mandates while coordinating with Argentina's CNRT on harmonized driver rest enforcement. The regulatory convergence is forcing carriers to standardize electronic logbook formats across Mercosur borders. Temperature-controlled pharmaceutical flows are most affected, as these segments face dual jurisdiction inspections that delay reefer units at Puerto Iguazú-Foz do Iguaçu crossings.
Shippers are consolidating fragmented agricultural loads through third-party logistics aggregators rather than contracting directly with carriers. Small-scale soybean and coffee exporters in Paraguay's Alto Paraná region are abandoning spot-market negotiations for annual volume commitments with bonded warehouse operators. The behavioral shift is most visible in the Brazil-Argentina-Paraguay tri-border cluster, where e-commerce fulfillment is pulling refrigerated last-mile capacity away from traditional produce distribution channels.
Latin America Cross Border Road Freight Market Segmentation
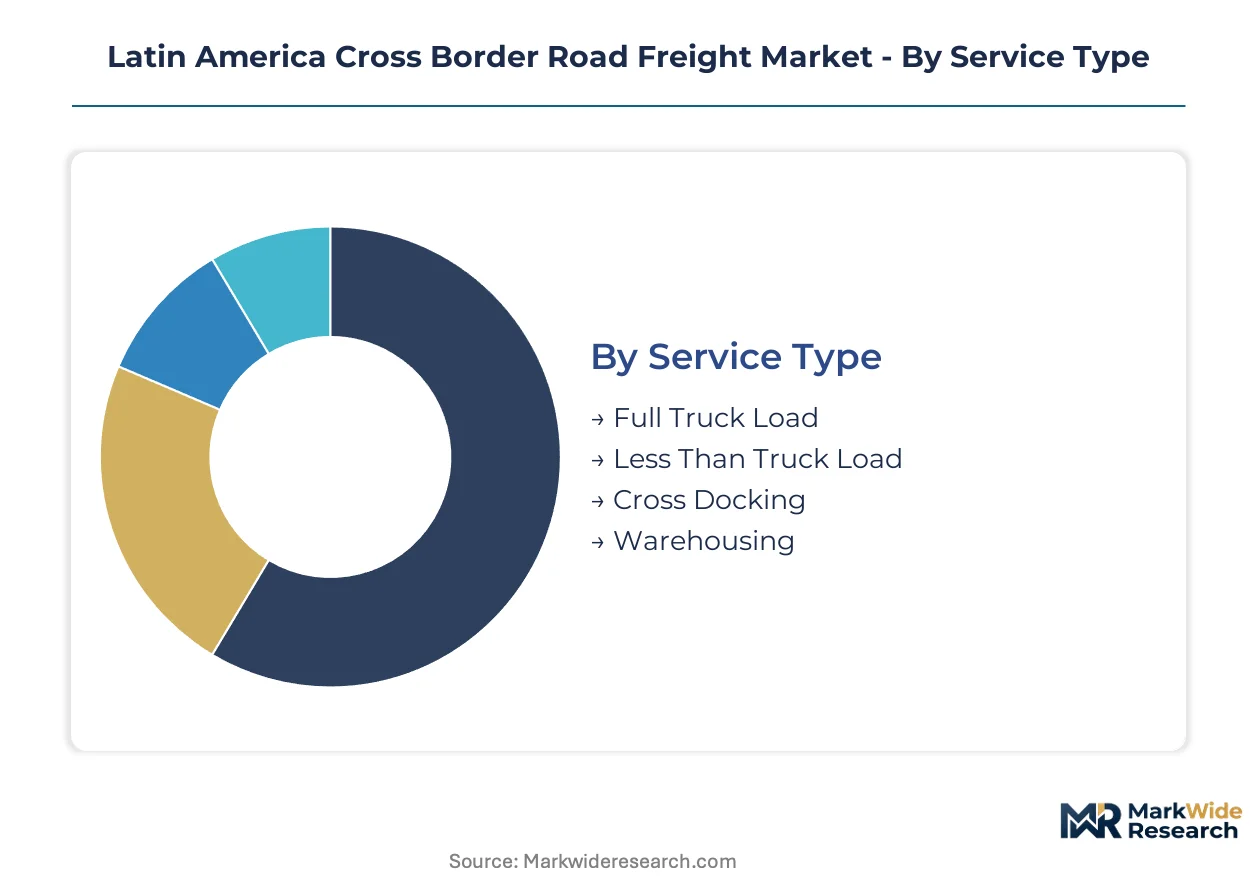
Cross-border road freight in Latin America fragments across service models, vehicle specifications, and technology adoption curves that reflect divergent cargo densities and corridor maturity. Understanding these splits reveals where margin pools concentrate and which infrastructure investments align with actual demand patterns.
Service Type:
Mature contract structures dominate high-volume corridors, while emerging aggregation models capture fragmented agricultural and e-commerce flows.
- Full Truck Load:Dedicated capacity contracts link São Paulo industrial parks to Buenos Aires assembly plants under automotive just-in-time protocols. Brazil-Argentina manufacturing integration locks in high-frequency lane commitments with minimal idle repositioning.
- Less Than Truck Load:Consolidation platforms aggregate small-scale soybean and coffee shipments from Paraguay's Alto Paraná region into bonded warehouse networks. E-commerce fulfillment is pulling refrigerated last-mile capacity away from traditional produce channels.
- Cross Docking:Transshipment facilities at Ciudad del Este-Posadas crossings mitigate cabotage restriction inefficiencies through rapid cargo transfer between national fleets.
- Warehousing:Bonded storage infrastructure anchors north-south logistics networks across Andean corridors, enabling duty-deferred consolidation.
Full Truck Load handles the majority of throughput; Less Than Truck Load is expanding most quickly on share.
Vehicle Type:
Cost tier differentiation separates temperature-controlled pharmaceutical investments from commodity dry freight assets.
- Reefer Truck:Temperature-controlled units maintain cold chain integrity across tropical corridors where ambient differentials exceed twenty degrees Celsius. Real-time monitoring systems are becoming mandatory for pharmaceutical flows through Puerto Iguazú-Foz do Iguaçu crossings.
- Flatbed Truck:Open-deck configurations serve construction materials and machinery moving through Brazil-Argentina-Paraguay tri-border clusters. Axle-load enforcement at Andean borders forces frequent trailer reconfiguration.
- Box Truck:Enclosed dry van capacity dominates consumer goods distribution on the Mexico-Guatemala Tapachula-Ciudad Hidalgo corridor.
- Cargo Van:Light commercial vehicles execute last-mile e-commerce delivery from cross-border consolidation hubs to urban fulfillment centers.
Reefer Truck commands premium pricing; Cargo Van is gaining share fastest as e-commerce penetration deepens.
End User:
Application-driven demand splits between integrated supply chain manufacturers and fragmented agricultural exporters.
- Manufacturing:Automotive and industrial shippers contract dedicated São Paulo-Buenos Aires capacity with electronic seal verification for customs pre-clearance.
- Agriculture:Mato Grosso soybean exporters and Paraguayan coffee growers are abandoning spot markets for annual volume commitments with third-party logistics aggregators.
- Retail:Department store chains operate private fleet networks with GPS-based route optimization across Mercosur borders.
- E-commerce:Digital marketplace sellers drive Less Than Truck Load fragmentation through small-batch, high-frequency replenishment patterns.
Manufacturing anchors contracted revenue; E-commerce is climbing the fastest on volume contribution.
Technology:
Customer type adoption curves separate enterprise fleet telematics from owner-operator mobile solutions.
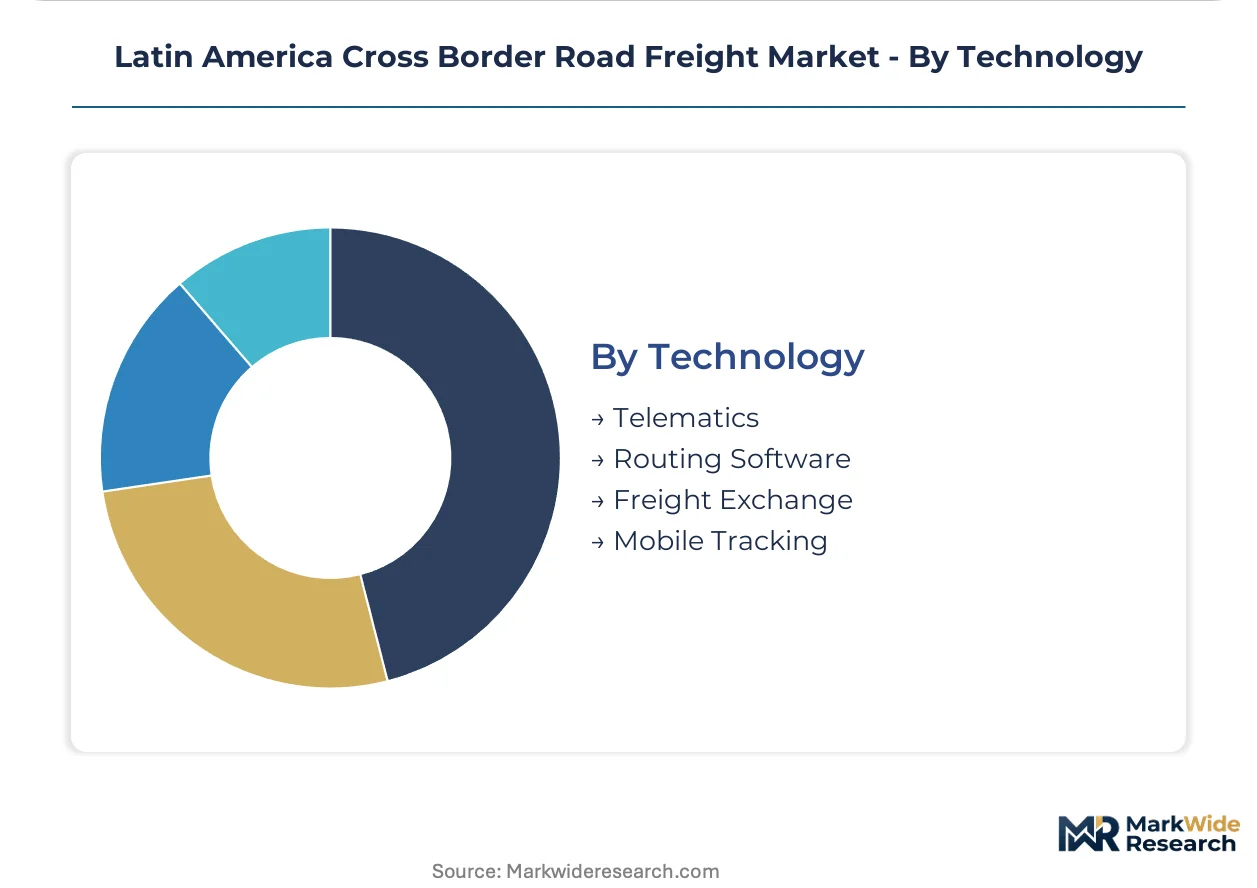
- Telematics:Embedded OEM dashboard systems are displacing aftermarket hardware as large agricultural exporters pre-clear loads before reaching Paraguayan checkpoints. Cellular coverage gaps across mountainous terrain force redundant satellite backup.
- Routing Software:Algorithmic optimization platforms compress transit times across the Andean spine by integrating real-time border delay data.
- Freight Exchange:Digital matching platforms connect small-scale shippers with available capacity on spot-market lanes.
- Mobile Tracking:Smartphone-based visibility tools serve fragmented agricultural exporters lacking capital for dedicated hardware installations.
Telematics captures the dominant technology spend; Freight Exchange is accelerating fastest on adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mercosur-EU agreement is deepening Brazil's integration with Atlantic shipping lanes, while the Mexico-Guatemala Tapachula-Ciudad Hidalgo corridor anchors Pacific freight flows into Central America.
Brazil
São Paulo's automotive industrial parks generate dedicated full truck load demand to Buenos Aires assembly plants. ANTT regulates interstate freight rates and driver rest mandates that carriers must navigate at tri-border crossings. Mato Grosso soybean exporters are consolidating fragmented shipments through bonded warehouse networks near the Paraguayan frontier.
Mexico
The Tapachula-Ciudad Hidalgo gateway channels agricultural exports toward Mexico City distribution hubs. SCT coordinates with Guatemala's Ministerio de Comunicaciones on harmonized overweight permits, though processing timeline mismatches persist. Nuevo León manufacturing clusters are pulling refrigerated capacity northward from underpenetrated Pacific corridors.
Argentina
CNRT enforces axle-load controls at Andean border crossings that force trailer reconfiguration for Brazil-bound freight. Buenos Aires assembly plants lock in high-frequency lane commitments under automotive just-in-time protocols. Puerto Iguazú-Foz do Iguaçu crossings experience dual jurisdiction inspections that delay temperature-controlled pharmaceutical flows.
Paraguay
Alto Paraná coffee growers are abandoning spot markets for annual volume commitments with third-party logistics aggregators. Cabotage restrictions at Ciudad del Este-Posadas crossings create deadheading inefficiencies where Paraguayan and Argentine weight limits diverge. Cross-docking facilities mitigate these friction points through rapid cargo transfer between national fleets.
Chile
The Andean spine compresses transit times for Pacific Alliance trade corridors linking Santiago to Mercosur markets. Mountainous terrain fragments cellular telematics coverage, forcing redundant satellite backup systems for GPS-based fleet tracking. Northern mining districts generate flatbed demand for machinery moving through tri-border clusters.
Latin America Cross Border Road Freight Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on capacity and equipment. The market structures around consolidated logistics networks with bonded warehouse infrastructure anchoring north-south lanes. Three archetypes dominate: pan-regional freight forwarders with customs brokerage integration, temperature-controlled specialists with reefer fleet investments, and automotive-dedicated carriers with just-in-time contract expertise. Competitive moves concentrate on strategic partnerships for corridor-specific depot networks and portfolio diversification into e-commerce less than truck load aggregation.
Among European-based logistics platforms, DHL Supply Chain, DB Schenker, and Kuehne Nagel occupy positions spanning the Mercosur and Pacific Alliance corridors. DHL Supply Chain exemplifies the bonded warehouse-anchored model across Andean routes. DB Schenker represents the integrated customs brokerage archetype emerging from Mercosur-EU documentation requirements. Kuehne Nagel sits within the temperature-controlled specialization tier serving pharmaceutical flows through tropical corridors.
| Leading Market Players |
|---|
| Atlasmex |
| DB Schenker |
| DHL Supply Chain |
| Rhenus Logistics |
| DSV |
| Ceva Logistics |
| XPO Logistics |
| OOCL Logistics |
| Kuehne Nagel |
| Others |
Supply & Pricing Matrix
São Paulo's industrial freight corridor concentrates capacity for automotive just-in-time contracts, translating dedicated lane commitments into premium pricing power for contracted full truck load services. Diesel subsidy phase-outs in Brazil and Argentina are compressing margins on long-haul routes, forcing carriers to pass fuel cost volatility through to spot-market less than truck load segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs cross-border freight contracts. Premium tiers attach to temperature-controlled pharmaceutical flows with real-time cold chain monitoring through Puerto Iguazú-Foz do Iguaçu crossings, while standard tiers cover dry van manufacturing supply chains and economy tiers capture agricultural spot markets. Price differentiation hinges on certification grade for customs pre-clearance telematics and volume scale for annual commitments. Pricing pressure stems from fuel cost liberalization squeezing long-haul operators. Small-scale agricultural shippers in Paraguay's Alto Paraná region exhibit highest price sensitivity, whereas automotive OEMs lock in long-term contracts with limited renegotiation frequency.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina dominates supply chain risk calculations for Mercosur corridor operators. Manufacturing inputs concentrate in São Paulo industrial parks, Buenos Aires assembly zones, and Nuevo León production clusters. Reefer fleet assets, diesel fuel procurement, and GPS telematics hardware constitute critical component dependencies. Single-source vulnerability persists for satellite backup systems covering Andean cellular gaps. Distribution runs through bonded warehouse networks anchoring north-south lanes across the Andean spine.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America cross-border road freight sits in early-cycle expansion as GPS-based fleet telematics migrates from optional optimization to mandatory customs compliance infrastructure. Regional trade corridor deepening accelerates adoption curves for integrated logistics platforms.
For Market Incumbents: Harden defensive positions by securing exclusive bonded warehouse capacity at Ciudad del Este-Posadas crossings before harmonized overweight permit protocols finalize. Deepen backward integration into reefer fleet maintenance networks to offset margin compression from diesel subsidy phase-outs. Incumbent carriers face substitution threat from digital freight exchanges aggregating fragmented agricultural volumes. For New Entrants and Emerging Players: Pursue underpenetrated Pacific corridor opportunities between Guatemala's Tapachula gateway and Mexico City distribution hubs, where consolidated agricultural exports lack direct contracting scale. Target less than truck load aggregation for small-scale coffee growers abandoning spot markets. A go-to-market angle anchored in mobile tracking solutions bypasses capital barriers of embedded OEM telematics. For Investors and Strategic Acquirers: Carve-out targets emerge from European logistics conglomerates seeking to divest non-core Latin American road freight assets amid portfolio rebalancing toward Asia-Pacific growth corridors. Long-term viability favors temperature-controlled specialists with reefer fleet investments and customs brokerage integration capabilities. Monitor bi-national carbon border adjustment proposals as inflection signal for fleet electrification capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | DHL Supply Chain anchors north-south lanes across Andean corridors with duty-deferred consolidation infrastructure. |
| Reefer Fleet Modernization | Kuehne Nagel sustains pharmaceutical cold chain integrity across tropical corridors exceeding twenty-degree ambient differentials. |
| Telematics Platform Integration | Embedded OEM dashboard systems displace aftermarket hardware as agricultural exporters pre-clear Paraguayan border loads. |
| Cross-Docking Facility Development | Rapid cargo transfer at tri-border clusters mitigates cabotage restriction inefficiencies between national fleets. |
| E-Commerce LTL Aggregation | Digital marketplaces pull refrigerated last-mile capacity from traditional produce channels into fragmented fulfillment networks. |
Research Methodology
Desk research of customs trade databases, national transport regulator filings, and bonded warehouse operator disclosures preceded structured interviews with fleet operations directors, customs brokerage managers, agricultural exporter logistics leads, and third-party logistics procurement officers. Primary fieldwork across São Paulo, Buenos Aires, and Mexico City freight corridors combined with secondary validation from ANTT rate filings, CNRT enforcement protocols, and SCT permit processing records. Bottom-up volume modeling triangulated against top-down corridor capacity assessments.
Assumptions held regulatory convergence timelines and fuel subsidy phase-out schedules within announced policy frameworks while varying trade corridor throughput scenarios across the projection horizon. Segmentation dimensions modeled include service type, vehicle specification, end-use industry, and technology adoption tier alongside corridor-specific maturity indices. CAGRs derived from historical lane volume trends and capacity expansion pipelines, with forecast inputs incorporating telematics penetration curves and reefer fleet replacement cycles.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification moves by European logistics platforms or accelerated bi-national carbon border adjustments would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Cross-Border Road Transport Market