
 Argentina Road Freight Transport Market | 2026-2036
Argentina Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Road Freight Transport Market Insights
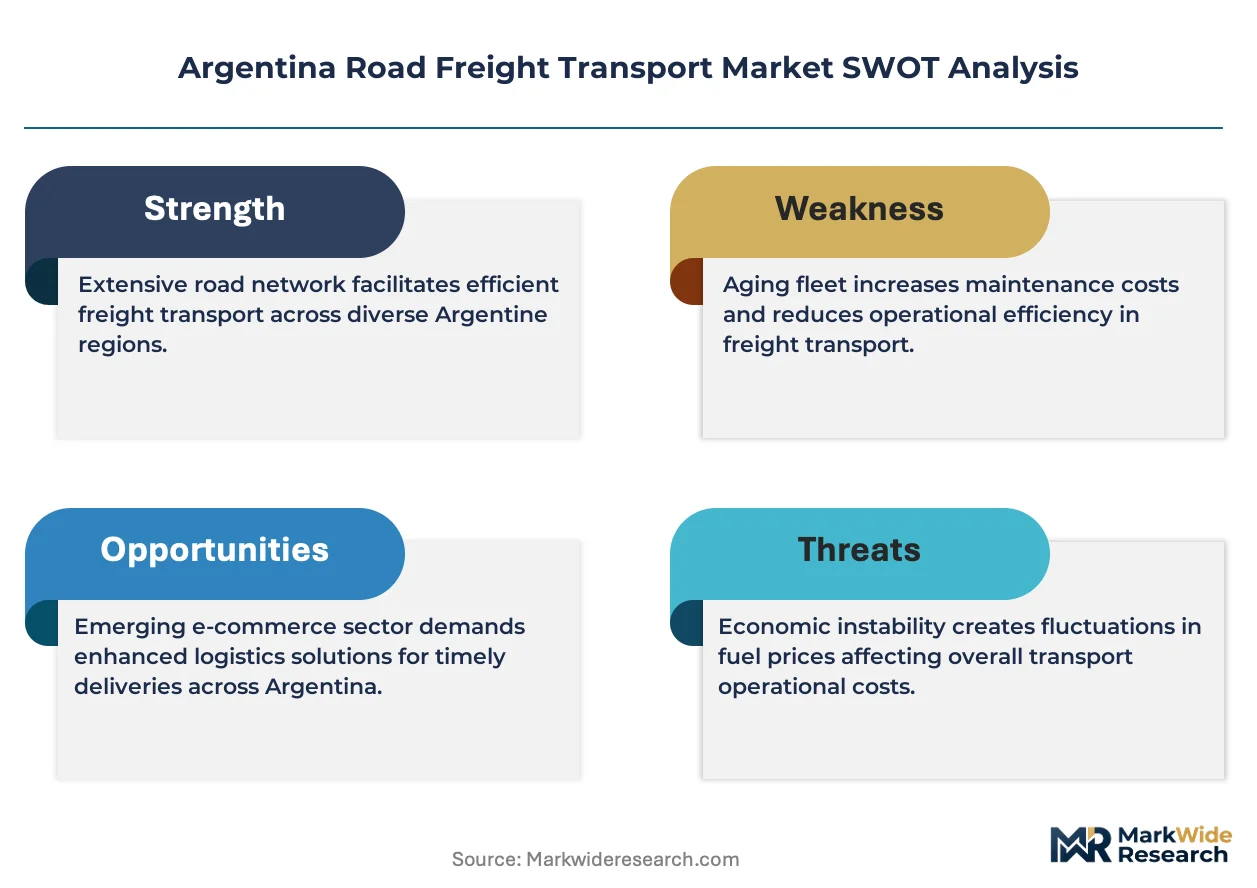
Asset-light leasing models are reshaping competitive dynamics in Argentina's road freight sector. Andreani Logistica S.A. leverages its nationwide depot network to sustain temperature-controlled capacity across pharmaceutical corridors. TASA Logistica anchors grain-export logistics through dedicated fleet contracts with Pampas agricultural cooperatives. OCASA competes on last-mile density in Greater Buenos Aires, where urban delivery slots command premium rates.
Road freight transport encompasses the movement of goods via motorized vehicles over paved highway infrastructure, utilizing trucks with gross vehicle weights ranging from light-duty vans to heavy tractor-trailers exceeding 45 tonnes, primarily serving supply chain continuity for time-sensitive and bulk cargo flows. Full truckload services dominate margin pools on long-haul agricultural corridors, while less than truckload segments fragment across provincial distributors with limited load consolidation technology. Third-party logistics channels capture growing share as manufacturers outsource fleet ownership to offset currency volatility exposure.
Argentina's National Transport Law and CNRT enforcement protocols govern axle-weight limits, driver hour restrictions, and vehicle inspection standards that directly shape fleet replacement cycles and insurance costs. Provincial transit authorities in Santa Fe and Buenos Aires impose supplementary municipal routing rules that constrain heavy vehicle access to urban cores during peak periods. Stakeholders must monitor pending revisions to fuel subsidy structures and cross-border Mercosur harmonization protocols that could reconfigure competitive cost positions overnight.
Market Dynamics
CNRT axle-weight enforcement protocols are compressing fleet replacement cycles across Argentina's agricultural corridors. Pampas grain exporters now face immediate equipment upgrades to maintain operating licenses.
Growth Catalysts
- Soybean export logistics:Pampas agricultural cooperatives are expanding dedicated fleet contracts to secure capacity for harvest-season surges. This demand pull tightens spot market availability during peak months.
- National Transport Law compliance:Mandatory vehicle inspection standards are accelerating retirement of overweight tractor-trailers. Fleet operators must modernize to avoid cargo detention at provincial checkpoints.
- Pharmaceutical cold chain:Buenos Aires-Rosario temperature-controlled corridors attract specialized investment from distributors serving ANMAT-regulated product flows.
Market Restraints
- Diesel price volatility:Fuel subsidy uncertainty exposes operators to margin compression without hedging instruments. Smaller fleet owners lack working capital to absorb sudden pump price adjustments.
- Axle-weight concentration:Enforcement authority rests with provincial transit departments in Santa Fe and Buenos Aires, creating fragmented compliance costs across operating territories.
- Rail freight substitution:Ferrocarril Belgrano Cargas rehabilitation threatens long-haul grain volumes on Rosario-Bahía Blanca routes where trucking currently dominates.
Strategic Opportunities
- Mendoza wine corridor:Unpenetrated refrigerated capacity exists for export-quality vineyard clusters seeking direct port access without Buenos Aires transshipment.
- Cross-border Mercosur harmonization:Pending driver hour and weight standard alignment would simplify fleet deployment into Uruguay and southern Brazil.
- Telematics-insurance convergence:Usage-based coverage models using real-time axle monitoring reduce premiums for compliant operators versus traditional actuarial pools.
Industry Challenges
- Certified mechanic scarcity:Refrigeration unit maintenance requires specialized training unavailable in provincial workforce pipelines, extending equipment downtime.
- Legacy fleet integration:Retrofitting older tractors with compliant axle configurations demands capital outlays that smaller operators cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Road Freight Transport Market |
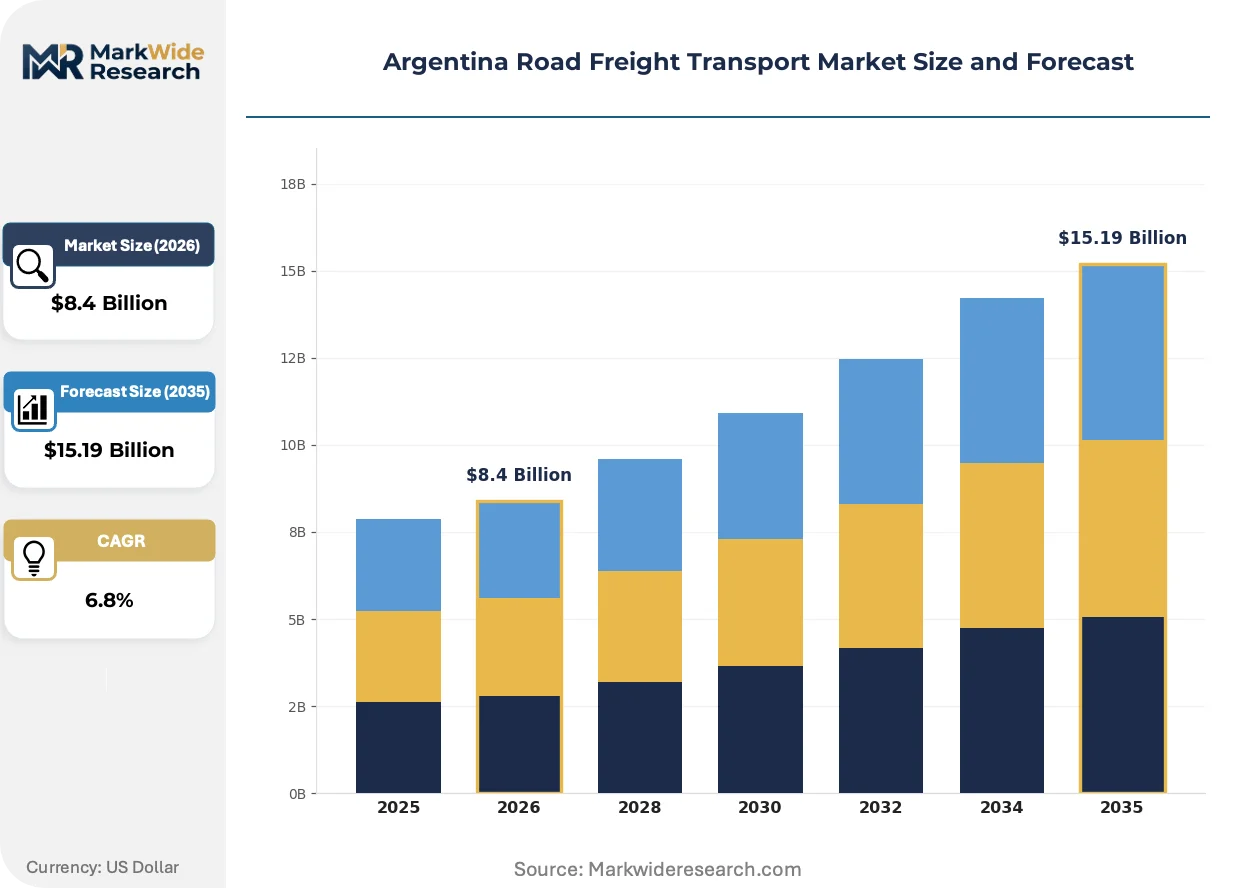
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Expedited Freight, Intermodal Vehicle Type: Truck, Van, Trailer, Specialized Vehicle End User: Retail, Manufacturing, Construction, Agriculture Distribution Channel: Direct, Third-Party Logistics, Freight Brokers, Online Platforms |
| Companies Covered | Andreani Logistica S.A., TASA Logistica, OCASA, Logistica Urbana S.A., Rivas S.A., Transfarmaco S.A., Clover Logistica, DHL Supply Chain Argentina, Organizacion Coordinadora Argentina S.R.L., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Road Freight Transport Market Trends and Innovations
Telematics-enabled compliance monitoring is redrawing competitive boundaries between asset-heavy and asset-light operators. Technology adoption separates carriers capable of real-time CNRT reporting from those dependent on manual inspection preparation.
On-board weighing systems with cellular transmission are rendering obsolete post-harvest detention risk at Santa Fe provincial checkpoints. Pampas grain haulers adopting this technology secure preferential loading slots from agricultural cooperatives. Real-time axle monitoring compresses insurance premium spreads between compliant and non-compliant fleet segments.
Argentina's National Transport Law revision debates center on unified driver hour limits across provincial jurisdictions. Current fragmentation forces operators to maintain separate logbook protocols for Buenos Aires versus Santa Fe transits. Pharmaceutical distributors lobby for harmonized temperature documentation standards to reduce border delay exposure on Mercosur routes.
Consolidated procurement through agricultural cooperatives displaces fragmented spot-market contracting for harvest-season capacity. Large Pampas exporters now mandate multi-year fleet commitments with penalty clauses for non-performance. This concentration shifts pricing power toward cooperative buyers and squeezes independent owner-operators into marginal corridor segments.
Argentina Road Freight Transport Market Segmentation
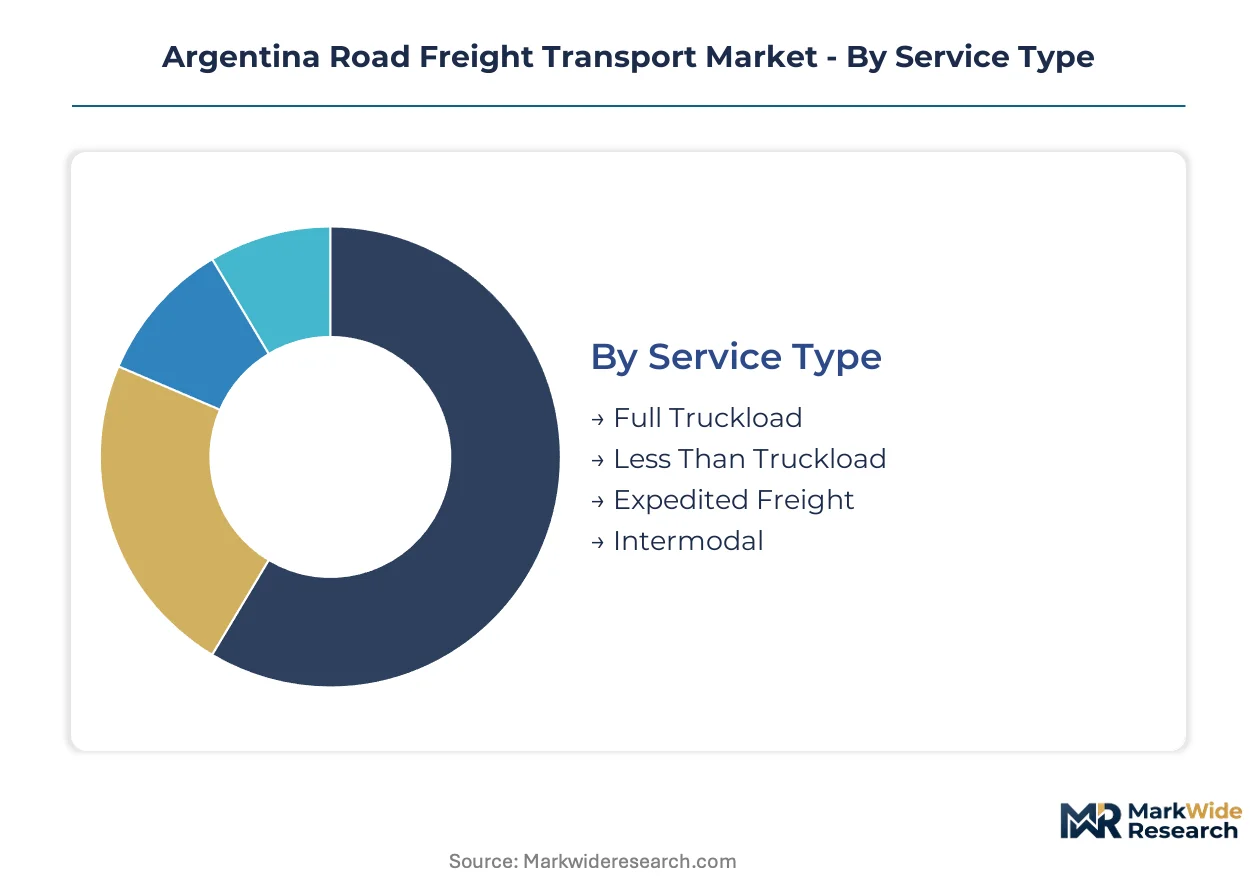
Segmentation in Argentina's road freight market reveals how service configuration, equipment specialization, and channel structure determine pricing power and customer retention. Each dimension carries distinct after-sales intensity profiles that shape operator investment priorities and partnership durability.
Service Type:
After-sales service intensity varies sharply across service configurations, with temperature-controlled and time-definite offerings demanding continuous equipment monitoring and rapid-response maintenance networks.
- Full Truckload:Dedicated tractor-trailer capacity moves single-shipper cargo from Pampas grain elevators to Rosario port terminals. Agricultural cooperatives in Santa Fe province now mandate multi-year fleet commitments with penalty clauses for harvest-season non-performance, compressing spot market availability during peak months.
- Less Than Truckload:Consolidated shipments from multiple shippers share trailer space on scheduled routes. Provincial distributors across Buenos Aires and Córdoba struggle with limited load consolidation technology, fragmenting margin pools and extending transit times for mid-size manufacturers.
- Expedited Freight:Time-critical deliveries with guaranteed transit windows for pharmaceutical and automotive components. ANMAT-regulated cold chain products between Buenos Aires and Rosario command premium rates for temperature-validated service.
- Intermodal:Coordinated truck-rail movements leveraging Ferrocarril Belgrano Cargas rehabilitation on select grain corridors. Threatens pure trucking volumes on Rosario-Bahía Blanca routes where rail infrastructure investment accelerates.
By volume, Full Truckload leads. By growth pace, Expedited Freight is ahead.
Vehicle Type:
Equipment specialization directly determines compliance burden under CNRT axle-weight enforcement, with heavier configurations facing accelerated replacement cycles.
- Truck:Rigid chassis vehicles with integrated cargo beds dominate urban distribution and short-haul agricultural collection. Santa Fe provincial checkpoints detain overweight units lacking on-board weighing systems, forcing fleet modernization.
- Van:Light-duty vehicles under 3.5 tonnes gross vehicle weight serve last-mile pharmaceutical and e-commerce delivery in Greater Buenos Aires. Urban delivery slots command premium rates during restricted access windows.
- Trailer:Detachable semi-trailers enable tractor flexibility across grain, container, and refrigerated applications. Pampas cooperatives prefer dedicated trailer pools with standardized axle configurations to minimize loading delays.
- Specialized Vehicle:Refrigerated units and tank configurations for temperature-sensitive and liquid bulk cargo. Certified mechanic scarcity for refrigeration maintenance extends equipment downtime in provincial corridors.
By fleet count, Trucks dominate. By investment intensity, Specialized Vehicles are climbing fastest.
End User:
Customer sector concentration shapes route density and equipment utilization, with agricultural and retail demand exhibiting opposing seasonal patterns.
- Retail:Consumer goods distribution to hypermarket and supermarket networks requires multi-temperature trailers and predictable delivery windows. Buenos Aires metropolitan concentration enables route optimization software deployment.
- Manufacturing:Industrial component and finished goods movement linking Córdoba automotive plants with port export facilities. Just-in-time production schedules demand expedited service reliability with penalty structures for delay.
- Construction:Heavy equipment and building materials transport with project-based demand spikes. Irregular volume patterns complicate fleet planning for dedicated contract operators.
- Agriculture:Soybean and grain export logistics from Pampas production zones to Rosario and Bahía Blanca ports. Harvest-season surge capacity requirements drive cooperative procurement consolidation and long-term fleet contracting.
Agriculture generates the highest peak-season volume. Retail shows the steadiest year-round demand profile.
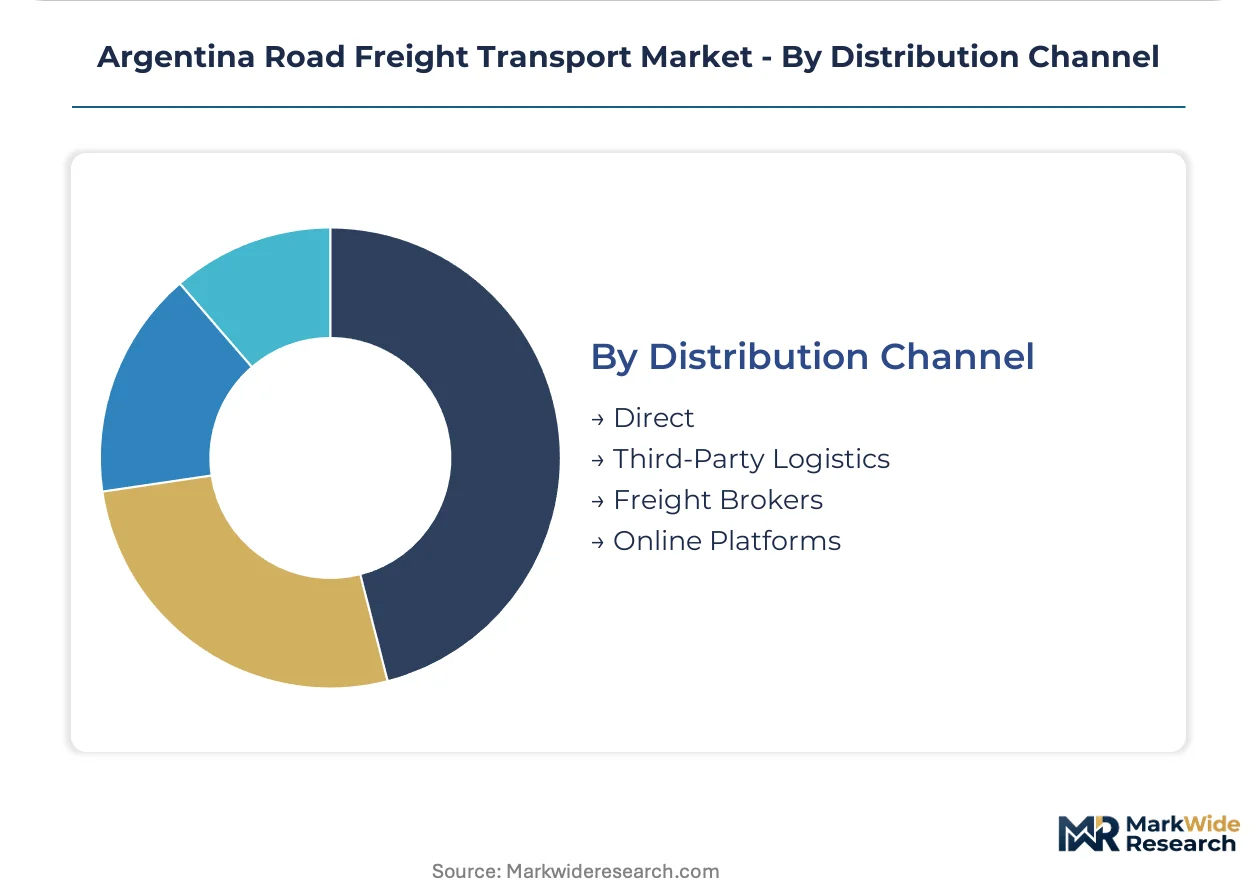
Distribution Channel:
Channel structure determines working capital requirements and customer relationship depth, with asset-light intermediaries gaining share as manufacturers outsource fleet ownership.
- Direct:Shipper-operated private fleets maintaining captive capacity for core lanes. Currency volatility exposure drives divestment toward third-party alternatives among multinational manufacturers.
- Third-Party Logistics:Integrated providers offering warehousing, transportation, and inventory management. Andreani Logistica leverages nationwide depot networks to sustain temperature-controlled pharmaceutical corridor coverage.
- Freight Brokers:Non-asset intermediaries matching spot market capacity with immediate shipper demand. Digital platforms fragment pricing transparency and compress margins for small fleet operators.
- Online Platforms:Digital freight matching services connecting shippers with available carrier capacity. Emerging channel with limited penetration outside Buenos Aires metropolitan freight corridors.
Third-Party Logistics captures the largest revenue share. Online Platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's export-import balance tilts heavily toward agricultural commodities, with road freight capacity concentrated on Pampas-to-port corridors serving soybean and grain shipments. Provincial enforcement fragmentation across Santa Fe and Buenos Aires creates divergent compliance costs that reshape fleet deployment patterns.
Buenos Aires Province
Pharmaceutical cold chain demand concentrates in the Greater Buenos Aires metropolitan zone, where ANMAT-regulated temperature documentation standards govern distribution. The provincial transit authority imposes municipal routing rules restricting heavy vehicle access during peak periods. Rosario-Buenos Aires refrigerated corridors attract specialized investment from distributors seeking validated service.
Santa Fe Province
Pampas grain elevators drive harvest-season surge capacity requirements through dedicated fleet contracts with agricultural cooperatives. CNRT axle-weight enforcement protocols compress fleet replacement cycles as provincial checkpoints detain non-compliant units. The Rosario port terminal cluster anchors soybean export logistics with multi-year procurement commitments.
Córdoba Province
Automotive component manufacturing links Córdoba industrial plants with port export facilities through just-in-time production schedules. The National Transport Law governs driver hour restrictions across provincial jurisdictions with fragmented logbook protocols. The Córdoba metropolitan corridor enables route optimization software deployment for manufacturing supply chains.
Mendoza Province
Wine export corridors seek direct port access without Buenos Aires transshipment, creating unpenetrated refrigerated capacity opportunities. Provincial transit departments enforce supplementary vehicle inspection standards beyond federal CNRT protocols. The Mendoza vineyard cluster represents export-quality production seeking specialized logistics partnerships.
Argentina Road Freight Transport Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in equipment and maintenance segments. The vendor base clusters around three operational models: asset-heavy fleet owners with captive capacity, asset-light intermediaries leveraging depot networks, and digital platforms matching spot demand. Strategic archetypes include agricultural corridor specialists, pharmaceutical cold chain operators, and urban last-mile density players. Competitive moves concentrate on multi-year fleet contracting with penalty structures and telematics-enabled compliance differentiation.
Among Argentina-based logistics providers, Andreani Logistica S.A., TASA Logistica, and OCASA occupy distinct positioning within this structure. Andreani represents the nationwide depot network archetype sustaining temperature-controlled pharmaceutical coverage. TASA exemplifies agricultural corridor specialization through Pampas cooperative relationships. OCASA anchors urban last-mile density in Greater Buenos Aires where restricted delivery windows command premium positioning. These three providers illustrate how service configuration and geographic focus determine competitive boundaries in a market shaped by CNRT enforcement and provincial regulatory fragmentation.
| Leading Market Players |
|---|
| Andreani Logistica S.A. |
| TASA Logistica |
| OCASA |
| Logistica Urbana S.A. |
| Rivas S.A. |
| Transfarmaco S.A. |
| Clover Logistica |
| DHL Supply Chain Argentina |
| Organizacion Coordinadora Argentina S.R.L. |
| Others |
Pricing and Supply Chain Analysis
Diesel subsidy volatility in Argentina determines both pricing tier spreads and supply chain shape, compressing margins for unhedged operators while forcing fleet modernization investments that reshape procurement patterns across Pampas agricultural corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on temperature-validation certification and volume scale commitments. Pharmaceutical distributors serving ANMAT-regulated corridors command premium positioning for validated cold chain service, while spot-market grain haulers face acute price sensitivity due to harvest-season capacity surges. Cost compression in the standard tier is intensifying because provincial fuel tax adjustments expose mid-size fleet operators to margin erosion without hedging instruments.
Supply Chain Analysis
Tractor and trailer manufacturing feeds from concentrated supply bases in Brazil, China, and the United States, with refrigeration unit components drawing from specialized production clusters in Germany and Japan. Steel sheet, axle assemblies, and telematics hardware represent critical input dependencies, while CNRT compliance certification creates regulatory chokepoints that extend equipment lead times. Distribution runs through authorized dealer networks in Buenos Aires and Rosario, with aftermarket parts flowing via cooperative procurement channels to Pampas fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's road freight market offers substantial service-attach opportunity, with telematics-enabled compliance monitoring and usage-based insurance layers expanding faster than pure equipment leasing revenue.
For Market Incumbents: Pre-empt rail freight substitution on Rosario-Bahía Blanca grain corridors by securing multi-year cooperative contracts with penalty structures for non-performance. Invest in backward integration into refrigeration maintenance capabilities to address certified mechanic scarcity that extends equipment downtime for competitors. Anchor fleet replacement cycles to CNRT enforcement protocol timelines.
For New Entrants and Emerging Players: Mendoza wine corridor refrigerated capacity represents the most penetrable entry point, with export-quality vineyard clusters seeking direct port access without Buenos Aires transshipment. Cross-border Mercosur harmonization preparation offers a second white-space target for fleet operators positioning for simplified driver hour and weight standard alignment. Pursue asset-light leasing models with telematics bundling as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors agricultural corridor specialists with captive cooperative relationships and pharmaceutical cold chain operators with ANMAT-validated infrastructure. Long-term viability hinges on regulatory compliance technology integration rather than pure scale. Monitor pending fuel subsidy structure revisions as the primary inflection indicator for margin compression exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Insurance Convergence | Real-time axle monitoring reduces premiums for CNRT-compliant operators versus traditional actuarial pools. |
| Multi-Year Fleet Contracting | Agricultural cooperatives in Santa Fe province now mandate penalty clauses for harvest-season non-performance. |
| Refrigeration Maintenance Capability Buildout | Certified mechanic scarcity in provincial corridors extends equipment downtime for unprepared competitors. |
| Cross-Border Mercosur Harmonization Preparation | Pending driver hour and weight standard alignment would simplify fleet deployment into Uruguay and Brazil. |
| Asset-Light Leasing Model Expansion | Currency volatility exposure drives manufacturers toward third-party alternatives and outsourced fleet ownership. |
Research Methodology
Operator-level perspectives from fleet managers, agricultural cooperative procurement directors, pharmaceutical distribution executives, CNRT enforcement officers, and insurance underwriters anchored the qualitative base for this study. Secondary validation drew from CNRT regulatory filings, Santa Fe and Buenos Aires provincial transit authority records, agricultural export statistics, and commercial vehicle registration databases. Bottom-up capacity modeling across service type, vehicle configuration, and end-use segments triangulated with top-down macroeconomic overlay analysis.
Scenario-bracketing around diesel price volatility, subsidy regime changes, and rail freight rehabilitation timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include service configuration, equipment specialization, end-use sector concentration, and distribution channel structure. CAGRs were derived from volume-flow projections tied to soybean export cycles, pharmaceutical cold chain expansion, and fleet replacement cycle acceleration under tightened axle-weight enforcement.
Macroeconomic conditions sit as an overlay; deviation in peso exchange rate stability, diesel subsidy continuity, or Mercosur harmonization progress would shift the trajectory. Forecasts reflect documented assumptions about CNRT enforcement intensity and cooperative procurement consolidation patterns. Cross-checking against agricultural export volume benchmarks and commercial vehicle sales data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
United Kingdom Road Freight Transport Market