
 Chile Road Freight Transport Market | 2026-2036
Chile Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Road Freight Transport Market Outlook
Truck driver availability is redrawing operational capacity across Chile's northern freight corridors. Transportes Nazar leverages its long-haul specialization to sustain volume commitments through the Atacama Desert routes. Andes Logistics de Chile S.A. anchors its network around port connectivity at Valparaíso and San Antonio. Sotraser competes through refrigerated fleet depth serving agricultural export timelines.
Chile road freight transport encompasses the movement of goods via highway networks using motorized commercial vehicles rated above 3.5 tonnes gross vehicle weight, operating across paved and unpaved corridors spanning over 85,000 kilometers of national roads. The system functions as the dominant inland logistics mode, handling approximately three-quarters of domestic cargo tonnage while connecting mining zones, agricultural valleys, and Pacific port terminals. Trucks dominate vehicle type deployment due to payload flexibility across mountainous topography and variable road conditions. Full Truck Load services capture the largest service type share by revenue, driven by mining bulk shipments and agricultural export consolidation, while Reefer Services registers the fastest structural expansion as fruit and seafood cold-chain requirements tighten. Finished Goods cargo type generates premium rate pools tied to just-in-time manufacturing and retail replenishment cycles.
Chile's Ministry of Transport enforces emission standards aligned with Mercosur technical regulations, compelling fleet renewal toward cleaner diesel and alternative fuel platforms. The National Customs Service and Ministry of Public Works coordinate weigh-in-motion enforcement and axle load limits that directly shape trailer specifications and route economics across the Pan-American Highway system. Stakeholders must monitor lithium corridor infrastructure commitments and biofuel blending mandates as these policy vectors will determine competitive fleet composition and corridor prioritization over the coming decade.
Market Dynamics
The Ministry of Transport's Euro VI-equivalent emission mandate is compressing fleet replacement cycles across Chile's carrier base, forcing capital reallocation toward cleaner diesel platforms and alternative fuel trials while reshaping competitive economics on the Pan-American Highway corridors.
Growth Catalysts
- Copper extraction logistics:Antofagasta Region mining operations generate sustained heavy-haul demand for articulated trucks moving concentrate from pit to port.
- Biofuel blending mandates:The Ministry of Energy's renewable diesel requirements are opening procurement channels for domestic agricultural feedstock processors.
- Reefer infrastructure:San Antonio port cold-chain investments enable year-round fruit export consolidation from Central Valley growers.
Market Restraints
- Axle load enforcement:National Customs Service weigh-in-motion systems on Route 5 enforce strict trailer specifications that limit payload optimization.
- Driver supply contraction:Long-haul recruitment pools in Atacama and Tarapacá regions face demographic compression and vocational training gaps.
- Fuel price volatility:Chile's net fuel import position exposes operating margins to peso-dollar exchange rate swings and international diesel benchmarks.
Strategic Opportunities
- Lithium corridor development:Salar de Atacama extraction expansion requires specialized bulk transport for battery-grade chemical shipments to Antofagasta port.
- Digital freight matching:Load board platforms are penetrating the fragmented agricultural carrier segment between Curicó and Valparaíso.
- Electrification pilots:The Ministry of Transport's zero-emission zone trials in Santiago Metropolitan Region create fleet testing grounds for battery-electric distribution trucks.
Industry Challenges
- Telematics integration:Legacy dispatch systems at mid-sized carriers in Biobío Region resist API connectivity with customer ERP platforms.
- Emissions certification timelines:Mercosur-aligned homologation procedures delay new vehicle registrations by four to six months during fleet renewal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Road Freight Transport Market |
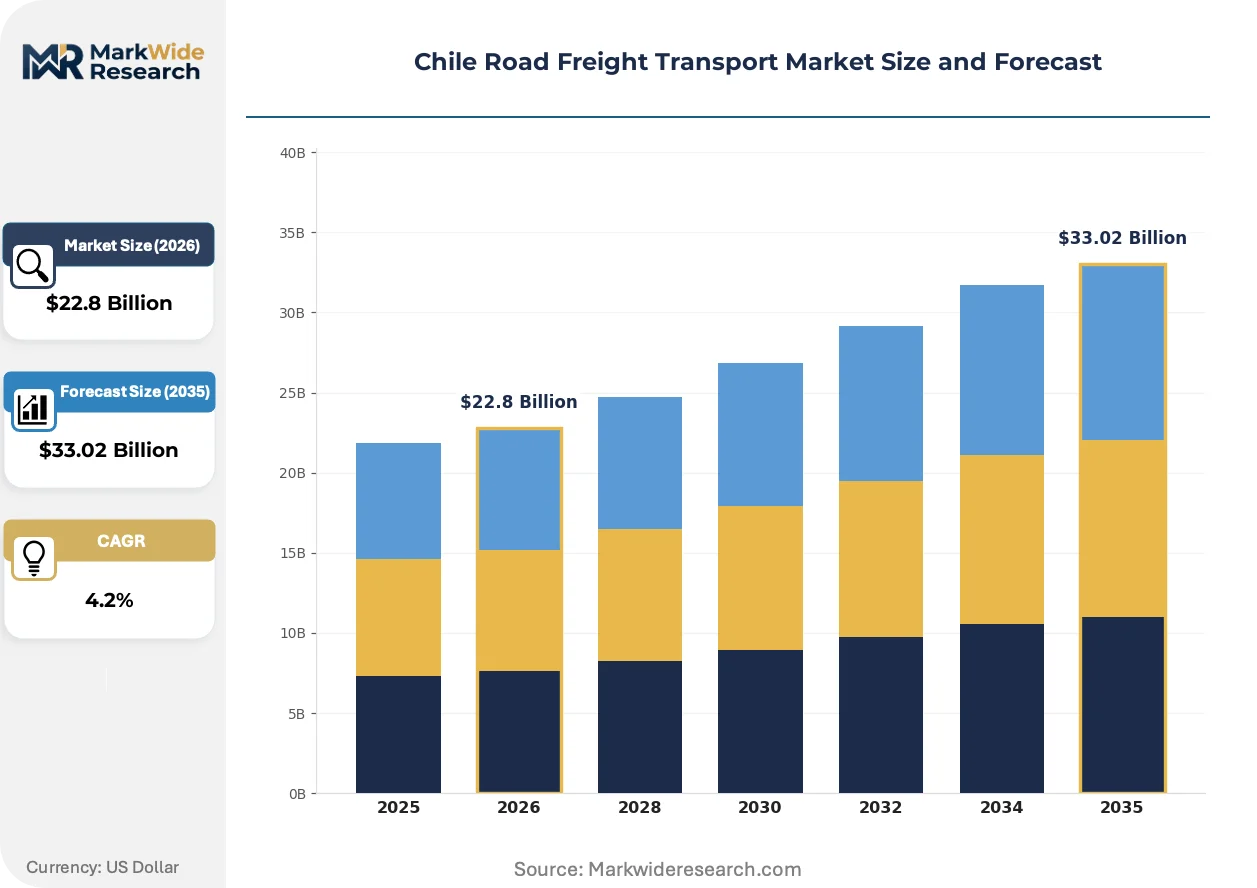
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $33.02 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Trailers, Pickups Cargo Type: Fruits, Vegetables, Raw Materials, Finished Goods Service Type: Full Truck Load, Less Than Truck Load, Reefer Services, Express Shipping End User: Agriculture Sector, Manufacturing Industry, Retail Sector, Logistics Providers |
| Companies Covered | Transportes Nazar, Transportes Santa Maria, Andes Logistics de Chile S.A., MR Transport, Tur-Bus Cargo, Agunsa (Agencias Universales S.A.), Sotraser, Jorquera Transporte SA, Transportes Casablanca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Road Freight Transport Market Strategic Shifts
Telematics and alternative powertrains are redrawing operational capabilities across Chile's freight corridors. Fleet managers face simultaneous pressure to cut emissions, optimize asset utilization, and maintain service reliability across extreme topography.
Autonomous convoying technology is fragmenting long-haul economics on the Route 5 desert stretches. Mining consortia in Antofagasta are piloting platooning systems for concentrate trucks operating on closed corridor segments. This automation is compressing driver headcount requirements while extending permissible daily operating hours.
Chile's Ministry of Transport aligns commercial vehicle standards with Mercosur technical regulations, compelling engine recalibration and after-treatment system upgrades. The Euro VI-equivalent mandate affects all new registrations above 3.5 tonnes gross vehicle weight. Heavy-haul carriers serving copper mines are absorbing compliance costs through extended financing terms.
Shippers in the agricultural export sector are consolidating procurement around carriers with real-time temperature monitoring capabilities. Reefer service contracts now specify minute-by-minute cold-chain data access rather than periodic manual logs. This specification shift is most pronounced among cherry and blueberry exporters operating through San Antonio terminal.
Chile Road Freight Transport Market Segmentation
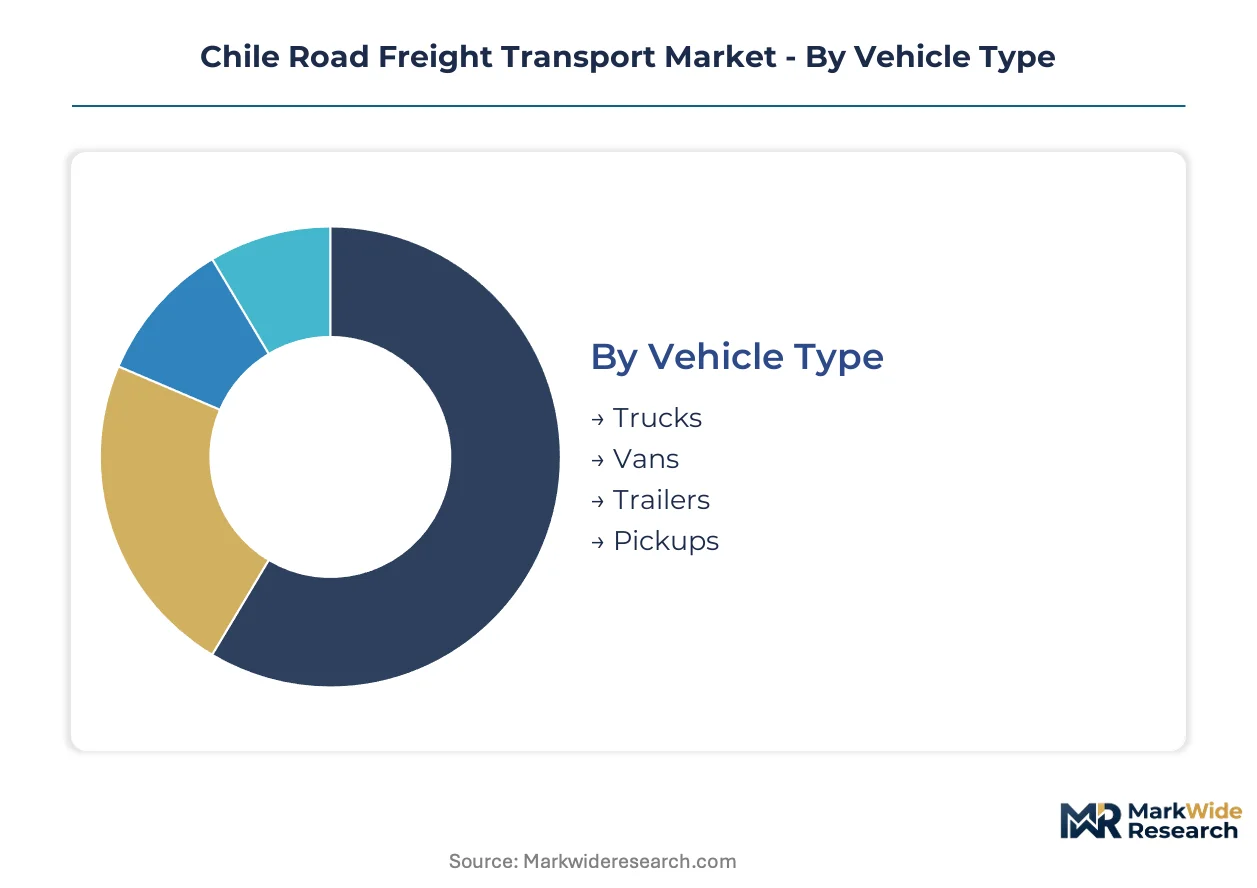
Segmentation in Chile's road freight market reveals how specialized equipment and service configurations align with distinct cargo economics. Mining bulk, agricultural cold-chain, and retail replenishment each demand dedicated fleet architectures that reshape carrier investment priorities across the Pan-American Highway corridors.
Vehicle Type:
Margin pools concentrate in heavy-haul configurations serving mining corridors, where payload optimization and desert durability command premium rate structures.
- Trucks:Articulated heavy-haul units dominate copper concentrate movements from Antofagasta pit operations to port terminals. The Ministry of Transport's Euro VI-equivalent mandate is compressing replacement cycles for this installed base. Trucks hold installed capacity. Trailers is rotating up the share rankings.
- Trailers:Specialized flatbed and tanker configurations handle lithium chemical shipments from Salar de Atacama extraction zones. Axle load enforcement on Route 5 weigh-in-motion systems limits trailer specification flexibility.
- Vans:Light commercial units serve last-mile distribution in Santiago Metropolitan Region urban cores. Express e-commerce timelines drive fleet sizing in this segment.
- Pickups:Utility vehicles support agricultural field operations and remote mining site logistics across Atacama Desert access roads.
Heavy-haul trucks anchor mining corridor economics. Trailer specialization is climbing fastest as lithium extraction scales.
Cargo Type:
Application intensity varies sharply across Chile's export-oriented cargo mix, with temperature-sensitive agricultural products commanding specialized fleet deployment.
- Fruits:Cherry, blueberry, and table grape exports from Central Valley growers require continuous cold-chain integrity through San Antonio port. Reefer monitoring specifications now demand minute-by-minute data access rather than manual logs. Fruits hold installed capacity. Finished Goods is rotating up the share rankings.
- Finished Goods:Manufacturing output from Biobío Region industrial parks moves on just-in-time schedules to retail distribution centers. Telematics integration pressures persist among mid-sized carriers serving this segment.
- Vegetables:Asparagus and leafy green shipments from Curicó consolidation points face compressed harvest-to-export windows.
- Raw Materials:Copper concentrate and lithium carbonate bulk movements generate the heaviest axle loads across northern corridor infrastructure.
Fruit exports drive reefer fleet specialization. Finished goods logistics is expanding most quickly as manufacturing timelines tighten.
Service Type:
Customer type differentiation separates contract-based mining logistics from spot-market agricultural procurement patterns.
- Full Truck Load:Dedicated capacity arrangements dominate mining bulk shipments and agricultural export consolidation. Long-haul desert routes from Antofagasta to port terminals operate on fixed rotation schedules. Full Truck Load holds installed capacity. Reefer Services is rotating up the share rankings.
- Reefer Services:Temperature-controlled capacity serves seafood from Los Lagos Region and fruit from Central Valley with year-round cold-chain requirements. San Antonio port infrastructure investments enable this segment's structural expansion.
- Less Than Truck Load:Consolidated shipments support retail replenishment and manufacturing component flows across intermediate distances.
- Express Shipping:Time-definite services concentrate in Santiago Metropolitan Region e-commerce fulfillment and pharmaceutical distribution.
Full truck load contracts anchor carrier revenue stability. Reefer services is gaining share fastest as export quality standards tighten.
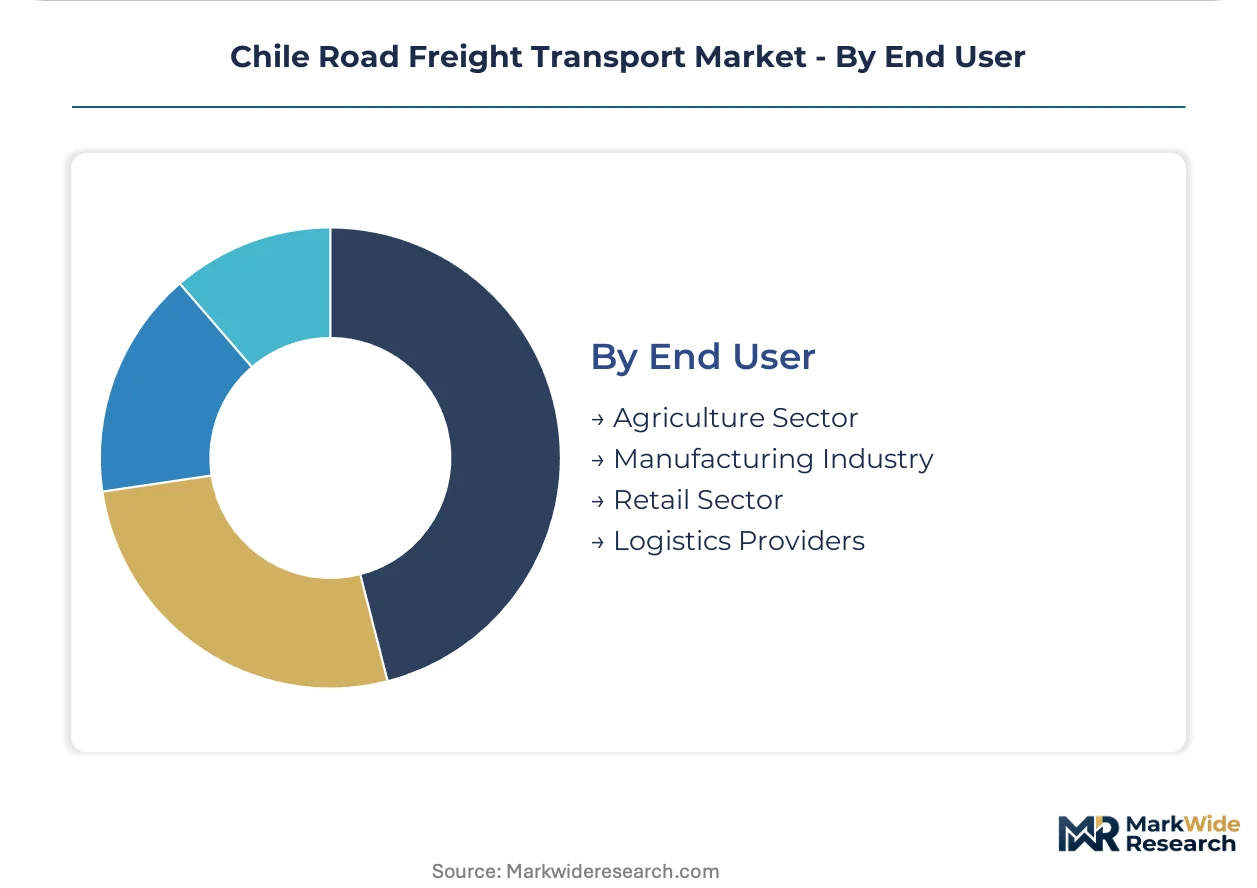
End User:
Supply concentration aligns with Chile's primary export sectors, where mining and agriculture generate disproportionate freight demand relative to GDP composition.
- Agriculture Sector:Central Valley fruit and vegetable exporters procure refrigerated capacity on seasonal contracts tied to harvest calendars. Cherry export peaks in November-December compress available reefer supply. Agriculture Sector holds installed capacity. Logistics Providers is rotating up the share rankings.
- Logistics Providers:Third-party operators aggregate fragmented agricultural carrier capacity between Curicó and Valparaíso. Digital freight matching platforms are penetrating this intermediary layer.
- Manufacturing Industry:Biobío Region automotive and food processing plants require inbound component and outbound finished goods coordination.
- Retail Sector:Santiago Metropolitan Region distribution centers replenish supermarket and e-commerce inventories on daily cycles.
Agricultural exporters command seasonal capacity allocation. Logistics providers is climbing the fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antofagasta Region commands rate premiums that exceed Santiago Metropolitan Region benchmarks by double-digit margins, reflecting the extreme operating conditions of Atacama Desert corridors and the non-negotiable reliability requirements of copper concentrate logistics.
Antofagasta Region
Copper concentrate movements from Escondida and Chuquicamata pit operations to Mejillones and Antofagasta port terminals generate the heaviest axle loads in national road freight. The Ministry of Transport enforces Euro VI-equivalent emission standards on all new heavy-haul registrations. Specialized carriers cluster around Calama and Antofagasta city to capture dedicated mining contracts.
Tarapacá Region
Lithium carbonate and lithium hydroxide shipments from Salar de Atacama extraction zones to Iquique and Patache ports are accelerating trailer demand for corrosive chemical transport. The National Customs Service operates weigh-in-motion enforcement on Route A-16 connecting extraction ponds to processing plants. Iquique Free Trade Zone infrastructure supports chemical export consolidation.
Valparaíso Region
Fruit export cold-chain logistics through San Antonio and Valparaíso ports drives reefer fleet specialization among carriers serving Central Valley growers. The Ministry of Public Works coordinates port access road upgrades to reduce harvest-to-vessel transit times. Curicó and San Fernando consolidation points anchor seasonal capacity procurement.
Biobío Region
Manufacturing component flows and finished goods distribution from Concepción-Talcahuano industrial parks operate on just-in-time schedules to retail distribution centers. The Ministry of Transport's telematics integration mandates are pressuring mid-sized carriers to upgrade legacy dispatch systems. Coronel and San Pedro de la Paz logistics parks concentrate warehousing capacity.
Santiago Metropolitan Region
Last-mile e-commerce fulfillment and pharmaceutical distribution dominate urban freight economics within the capital's ring road network. The Ministry of Transport's zero-emission zone trials in downtown Santiago are creating testing grounds for battery-electric distribution trucks. Pudahuel and Quilicura distribution centers handle cross-docking for national retail replenishment.
Chile Road Freight Transport Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Chile's road freight market. The carrier base fragments across three operational tiers: mining-specialized heavy-haul operators, agricultural reefer service providers, and diversified logistics platforms. Dominant competitive moves include fleet modernization to meet Euro VI-equivalent emission mandates and strategic partnerships with mining consortia for dedicated corridor access.
Among Chilean carriers with established mining corridor presence, Transportes Nazar, Andes Logistics de Chile S.A., and Sotraser represent distinct strategic archetypes. Transportes Nazar exemplifies long-haul desert specialization through sustained volume commitments across Atacama routes. Andes Logistics de Chile S.A. occupies a position anchored around port connectivity infrastructure at Valparaíso and San Antonio terminals. Sotraser sits within the refrigerated service tier, exemplifying fleet depth aligned with agricultural export cold-chain requirements.
| Leading Market Players |
|---|
| Transportes Nazar |
| Transportes Santa Maria |
| Andes Logistics de Chile S.A. |
| MR Transport |
| Tur-Bus Cargo |
| Agunsa (Agencias Universales S.A.) |
| Sotraser |
| Jorquera Transporte SA |
| Transportes Casablanca |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day lead times for Euro VI-equivalent truck chassis from Brazilian assembly plants concentrate pricing power among carriers with advance fleet commitments, while spot-market operators absorb margin compression from currency volatility and extended replacement cycles.
Pricing Analysis
Antofagasta-to-port heavy-haul rates command double-digit premiums over Santiago Metropolitan Region benchmarks due to desert operating conditions and mining contract reliability requirements. Contract-based long-term offtake dominates mining corridors, with price differentiation driven by payload optimization capability and after-hours service availability. Cost compression in the agricultural reefer tier is intensifying because San Antonio port cold-chain infrastructure expansion is attracting new carrier entry. Small-scale fruit exporters in Curicó exhibit highest price sensitivity, while copper concentrate shippers prioritize reliability over rate negotiation.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Central Valley fruit exporters facing compressed harvest-to-vessel windows, while mining consortia maintain strategic stockpiles of concentrate at pit heads to buffer port congestion. Heavy-haul truck chassis supply concentrates in Brazil, Mexico, and the United States. Diesel engine after-treatment systems and lithium battery cells constitute critical component dependencies. Single-source vulnerability runs through Brazilian engine control module suppliers. Distribution runs through authorized dealer networks anchored in Santiago and Antofagasta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because reefer fleet telematics subscriptions and predictive maintenance contracts are expanding faster than base vehicle sales across Chilean carrier bases.
For Market Incumbents: Fortify mining corridor dominance through captive maintenance facilities at Calama and Mejillones, while accelerating Euro VI-equivalent fleet turnover ahead of regulatory deadlines. The Ministry of Transport's emission mandate threatens operators with aged installed base. Backward integration into driver training academies in Atacama and Tarapacá regions addresses demographic compression in long-haul recruitment pools.
For New Entrants and Emerging Players: Euro VI-equivalent certification fast-track through Mercosur mutual recognition agreements enables rapid fleet deployment against incumbent replacement backlogs. Agricultural reefer services between Curicó and San Antonio present the most penetrable white space, given fragmented carrier capacity and rising cherry export quality requirements. Digital freight matching platforms offer the clearest go-to-market angle for aggregating seasonal spot demand.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because carrier fragmentation across Biobío Region mid-sized operators creates roll-up opportunity as telematics mandates force capital investments. Target vertically integrated specialists combining fleet ownership with port terminal concessions. Watch lithium extraction permit approvals as the inflection signal for Salar de Atacama corridor capacity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Program | Euro VI-equivalent compliance secures mining contract eligibility under Ministry of Transport mandates. |
| Reefer Telematics Integration | Real-time cold-chain data access differentiates carriers serving San Antonio fruit exporters. |
| Lithium Corridor Partnership | Dedicated chemical transport contracts with Salar de Atacama processors anchor trailer specialization. |
| Driver Training Academy | Captive vocational pipelines address recruitment gaps across Atacama Desert long-haul routes. |
| Digital Freight Platform | Load board penetration between Curicó and Valparaíso consolidates fragmented agricultural carrier capacity. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations managers, mining logistics procurement leads, agricultural export coordinators, and Ministry of Transport regulatory officials and refined through secondary validation against customs trade data, National Customs Service weigh-in-motion statistics, SEC filings of listed Latin American transport groups, and Ministry of Energy biofuel blending records. Bottom-up carrier capacity modeling and top-down cargo flow estimates were triangulated to converge on market sizing.
Variance decomposition across vehicle type, cargo category, service configuration, and end-user sector shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-ton-mile elasticity assumptions. Forecast inputs incorporated lithium extraction permit timelines, Euro VI-equivalent fleet replacement curves, and San Antonio port cold-chain infrastructure commissioning schedules.
Decision-makers should treat outputs as directional under assumptions of sustained copper concentrate volumes and stable peso-dollar exchange rates; material deviation would warrant model refresh. Revision becomes warranted when biofuel blending mandate enforcement crosses thresholds that alter fleet operating cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Europe Customs Brokerage Market