
 Malaysia Domestic CEP Market | 2026-2036
Malaysia Domestic CEP Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Domestic CEP Market Insights
Last-mile hub networks in Selangor and Johor is tilting toward automated sortation and micro-fulfillment nodes. Pos Malaysia leverages its nationwide post office infrastructure to sustain rural coverage density that private rivals cannot replicate. GD Express anchors premium express lanes between industrial zones in Penang and Port Klang. J&T Express competes aggressively on price in the high-volume e-commerce corridor while Ninja Van differentiates through data-driven route optimization.
Malaysia Domestic CEP encompasses courier, express, and parcel services involving time-definite collection, line-haul transport, and delivery of documents and packages weighing typically under 30 kilograms, utilizing barcode scanning, GPS tracking, and electronic proof-of-delivery systems to ensure chain-of-custody visibility. Same-day delivery commands premium pricing but requires dense urban depot placement, while standard delivery still occupies the largest volume share across East and West Malaysia. Express delivery leads margin generation for cross-border connected manufacturers in electronics and medical devices. E-commerce platforms represent the fastest-growing end user category as marketplace sellers abandon self-fulfillment.
MCMC enforces service quality standards under the Communications and Multimedia Act, while the Road Transport Department regulates commercial vehicle licensing and driver certification for last-mile fleets. BIS-equivalent courier packaging standards and occupational safety requirements under DOSH shape operational compliance costs for all licensed operators. Stakeholders must weigh fleet electrification timelines against charging infrastructure gaps in secondary cities before committing capital to depot expansion.
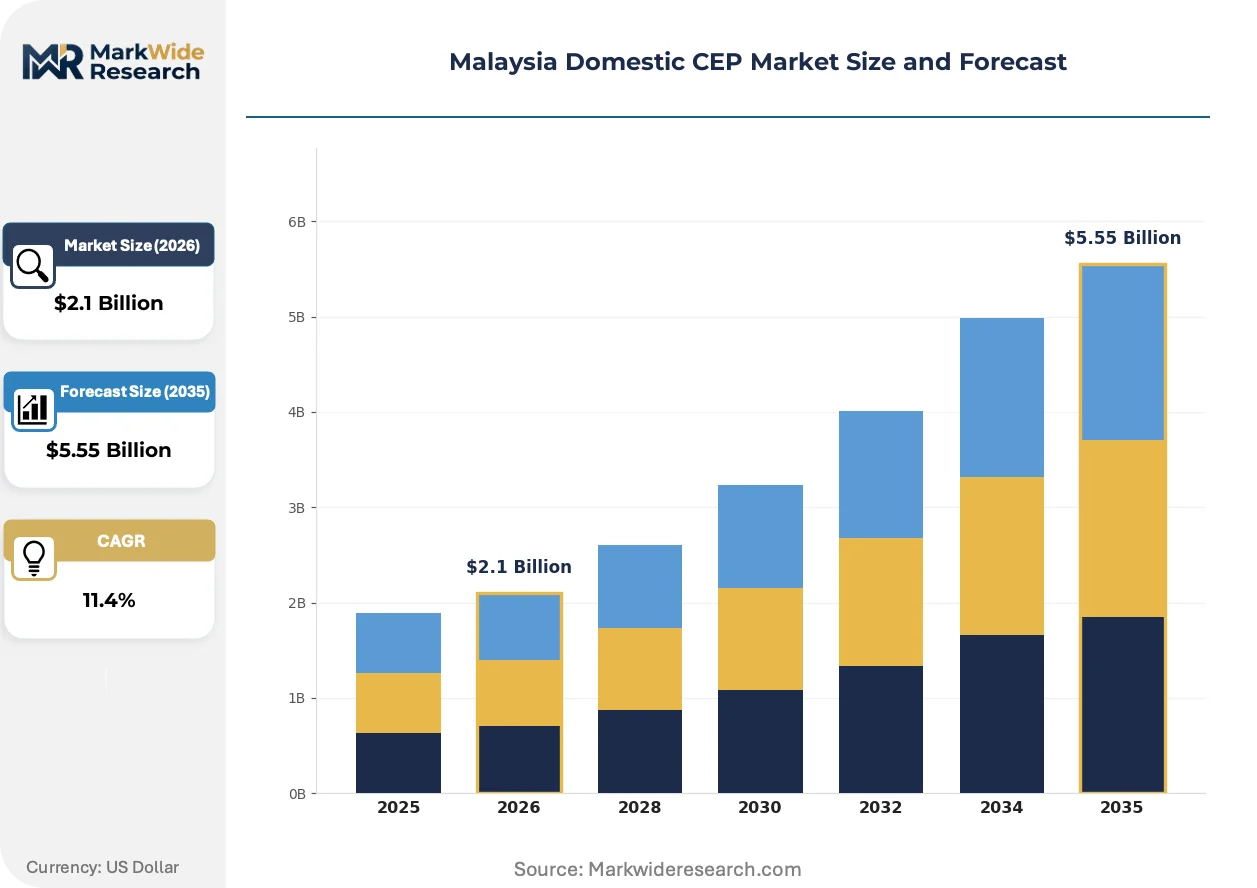
Market Dynamics
E-commerce platforms now command the majority of parcel volume growth across Peninsular Malaysia, forcing carriers to reconfigure hub networks around same-day delivery corridors in Greater Kuala Lumpur while maintaining cost discipline on rural routes.
Growth Catalysts
- Communications and Multimedia Act:MCMC service quality benchmarks mandate minimum delivery timeframes and tracking visibility, pushing operators toward barcode scanning and GPS-enabled fleet upgrades that improve customer retention.
- Electronics manufacturing clusters:Express delivery demand from medical device and semiconductor producers in Penang and Selangor generates premium-margin volumes requiring time-definite line-haul services.
- Digital retail penetration:Marketplace sellers abandoning self-fulfillment creates concentrated B2C parcel flows that justify automated sortation investments in Johor and Selangor hubs.
Market Restraints
- Diesel price volatility:Last-mile fleet operators face margin compression from fuel cost swings that standard delivery pricing cannot fully pass through to price-sensitive e-commerce shippers.
- Charging infrastructure gaps:Depot electrification timelines stall in secondary cities outside Klang Valley where grid capacity and fast-charging station density remain insufficient for commercial EV deployment.
- Road Transport Department certification:Commercial driver licensing requirements create bottlenecks for fleet expansion during peak seasonal demand surges in East Malaysia.
Strategic Opportunities
- East Malaysia underpenetration:Sarawak and Sabah present white-space potential for express networks serving resource extraction and plantation logistics with limited incumbent competition.
- DOSH occupational safety alignment:Proactive compliance with workplace safety standards opens preferred supplier status with government and healthcare procurement panels.
- Micro-fulfillment convergence:Integration of automated sortation with urban dark stores enables sub-two-hour delivery windows for grocery and pharmacy verticals in dense Klang Valley districts.
Industry Challenges
- Warehouse automation talent scarcity:Maintenance technicians for robotic sortation systems command premium wages that strain operational budgets outside Selangor's technical labor pool.
- Legacy IT integration friction:Electronic proof-of-delivery systems must interface with disparate marketplace seller platforms, creating data synchronization failures and disputed delivery confirmations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Domestic CEP Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, Next-Day Delivery End User: Retailers, E-commerce Platforms, Corporates, Individual Consumers Distribution Channel: Online, Offline, Third-Party Logistics, Direct Sales Package Type: Envelope, Box, Pallet, Crate |
| Companies Covered | Pos Malaysia, GD Express, City-Link Express, Ninja Van, J&T Express, ABX Express, Skynet Express, TA-Q-BIN, Lalamove, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Domestic CEP Market Trends and Innovations
Parcel logistics across Malaysia is migrating from labor-intensive hub operations toward capital-heavy automation, with regulatory pressure and labor cost trajectories accelerating technology deployment timelines beyond original carrier forecasts.
Automated sortation systems are migrating from manual belt-fed configurations toward AI-driven parcel dimensioning and routing in Selangor and Johor distribution centers. E-commerce platforms with captive logistics arms are adopting these systems fastest, compressing per-parcel handling costs by eliminating secondary manual touches. The technology is migrating from proof-of-concept installations in Port Klang toward standardized deployment across tier-two hubs within the forecast window.
MCMC enforcement of service quality standards under the Communications and Multimedia Act is tightening delivery timeframe mandates and complaint resolution protocols. Carriers must now maintain real-time tracking portals and automated customer notification systems or face license review. Express operators serving cross-border manufacturers in Penang face the steepest compliance investments, as medical device and electronics shippers demand audit-ready chain-of-custody documentation.
Consolidation of marketplace seller fulfillment is displacing fragmented self-ship models with platform-integrated logistics contracts. Third-party sellers on dominant e-commerce channels now default to designated carrier partnerships rather than negotiating spot rates. This concentration is most visible in Greater Kuala Lumpur, where platform-controlled parcel volumes now determine hub capacity planning for private express operators.
Malaysia Domestic CEP Market Segmentation
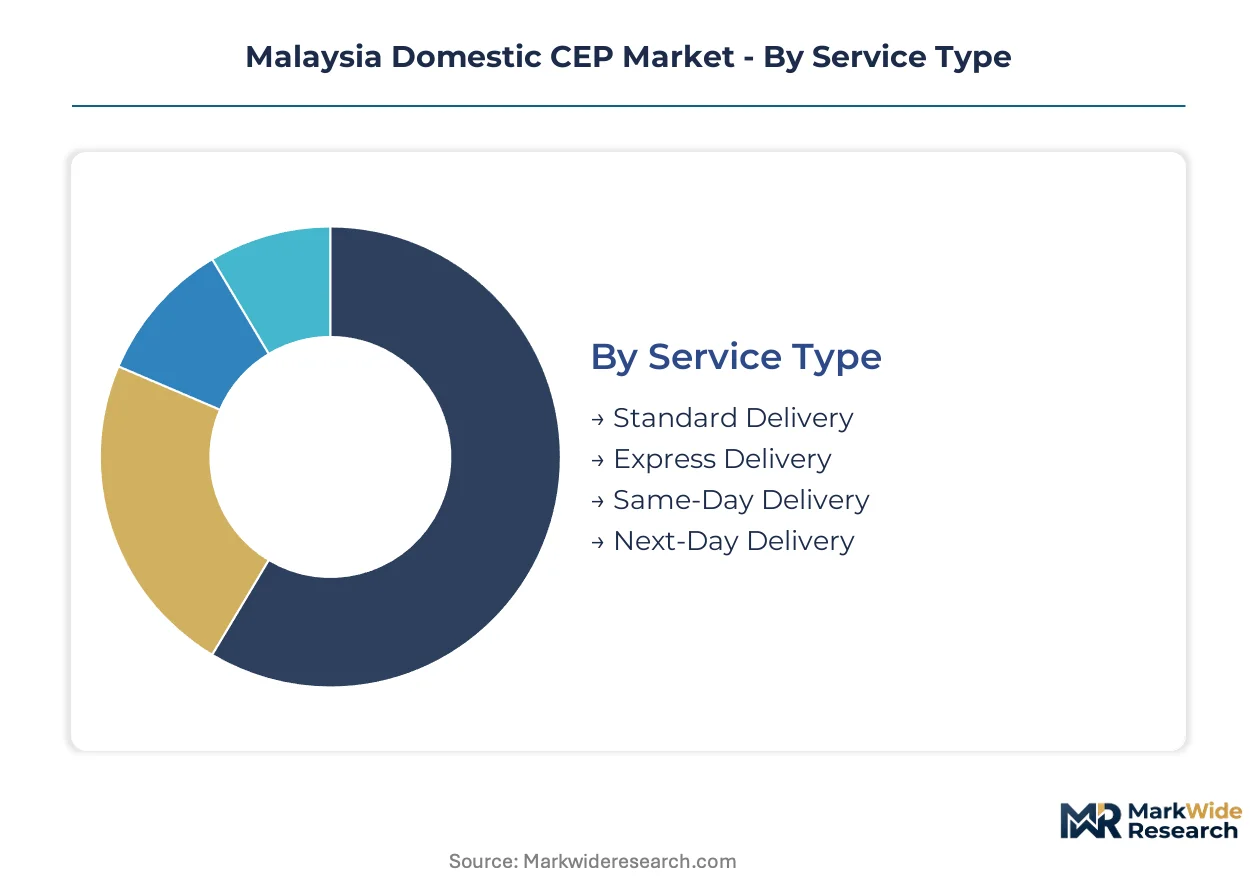
Malaysia Domestic CEP operators configure service portfolios around delivery velocity tiers and platform-integrated fulfillment models. Segmentation reveals where automation investments concentrate and which customer categories drive margin compression versus premium capture.
Service Type:
Mature corridors in Greater Kuala Lumpur anchor volume, while emerging velocity tiers reshape capital allocation across the peninsula.
- Standard Delivery:Two-to-three-day line-haul networks utilizing barcode scanning and GPS tracking for non-urgent parcels. Demand concentrates in East Malaysia and secondary Peninsular cities where cost sensitivity outweighs speed requirements, though diesel price volatility squeezes margins on these routes.
- Express Delivery:Time-definite services with guaranteed delivery windows for documents and packages under 30 kilograms. Penang electronics manufacturers and Selangor medical device producers generate premium-margin volumes requiring audit-ready chain-of-custody documentation under MCMC mandates.
- Same-Day Delivery:Dense urban depot placement enables sub-six-hour fulfillment for Klang Valley grocery and pharmacy verticals.
- Next-Day Delivery:Overnight line-haul services connecting Johor and Selangor hubs to East Malaysia.
Standard Delivery retains volume leadership; Same-Day Delivery holds the steepest expansion curve.
End User:
Customer concentration patterns split between platform-captive volumes and fragmented self-fulfillment legacy.
- E-commerce Platforms:Marketplace sellers abandoning self-fulfillment create concentrated B2C parcel flows that justify automated sortation investments in Johor and Selangor hubs. Platform-controlled volumes now determine hub capacity planning for private express operators in Greater Kuala Lumpur.
- Corporates:Cross-border connected manufacturers in electronics and medical devices generate express delivery demand with stringent documentation requirements.
- Retailers:Brick-and-mortar chains adopting omnichannel fulfillment models.
- Individual Consumers:Price-sensitive shippers utilizing spot-rate services for occasional parcel dispatch.
E-commerce Platforms dominate volume growth; Corporates sustain the highest yield per parcel.
Distribution Channel:
Channel economics favor integrated platform logistics over fragmented third-party arrangements.
- Third-Party Logistics:Independent carriers compete on price in high-volume corridors while differentiating through data-driven route optimization. J&T Express and Ninja Van deploy distinct technology stacks to capture e-commerce platform contracts.
- Online:Digital booking portals with real-time tracking integration mandated by MCMC service quality benchmarks.
- Offline:Pos Malaysia leverages nationwide post office infrastructure for rural coverage density.
- Direct Sales:Enterprise contracts with electronics and medical device manufacturers in Penang and Selangor.
Third-Party Logistics captures the majority of platform-integrated volume; Direct Sales delivers the most stable contract tenure.
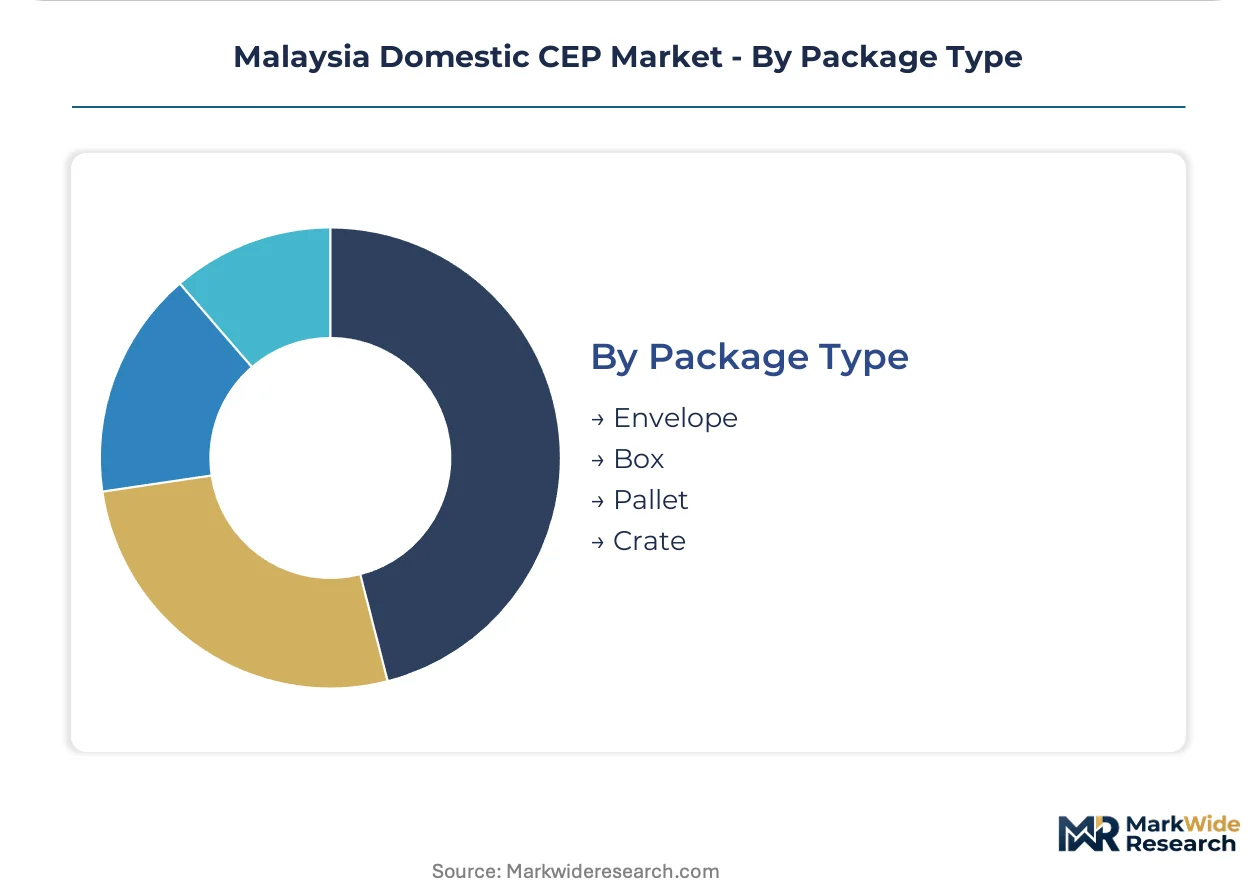
Package Type:
Physical handling requirements dictate automation compatibility and last-mile fleet configuration.
- Box:Rectangular corrugated containers dominating e-commerce parcel flows. AI-driven dimensioning systems in Selangor and Johor distribution centers compress per-parcel handling costs by eliminating secondary manual touches.
- Envelope:Document pouches requiring flat-sort automation for corporate express lanes.
- Pallet:Unitized loads for B2B industrial zone transfers between Port Klang and Penang.
- Crate:Rigid containers for fragile electronics and medical device shipments.
Box formats command the highest automation investment; Envelope volumes face steady displacement from digital document substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port Klang's container throughput infrastructure underwrites Peninsular Malaysia's dominance in parcel logistics, with the Klang Valley corridor absorbing the bulk of automated sortation investment and same-day delivery capacity deployment across the forecast window.
Greater Kuala Lumpur and Selangor
E-commerce platform consolidation drives dense urban depot placement for sub-six-hour fulfillment windows. MCMC service quality mandates under the Communications and Multimedia Act enforce real-time tracking portals and automated customer notification systems. Cyberjaya and Shah Alam distribution centers anchor AI-driven parcel dimensioning investments that eliminate secondary manual touches.
Johor
Cross-border manufacturing linkages to Singapore generate express delivery demand for electronics and medical device producers. The Iskandar Malaysia development corridor attracts automated sortation deployments serving platform-integrated logistics contracts. Pasir Gudang industrial zones concentrate overnight line-haul capacity connecting to East Malaysia.
Penang
Electronics manufacturing clusters in Bayan Lepas and Batu Kawan generate premium-margin express volumes requiring time-definite services. Audit-ready chain-of-custody documentation requirements from medical device shapers reshape carrier compliance investments. The Port of Penang facilitates cross-border connected manufacturer logistics with stringent delivery windows.
Sarawak
Resource extraction and plantation logistics present white-space potential for express networks with limited incumbent competition. Road Transport Department commercial driver licensing requirements create bottlenecks for fleet expansion during peak seasonal demand surges. Kuching and Miri concentrate last-mile infrastructure investment serving B2B industrial accounts.
Sabah
Secondary city charging infrastructure gaps stall depot electrification timelines outside core urban centers. Diesel price volatility squeezes margins on standard delivery routes where cost sensitivity outweighs speed requirements. Kota Kinabalu anchors regional hub operations connecting to Peninsular Malaysia via overnight air and sea freight corridors.
Malaysia Domestic CEP Market Competitive Landscape
On the supply side, the industry is bifurcated between incumbent postal infrastructure and private express operators competing on velocity tiers and technology differentiation. Pos Malaysia retains unmatched rural coverage density through its nationwide post office network, while private carriers concentrate automated sortation investment in Selangor and Johor hubs. Two strategic archetypes dominate: platform-integrated logistics providers capturing consolidated e-commerce volumes, and premium express specialists serving cross-border manufacturers with time-definite documentation requirements. Competitive dynamics center on hub capacity expansion and data-driven route optimization capabilities rather than price alone.
Within the integrated platform tier, J&T Express and Ninja Van exemplify volume-driven positioning through technology-enabled operational models. Pos Malaysia anchors the universal service obligation archetype with infrastructure no rival can replicate. GD Express occupies the premium express lane between industrial zones, representing the cross-border manufacturing specialist category. These three players collectively illustrate how carrier strategy fragments across velocity tiers, geographic coverage mandates, and end-user concentration patterns.
| Leading Market Players |
|---|
| Pos Malaysia |
| GD Express |
| City-Link Express |
| Ninja Van |
| J&T Express |
| ABX Express |
| Skynet Express |
| TA-Q-BIN |
| Lalamove |
| Others |
Pricing and Supply Chain Analysis
Selangor's automated sortation hub concentration grants carriers serving Greater Kuala Lumpur disproportionate pricing leverage on same-day delivery corridors, while diesel-dependent operators in East Malaysia absorb margin compression they cannot pass downstream to price-sensitive e-commerce shippers.
Pricing Analysis
Volume-discount tiering structures dominate platform-integrated logistics contracts, with e-commerce marketplaces extracting steepest discounts for consolidated parcel flows while corporates in Penang electronics clusters pay premiums for audit-ready chain-of-custody documentation. Price differentiation rests on delivery velocity guarantees and MCMC compliance certification tiers. Pricing pressure intensifies in standard delivery segments as J&T Express and Ninja Van compete aggressively for high-volume B2C flows. Individual consumers exhibit highest price sensitivity, while medical device manufacturers in Selangor demonstrate lowest elasticity for time-definite express services.
Supply Chain Analysis
Export-control regimes on automated sortation technology limit equipment flows from Germany, Japan, and South Korea into Malaysian distribution centers, constraining depot automation timelines. Component dependencies center on conveyor systems, AI-driven dimensioning hardware, and fleet telematics modules from these manufacturing bases. Single-source vulnerability concentrates in robotic maintenance technician labor pools centered on Selangor's technical training corridors. Distribution runs through platform-integrated hub networks in Johor and Selangor before radiating to secondary cities via diesel-dependent line-haul fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of technicians qualified for robotic sortation system maintenance concentrates operational risk with carriers who failed to secure training pipelines early, locking in capability gaps that widen with each automation deployment cycle.
For Market Incumbents: Insulate premium express margins by deepening backward integration into captive line-haul capacity between Penang and Port Klang, countering fuel cost volatility that threatens standard delivery profitability. Accelerate certification investment under MCMC service quality mandates to disqualify price-competitive challengers from government and healthcare procurement panels. Secure exclusive technician training partnerships with Selangor technical institutes before labor scarcity inflates maintenance costs further.
For New Entrants and Emerging Players: Establish a beachhead in Sarawak and Sabah express corridors where resource extraction logistics face limited incumbent competition and platform-integrated carriers underinvest in rural coverage density. Target plantation and B2B industrial accounts in Kuching and Miri with overnight line-haul services connecting to Peninsular hubs. Deploy go-to-market strategies emphasizing DOSH occupational safety alignment to unlock preferred supplier status with government procurement channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with proven automated sortation deployment experience and platform-integrated logistics contracts locked through the projection horizon. Long-term viability hinges on electrification readiness as charging infrastructure matures in secondary cities. Acquisition targets should demonstrate functional EV depot pilots and technician training pipelines. Watch for inflection when MCMC tightens delivery timeframe mandates beyond current compliance thresholds, forcing laggards into expensive catch-up investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Deployment | AI-driven dimensioning in Selangor hubs eliminates secondary manual touches and compresses per-parcel handling costs. |
| Fleet Electrification Pilot | EV depot trials in Cyberjaya and Shah Alam position carriers for MCMC carbon disclosure requirements ahead of rivals. |
| Platform-Integrated Logistics Contract | Exclusive partnerships with dominant e-commerce marketplaces lock in volume visibility that justifies hub capacity expansion. |
| East Malaysia Network Buildout | Express lane investment in Sarawak and Sabah captures white-space B2B demand from resource extraction and plantation logistics. |
| MCMC Compliance Certification | Proactive alignment with service quality mandates secures preferred supplier status for government and healthcare procurement panels. |
Research Methodology
The analysis maps courier, express, and parcel service tiers alongside automated sortation technology adoption curves, each validated through fleet operations directors, hub automation engineers, platform logistics procurement managers, and MCMC regulatory affairs specialists. Primary interview insights triangulate against secondary sources including MCMC service quality enforcement records, Road Transport Department commercial vehicle licensing data, and DOSH occupational safety compliance filings. Bottom-up parcel volume modeling across velocity tiers reconciles with top-down market sizing derived from e-commerce platform transaction disclosures.
Assumptions held fixed include MCMC regulatory enforcement intensity, diesel price volatility bands, and platform-fulfillment consolidation trajectories across the modeling period. Segmentation dimensions span delivery velocity tiers, end-user concentration patterns, distribution channel structures, and package format automation compatibility. CAGRs derive from parcel volume elasticity against e-commerce penetration rates and hub capacity expansion schedules. Forecast inputs incorporate fleet electrification timelines constrained by secondary city charging infrastructure buildout and technician labor pool growth projections.
Macroeconomic conditions sit as an overlay; deviation in ringgit exchange rates, diesel subsidy policies, or e-commerce platform commission structures would shift the trajectory. Material shifts in MCMC service quality mandate enforcement or Road Transport Department driver certification bottlenecks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Netherlands Road Freight Transport Market