
 India less than-Truck-Load (LTL) Market | 2026-2036
India less than-Truck-Load (LTL) Market Size, Share, and Industry Trends Forecast 2026-2036
India less than-Truck-Load (LTL) Market Insights
Trained fleet operators and certified warehouse supervisors is reorganizing how cargo networks scale across India's fragmented road freight sector. Delhivery Limited leverages its technology-first hub architecture to dominate last-mile connectivity in dense urban corridors. VRL Logistics Ltd anchors its position through disciplined route density across southern and western India. Transport Corporation of India Limited (TCI) sustains competitive advantage with integrated cold-chain capabilities spanning pharmaceutical and perishable verticals.
Less than-Truck-Load (LTL) freight consolidation combines multiple small shipments from distinct shippers into a single truckload, typically requiring hub-and-spoke sorting facilities with cross-docking throughput exceeding 5,000 tonnes daily at major nodes. The primary commercial purpose is reducing per-unit transport cost for shipments below full-truck capacity while maintaining scheduled delivery reliability. Standard and expedited service types capture the bulk of volume, though temperature-controlled segments command premium pricing due to pharmaceutical cold-chain compliance requirements. E-commerce end users represent the fastest-expanding demand pool, while GPS tracking and automated dispatch technologies increasingly determine carrier selection criteria among enterprise shippers.
BIS certification for vehicle tracking devices, GST e-way bill mandates, and state-level motor vehicle regulations collectively enforce digital traceability and tax compliance across interstate LTL movements. The PLI scheme for logistics infrastructure incentivizes automated material handling investments, narrowing the technology gap between organized and unorganized fleet operators. Stakeholders must monitor how FASTag penetration and national logistics policy implementation reshape terminal-to-terminal versus door-to-door delivery economics.
Market Dynamics
GST e-way bill mandates and FASTag penetration are compressing terminal dwell times while forcing unorganized fleet operators toward digital compliance or market exit.
Growth Catalysts
- E-commerce fulfillment networks:Tier-2 and tier-3 city penetration by online retail platforms generates sustained small-shipment volumes requiring scheduled LTL consolidation.
- PLI scheme for logistics infrastructure:Automated material handling and sorting equipment investments receive production-linked incentives, narrowing technology gaps between organized and fragmented operators.
- Pharmaceutical cold-chain compliance:Temperature-controlled LTL services capture premium pricing as CDSCO regulations tighten distribution integrity requirements for biologics and vaccines.
Market Restraints
- Diesel price volatility:Fuel constitutes 35-40% of operating costs for road freight operators, with no hedge mechanisms available to mid-tier fleet owners.
- Driver shortage concentration:Trained commercial vehicle operators cluster in Maharashtra, Karnataka, and Tamil Nadu, leaving northern and eastern corridors underserved.
- Interstate permit friction:State-level motor vehicle regulations maintain redundant documentation requirements despite GST harmonization, inflating transit times.
Strategic Opportunities
- Northeastern corridor underpenetration:Assam, Manipur, and Nagaland manufacturing clusters lack organized LTL infrastructure, creating first-mover positioning for automated hub operators.
- Cross-docking technology convergence:Integration of RFID tagging with automated sortation systems enables real-time shipment tracking without manual scanning bottlenecks.
- Door-to-door channel innovation:Direct pickup from micro-warehouses in dense urban cores bypasses traditional terminal aggregation, reducing first-mile costs for e-commerce shippers.
Industry Challenges
- Certified warehouse supervisor scarcity:BIS-compliant facility management training programs produce fewer than 2,000 qualified graduates annually against industry demand.
- Legacy TMS integration complexity:Mid-tier operators struggle to synchronize GST e-way bill APIs with existing fleet management software without custom development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India less than-Truck-Load (LTL) Market |
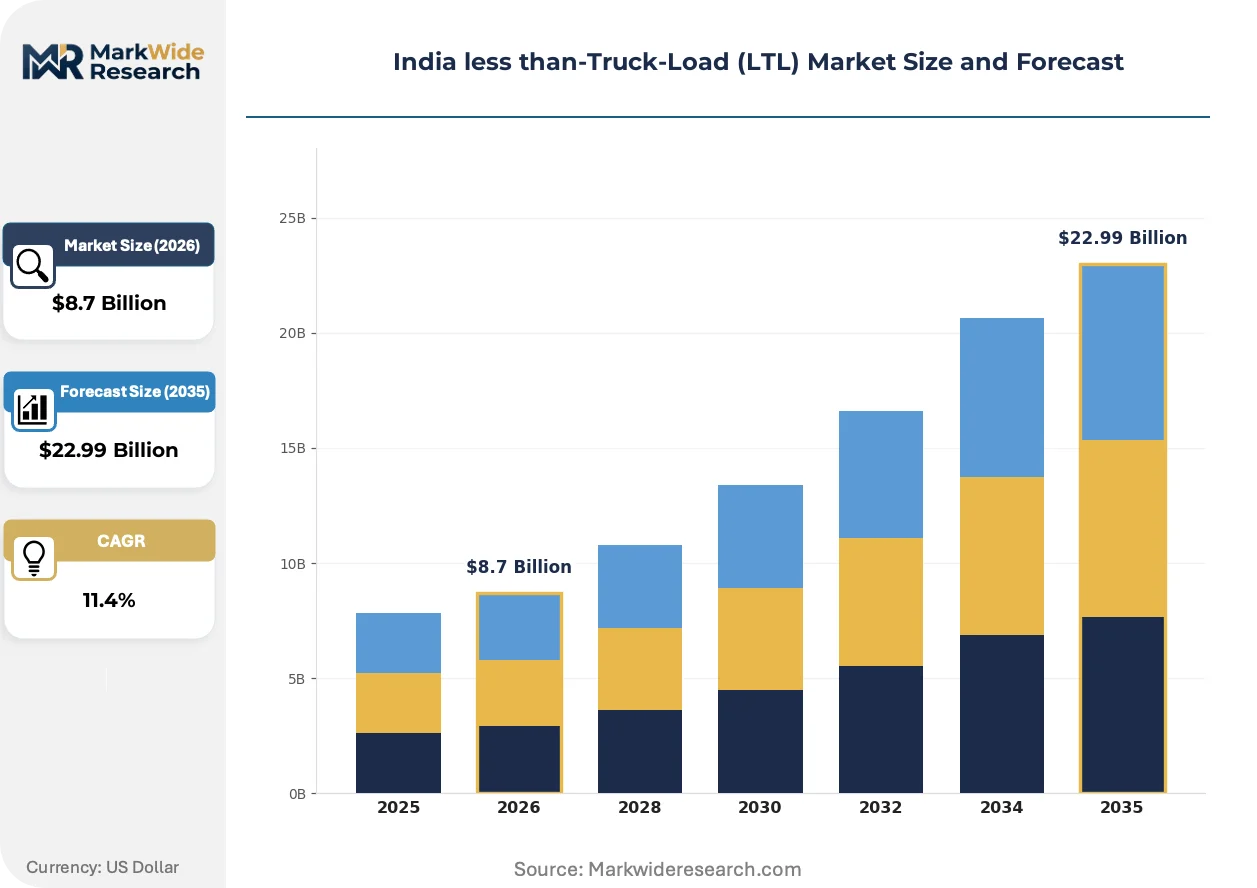
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard, Expedited, Fragile, Temperature-Controlled End User: Retailers, Manufacturers, E-commerce, Pharmaceuticals Technology: GPS Tracking, Automated Dispatch, Cloud Solutions, Load Optimization Delivery Mode: Street-Level, Dock-to-Dock, Door-to-Door, Terminal-to-Terminal |
| Companies Covered | Mahindra Logistics Ltd, Delhivery Limited, Transport Corporation of India Limited (TCI), VRL Logistics Ltd, ABC India Limited, BLR Logistiks (I) Ltd, V-Trans, Gati Express & Supply Chain Private Limited, Allcargo Logistics Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India less than-Truck-Load (LTL) Market Trends and Innovations
Digital freight matching platforms and automated sortation hardware are restructuring how cargo consolidators capture margin in India's fragmented road transport sector.
AI-powered dynamic routing engines analyze real-time traffic, fuel station density, and toll plaza queue lengths to optimize multi-drop LTL sequences. Third-party logistics providers in Delhi-NCR and Bengaluru are deploying these systems across 500-plus vehicle fleets. This capability is displacing static route planning that relied on driver experience and paper manifests.
BIS certification for vehicle tracking devices mandates AIS 140-compliant GPS hardware with emergency button functionality across all commercial vehicles above 3.5 tonnes. Fleet operators must retrofit existing assets or face permit renewal blocks. Pharmaceutical and e-commerce shippers now exclude non-compliant carriers from vendor panels, compressing the addressable supplier base.
Enterprise shippers are unbundling transportation from warehousing contracts, selecting LTL carriers through dedicated procurement teams rather than bundled 3PL relationships. Automotive component manufacturers in Pune and Chennai now run reverse auctions for lane-specific freight. This pattern concentrates volume with technology-transparent operators who expose real-time tracking APIs.
India less than-Truck-Load (LTL) Market Segmentation
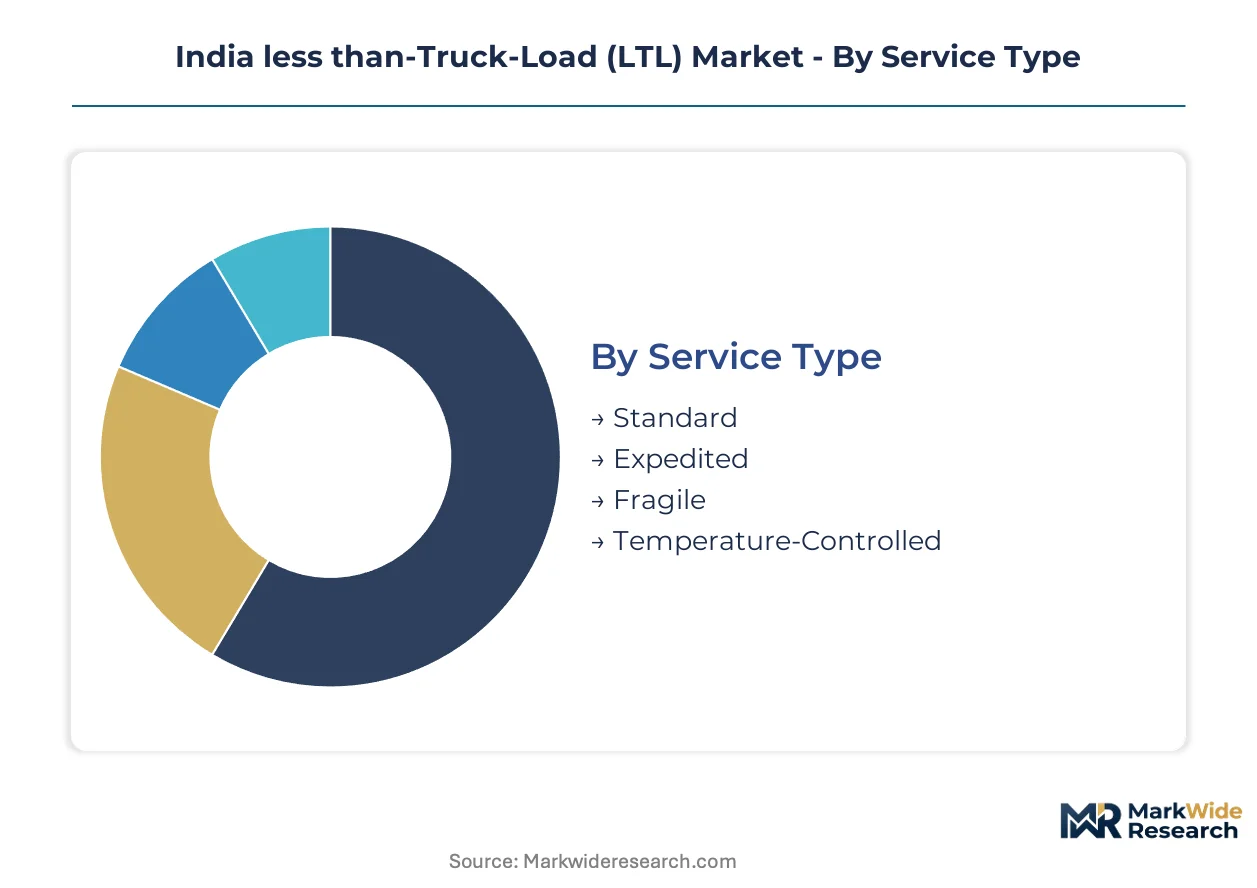
LTL carriers in India compete through service differentiation rather than commodity pricing. Segment boundaries determine technology investment priorities and margin capture potential across Maharashtra, Karnataka, and Tamil Nadu manufacturing corridors.
Service Type:
Temperature-controlled and expedited services command premium spreads above standard freight rates due to compliance overhead and asset specificity.
- Standard:Scheduled consolidation of non-specialized cargo through hub-and-spoke networks with fixed transit windows. Retail replenishment flows from Mumbai and Bengaluru distribution centers absorb the bulk of standard LTL volume as organized retail expands store footprints.
- Expedited:Time-definite delivery with guaranteed transit windows, typically utilizing direct line-haul bypass of intermediate sorting facilities. Automotive component manufacturers in Pune and Chennai procurement teams specify expedited service for production-critical inventory buffers.
- Fragile:Specialized handling protocols for glass, ceramics, and electronics with reduced stacking heights and shock-absorbent packaging mandates.
- Temperature-Controlled:Refrigerated transport maintaining 2-8°C or 15-25°C ranges per CDSCO pharmaceutical distribution guidelines.
Standard service holds installed capacity. Temperature-controlled is rotating up the share rankings.
End User:
Customer procurement sophistication determines API integration requirements and contract tenure structures.
- E-commerce:High-velocity small-parcel flows requiring same-day or next-day delivery commitments with real-time tracking visibility. Platform fulfillment networks penetrating tier-2 and tier-3 cities generate sustained shipment volumes that strain traditional terminal infrastructure.
- Pharmaceuticals:CDSCO-regulated distribution with temperature integrity documentation and batch-level traceability mandates. Biologics and vaccine manufacturers exclude non-compliant carriers from approved vendor panels.
- Retailers:Scheduled replenishment of fast-moving consumer goods with predictable seasonal amplitude.
- Manufacturers:Component and sub-assembly flows with just-in-time delivery windows tied to production schedules.
Pharmaceuticals maintains contract stickiness. E-commerce is expanding most quickly as platform penetration deepens.
Technology:
Technology stack choices separate organized operators from fragmented fleet owners in vendor selection processes.
- GPS Tracking:AIS 140-compliant vehicle location systems with emergency button functionality mandated by BIS certification rules. Fleet operators face permit renewal blocks for non-compliant assets.
- Automated Dispatch:AI-powered routing engines analyzing real-time traffic and toll queue lengths to optimize multi-drop sequences.
- Cloud Solutions:Centralized shipment data repositories enabling customer self-service tracking and electronic proof-of-delivery.
- Load Optimization:Algorithmic cargo sequencing maximizing cubic utilization and minimizing handling damage.
GPS Tracking holds regulatory-mandated ubiquity. Automated Dispatch is rotating up the share rankings as fleet scale thresholds rise.
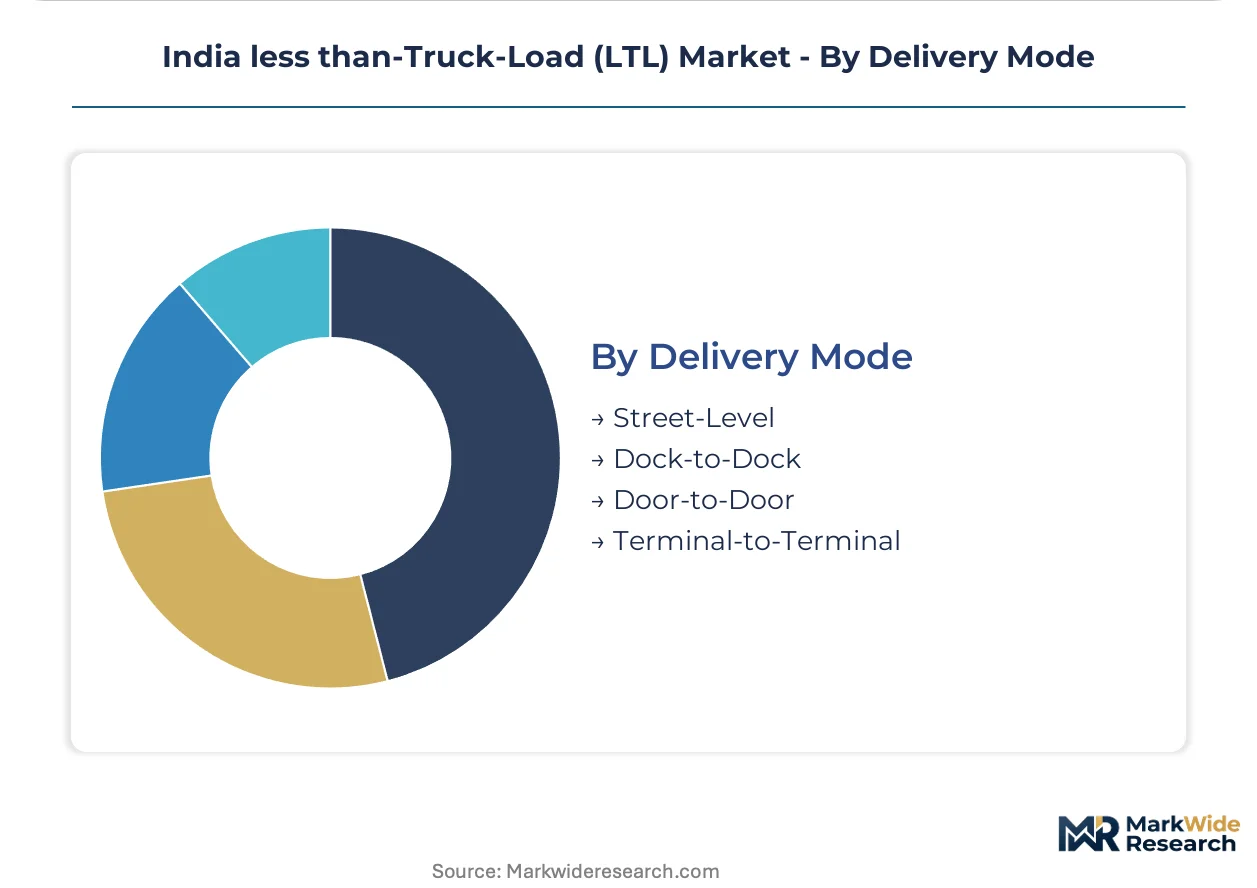
Delivery Mode:
Last-mile configuration determines labor cost structures and customer convenience trade-offs.
- Door-to-Door:Direct pickup and delivery without shipper or consignee terminal visits, capturing premium pricing for convenience. Micro-warehouse networks in dense urban cores enable first-mile consolidation without traditional terminal aggregation.
- Terminal-to-Terminal:Shipper and consignee both responsible for terminal access, minimizing carrier labor costs but constraining addressable market.
- Street-Level:Curb-side delivery without inside building access, common for bulky retail merchandise.
- Dock-to-Dock:Loading dock to loading dock transfer excluding any ground-level handling.
Terminal-to-Terminal holds legacy volume concentration. Door-to-Door is rotating up the share rankings as e-commerce shippers prioritize convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification for vehicle tracking devices and the PLI scheme for logistics infrastructure anchor Maharashtra as the dominant geography, with GST harmonization reducing interstate friction across manufacturing corridors.
Maharashtra
Mumbai-Pune manufacturing belt generates dense automotive component flows requiring scheduled LTL consolidation. The state's motor vehicle regulations enforce AIS 140-compliant GPS hardware across commercial fleets. Chakan and Talegaon industrial clusters absorb expedited freight services for just-in-time production schedules.
Karnataka
Bengaluru's e-commerce fulfillment networks penetrate tier-2 and tier-3 cities with high-velocity small-parcel volumes. FASTag penetration at state toll plazas compresses terminal dwell times for interstate movements. Hosur and Peenya industrial estates concentrate pharmaceutical and electronics manufacturing demanding temperature-controlled distribution.
Tamil Nadu
Chennai's automotive OEMs specify time-definite LTL for production-critical inventory buffers. CDSCO regulations tighten distribution integrity requirements for biologics manufactured in Sriperumbudur. Coimbatore's textile machinery cluster generates fragile cargo requiring specialized handling protocols.
Gujarat
Sanand and Halol automotive hubs generate component flows toward northern and western consumption centers. The state's logistics parks receive PLI scheme incentives for automated material handling investments. Mundra port connectivity creates transshipment demand for containerized LTL consolidation.
Telangana
Hyderabad's pharmaceutical formulation units require cold-chain compliance for vaccine distribution to tier-2 cities. State-level warehouse licensing reforms accelerate organized operator entry. Genome Valley biologics manufacturers exclude non-compliant carriers from approved vendor panels.
India less than-Truck-Load (LTL) Market Competitive Landscape
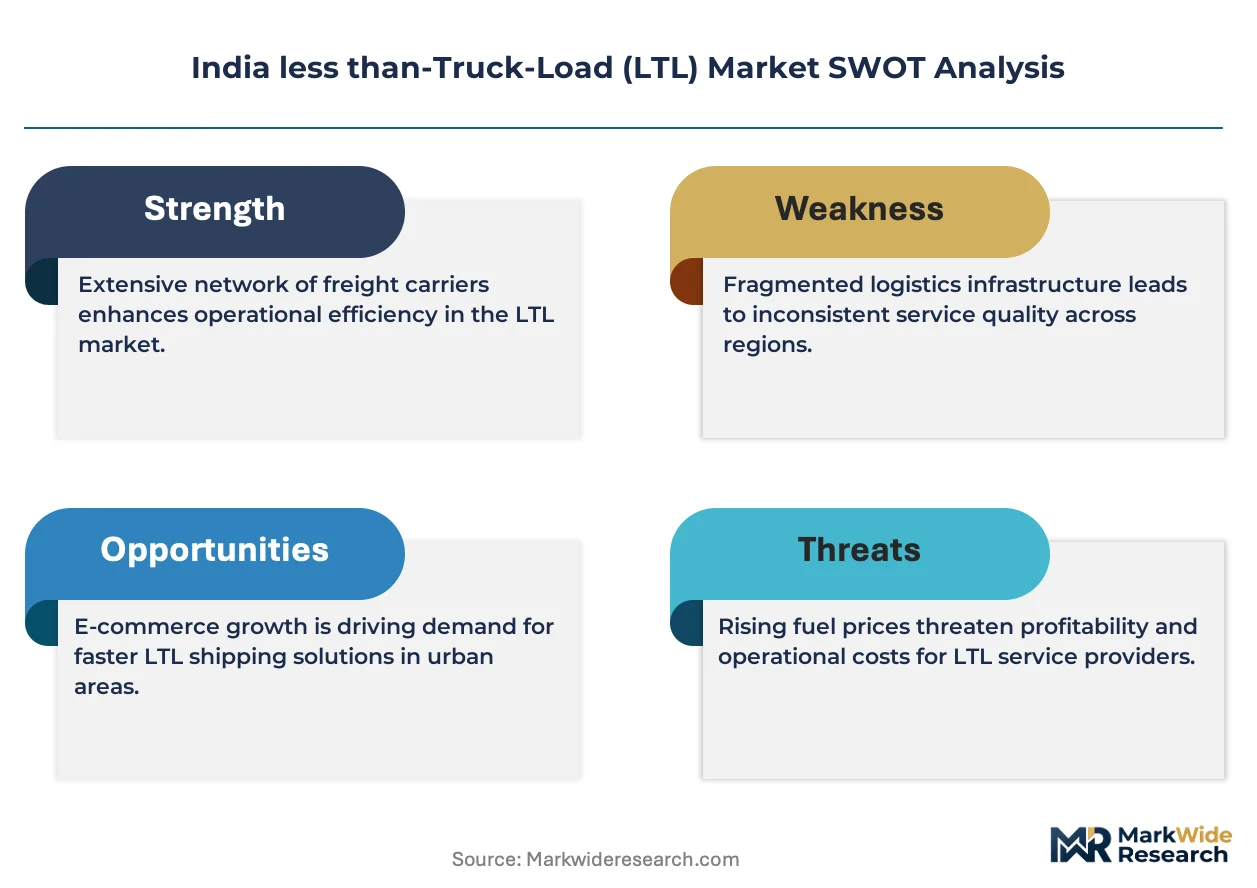
A small set of integrated leaders sits above a broader specialist tier, with technology-transparent operators capturing volume from bundled 3PL relationships. The organized segment narrows gaps with fragmented fleet owners through automated hub investments. Three archetypes dominate: technology-first platform operators, route-density specialists in southern corridors, and integrated cold-chain providers. Competitive moves concentrate on M&A for hub network expansion and API integration partnerships with enterprise shippers.
Among integrated logistics providers, Delhivery Limited and Transport Corporation of India Limited occupy positions exemplifying technology-first and cold-chain specialist archetypes respectively. VRL Logistics Ltd anchors the route-density specialist tier with disciplined network coverage across western and southern India. These three represent the competitive positioning spectrum: platform-native dispatch systems, pharmaceutical compliance infrastructure, and corridor-specific frequency optimization.
| Leading Market Players |
|---|
| Mahindra Logistics Ltd |
| Delhivery Limited |
| Transport Corporation of India Limited (TCI) |
| VRL Logistics Ltd |
| ABC India Limited |
| BLR Logistiks (I) Ltd |
| V-Trans |
| Gati Express & Supply Chain Private Limited |
| Allcargo Logistics Ltd |
| Others |
Pricing and Supply Chain Analysis
Forty-eight to seventy-two hour terminal dwell times in Maharashtra and Karnataka corridors concentrate pricing power with hub operators possessing automated sortation capacity, while diesel cost pass-through limitations compress margins for asset-light brokers. This lead-time band shapes how BIS-certified fleet owners extract premiums against unorganized competitors lacking GST e-way bill integration.
Pricing Analysis
Maharashtra-to-Tamil Nadu lanes command 15-20% premiums over western corridor equivalents due to driver shortage concentration and higher toll density. Pricing stratifies across temperature-controlled, expedited, and standard tiers, with CDSCO certification and AIS 140 GPS compliance as primary differentiation drivers. Cost compression in standard freight is intensifying because diesel price volatility lacks hedge mechanisms for mid-tier operators. E-commerce shippers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize compliance over rate negotiation.
Supply Chain Analysis
Inbound logistics costs for automated material handling equipment hinge on Mundra port congestion and container availability from Chinese and German manufacturing hubs. Domestic production of refrigerated truck bodies draws from Gujarat and Maharashtra steel fabrication clusters, while telematics hardware sources from Taiwan and South Korea. Single-source vulnerability in AIS 140-certified GPS modules creates procurement risk for fleet retrofit programs. Distribution runs through hub-and-spoke networks with cross-docking nodes in Mumbai, Bengaluru, and Chennai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India LTL market tracks a cyclical recovery pattern tied to e-commerce fulfillment network expansion into tier-2 and tier-3 cities, with GST harmonization and PLI scheme incentives providing counter-cyclical support.
For Market Incumbents: Compound route density advantages through disciplined M&A in northeastern corridors where organized infrastructure remains sparse. Integrate backward into captive driver training programs to offset Maharashtra-Karnataka-Tamil Nadu operator concentration. Defend margin position by accelerating API integration partnerships with enterprise pharmaceutical shippers before CDSCO compliance mandates harden vendor panels. For New Entrants and Emerging Players: Differentiate on door-to-door channel innovation targeting micro-warehouse networks in dense urban cores, bypassing traditional terminal aggregation costs. Penetrate Assam and Manipur manufacturing clusters where automated hub infrastructure is underdeveloped. Pursue asset-light partnerships with existing FASTag-compliant fleet operators rather than greenfield capacity builds. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified logistics conglomerates seeking to monetize non-core LTL divisions amid balance sheet restructuring. Long-term viability favors operators with integrated cold-chain certification and technology-transparent tracking APIs. Monitor FASTag penetration rates at state toll plazas as inflection indicator for terminal dwell time compression and working capital efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hub Network Expansion | PLI scheme incentives narrow technology gaps with unorganized competitors in Maharashtra and Karnataka corridors. |
| Cold-Chain Certification Investment | CDSCO compliance infrastructure captures pharmaceutical biologics distribution excluded from non-certified vendor panels. |
| API Integration Partnerships | Real-time tracking transparency displaces bundled 3PL relationships among automotive component manufacturers in Pune. |
| Driver Training Program Development | BIS-compliant certification addresses certified warehouse supervisor scarcity constraining facility management scaling. |
| Northeastern Corridor Entry | First-mover positioning in Assam and Nagaland manufacturing clusters leverages underpenetrated organized LTL infrastructure. |
Research Methodology
Cross-validation between fleet operator interviews and regulatory filing analysis anchors the qualitative findings in operational reality. Primary fieldwork encompassed logistics park operators, pharmaceutical distribution managers, e-commerce fulfillment heads, and GST compliance officers across Maharashtra, Karnataka, Tamil Nadu, and Telangana. Secondary sources included BIS certification records, CDSCO distribution guidelines, state motor vehicle department permit data, and PLI scheme implementation reports. Bottom-up volume modeling from lane-specific freight flows reconciled against top-down GDP elasticity estimates.
Sensitivity analysis around diesel price assumptions and e-commerce penetration rates tested forecast robustness across the projection horizon. Segmentation dimensions encompassed service type, end-user vertical, technology stack, and delivery mode, with regional production cluster as an additional India-specific layer. CAGRs derived from logistic curve fitting to historical tonnage data, incorporating GST implementation timeline effects and FASTag adoption curves as industry-specific inputs.
Material uncertainties — diesel price volatility spikes, interstate permit friction resurgence, and PLI scheme incentive modifications — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and technology adoption timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market