
 Vietnam Real Estate & Mortgage Market | 2026-2036
Vietnam Real Estate & Mortgage Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Real Estate & Mortgage Market Insights
Industrial logistics and high-density residential verticals is rebalancing developer pipelines away from resort-style leisure assets. Vingroup leverages its integrated township model to control land-to-handover timelines across Hanoi and Ho Chi Minh City megaprojects. Dat Xanh Group anchors its position through brokerage-to-development backward integration, capturing margin at multiple transaction points. Novaland Group specializes in mid-rise residential infill across southern provinces, navigating tighter zoning with compact floorplates.
Vietnam real estate and mortgage activity encompasses land acquisition, construction finance, residential and commercial sales, and long-term debt instruments collateralized by property titles. Mortgage underwriting employs loan-to-value ratios typically capped by central bank directive, with tenor structures ranging from fifteen to twenty-five years and interest rates benchmarked against government bond yields plus regulated spreads. Residential property type commands the deepest financing pool, though industrial segments are recording the fastest credit growth as manufacturing foreign direct investment escalates land absorption around northern ports. Fixed-rate financing structures dominate consumer preference for payment predictability, while construction loan instruments carry higher spreads reflecting staged disbursement risk and presale dependency.
The State Bank of Vietnam governs macroprudential lending limits and foreign currency exposure rules for mortgage portfolios, while the Ministry of Construction administers building codes and fire safety standards that shape project feasibility timelines. BIS certification requirements for construction materials and the Ministry of Natural Resources and Environment land-use master plans constrain greenfield site availability and elevate compliance costs for developers. Stakeholders must monitor how forthcoming revisions to the Housing Law and Land Law affect foreign ownership quotas and collective land compensation mechanisms, as these provisions will determine capital accessibility and project bankability for the next development cycle.
Market Dynamics
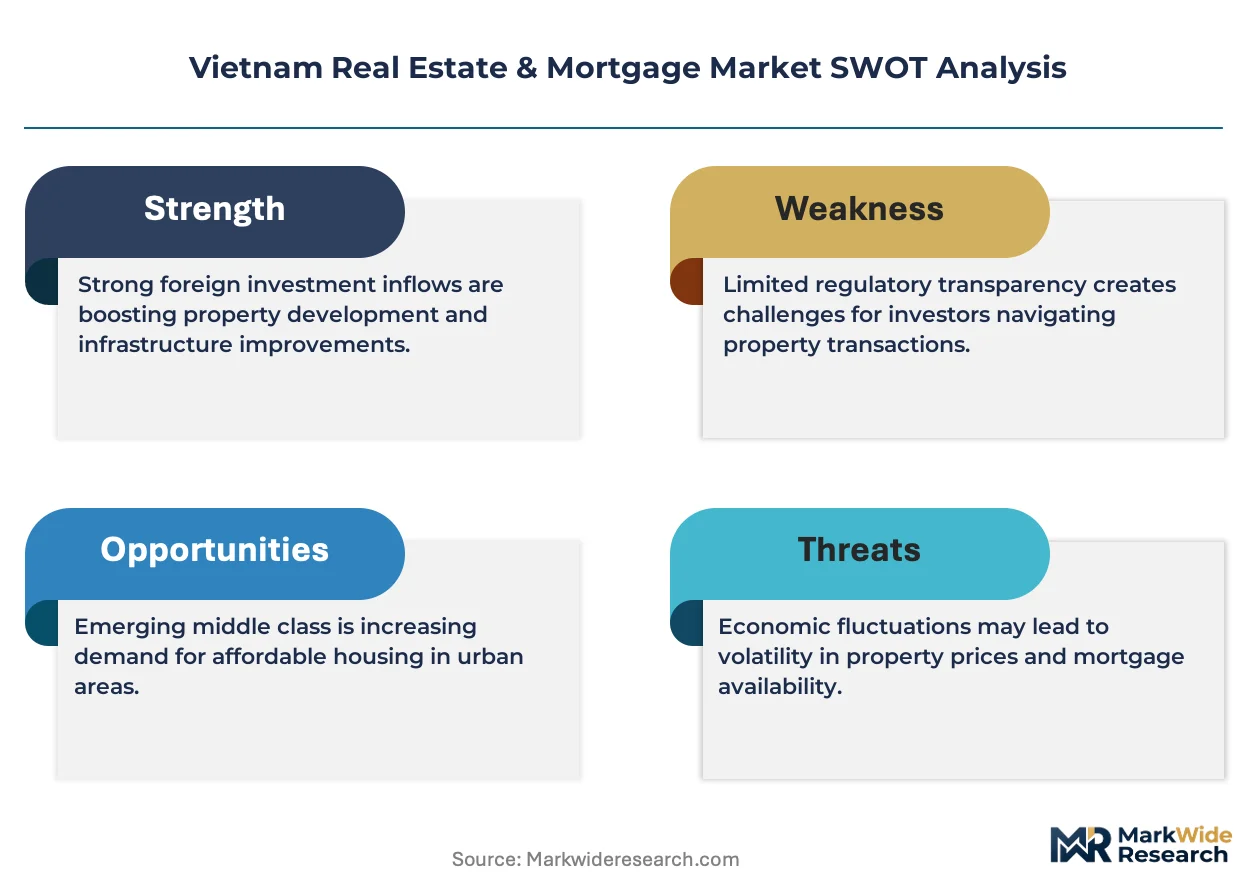
The State Bank of Vietnam's mortgage lending caps are compressing developer liquidity timelines while redirecting capital toward green-certified residential projects. This macroprudential tightening intersects with Vinhomes' integrated township rollout to reshape origination patterns across Ho Chi Minh City and Hanoi corridors.
Growth Catalysts
- Green Building Certification Mandates:The Ministry of Construction's revised fire safety and environmental standards are elevating compliance costs but unlocking preferential financing terms for certified projects. Developers pursuing EDGE or LOTUS ratings gain access to expanded credit quotas.
- Manufacturing FDI Inflows:Northern port provinces around Hai Phong are absorbing record industrial land absorption. This is accelerating construction finance demand for logistics facilities and worker housing clusters.
- Provincial Urbanization:Binh Duong and Dong Nai satellite corridors are capturing spillover demand from Ho Chi Minh City's constrained core. First-time buyers priced out of central districts are migrating to these transit-linked peripheries.
Market Restraints
- Land-Use Master Plan Constraints:The Ministry of Natural Resources and Environment's greenfield site restrictions are elevating land acquisition costs. Developers face extended compensation negotiations with collective land holders.
- Foreign Ownership Quota Caps:Current Housing Law provisions limit offshore buyers to 30% of units in any condominium project. This constrains capital inflows from regional investors seeking Vietnam exposure.
- Construction Material Certification Delays:BIS compliance timelines for imported steel and cement are extending project feasibility windows. Staged disbursement risk is widening construction loan spreads.
Strategic Opportunities
- Industrial-Residential Hybrid Formats:Worker housing integrated with manufacturing zones represents underpenetrated inventory. Developers can capture rental yield alongside land value appreciation in Bac Ninh and Hung Yen provinces.
- Digital Mortgage Origination:Tech-enabled pre-approval platforms are compressing underwriting cycles. Banks deploying AI-driven credit scoring can expand penetration among informal-income borrowers.
- Renewable Energy Integration:Solar rooftop mandates for commercial buildings are creating new asset classes. Green bond financing for net-zero residential towers aligns with State Bank of Vietnam priority lending directives.
Industry Challenges
- Project Finance Structuring Expertise:Limited domestic capacity in structured debt instruments constrains complex development financing. Banks require external advisors for multi-tranche construction facilities.
- Presale Dependency Risk:Staged disbursement mechanisms tie construction progress to unit pre-commitment rates. Developers face working capital strain when absorption slows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Real Estate & Mortgage Market |
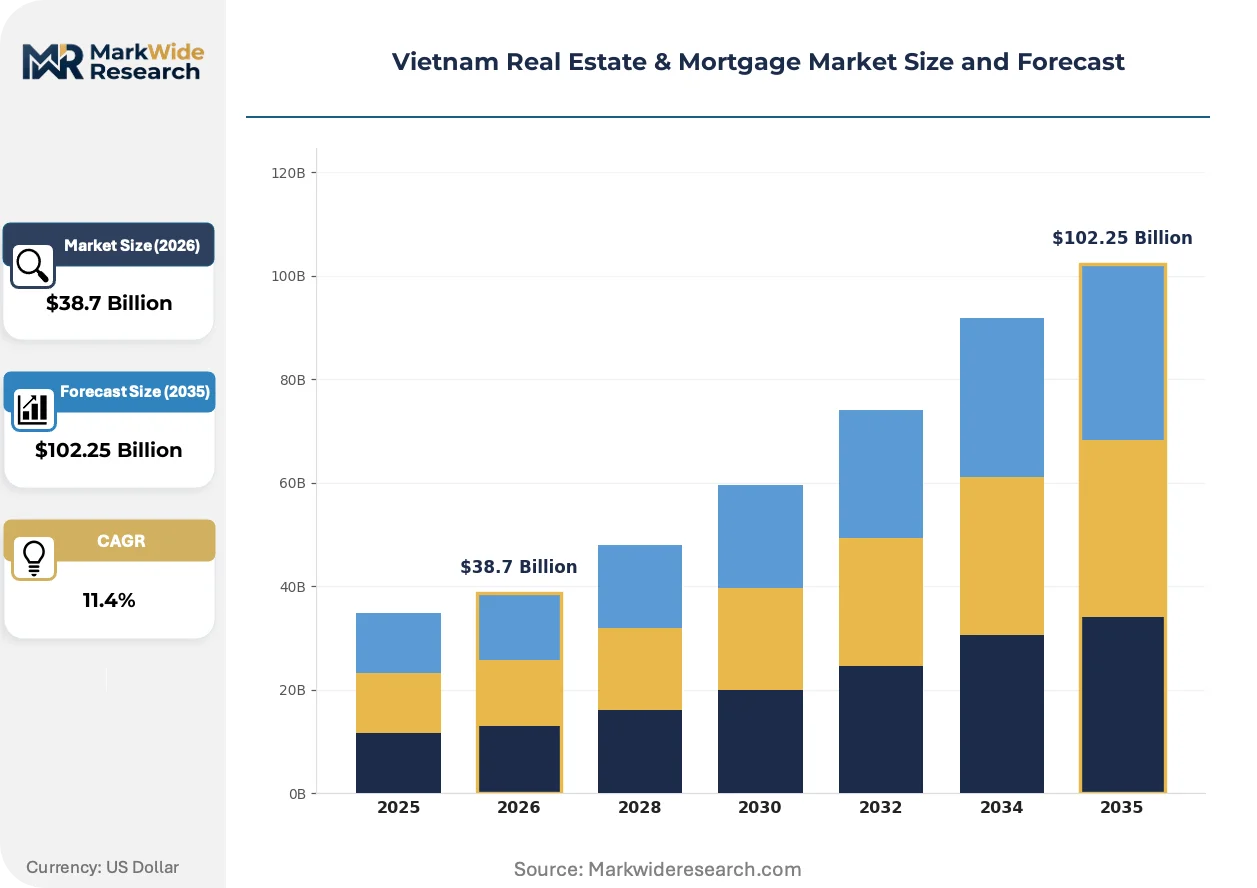
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Agricultural Financing Type: Fixed-rate, Adjustable-rate, Interest-only, Construction loan Customer Segment: First-time buyers, Real estate investors, Foreign buyers, Developers Investment Stage: Pre-development, Construction, Leasing, Fully developed |
| Companies Covered | Vingroup, Dat Xanh Group, FLC Group, Novaland Group, Nam Long Investment Corporation, Hung Thinh Real Estate Business Investment Corporation, Sun Group, Phat Dat Corporation, JLL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Real Estate & Mortgage Market Trends and Innovations
Digital underwriting platforms and modular construction methods are compressing development cycles while elevating data transparency across Vietnam's property transaction chain. These shifts are reshaping how capital flows from origination to handover.
Blockchain-enabled land title verification is consolidating transaction security across secondary market transfers. Provincial land registries in Da Nang and Can Tho are piloting distributed ledger integration to reduce title dispute resolution timelines. This compression of due diligence friction is accelerating portfolio turnover for institutional investors.
The State Bank of Vietnam's revised mortgage lending caps are tightening liquidity conditions for non-certified projects while expanding quotas for green-rated inventory. Developers must now sequence certification timelines ahead of financing applications to access preferential terms. Residential segments in Ho Chi Minh City are responding by accelerating EDGE pre-certification submissions.
Buyer preference is rotating toward fixed-rate tenors as floating-rate volatility erodes payment predictability. Young professionals in Hanoi are prioritizing twenty-year locked structures over shorter adjustable alternatives. This shift is forcing banks to rebalance liability hedging strategies and extend swap market participation.
Vietnam Real Estate & Mortgage Market Segmentation
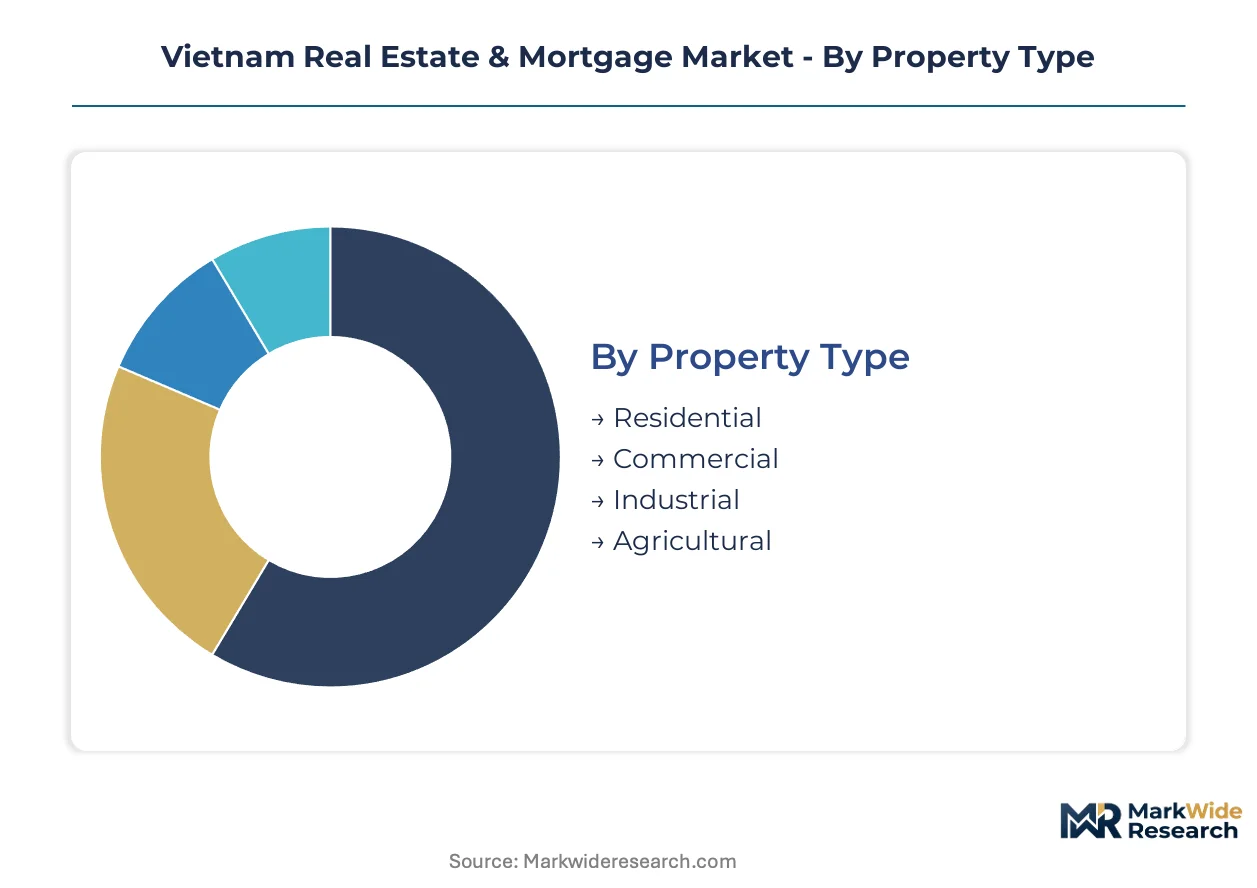
Segmentation in Vietnam's real estate and mortgage market determines which capital pools and regulatory frameworks apply to each transaction. The Ministry of Construction's certification mandates and State Bank of Vietnam's lending caps create divergent compliance burdens across property types and financing structures.
Property Type:
EDGE and LOTUS certification requirements from the Ministry of Construction apply unevenly across property categories, with residential and commercial segments facing the strictest environmental compliance timelines.
- Residential:High-density vertical developments dominate origination volume in Ho Chi Minh City and Hanoi. First-time buyers from the expanding middle class drive mortgage applications for condominiums and township units, with fixed-rate preference intensifying as the State Bank of Vietnam tightens lending caps.
- Commercial:Office towers and retail complexes carry higher loan-to-value thresholds but require extended feasibility studies. Solar rooftop mandates from the Ministry of Natural Resources and Environment are reshaping underwriting criteria for new commercial construction in Da Nang and Can Tho.
- Industrial:Logistics facilities around Hai Phong and Bac Ninh absorb accelerating construction finance demand.
- Agricultural:Land-use master plan restrictions limit greenfield conversion approvals.
Residential sits at the top of the volume ranking, with Industrial climbing the fastest.
Financing Type:
Cost tier differentiation separates mass-market accessible products from specialized construction instruments carrying staged disbursement risk.
- Fixed-rate:Twenty-year locked structures dominate consumer preference among young professionals in Hanoi seeking payment predictability. Banks are extending swap market participation to hedge liability exposure as demand concentrates in this category.
- Adjustable-rate:Shorter-tenor floating products retain niche appeal among speculative investors. Rate volatility tied to government bond yield movements constrains uptake in Binh Duong and Dong Nai corridor markets.
- Interest-only:Developer bridge financing relies on presale commitment thresholds.
- Construction loan:Multi-tranche facilities carry wider spreads reflecting staged disbursement mechanics.
Fixed-rate commands the deepest capital pool, with Construction loan gaining share fastest among developer pipelines.
Customer Segment:
Foreign ownership quota enforcement under the Housing Law creates a hard segmentation boundary between domestic-accessible and internationally restricted inventory.
- First-time buyers:Middle-class households priced out of Ho Chi Minh City's core are migrating to satellite corridors. Tech-enabled pre-approval platforms are compressing underwriting cycles for this informal-income-heavy segment.
- Real estate investors:Portfolio holders prioritize rental yield stability in transit-linked peripheries. Da Nang and Can Tho secondary markets attract yield-focused capital seeking lower entry points than primary metros.
- Foreign buyers:30% unit caps per condominium project constrain regional investor access.
- Developers:Vingroup and Dat Xanh Group anchor origination demand for construction facilities.
First-time buyers generate the highest transaction frequency, with Foreign buyers expanding most quickly within quota-permitted inventory.
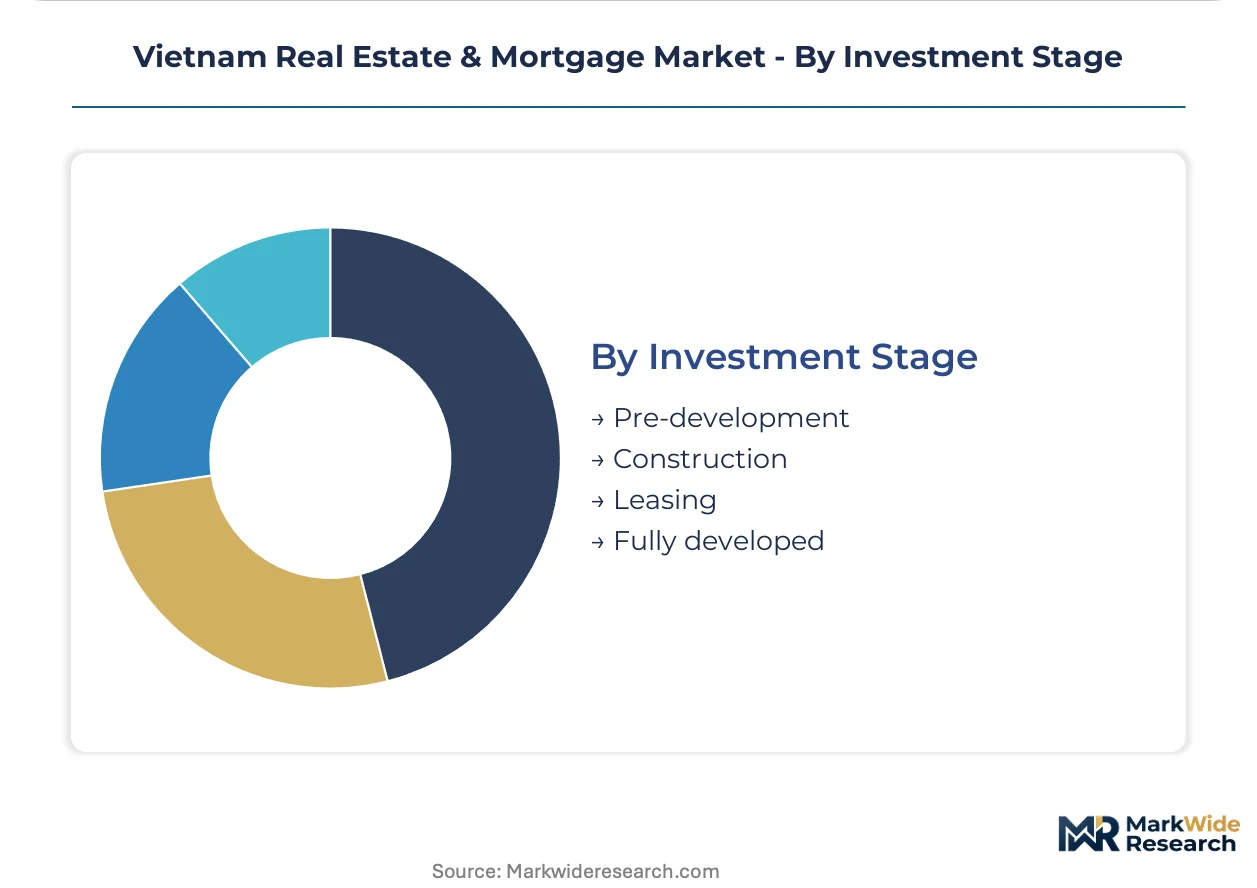
Investment Stage:
Maturity-based risk profiles determine which financing instruments match each development phase, from land acquisition through stabilized operation.
- Pre-development:Land compensation negotiations with collective holders extend timelines. The Ministry of Natural Resources and Environment's master plan constraints elevate site scarcity premiums in greenfield zones.
- Construction:Staged disbursement ties capital release to physical progress and presale rates. BIS certification delays for imported steel and cement widen project feasibility windows.
- Leasing:Income-producing assets attract institutional capital seeking yield stability.
- Fully developed:Stabilized properties collateralize long-term debt with lowest risk spreads.
Construction absorbs the dominant financing volume, with Leasing showing the steepest expansion trajectory among institutional portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across Southeast Asian property markets is redirecting developer capital toward jurisdictions with streamlined green certification pathways and relaxed foreign ownership frameworks. Vietnam's evolving Land Law revisions position it favorably against neighbors with more restrictive collective compensation mechanisms.
Ho Chi Minh City
First-time buyer demand from the expanding middle class concentrates mortgage origination in high-density vertical developments. The State Bank of Vietnam's lending caps compress liquidity timelines for non-certified projects while expanding quotas for green-rated inventory. The Thu Thiem New Urban Area and District 2 corridor absorb dominant financing flows as Vinhomes accelerates its integrated township rollout.
Hanoi
Young professionals prioritize twenty-year fixed-rate structures over adjustable alternatives, forcing banks to extend swap market participation for liability hedging. The Ministry of Construction's fire safety and environmental standards elevate compliance costs but unlock preferential financing terms for EDGE-certified projects. Long Bien and Gia Lam districts capture spillover demand from the constrained central districts.
Binh Duong Province
Transit-linked peripheries capture migration from buyers priced out of Ho Chi Minh City's core, accelerating residential absorption in Thu Dau Mot and Di An townships. Provincial urbanization policies align with the Ministry of Natural Resources and Environment's land-use master plans to streamline greenfield conversion approvals. Manufacturing FDI inflows from adjacent industrial zones sustain worker housing demand.
Hai Phong and Northern Port Provinces
Record industrial land absorption around deep-water ports accelerates construction finance demand for logistics facilities and accompanying worker housing clusters. The Ministry of Construction's building codes shape project feasibility timelines for manufacturing-integrated residential formats. Bac Ninh and Hung Yen provinces represent underpenetrated inventory for industrial-residential hybrid development.
Da Nang
Secondary market turnover accelerates as provincial land registries pilot blockchain-enabled land title verification to reduce dispute resolution timelines. Yield-focused institutional capital seeks lower entry points than primary metros, concentrating leasing activity in the Han River corridor. Solar rooftop mandates for commercial buildings reshape underwriting criteria for new construction.
Vietnam Real Estate & Mortgage Market Competitive Landscape
Backward integration into land banking and brokerage networks dominates the current landscape as developers seek margin capture across multiple transaction points. The market structure concentrates around vertically integrated conglomerates with captive construction arms, mid-scale specialists in provincial infill, and diversified holding groups with hospitality exposure. Three archetypes define competitive positioning: township-scale integrators controlling end-to-end timelines, brokerage-anchored developers leveraging transaction data for site selection, and compact-floorplate specialists navigating tighter zoning in southern provinces. M&A activity and green certification pre-positioning constitute the dominant competitive moves as liquidity conditions tighten.
Among Vietnamese developers, Vingroup exemplifies the integrated township archetype through its megaproject pipeline spanning Hanoi and Ho Chi Minh City corridors. Dat Xanh Group occupies a position representing brokerage-to-development backward integration, capturing margin at land acquisition and sales transaction points. Novaland Group sits within the compact residential specialist tier, focusing on mid-rise infill across southern provinces. These three anchors illustrate how scale, data access, and zoning agility respectively define viable competitive positions under current regulatory constraints.
| Leading Market Players |
|---|
| Vingroup |
| Dat Xanh Group |
| FLC Group |
| Novaland Group |
| Nam Long Investment Corporation |
| Hung Thinh Real Estate Business Investment Corporation |
| Sun Group |
| Phat Dat Corporation |
| JLL |
| Others |
Pricing and Supply Chain Analysis
Imported steel and cement certification costs cascade through construction loan spreads, compressing margins for non-certified developers while green-rated projects command preferential quota access from the State Bank of Vietnam. BIS compliance timelines extend project feasibility windows, forcing developers to sequence certification ahead of financing applications and pushing cost differentiation toward environmental compliance tiers.
Pricing Analysis
Developer-to-bank direct negotiations establish construction facility spreads, with green-certified projects accessing tighter pricing through State Bank of Vietnam priority lending directives. Price differentiation hinges on EDGE/LOTUS certification grade and presale commitment thresholds, with non-certified inventory facing widening spreads as liquidity conditions tighten. Pricing pressure intensifies in the mid-rise residential segment as presale dependency strains working capital timelines. First-time buyers in Binh Duong and Dong Nai corridors exhibit highest price sensitivity, while institutional leasing investors in Da Nang absorb premium pricing for yield stability.
Supply Chain Analysis
Direct-to-developer channels handle bulk material procurement for township-scale projects, bypassing distributor markups on steel and cement volumes. Supply concentrates in China, South Korea, and domestic Vietnamese production for construction-grade steel, with cement drawing from domestic kiln capacity and Thai imports. BIS certification requirements for imported materials create regulatory chokepoints, while logistics bottlenecks at northern ports constrain just-in-time delivery for Hai Phong industrial-residential hybrids. Distribution runs through captive construction arms for integrated developers like Vingroup, with independent developers relying on spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's real estate market operates as a regulatory compounder where State Bank of Vietnam green lending quotas and Ministry of Construction certification mandates continuously revalue inventory tiers. The Housing Law and Land Law revisions represent the pivotal regulatory milestone accelerating capital migration toward compliant, foreign-accessible projects.
For Market Incumbents: Cement township-scale integration advantages by accelerating EDGE pre-certification across Hanoi and Ho Chi Minh City pipelines before competing supply reaches market. Threaten margin compression from Dat Xanh Group's brokerage-data site selection by locking transit-linked land banks in Binh Duong and Dong Nai corridors. Priority lever: captive construction capacity to control staged disbursement timelines and reduce presale dependency risk. For New Entrants and Emerging Players: Digital mortgage origination platforms offer the lowest-friction entry vector, compressing underwriting cycles for informal-income first-time buyers underserved by incumbent banks. White-space targets cluster in Bac Ninh and Hung Yen industrial-residential hybrids, where manufacturing FDI sustains worker housing demand without competing against Vinhomes township scale. Go-to-market angle: AI-driven credit scoring partnerships with provincial banks seeking tech-enabled penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where brokerage networks control transaction data flow and land banking intelligence, making Dat Xanh Group-type backward integration models scarce acquisition targets. Long-term viability favors developers with certified inventory pipelines and foreign-ownership quota headroom. Acquisition archetype: mid-scale southern province specialists with compact floorplate zoning agility and green certification progress. Signal to watch: State Bank of Vietnam quota expansion for green-rated projects as inflection indicator for certified inventory premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Pre-Positioning | EDGE pre-certification unlocks State Bank of Vietnam preferential lending quotas ahead of competitors. |
| Industrial-Residential Hybrid Development | Worker housing integrated with Bac Ninh manufacturing zones captures rental yield plus land appreciation. |
| Digital Mortgage Platform Launch | AI-driven underwriting expands penetration among informal-income first-time buyers in satellite corridors. |
| Backward Integration into Land Banking | Brokerage transaction data enables predictive site selection and margin capture across acquisition and sales. |
| Renewable Energy Asset Integration | Solar rooftop mandates for commercial buildings create green bond financing eligibility for net-zero towers. |
Research Methodology
Coverage spans Vietnam's northern port provinces, central coastal corridors, and southern economic zone, with primary inputs from each region combined with secondary validation. Primary interviews engaged real estate development executives, State Bank of Vietnam lending officers, Ministry of Construction certification specialists, and industrial zone planning directors. Secondary sources incorporated Housing Law and Land Law draft provisions, Ministry of Natural Resources and Environment land-use master plans, and State Bank of Vietnam macroprudential circulars. Bottom-up project pipeline tracking and top-down credit flow analysis provided triangulation.
Rate-of-change decomposition separated volume growth from price tier shifts across the projection horizon. Segmentation dimensions modeled include property type, financing structure, customer segment, and investment stage, with provincial regulatory cluster as an additional industry-specific dimension. CAGRs derived from historical origination trends adjusted for policy intervention effects. Industry-specific forecast inputs encompassed manufacturing FDI absorption rates and green certification pipeline conversion timelines.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled land title verification would alter the outlook for secondary market turnover velocity. Forecasts reflect base-case assumptions regarding Housing Law foreign ownership quota maintenance and State Bank of Vietnam lending cap trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Spain Residential Real Estate Market
Real Estate
Warehouse Management Service Market
Real Estate
Saudi Arabia Real Estate Brokerage Market
Real Estate
Europe Residential Real Estate Market
Real Estate
Office Real Estate Market
Real Estate
Israel Commercial Real Estate Market
Real Estate
United Kingdom Office Real Estate Market
Real Estate
Asia Pacific REIT Market
Real Estate
Taiwan Facility Management Services Market
Real Estate
Brazil Facility Management Market
Real Estate
Europe Condominiums and Apartments Market
Real Estate
Japan Facility Management Market
Real Estate
Germany Self-Storage Market
Real Estate
United States Self Storage Market
Real Estate
Canada Condominiums and Apartments Market
Real Estate
US Property Management Software Market