
 Japan Facility Management Market | 2026-2036
Japan Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Facility Management Market Foresight
The gap between premium integrated FM contracts and commodity single-service agreements is expanding across Japan's facility management landscape. Sodexo Japan leverages its food services heritage to bundle catering with hard FM, creating stickier client relationships in corporate office towers. Secom Co., Ltd. anchors its position through proprietary security technology that feeds directly into building automation dashboards. Mitsui Fudosan Co., Ltd. differentiates by controlling both property ownership and in-house FM operations across its vast Tokyo portfolio.
Japan Facility Management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, groundskeeping) to ensure optimal building performance, occupant safety, and regulatory compliance across commercial and institutional assets. The discipline integrates CMMS Software platforms for work-order tracking and preventive scheduling, with leading deployments connecting HVAC sensors to centralized dashboards that flag degradation before system failure. Among service types, Maintenance Services commands the deepest margin pools due to specialized technician scarcity and long-term contractual lock-in, while Security Services faces technology-driven disruption as IoT Solutions and Automation Tools displace manned guarding in peripheral zones. Corporate Offices represent the most mature facility type, though Healthcare Facilities generate the fastest technology refresh cycles as infection control protocols and energy benchmarking tighten.
METI enforces building energy codes that compel facility operators to deploy Energy Management Systems and report consumption metrics, directly expanding the addressable market for technology-enabled FM providers. JIS standards for fire safety and earthquake resilience shape maintenance frequencies and contractor qualification requirements, creating barriers for unaccredited competitors. Stakeholders must weigh whether to build captive technical capabilities or deepen vendor partnerships as Japan's labor shortage intensifies and regulatory compliance grows more data-intensive.
Market Dynamics
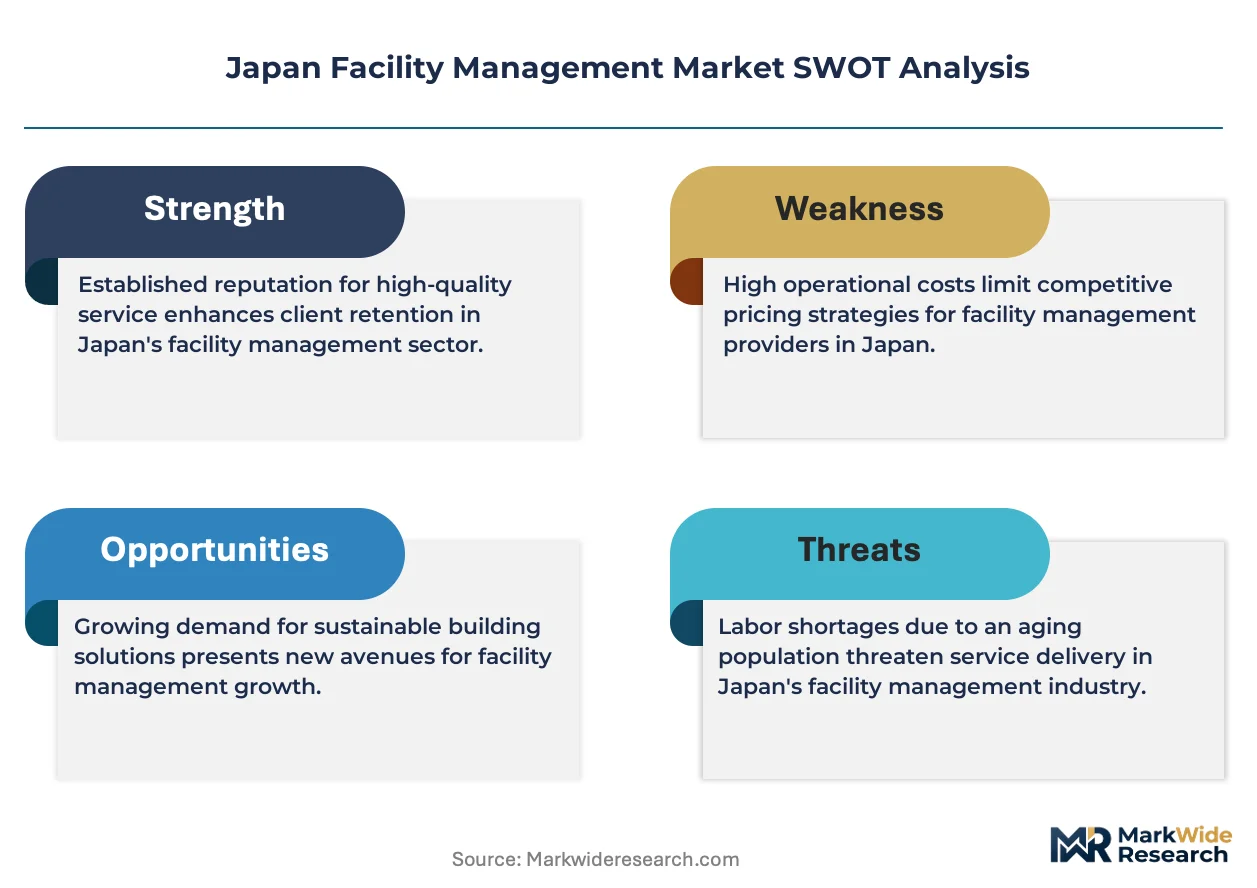
Japan's facility management sector faces a structural labor shortage that is compressing service delivery models and accelerating technology substitution across hard FM functions. METI's building energy efficiency mandates are simultaneously forcing capital deployment into building automation systems while narrowing the pool of qualified contractors capable of integrated delivery.
Growth Catalysts
- Healthcare outsourcing acceleration:Japanese hospitals are expanding non-core operations delegation to specialized FM providers as clinical staff shortages intensify and infection control protocols demand dedicated expertise.
- Energy Management Systems deployment:METI's consumption reporting requirements for commercial buildings above 3,000 square meters are creating mandatory upgrade cycles across Greater Tokyo's aging office stock.
- CMMS Software integration:Work-order tracking platforms connecting HVAC sensors to centralized dashboards are enabling predictive maintenance contracts that lock in multi-year client relationships.
Market Restraints
- Specialized technician scarcity:Japan's declining working-age population is constraining supply of certified mechanical and electrical maintenance engineers, inflating wage costs for skilled hard FM labor.
- Long regulatory approval cycles:JIS certification requirements for fire safety and earthquake resilience systems create 12-18 month barriers for new equipment vendors entering the maintenance services segment.
- IoT substitution of manned guarding:Perimeter security automation is compressing revenue pools in traditional security services as building operators redeploy guard budgets to sensor networks.
Strategic Opportunities
- Osaka-Kobe corridor expansion:Western Japan's commercial development is creating underserved demand for integrated FM contracts outside the saturated Greater Tokyo market.
- Healthcare technology refresh cycles:Infection control benchmarking and energy consumption mandates are accelerating equipment replacement timelines in hospitals and eldercare facilities.
- Building automation convergence:Integration of proprietary security feeds with HVAC and lighting control systems is enabling premium bundled service offerings that commodity providers cannot replicate.
Industry Challenges
- Legacy system integration complexity:Facility operators struggle to connect 1980s-era building management systems to modern IoT sensor networks without full infrastructure replacement.
- Certification timeline compression:METI's tightening energy codes are outpacing the training pipeline for auditors and retrofit specialists qualified to verify compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Facility Management Market |
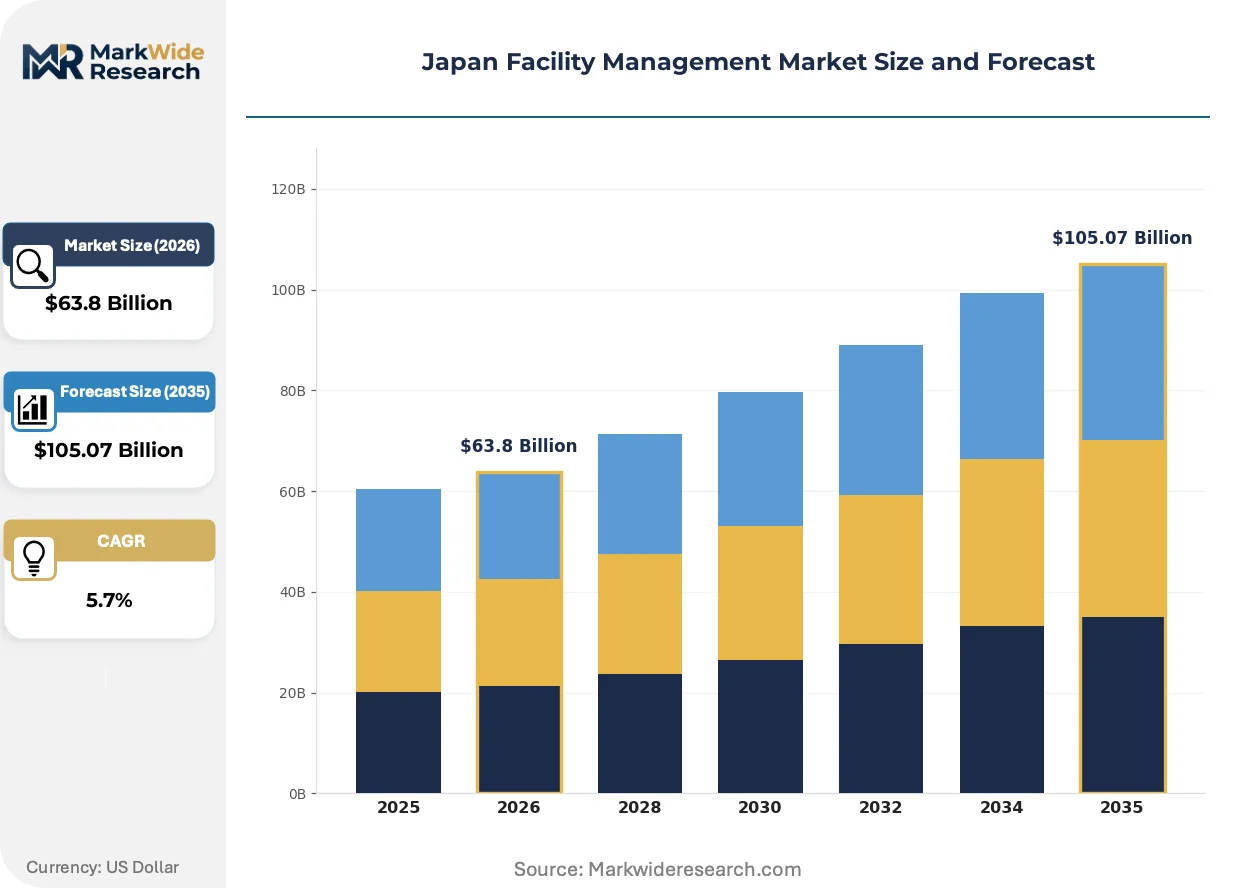
| Market Size in 2026 | $63.8 Billion |
| Market Size in 2035 | $105.07 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Landscaping, Maintenance Services End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Industrial Plants Technology: CMMS Software, IoT Solutions, Energy Management Systems, Automation Tools Facility Type: Residential Complexes, Corporate Offices, Retail Spaces, Warehouses |
| Companies Covered | Sodexo Japan, Secom Co., Ltd., ISS Facility Services Japan, Mitsui Fudosan Co., Ltd., Tokyu Community Corporation, JLL Japan, Cushman & Wakefield Japan, NTT Facilities, Inc., CBRE Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Facility Management Market Shifts & Advancements
Technology convergence and regulatory data mandates are restructuring how Japanese facility operators procure and manage building services. The sector is moving from reactive maintenance schedules toward sensor-driven predictive models that tie contractor compensation to measurable performance outcomes.
Building automation platforms are absorbing standalone security, HVAC, and lighting control functions into unified dashboards. Corporate office towers in Minato and Chiyoda wards are deploying these systems fastest, with landlords capturing energy savings through performance-guaranteed FM contracts that shift operational risk to service providers.
METI's building energy codes now require consumption reporting for commercial assets above 3,000 square meters. This mandate is expanding addressable demand for technology-enabled FM providers capable of continuous monitoring and automated compliance documentation, particularly among mid-size office buildings that previously managed energy ad hoc.
Integrated service contracts are displacing single-service agreements as the preferred procurement model for premium commercial assets. Healthcare facilities in Kanagawa and Saitama prefectures are leading this transition, bundling hard FM, soft services, and technology management under unified vendor relationships that reduce coordination overhead and clarify accountability.
Japan Facility Management Market Segmentation
Procurement patterns across Japan's facility management sector diverge sharply by certification burden and regulatory exposure. Segmentation reveals which service categories absorb JIS compliance costs and which technology tiers command premium pricing from METI-mandated building operators.
Service Type:
JIS fire safety and earthquake resilience certifications create 12-18 month approval barriers that concentrate market power among established maintenance and security contractors.
- Maintenance Services:Hard FM functions encompassing mechanical, electrical, and plumbing systems require certified technician credentials that Japan's shrinking workforce struggles to supply. Demand concentrates in Greater Tokyo's aging commercial towers where landlords face METI-mandated energy retrofit deadlines without in-house technical depth.
- Security Services:Manned guarding and perimeter protection face technology substitution as IoT sensors displace human presence in peripheral zones. Corporate office towers in Minato and Chiyoda wards are deploying integrated automation fastest, compressing traditional revenue pools while expanding demand for cyber-physical system management.
- Cleaning Services:Infection control protocols in healthcare and eldercare facilities now specify chemical certification and airflow management beyond basic janitorial functions.
- Landscaping:Grounds maintenance contracts attach primarily to corporate campuses and residential complexes with aesthetic positioning requirements.
Leading the category by volume: Maintenance Services. Growing fastest: Security Services technology integration.
End User:
Regulatory intensity varies by facility type, with healthcare and industrial plants facing the deepest audit and reporting obligations.
- Healthcare Facilities:Japanese hospitals and eldercare operators outsource non-core operations as clinical staff shortages intensify. Kanagawa and Saitama prefectures lead bundled procurement combining hard FM, soft services, and infection control technology under unified vendor relationships.
- Industrial Plants:Manufacturing facilities require specialized hazardous materials handling and equipment-specific maintenance protocols that generalist providers cannot replicate.
- Commercial Buildings:METI energy reporting mandates for assets above 3,000 square meters drive CMMS and sensor deployment across Greater Tokyo's aging stock.
- Educational Institutions:Public sector procurement favors established contractors with JIS certification histories and multi-site management capability.
Deepest margin pool: Healthcare Facilities. Steepest expansion trajectory: Commercial Buildings automation retrofit.
Technology:
Capital deployment into building automation separates premium integrated providers from commodity single-service competitors.
- Energy Management Systems:Continuous monitoring platforms for consumption tracking and automated compliance documentation. METI reporting requirements for commercial buildings above 3,000 square meters create mandatory upgrade cycles across mid-size office properties that previously managed energy ad hoc.
- CMMS Software:Work-order tracking and preventive scheduling platforms connecting HVAC sensors to centralized dashboards. Predictive maintenance contracts lock in multi-year client relationships by flagging system degradation before failure.
- IoT Solutions:Sensor networks for occupancy, air quality, and equipment performance monitoring that feed unified building automation dashboards.
- Automation Tools:Control systems integrating HVAC, lighting, and security functions into single-operator interfaces.
Highest deployment rate: Energy Management Systems. Fastest technology refresh: CMMS Software predictive modules.
Facility Type:
Asset age and ownership structure determine procurement sophistication, with institutional landlords driving integrated contract adoption.
- Corporate Offices:Premium towers in Tokyo's central wards deploy unified automation platforms fastest, with landlords capturing energy savings through performance-guaranteed FM contracts that shift operational risk to service providers.
- Warehouses:Logistics facilities prioritize security automation and energy efficiency for climate-controlled storage, with peripheral location cost pressures accelerating IoT substitution of manned guarding.
- Retail Spaces:Consumer-facing properties balance aesthetic maintenance requirements with foot-traffic-driven cleaning frequencies.
- Residential Complexes:Multi-unit buildings concentrate demand for bundled soft services with limited hard FM technical complexity.
Most mature procurement: Corporate Offices. Fastest automation adoption: Warehouses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Tokyo dominates Japan's facility management activity, with Minato and Chiyoda wards hosting the densest concentration of premium integrated contracts and building automation deployments.
Kanto/Tokyo
Corporate office towers and healthcare complexes drive demand for bundled hard FM, soft services, and technology management. METI's energy reporting mandates for buildings above 3,000 square meters accelerate CMMS and sensor deployment across aging commercial stock in central wards.
Kansai/Osaka
The Osaka-Kobe corridor presents expansion opportunities as commercial development creates underserved demand outside saturated Tokyo markets. Industrial facilities and logistics warehouses prioritize security automation and climate-controlled storage energy efficiency.
Chubu/Nagoya
Manufacturing-heavy industrial plants require specialized hazardous materials handling and equipment-specific maintenance protocols. Automotive and precision machinery clusters concentrate demand for certified mechanical and electrical maintenance engineers.
Kyushu
Semiconductor and electronics manufacturing facilities anchor hard FM demand with stringent cleanroom and infection control requirements. Regional hospitals and eldercare operators increasingly outsource non-core operations amid clinical staff shortages.
Hokkaido
Tourism and hospitality properties concentrate soft services procurement, while cold-chain logistics facilities drive energy management system investments. Remote location cost pressures accelerate IoT substitution of manned guarding in peripheral security zones.
Japan Facility Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and technology integration capabilities. The market structures around three tiers: integrated providers bundling hard and soft services with proprietary automation platforms, specialized contractors holding JIS certifications for fire safety and earthquake resilience systems, and single-service operators competing on price for standardized cleaning and landscaping. Dominant competitive moves include vertical integration of property ownership with in-house FM operations and strategic partnerships connecting CMMS vendors with legacy building management system installers.
Within the integrated services tier, Sodexo Japan leverages food services heritage to anchor bundled corporate contracts, while Secom Co., Ltd. exemplifies technology-driven differentiation through proprietary security feeds feeding building automation dashboards. Mitsui Fudosan Co., Ltd. represents the property-owner-integrator archetype controlling both asset ownership and captive FM operations across vast Tokyo portfolios.
| Leading Market Players |
|---|
| Sodexo Japan |
| Secom Co., Ltd. |
| ISS Facility Services Japan |
| Mitsui Fudosan Co., Ltd. |
| Tokyu Community Corporation |
| JLL Japan |
| Cushman & Wakefield Japan |
| NTT Facilities, Inc. |
| CBRE Group |
| Others |
Supply & Pricing Matrix
Certification-ladder divergence between JIS-accredited integrated providers and unqualified commodity operators manifests in both pricing power and supplier network configuration across Japan's facility management sector. Premium contracts in Tokyo's Minato and Chiyoda wards command substantial uplifts over standardized agreements, while METI-mandated energy compliance costs filter through to mid-size building operators lacking captive technical depth.
Pricing Analysis
Outcome-based pricing tied to energy savings guarantees anchors contract structures for premium integrated FM providers serving Greater Tokyo's corporate office towers. Three-tier pricing stratification separates JIS-certified maintenance specialists from technology-enabled automation vendors and price-competitive single-service cleaners. Cost compression in commodity cleaning and landscaping intensifies as labor scarcity inflates wage bills without corresponding value-add differentiation. Healthcare facilities demonstrate lowest price sensitivity given infection control liability exposure, while retail landlords in peripheral wards exhibit highest sensitivity to soft service costs.
Supply Chain Analysis
Regional distribution centers in Osaka and Nagoya feed hub-and-spoke patterns supporting technician deployment across western and central Japan. Component supply draws from domestic electrical and HVAC equipment manufacturers alongside sensor and automation technology imports from Taiwan and South Korea. Single-source vulnerability concentrates in proprietary building automation software and specialized cleanroom filtration systems. Distribution runs through direct vendor relationships with major property developers and tiered subcontractor networks serving fragmented mid-size building owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's facility management market operates as a supply-constrained environment where certified technician scarcity props pricing for qualified providers. Labor pipeline limitations and METI's accelerating compliance timelines create durable capacity bottlenecks protecting incumbent margins.
For Market Incumbents: Anchor market position through captive training pipelines addressing JIS certification backlogs while deepening technology integration partnerships. Threat from IoT-enabled security automation demands defensive investment in unified building automation platforms beyond traditional service boundaries. Priority lever rests with backward integration into CMMS software development to lock client switching costs.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in healthcare facility management offers white-space entry for specialized infection control providers bundling hard FM with clinical environment expertise. Osaka-Kobe corridor commercial development presents underserved demand outside Tokyo's saturated procurement landscape. Go-to-market angle should emphasize performance-guaranteed energy savings contracts capturing METI compliance urgency among mid-size building operators.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-enabled integrated providers given METI's mandatory consumption reporting expansion across the analysis window. Long-term viability favors platforms combining proprietary automation with JIS certification depth rather than pure-play labor arbitrage models. Signal to watch is consolidation velocity among mid-tier maintenance contractors facing technician recruitment failure.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMS Platform Integration | Unifies work-order tracking with predictive HVAC maintenance for multi-year contract lock-in. |
| JIS Certification Investment | Accelerates fire safety and earthquake resilience approval timelines for competitive bidding eligibility. |
| Healthcare Bundle Expansion | Captures infection control outsourcing acceleration in Kanagawa and Saitama prefecture hospitals. |
| Energy Management System Deployment | Addresses METI mandatory reporting for commercial buildings above 3,000 square meters. |
| Osaka-Kobe Corridor Market Entry | Targets underserved integrated FM demand in western Japan's commercial development pipeline. |
Research Methodology
Independent corroboration across facility management executives, property developer procurement leads, JIS certification auditors, and METI policy specialists underwrites the qualitative findings in this study. Primary interviews with maintenance directors at Tokyo commercial towers, healthcare facility operations managers, and building automation integration specialists combined with secondary validation from METI energy consumption disclosures, JIS standards documentation, and prefecture-level building stock databases. Bottom-up service provider revenue analysis and top-down building automation deployment estimates were triangulated to establish market sizing boundaries.
Comparable-period anchoring to historical CMMS adoption curves and energy retrofit completion rates structured the forecast window across the projection horizon. Segmentation dimensions modeled include service type certification tier, end-user regulatory exposure intensity, technology deployment complexity, and facility ownership structure. CAGRs were derived from technician supply constraints, METI mandate phase-in schedules, and healthcare outsourcing penetration patterns. Forecast inputs incorporated building age distribution across Greater Tokyo and automation substitution elasticity in security services.
Inputs from JIS certification bodies and METI compliance databases were available through the study window; gaps in proprietary CMMS utilization metrics and subcontractor pricing transparency introduce uncertainty bands around technology penetration estimates. Forecasts reflect documented assumptions regarding labor force participation trends and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Sweden Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Bulgaria Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Philippines Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
New Zealand Facility Management Market