
 Warehouse Management Service Market | 2026-2036
Warehouse Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Management Service Market Insights
Germany's industrial logistics corridor is fragmenting as legacy warehouse operators split technology procurement between established platforms and specialized cloud entrants. Manhattan Associates dominates North American enterprise installations with deep retail specialization. SAP EWM leverages its ERP integration backbone to anchor complex manufacturing environments. Softeon competes through configurable fulfillment engines that serve mid-market third-party logistics providers.
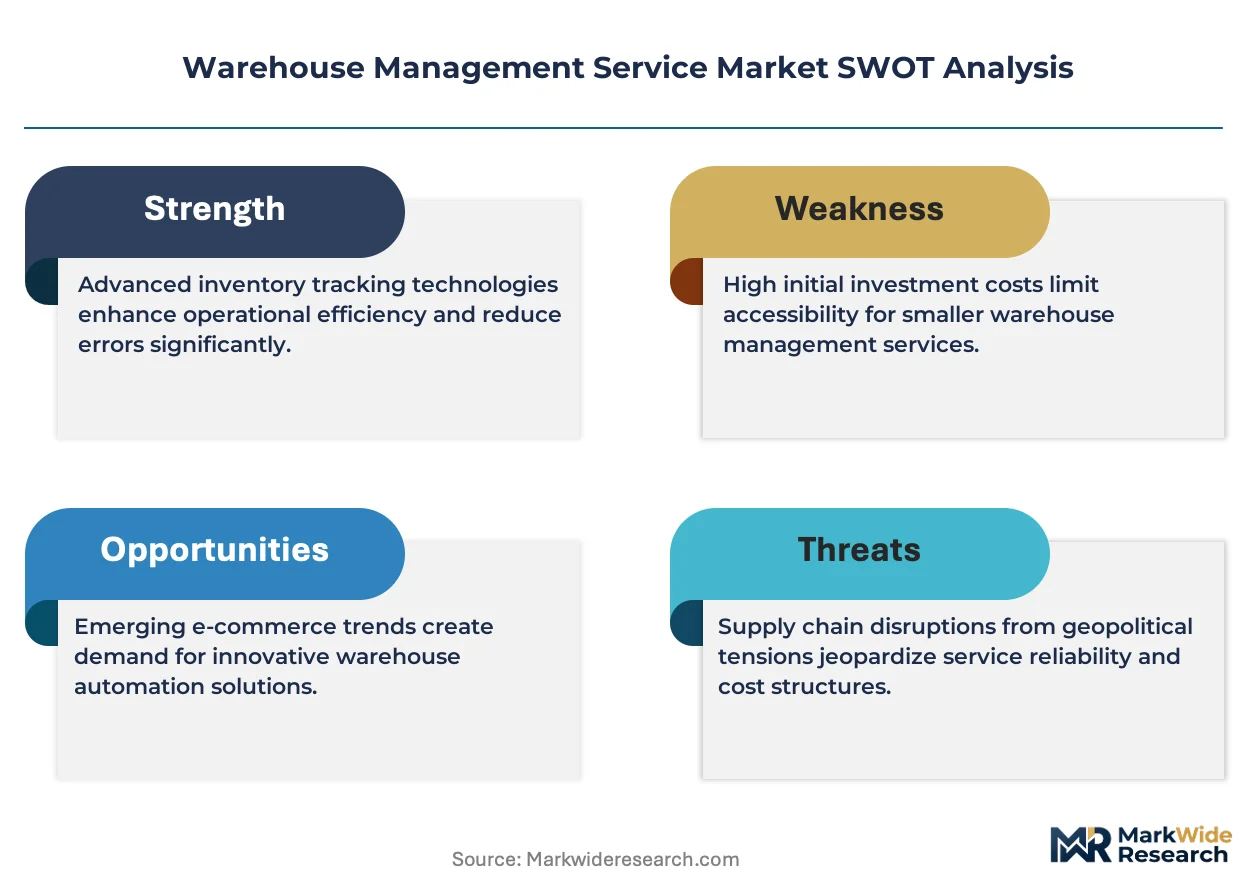
Warehouse management service denotes the outsourced design, deployment, and operation of software systems that coordinate inventory placement, order picking, labor allocation, and shipping execution across distribution facilities, typically integrating real-time data capture through barcode scanning and RFID protocols to maintain stock accuracy above 99.5%. Cloud-based deployment leads in new installations because capital-constrained operators prefer subscription models over perpetual license commitments. Managed services represents the fastest-expanding category as e-commerce fulfillment networks outsource platform maintenance and peak-season capacity scaling to vendors rather than building internal DevOps teams. Inventory management and order fulfillment together occupy the largest margin pools within the solution layer, since labor optimization algorithms command premium pricing when tied to guaranteed throughput improvements.
FDA traceability requirements for pharmaceutical distribution, EU GDPR constraints on customer data handling, and OSHA warehouse safety mandates collectively shape platform architecture by mandating audit trails, access controls, and incident documentation that WMS vendors must embed natively. The EU AI Act adds algorithmic transparency obligations for automated picking and routing systems deployed in European facilities. Stakeholders must decide whether to consolidate vendor relationships around full-suite providers or maintain multi-platform environments that segment regulatory exposure by geography.
Market Dynamics
Omnichannel fulfillment networks are fragmenting technology procurement decisions as warehouse operators split capital between established platforms and specialized cloud entrants to manage peak-season volatility without building permanent DevOps capacity.
Growth Catalysts
- EU AI Act Algorithmic Transparency:European facilities must embed explainability into automated picking and routing systems, accelerating replacement of black-box legacy platforms with auditable cloud architectures that natively document decision trails.
- Pharmaceutical Cold Chain Traceability:FDA mandates for pharmaceutical distribution require lot-level tracking from manufacturer to patient, forcing warehouse operators to deploy sensor-integrated WMS modules that maintain continuous temperature and location records.
- Stuttgart-Hamburg Industrial Corridor:Germany's automotive and precision manufacturing clusters are driving advanced WMS deployments with deep ERP integration to coordinate just-in-sequence parts delivery across multi-tier supplier networks.
Market Restraints
- GDPR Data Localization Costs:EU operators face structural cost penalties when selecting non-European cloud infrastructure, as customer order data and workforce performance metrics must remain within jurisdictional boundaries.
- RFID Hardware Supply Concentration:UHF tag and reader manufacturing concentrates in East Asian foundries, exposing European and North American warehouse operators to input cost volatility and extended procurement lead times.
- Legacy System Technical Debt:Perpetual-license WMS installations from the 2010s lack API-native architectures, creating integration friction with modern robotics orchestration layers and real-time visibility platforms.
Strategic Opportunities
- Third-Party Logistics Managed Services:Capital-constrained 3PL providers represent underpenetrated demand for subscription-based platform operation, allowing vendors to capture recurring revenue from seasonal fulfillment networks.
- Warehouse Robotics Convergence:Integration of autonomous mobile robots with WMS-directed put-away algorithms creates white space for vendors offering unified control planes that coordinate human and machine labor allocation.
- OSHA Safety Mandate Embedded Compliance:Incident documentation and ergonomic monitoring requirements create regulatory tailwind for platforms offering native safety module subscriptions that automate OSHA reporting workflows.
Industry Challenges
- DevOps Talent Scarcity:Warehouse operators lack internal capability to maintain cloud-native platform configurations, forcing reliance on vendor-managed services that compress operational autonomy.
- Multi-Platform Integration Complexity:Operators segmenting regulatory exposure by geography must orchestrate data flows between region-specific WMS instances, multiplying interface maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Management Service Market |
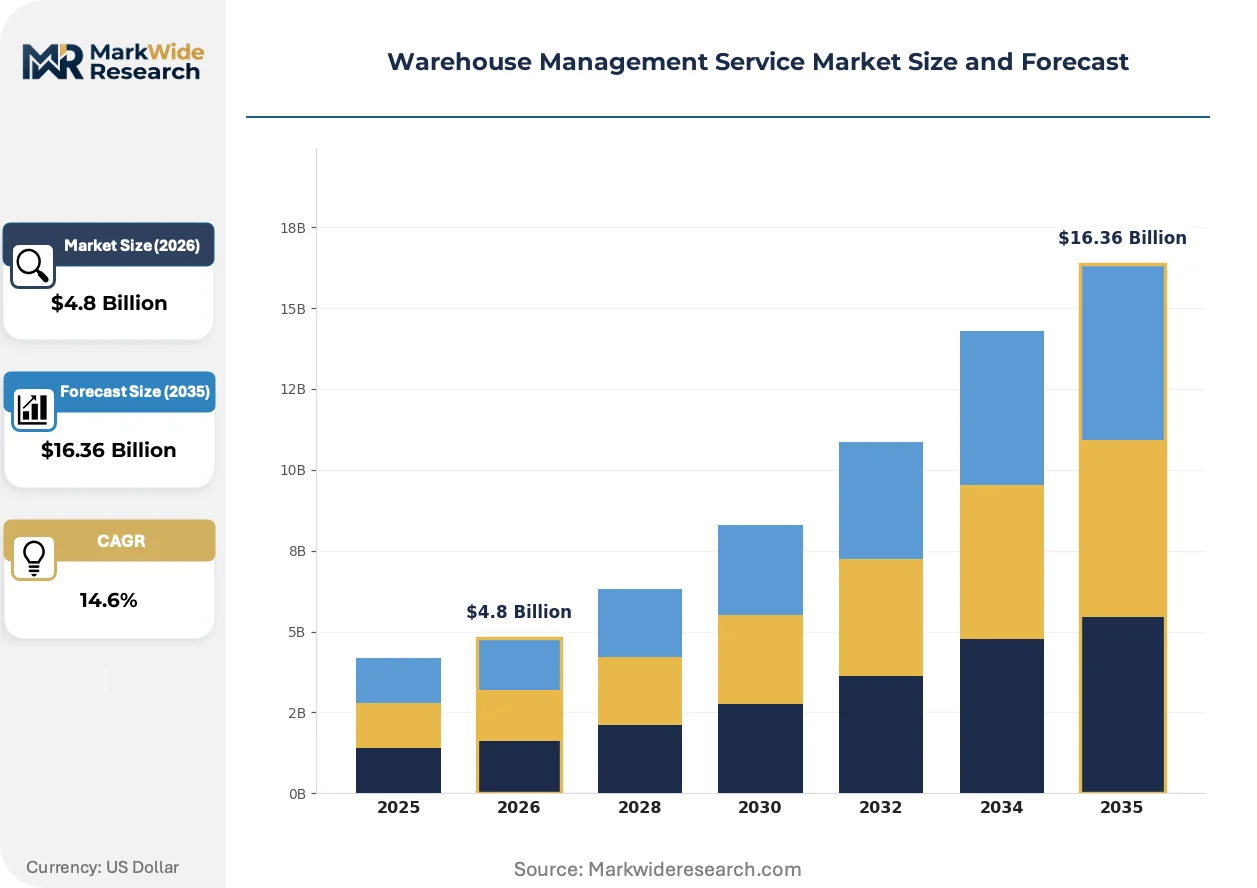
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud-Based, On-Premises, Hybrid, Managed Services Solution: Inventory Management, Order Fulfillment, Labor Management, Transportation Management End User: E-Commerce, Retail, Manufacturing, Third-Party Logistics Technology: RFID, Barcode Scanning, IoT, Artificial Intelligence |
| Companies Covered | SAP EWM, Infor WMS, Manhattan Associates, Logiwa WMS, Softeon, Blue Yonder, Oracle WMS, Tecsys, Infios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Management Service Market Trends and Innovations
Cloud-native architectures are compressing deployment timelines from months to weeks while embedding compliance functionality that previously required separate governance layers.
Computer vision systems for real-time inventory verification are rendering obsolete manual cycle-counting procedures and fixed-position barcode scanning infrastructure. Mid-market 3PL providers in Germany and the Netherlands are adopting camera-based dimensioning and damage detection at pilot scale. The technology is rendering obsolete labor-intensive quality assurance stations that previously bottlenecked outbound shipping lanes.
REACH chemical traceability requirements are forcing European warehouse operators to document storage conditions for hazardous materials across their entire facility footprint. WMS vendors must now embed substance registry integration and automated segregation rule enforcement to prevent incompatible chemical co-location. Pharmaceutical and specialty chemical distributors in the Benelux region are prioritizing platforms with pre-certified REACH compliance modules.
Subscription pricing for warehouse management functionality is displacing perpetual license commitments among capital-constrained operators. Third-party logistics providers facing e-commerce volume unpredictability prefer usage-scaled SaaS contracts that align technology costs with actual shipment throughput. This procurement model shift is most visible in Germany's mid-market logistics sector, where private-equity-backed 3PL rollups standardize on cloud platforms to accelerate portfolio integration timelines.
Warehouse Management Service Market Segmentation
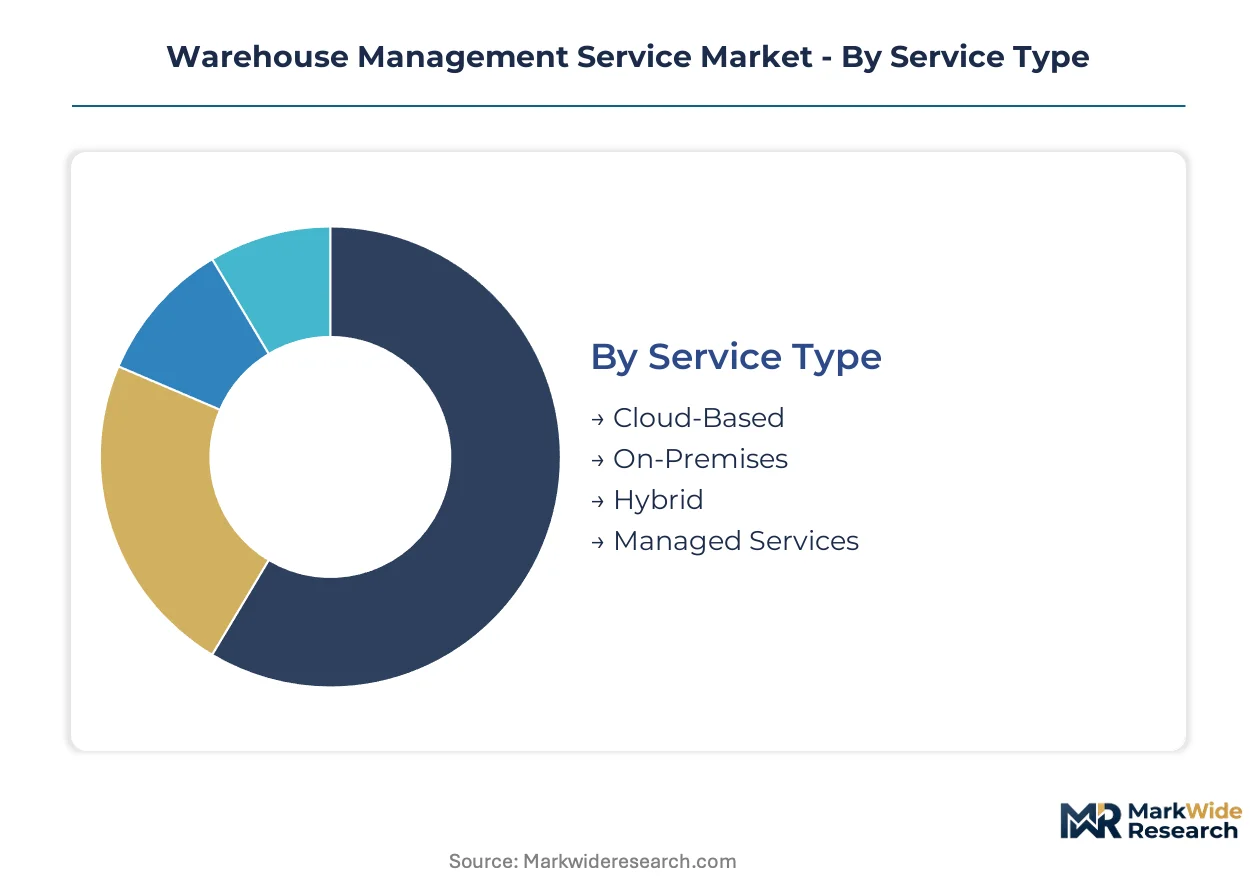
Warehouse management service procurement splits across four critical dimensions that determine platform architecture, compliance burden, and operational control. Service type dictates capital structure and vendor dependency. Solution modules align with margin concentration in labor optimization and inventory accuracy. End-user verticals impose divergent throughput requirements and regulatory obligations. Technology integration separates legacy operators from cloud-native entrants.
Service Type:
Deployment models span from full capital ownership to complete vendor-operated environments, with procurement decisions hinging on DevOps capability and seasonal volume volatility.
- Cloud-Based:Multi-tenant SaaS architectures with API-native integration layers enable rapid deployment without infrastructure capital. German mid-market 3PL providers favor subscription models that align technology costs with actual shipment throughput during peak e-commerce seasons.
- Managed Services:Vendors assume full platform operation including maintenance, updates, and peak-season capacity scaling. Third-party logistics providers facing unpredictable volume patterns outsource DevOps functions entirely to preserve operational flexibility and compress fixed cost structures.
- On-Premises:Perpetual-license installations with dedicated hardware stacks persist in defense and pharmaceutical facilities with strict data sovereignty requirements.
- Hybrid:Split deployments maintaining sensitive inventory data on local servers while leveraging cloud analytics for demand forecasting and labor optimization.
The dominant share belongs to Cloud-Based deployments, while Managed Services is closing the gap fastest.
Solution:
Functional modules compete for procurement priority based on guaranteed ROI metrics and regulatory documentation requirements.
- Inventory Management:Real-time stock positioning algorithms with lot-level traceability and automated cycle-counting verification. Pharmaceutical distributors in the Benelux region prioritize platforms with FDA-compliant audit trails for cold chain documentation.
- Order Fulfillment:Wave planning, pick-path optimization, and shipping execution coordination with guaranteed throughput improvements. E-commerce networks demand fulfillment engines that orchestrate same-day delivery promises across fragmented warehouse footprints.
- Labor Management:Workforce scheduling, performance tracking, and ergonomic monitoring modules that automate OSHA incident documentation.
- Transportation Management:Carrier selection, load building, and outbound shipment visibility with embedded freight cost allocation.
Inventory Management commands the largest installed base, though Order Fulfillment is expanding most quickly as omnichannel complexity intensifies.
End User:
Vertical-specific throughput patterns and compliance obligations shape platform configuration requirements and vendor selection criteria.
- Third-Party Logistics:Multi-tenant environments serving fragmented client portfolios with divergent SLA requirements and seasonal spikes. Private-equity-backed 3PL rollups in Germany standardize on unified cloud platforms to accelerate post-acquisition integration timelines.
- Manufacturing:Deep ERP integration for just-in-sequence parts coordination across multi-tier supplier networks. Stuttgart automotive clusters drive deployments with embedded production line synchronization capabilities.
- E-Commerce:Returns processing, same-day fulfillment, and dynamic slotting algorithms for unpredictable SKU velocity patterns.
- Retail:Store fulfillment, ship-from-store, and buy-online-pickup-in-store orchestration across distributed store networks.
Third-Party Logistics anchors current demand, while Manufacturing is gaining share fastest through automotive supply chain digitization.
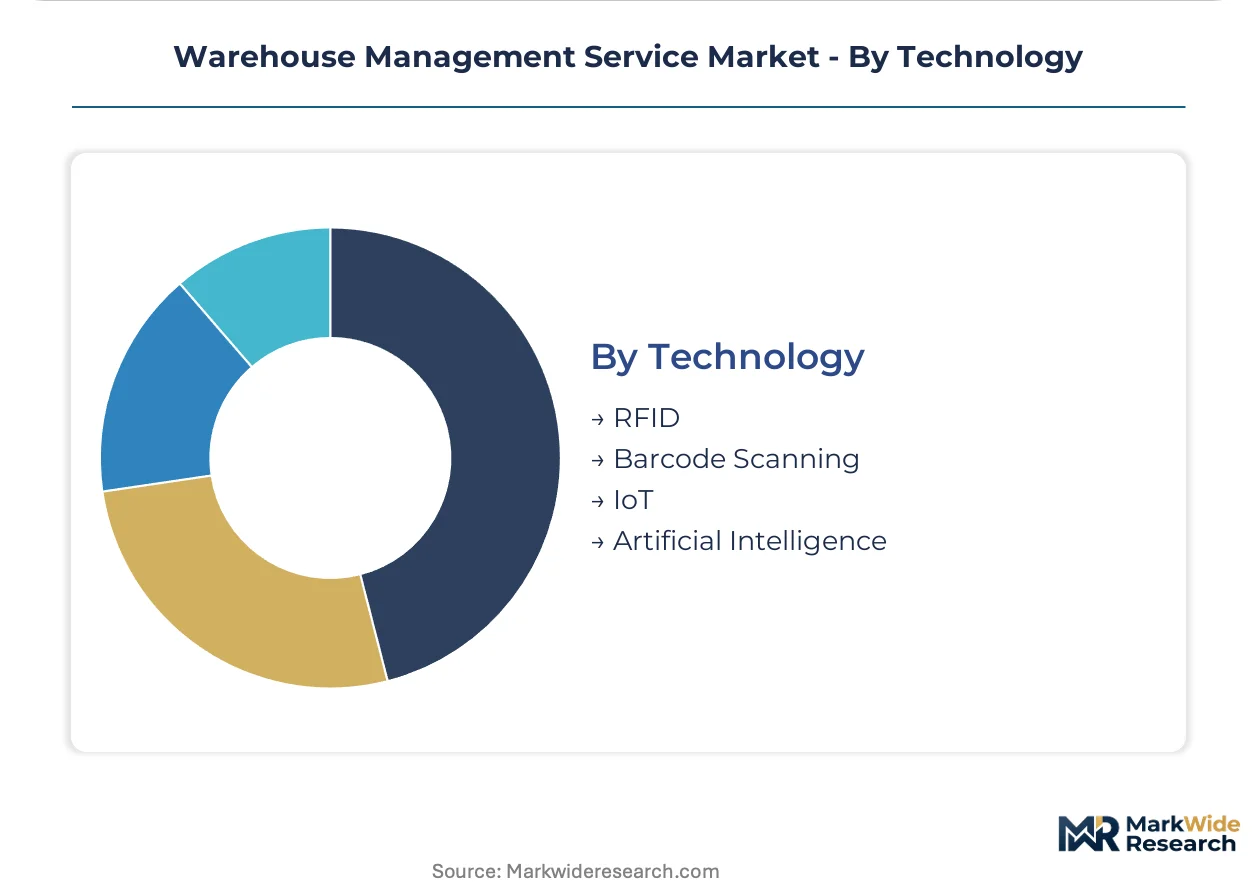
Technology:
Data capture and decision automation layers determine stock accuracy thresholds and labor substitution potential.
- Artificial Intelligence:Predictive demand forecasting, dynamic slotting optimization, and automated picking path generation with embedded EU AI Act explainability requirements. European facilities must document algorithmic decision trails for automated routing systems.
- RFID:UHF tag-based inventory verification with bulk reading capabilities for pallet-level tracking without line-of-sight constraints. Pharmaceutical cold chain operators deploy sensor-integrated tags for continuous temperature monitoring.
- Barcode Scanning:Fixed-position and mobile laser scanning infrastructure for discrete item verification and shipping documentation.
- IoT:Sensor networks for environmental monitoring, equipment predictive maintenance, and real-time location tracking of mobile assets.
Barcode Scanning retains the broadest installed footprint, yet Artificial Intelligence shows the steepest expansion trajectory as algorithmic transparency mandates reshape European procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act anchor European procurement patterns, while FDA traceability mandates reshape North American pharmaceutical distribution networks. Cloud-based platform adoption concentrates in industrial corridors with dense third-party logistics activity.
Germany
Automotive just-in-sequence supply chains and pharmaceutical cold chain distribution drive advanced WMS deployments. The EU AI Act mandates algorithmic transparency for automated picking systems in Stuttgart and Hamburg facilities. Industrial clusters around Baden-Württemberg anchor ERP-integrated warehouse operations serving multi-tier supplier networks.
United States
E-commerce fulfillment volatility and omnichannel retail complexity push operators toward managed service models. FDA pharmaceutical traceability requirements force lot-level tracking infrastructure from manufacturer to patient. Distribution gravity concentrates in Chicago, Dallas-Fort Worth, and Southern California inland empire corridors.
United Kingdom
Post-Brexit customs documentation and cross-border fulfillment friction elevate demand for compliance-embedded platforms. GDPR data localization obligations constrain cloud infrastructure selection for customer order processing. Midlands logistics hubs around Birmingham and Leicester drive mid-market 3PL standardization on subscription-based systems.
Netherlands
Rotterdam-Europoort port logistics and Benelux pharmaceutical distribution create dense WMS deployment activity. REACH chemical traceability mandates require substance registry integration for hazardous materials storage. Randstad logistics operators prioritize platforms with pre-certified compliance modules for specialty chemical handling.
China
Domestic e-commerce volume scale and manufacturing export fulfillment drive warehouse automation investment. SAMR data governance requirements shape cloud platform architecture for consumer goods distribution. Yangtze River Delta clusters around Shanghai and Suzhou anchor robotics-integrated fulfillment center deployments.
Warehouse Management Service Market Competitive Landscape
Enterprise-suite incumbents and cloud-native specialists split the market along deployment-model lines. Manhattan Associates dominates North American retail installations with deep omnichannel specialization. SAP EWM leverages ERP integration backbones to anchor complex manufacturing environments. Softeon competes through configurable fulfillment engines serving mid-market third-party logistics providers. Consolidation pressure intensifies as vendors acquire robotics orchestration capabilities and vertical-specific compliance modules.
Within the enterprise-suite tier, SAP EWM and Oracle WMS represent the ERP-anchored archetype, while Manhattan Associates exemplifies retail-specialized platform depth. Cloud-native entrants including Softeon occupy positions serving capital-constrained operators seeking subscription flexibility. Blue Yonder and Infor WMS sit within the supply-chain-suite category, competing on unified planning-execution integration. These six companies collectively span the strategic archetypes reshaping procurement decisions across pharmaceutical, automotive, and e-commerce verticals.
| Leading Market Players |
|---|
| SAP EWM |
| Infor WMS |
| Manhattan Associates |
| Logiwa WMS |
| Softeon |
| Blue Yonder |
| Oracle WMS |
| Tecsys |
| Infios |
| Others |
Pricing and Supply Chain Analysis
East Asian RFID hardware concentration creates dual exposure for European and North American warehouse operators, compressing margin spreads between premium cloud-native platforms and legacy perpetual-license tiers while forcing procurement teams toward extended inventory positions on UHF tags and readers.
Pricing Analysis
German mid-market 3PL providers pay subscription premiums 15-25% above Benelux counterparts due to EU AI Act compliance embedding costs. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and regulatory certification tier. Pricing pressure stems from private-equity-backed 3PL rollups demanding usage-scaled SaaS contracts that align technology costs with shipment throughput. Capital-constrained operators show highest price sensitivity; pharmaceutical cold chain distributors with FDA traceability mandates show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations as vendors compete for 3PL managed services contracts. Hardware manufacturing concentrates in China, South Korea, and Taiwan for UHF RFID tags, readers, and sensor modules. Component dependencies include semiconductor chips for IoT gateways, lithium cells for cold chain sensors, and precision optics for computer vision systems. Single-source vulnerability runs through East Asian foundry concentration for UHF tag production. Distribution runs through systems integrators and direct vendor relationships with large enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as EU AI Act compliance requirements and FDA traceability mandates create switching costs that lock warehouse operators into certified platform ecosystems.
For Market Incumbents: Harden platform architectures against algorithmic transparency audits mandated by the EU AI Act, embedding native decision-trail documentation that emerging cloud entrants lack. Deepen ERP integration backbones serving Stuttgart automotive clusters to increase replacement friction. Acquire robotics orchestration capabilities before specialized AMR vendors consolidate warehouse automation layers. For New Entrants and Emerging Players: Pursue white-space opportunity in mid-market 3PL managed services, where capital constraints and DevOps talent scarcity create procurement urgency. Benelux pharmaceutical distributors with REACH chemical traceability requirements represent underpenetrated demand for pre-certified compliance modules. Lead with subscription pricing that aligns technology costs with seasonal shipment throughput. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vendors with embedded regulatory compliance and unified robotics control planes. Long-term viability hinges on capturing recurring revenue from managed services rather than perpetual license transitions. Watch for FDA traceability mandate expansion into medical device distribution as inflection signal for cold chain WMS demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Module Development | EU AI Act algorithmic transparency requirements force native audit-trail embedding for European facilities. |
| Robotics Orchestration Acquisition | Unified control planes coordinating human and AMR labor allocation command premium positioning in fulfillment networks. |
| Managed Services Subscription Expansion | Private-equity-backed 3PL rollups standardize on vendor-operated platforms to compress fixed cost structures. |
| ERP Integration Backbone Deepening | Stuttgart automotive clusters demand just-in-sequence synchronization across multi-tier supplier networks. |
| REACH Pre-Certification Investment | Benelux chemical distributors prioritize platforms with substance registry integration for hazardous materials storage. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse operations directors, 3PL procurement leads, WMS platform engineers, and regulatory compliance officers and refined through secondary validation against SEC filings, EU regulatory databases, customs trade data, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated with top-down market sizing across deployment models, solution modules, end-user verticals, and technology integration layers.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with warehouse automation investment cycles and e-commerce fulfillment volatility shaping trajectory assumptions. Segmentation dimensions modeled include service type, solution functionality, end-user vertical, and technology integration complexity. CAGRs derived from shipment throughput correlations and platform adoption velocity curves. Industry-specific inputs incorporated EU AI Act implementation timelines and FDA pharmaceutical traceability mandate expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting private-equity 3PL rollup activity or East Asian semiconductor export restrictions would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and cloud migration velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Switzerland Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Romania Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Bulgaria Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Brazil Facility Management Market