
 Brazil Facility Management Market | 2026-2036
Brazil Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Facility Management Market Analysis
Integrated service bundling is realigning procurement patterns across Brazil's facility management sector. JLL leverages its technology platform to consolidate hard and soft services under single contracts. Sodexo Group anchors its position through food and facilities convergence in corporate campuses. CBRE Group, Inc. differentiates via workplace experience platforms that layer analytics onto traditional FM delivery.
Facility management encompasses the professional coordination of building operations, maintenance, cleaning, security, and environmental systems to ensure functional, safe, and efficient physical infrastructure. The discipline relies on CMMS platforms to schedule preventive maintenance, track asset lifecycles, and manage work orders across distributed property portfolios. Cleaning Services commands the largest revenue pool due to labor intensity and regulatory frequency requirements, while Building Automation represents the fastest-expanding technology segment as energy efficiency mandates intensify. Corporate Offices generate the most stable demand volume, though Healthcare Facilities offer superior margins due to specialized compliance protocols and 24/7 operational requirements.
ANVISA enforces strict hygiene and environmental control standards for healthcare facilities, directly elevating technical service requirements and vendor qualification barriers. Brazil's national labor regulator and CONMETRO certification frameworks further shape contract structures, particularly around outsourcing limits and technical workforce credentials. Stakeholders must monitor how pending municipal energy efficiency codes in São Paulo and Rio de Janeiro will force retrofit decisions across aging commercial stock.
Market Dynamics
Smart building automation platforms are compressing service delivery timelines across Brazil's commercial property stock. São Paulo's municipal energy codes are accelerating retrofit mandates that reshape vendor qualification requirements and contract bundling patterns.
Growth Catalysts
- ANVISA Sanitation Mandates:Healthcare facilities must upgrade HVAC and surface disinfection protocols, creating specialized service demand that commands premium pricing tiers.
- São Paulo Energy Efficiency Codes:Commercial buildings face mandatory automation retrofits, pulling integrated FM bundles into long-term contracts with performance guarantees.
- IoT Sensor Networks:Predictive maintenance platforms reduce unplanned downtime in corporate campuses, shifting buyer preference toward technology-enabled service providers.
Market Restraints
- Technical Workforce Scarcity:CONMETRO-certified technicians remain concentrated in São Paulo and Rio de Janeiro, limiting service expansion into secondary metros.
- Labor Cost Volatility:Brazil's national labor regulator enforces strict outsourcing limits that compress margin flexibility on cleaning and security contracts.
- Legacy Infrastructure Fragmentation:Aging commercial stock in Belo Horizonto and Porto Alegre requires costly pre-automation upgrades before smart systems can deploy.
Strategic Opportunities
- Northeast Corridor Expansion:Recife and Fortaleza office construction is outpacing qualified FM vendor presence, creating first-mover advantages for certified entrants.
- Healthcare Convergence:Diagnostic clinic chains seek single-vendor partnerships covering food, cleaning, and biomedical equipment maintenance under unified compliance frameworks.
- Remote Monitoring Platforms:Cloud-based CMMS integration with existing building management systems opens subscription revenue streams independent of labor-heavy service delivery.
Industry Challenges
- CONMETRO Certification Backlogs:Technical workforce credentialing delays stretch 8-14 months, constraining vendor capacity to fulfill contracted service levels.
- Multi-Site Integration Complexity:Corporate clients with distributed portfolios demand unified reporting across disparate legacy systems that resist standard API connections.
- Data Security Compliance:Facility IoT networks handling tenant occupancy patterns must align with Brazil's data protection framework, adding legal review cycles to deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Facility Management Market |
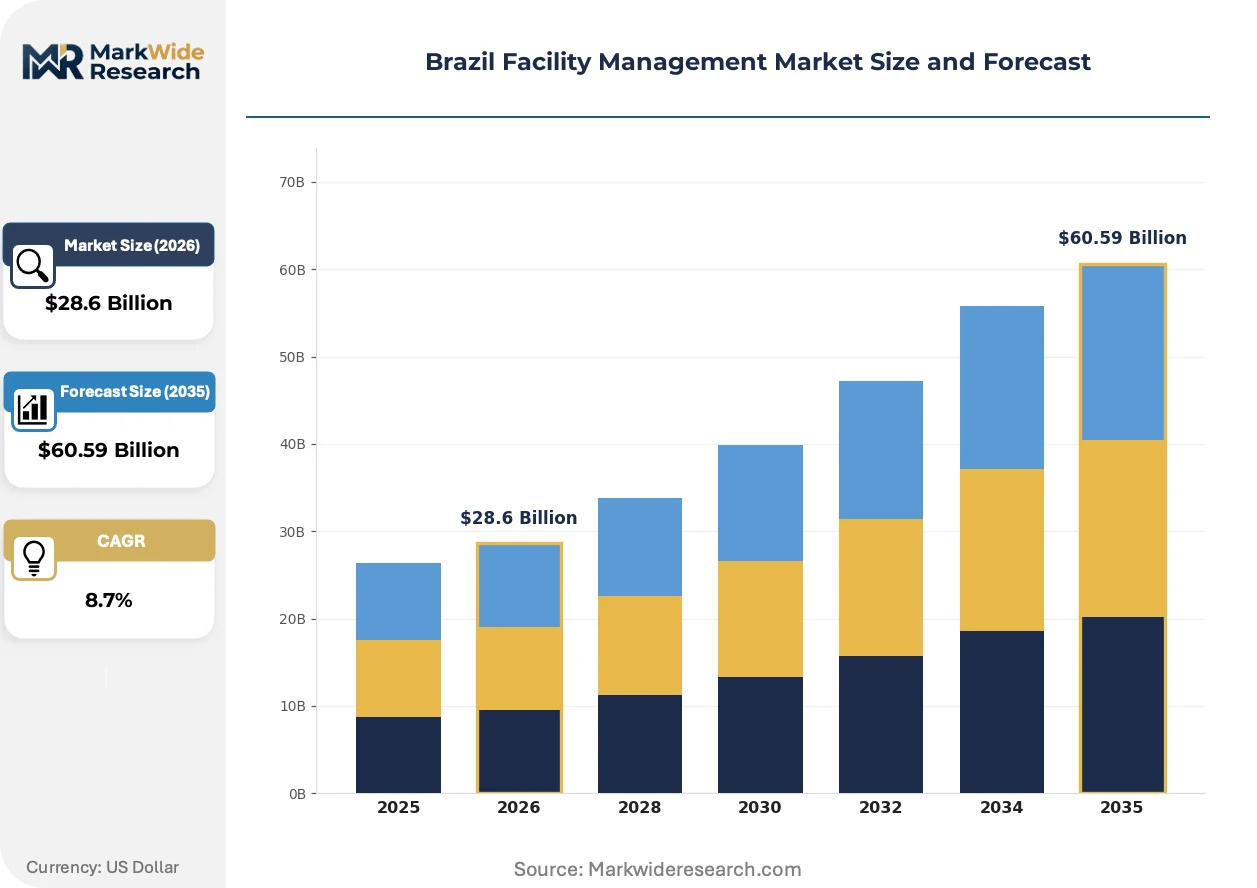
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, HVAC Services Client Type: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Stores Technology: FM Software, CMMS, IoT Solutions, Building Automation End Use: Commercial, Institutional, Residential, Industrial |
| Companies Covered | Jones Lang LaSalle IP, Inc. (JLL), ISS Facility Services, CBRE Group, Inc., Brasanitas Group, G4S Brazil, GPS Group, Cushman and Wakefield PLC, GRSA, Sodexo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Facility Management Market Emerging Trajectories
Digital service delivery models are displacing labor-intensive inspection routines across Brazil's facility management sector. Technology convergence is compressing the traditional separation between hard infrastructure maintenance and soft service operations.
Building automation software is modularizing how energy management, access control, and environmental monitoring systems interoperate. Corporate office landlords in São Paulo are adopting these platforms fastest, driven by municipal efficiency mandates that penalize non-compliance. The technology is modularizing vendor service portfolios into discrete, API-connected components that buyers can mix across providers rather than accepting bundled single-source contracts.
ANVISA's updated healthcare facility hygiene protocols now require continuous environmental monitoring documentation rather than periodic inspection logs. Hospital and clinic operators must deploy automated sensor networks or risk accreditation suspension. The diagnostic and surgical center segment is responding fastest, with facility managers prioritizing vendors who embed compliance reporting directly into service delivery workflows.
Corporate procurement teams are consolidating vendor relationships around outcome-based performance metrics rather than input-based service specifications. Food service and cleaning contracts that historically ran on separate RFP cycles now merge into unified workplace experience tenders. This pattern concentrates most visibly among technology and financial services tenants in São Paulo's Faria Lima corridor, where lease structures increasingly pass FM costs directly to occupiers who demand transparent KPI dashboards.
Brazil Facility Management Market Segmentation
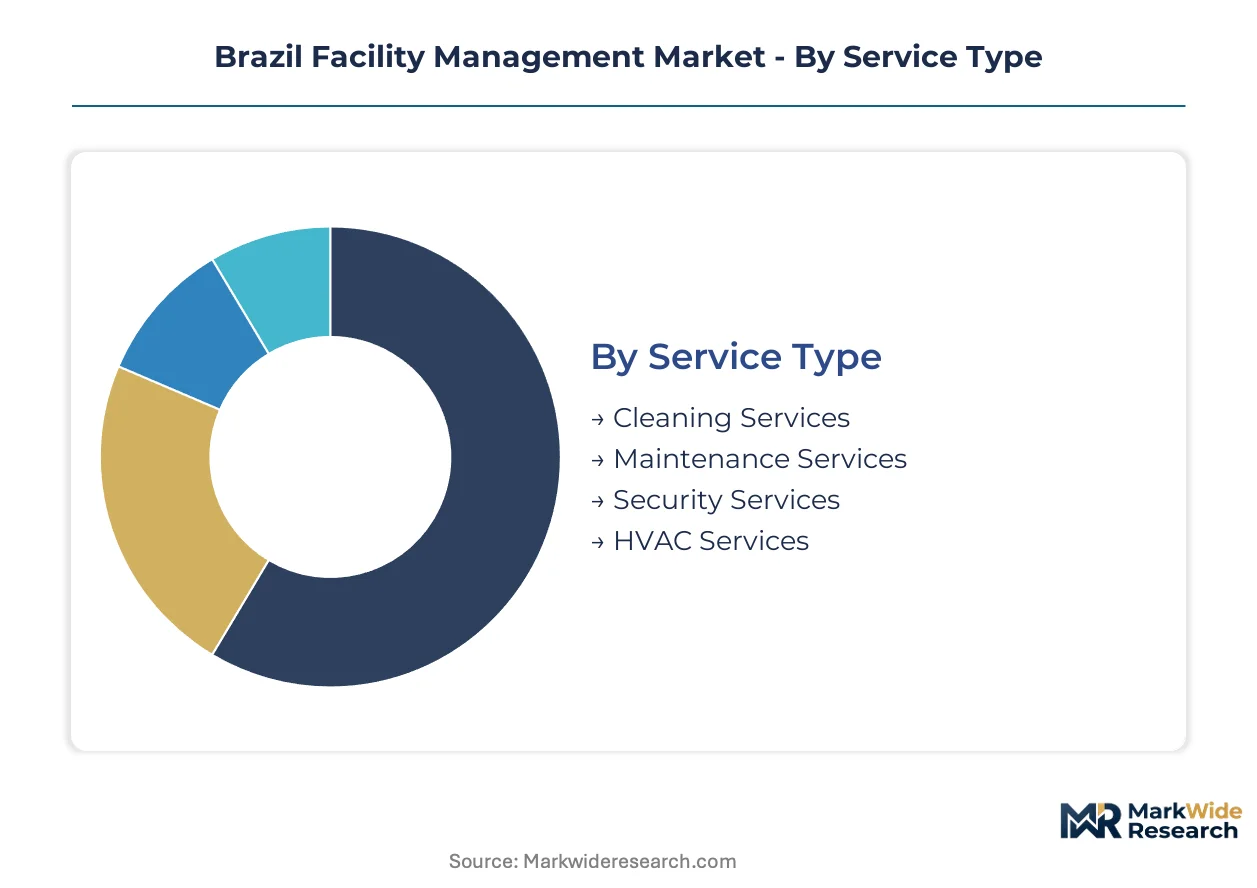
Segmentation in Brazil's facility management market reveals how service delivery models diverge across client sophistication levels and regulatory exposure. Procurement teams in São Paulo's commercial corridor demand integrated technology platforms, while secondary metros still purchase discrete labor services. Understanding these splits exposes where margin compression and premium pricing coexist.
Service Type:
Standalone labor services dominate contract volumes, yet embedded technology-augmented offerings capture expanding share as automation retrofits accelerate.
- Cleaning Services:Labor-intensive surface disinfection and waste management operations requiring frequent regulatory compliance documentation. São Paulo healthcare clusters drive specialized sanitization demand under ANVISA protocols that mandate stricter credentialing than commercial office contracts.
- Maintenance Services:Preventive and corrective interventions spanning electrical, plumbing, and structural systems. Corporate campuses in Faria Lima corridor increasingly bundle these with CMMS platforms that track asset lifecycles and automate work order dispatch.
- Security Services:Personnel-based access control and surveillance operations.
- HVAC Services:Climate system installation, repair, and optimization for energy efficiency mandates.
Cleaning Services leads volumes today; Building Automation-adjacent HVAC Services is gaining share fastest.
Client Type:
Cost tier stratification separates price-sensitive institutional buyers from premium-margin healthcare operators willing to pay for compliance certainty.
- Healthcare Facilities:Hospitals, diagnostic clinics, and surgical centers requiring 24/7 operational continuity and ANVISA-certified environmental controls. Recife and Fortaleza expansion corridors face acute vendor scarcity, allowing certified entrants to command premium pricing.
- Corporate Offices:Technology and financial services tenants demanding workplace experience platforms with transparent KPI dashboards. São Paulo's commercial stock concentrates here, though Rio de Janeiro's Barra da Tijuca cluster is expanding rapidly.
- Educational Institutions:Universities and K-12 facilities with seasonal demand fluctuations.
- Retail Stores:High-frequency cleaning and security requirements across distributed branch networks.
Corporate Offices anchor revenue stability; Healthcare Facilities delivers the steepest margin expansion trajectory.
Technology:
Application maturity varies sharply—legacy CMMS platforms are commoditized while IoT sensor networks remain deployment-constrained by integration complexity.
- Building Automation:Integrated energy management, access control, and environmental monitoring systems. São Paulo municipal efficiency codes are accelerating retrofit mandates that reshape vendor qualification requirements.
- IoT Solutions:Predictive maintenance platforms reduce unplanned downtime in corporate campuses. Deployment faces data security compliance requirements under Brazil's data protection framework that add legal review cycles.
- CMMS:Work order scheduling and asset lifecycle tracking platforms.
- FM Software:Broad operational management suites spanning multiple service categories.
CMMS penetration is deepest; IoT Solutions is climbing the fastest.
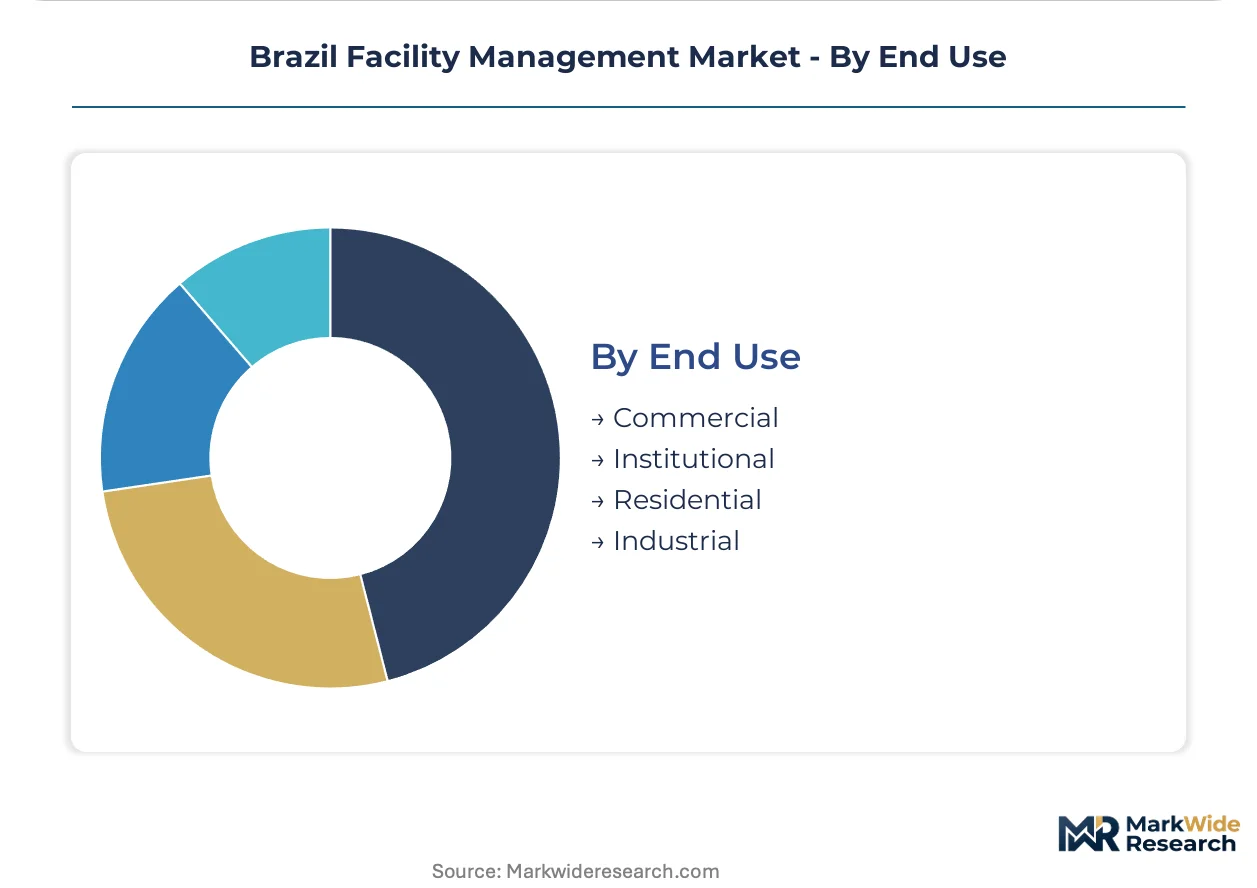
End Use:
Customer type concentration shapes procurement sophistication—commercial buyers lead technology adoption while institutional purchasers lag on digital integration.
- Commercial:Office towers, shopping centers, and mixed-use developments requiring integrated service bundles. São Paulo's aging stock in Belo Horizonto and Porto Alegre needs costly pre-automation upgrades before smart systems deploy.
- Industrial:Manufacturing and logistics facilities with specialized equipment maintenance needs. Northeast corridor expansion in Recife and Fortaleza is outpacing qualified vendor presence.
- Institutional:Government and non-profit facilities with constrained procurement flexibility.
- Residential:Condominium and multi-family property management services.
Commercial dominates contract value; Industrial is expanding most quickly on manufacturing reshoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's facility management sector traces its modern scale to São Paulo's commercial real estate boom of the 1990s, when multinational property services first established integrated operations. The market now distributes across five state-level economies with distinct procurement sophistication levels.
São Paulo
Faria Lima corridor tenants demand workplace experience platforms with unified KPI dashboards. ANVISA-certified vendors command premium pricing for healthcare facility contracts in the city's medical district. The metropolitan area concentrates over half of Brazil's CONMETRO-certified technical workforce.
Rio de Janeiro
Barra da Tijuca cluster expansion is accelerating corporate office construction. Municipal energy efficiency codes pending approval will force automation retrofits across aging commercial stock. State-level labor enforcement creates outsourcing constraints that reshape contract structures.
Minas Gerais
Belo Horizonte's industrial parks generate specialized equipment maintenance demand. Legacy infrastructure fragmentation requires costly pre-automation upgrades before smart building systems deploy. The state's manufacturing reshoring trend pulls qualified FM vendors from São Paulo.
Rio Grande do Sul
Porto Alegre's commercial stock faces similar aging infrastructure challenges. CONMETRO certification backlogs constrain vendor capacity to fulfill service contracts. Local procurement teams remain price-sensitive compared to São Paulo counterparts.
Bahia
Salvador's logistics and petrochemical facilities create industrial FM demand. Northeast corridor expansion outpaces qualified vendor presence, creating first-mover advantages for certified entrants. Federal infrastructure investment is accelerating facility construction timelines.
Brazil Facility Management Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance certification and technology integration capabilities. The market exhibits moderate concentration with ten significant operators controlling integrated service bundles. Three archetypes dominate: global property services platforms, regional labor-specialist conglomerates, and technology-augmented niche providers. Consolidation through acquisition of certified local operators and strategic partnerships for IoT platform licensing represent the dominant competitive vectors.
Within the global platform tier, JLL, CBRE Group, Inc., and Sodexo Group anchor premium positioning through technology convergence and workplace experience bundling. These operators exemplify the integrated service model reshaping procurement patterns. Regional specialists including Brasanitas Group and GPS Group occupy mid-tier positions focused on labor-intensive cleaning and security contracts. The competitive dynamic pits scale-driven technology platforms against relationship-driven local operators for corporate campus and healthcare facility contracts.
| Leading Market Players |
|---|
| Jones Lang LaSalle IP, Inc. (JLL) |
| ISS Facility Services |
| CBRE Group, Inc. |
| Brasanitas Group |
| G4S Brazil |
| GPS Group |
| Cushman and Wakefield PLC |
| GRSA |
| Sodexo Group |
| Others |
Supply Flow & Price Mechanics
Labor cost indices in São Paulo and Rio de Janeiro cascade through Brazil's facility management sector into three distinct pricing tiers. ANVISA certification requirements and CONMETRO credentialing backlogs concentrate qualified technician supply, amplifying premium pricing power for compliant vendors while compressing margins in commoditized cleaning and security segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures. Price differentiation separates ANVISA-certified healthcare specialists from standard commercial office operators and unlicensed regional labor providers. Pricing pressure stems from Brazil's national labor regulator enforcing strict outsourcing limits that constrain margin flexibility on high-volume cleaning contracts. Institutional buyers in government and education segments exhibit highest price sensitivity, while diagnostic clinic chains prioritize compliance certainty over cost minimization.
Supply Chain Analysis
Domestic-content mandates in federal infrastructure procurement reshape sourcing patterns toward Brazilian-certified technician networks and locally registered CMMS platforms. Geographic supply concentration centers on São Paulo and Rio de Janeiro for CONMETRO-credentialed technical labor, with secondary metros drawing from these pools. Raw material dependencies include IoT sensor hardware from East Asian manufacturing hubs, cloud infrastructure subscriptions, and specialized disinfection chemicals. Single-source vulnerability runs through concentrated certification bodies creating 8-14 month credentialing delays. Distribution runs through direct vendor-client relationships for integrated bundles and subcontractor networks for discrete labor services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's facility management sector reads as a late-cycle quality story where healthcare compliance convergence and smart building automation are displacing price-based competition. ANVISA's tightened sanitation protocols pull procurement teams toward premium-tier vendors with embedded compliance documentation capabilities.
For Market Incumbents: Acquire CONMETRO-certified technical workforce assets in the Northeast corridor before competitor entry accelerates. Consolidate regional labor-specialist operators to defend against technology platforms encroaching on integrated service contracts. Prioritize CMMS-to-IoT platform integration investments that create switching costs among corporate campus clients. For New Entrants and Emerging Players: Launch via remote monitoring platform subscriptions that bypass labor-heavy service delivery cost structures. Target Recife and Fortaleza office construction corridors where qualified vendor scarcity allows first-mover premium positioning. Pursue diagnostic clinic chains seeking unified food, cleaning, and biomedical equipment maintenance partnerships under single compliance frameworks. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-augmented niche providers holding healthcare sector certifications and proprietary IoT integration capabilities. Long-term viability favors operators capturing recurring platform revenue independent of wage-inflation exposure. Watch ANVISA enforcement intensity and municipal energy code adoption velocity as inflection indicators for premium-tier demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CONMETRO Certification Acquisition | Accelerates market entry into healthcare and industrial segments requiring credentialed technical labor. |
| IoT Platform Licensing Partnership | Enables predictive maintenance offerings without proprietary R&D investment in sensor hardware. |
| Northeast Corridor Workforce Buildout | Captures first-mover positioning in Recife and Fortaleza ahead of competitor certification completion. |
| Healthcare Compliance Integration | Embeds ANVISA documentation directly into service workflows creating accreditation-dependent client retention. |
| CMMS Subscription Model Launch | Generates recurring revenue streams decoupled from Brazil's volatile labor cost environment. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply-side estimates. Primary fieldwork engaged facility management executives at global property services platforms, regional labor-specialist operators, healthcare facility directors, corporate real estate procurement leads, and CONMETRO certification officials. Secondary validation drew from ANVISA regulatory filings, municipal energy code drafts in São Paulo and Rio de Janeiro, federal labor enforcement bulletins, and commercial real estate transaction databases. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Comparable historical periods anchored the projection framework against verified baseline data across the analysis window. The analytical model segmented demand by service type, client vertical, technology adoption tier, and metropolitan concentration. CAGRs derived from regression analysis of contract value growth rates, retrofit mandate implementation timelines, and healthcare construction permitting data. Forecast inputs included ANVISA enforcement intensity indices and municipal energy code adoption schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated automation retrofit mandates or prolonged CONMETRO certification backlogs. Assumptions reflect current regulatory trajectories and labor market conditions. ANVISA protocol revisions, federal outsourcing regulation changes, and IoT data security compliance rulings warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
South Africa Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Malta Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Philippines Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Italy Facility Management Services Market