
 Asia Pacific REIT Market | 2026-2036
Asia Pacific REIT Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific REIT Market Insights
Institutional sovereign wealth funds and pension managers is bifurcating the Asia Pacific REIT buyer base away from traditional retail investors seeking dividend yield. Link REIT leverages its dominance in Hong Kong retail and mainland China logistics to sustain portfolio resilience across cyclical downturns. Goodman Group anchors industrial and data center exposure through development-led strategies in Australia and Japan. Ascendas REIT competes on specialized business park and logistics assets across Singapore and India.
A real estate investment trust pools capital from multiple investors to own, operate, or finance income-producing properties, typically distributing at least 90% of taxable income to unitholders to maintain pass-through tax status. The vehicle structures around property type segmentation, with industrial and data center assets commanding yield compression while hospitality recovers from pandemic-era disruptions. Core and core-plus investment strategies occupy the majority of institutional allocations, though value-add approaches in Southeast Asian logistics are gaining traction as vacancy rates tighten. Distribution through exchange-traded channels dominates retail access, while private placement vehicles control institutional blocks in premium Sydney and Tokyo assets.
Japan's FSA and METI enforce disclosure standards and governance codes that shape REIT reporting transparency, while Singapore's MAS regulates leverage caps and distribution requirements for listed trusts. Australia's ASIC and APRA frameworks govern stapled structures and wholesale fund access, creating compliance complexity for cross-border sponsors. Stakeholders must monitor how Japan's green building standards and Singapore's sustainability-linked financing rules reshape capital allocation toward certified assets.
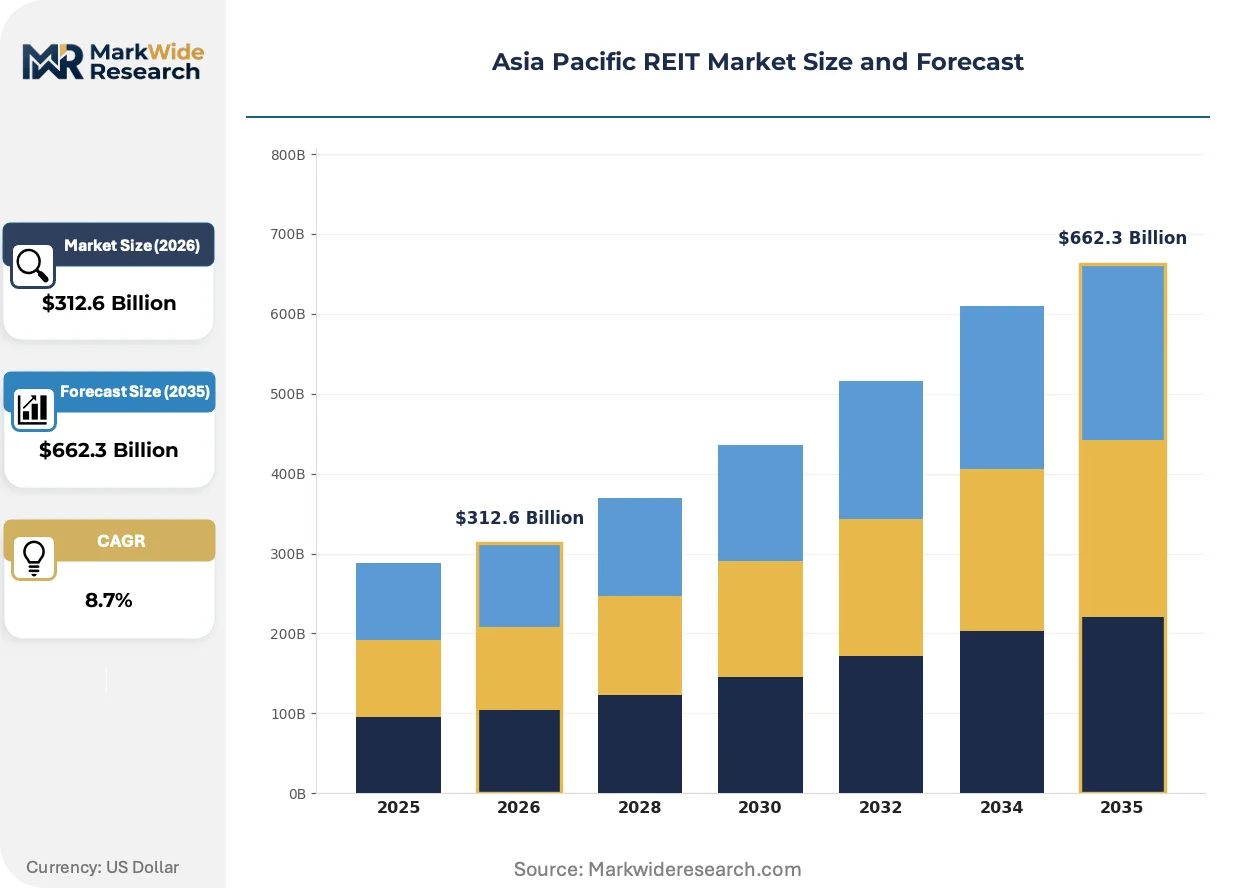
Market Dynamics
Institutional capital rotation into stabilized logistics and data center assets is compressing yield spreads across the Asia Pacific REIT landscape, forcing managers to rebalance portfolios toward alternative property segments.
Growth Catalysts
- Japan's METI disclosure standards:Enhanced transparency requirements are attracting foreign institutional capital seeking governance-aligned vehicles.
- Singapore's downtown core demand:Prime commercial compression is redirecting flows into industrial and data center premiums.
- Pension fund yield mandates:Australia's superannuation system is deploying record allocations into income-producing real estate structures.
Market Restraints
- Interest rate sensitivity:Rising policy rates across Australia, Japan, and South Korea are widening cap rate spreads and pressuring NAVs.
- Currency volatility:Cross-border investors face hedging costs that erode net returns on unhedged Singapore dollar and yen exposures.
- Development pipeline delays:Protracted approval timelines in Australian state jurisdictions are constraining supply response to logistics demand.
Strategic Opportunities
- India's logistics parks:Underpenetrated warehouse infrastructure in Mumbai-Delhi corridors offers development-led entry points.
- Japan's green building certification:METI's tightening environmental standards create first-mover advantages for certified asset portfolios.
- Data center colocation:Cloud hyperscaler demand in Sydney and Tokyo is outpacing supply, supporting premium lease structures.
Industry Challenges
- ESG reporting standardization:Divergent sustainability frameworks across Japan's GRESB alignment and Singapore's MAS requirements complicate cross-border compliance.
- Asset management specialization:Shortage of technicians skilled in data center cooling systems and industrial automation is inflating operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific REIT Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Hospitality Investment Strategy: Core, Core-Plus, Value-Add, Opportunistic Asset Class: Retail, Office, Healthcare, Mixed-Use Distribution Channel: Direct Investment, Exchange-Traded, Private Placement, Institutional |
| Companies Covered | Link REIT, Goodman Group, Ascendas REIT, Nippon Building Fund, Scentre Group, CapitaLand Integrated Commercial Trust, NTT Global Data Center REIT, Centurion, Japan Real Estate Investment Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific REIT Market Trends and Innovations
Technology-enabled asset management and sustainability-linked financing are restructuring how Asia Pacific REITs attract capital and optimize property-level returns.
Smart building management systems integrating IoT sensors and predictive analytics are supplanting manual facility oversight in premium logistics and office assets. Japanese and Australian REITs are deploying these platforms to reduce energy intensity and extend asset lifecycles. The shift is compressing operating expense ratios and enabling dynamic lease pricing tied to real-time space utilization.
Singapore's MAS sustainability-linked financing rules are mandating disclosure of climate risk exposure across listed trust portfolios. The framework requires stress-testing against transition scenarios and physical asset vulnerability. Industrial and hospitality segments face the steepest compliance curves as they retrofit aging stock to meet certification thresholds.
Direct institutional placement is displacing retail-dominant capital structures for large-format assets in Sydney and Tokyo. Sovereign wealth funds and pension managers are negotiating bilateral stakes in premium logistics parks, bypassing exchange liquidity premiums. This channel shift is most pronounced in data center and cold storage assets where scale thresholds exclude fragmented ownership.
Asia Pacific REIT Market Segmentation
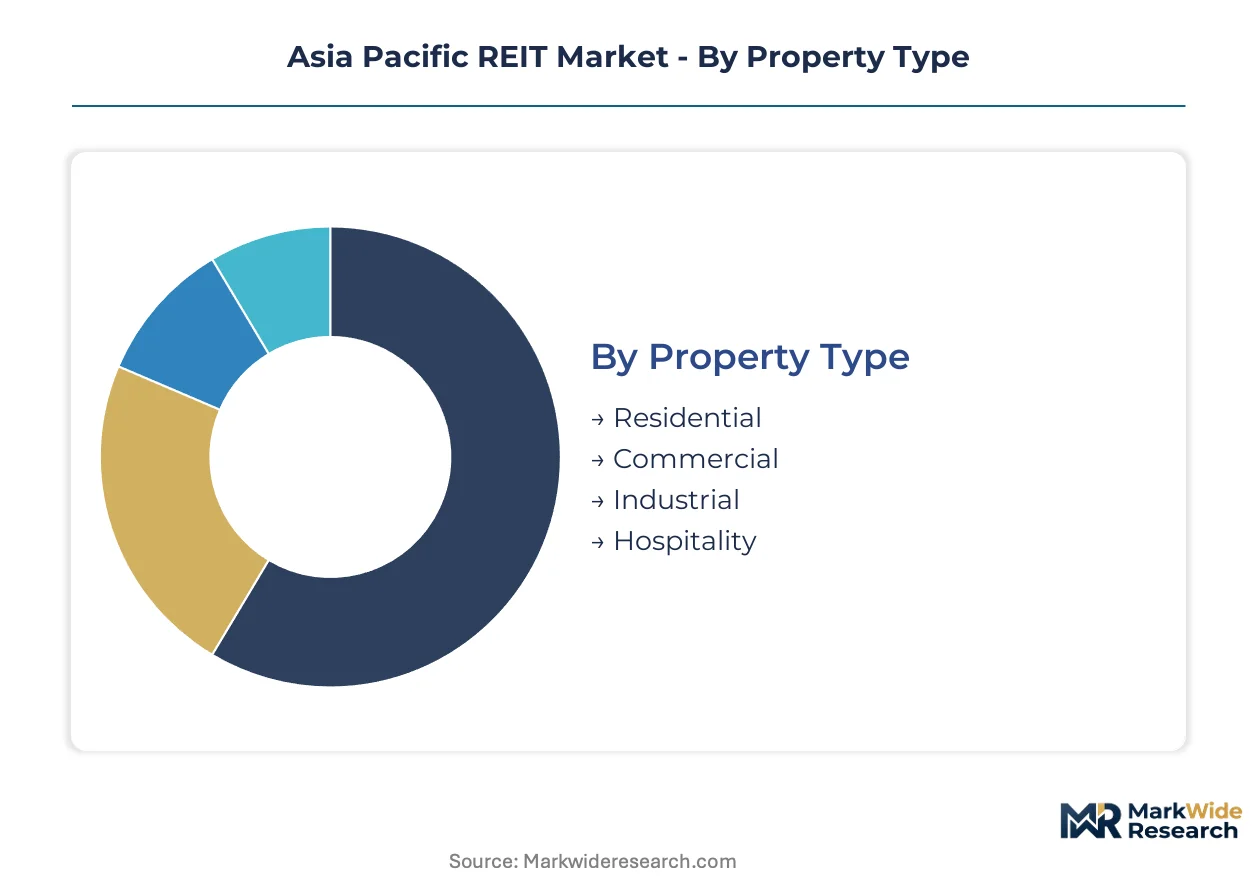
Property type segmentation determines how REITs allocate capital across income-generating assets with divergent yield profiles and cyclical sensitivities. Investment strategy and distribution channel classifications further differentiate vehicles by risk tolerance and investor access mechanisms.
Property Type:
Industrial and logistics assets face intensifying substitution pressure from direct institutional ownership and private infrastructure funds seeking yield without REIT liquidity constraints.
- Residential:Multifamily rental properties and build-to-rent developments concentrate demand in Australia's Sydney-Melbourne corridor and Japan's urban prefectures, where housing affordability gaps sustain institutional rental demand. Rent control regimes in some Australian states compress net operating income growth.
- Commercial:Prime office and retail assets in Singapore's downtown core and Hong Kong's central district trade at compressed yields against rising interest rate sensitivity. Flight-to-quality dynamics favor grade-A stock with green certification.
- Industrial:Logistics warehouses and last-mile distribution centers anchor pension fund allocations across Japan's Greater Tokyo area and Australia's eastern seaboard. E-commerce fulfillment demand outpaces supply in underpenetrated Indian corridors.
- Hospitality:Hotels and serviced apartments recover from pandemic-era disruptions with RevPAR momentum concentrated in Australia's leisure destinations and Japan's inbound tourism markets. Operating leverage amplifies cash flow volatility.
Industrial anchors the volume base while hospitality gains share at the steepest rate.
Investment Strategy:
Risk-return positioning stratifies capital deployment across stabilized income and development-led appreciation plays.
- Core:Stabilized, fully leased assets in prime locations with minimal capital expenditure requirements. Australian superannuation funds concentrate allocations here for yield matching liabilities.
- Core-Plus:Assets with modest value-add potential through lease rollover or light refurbishment. Singapore's MAS leverage caps constrain gearing on these vehicles.
- Value-Add:Properties requiring active management, repositioning, or lease-up to achieve stabilized returns. Southeast Asian logistics parks attract this capital seeking development premiums.
- Opportunistic:Distressed acquisitions, ground-up development, or complex recapitalizations with highest return hurdles. Japan's regional office markets and India's emerging logistics corridors draw specialist managers.
Core strategies dominate institutional allocations while value-add approaches expand most quickly among regional specialists.
Asset Class:
Functional use classification shapes operating expense structures and tenant covenant quality.
- Retail:Shopping centers and high-street assets face structural headwinds from e-commerce penetration, though convenience-based neighborhood retail in Australian suburbs shows resilience.
- Office:Grade-A stock in Singapore and Tokyo commands rent premiums for wellness-certified space, while secondary assets suffer vacancy erosion from hybrid work normalization.
- Healthcare:Hospitals, aged care facilities, and medical office buildings attract defensive capital seeking inflation-linked revenue streams. Australia's demographic aging supports demand.
- Mixed-Use:Integrated developments combining residential, commercial, and retail components optimize land value in dense Asian urban centers. Japan's METI guidelines encourage this format for transit-oriented sites.
Office retains the largest capital stock while healthcare climbs the fastest on demographic tailwinds.
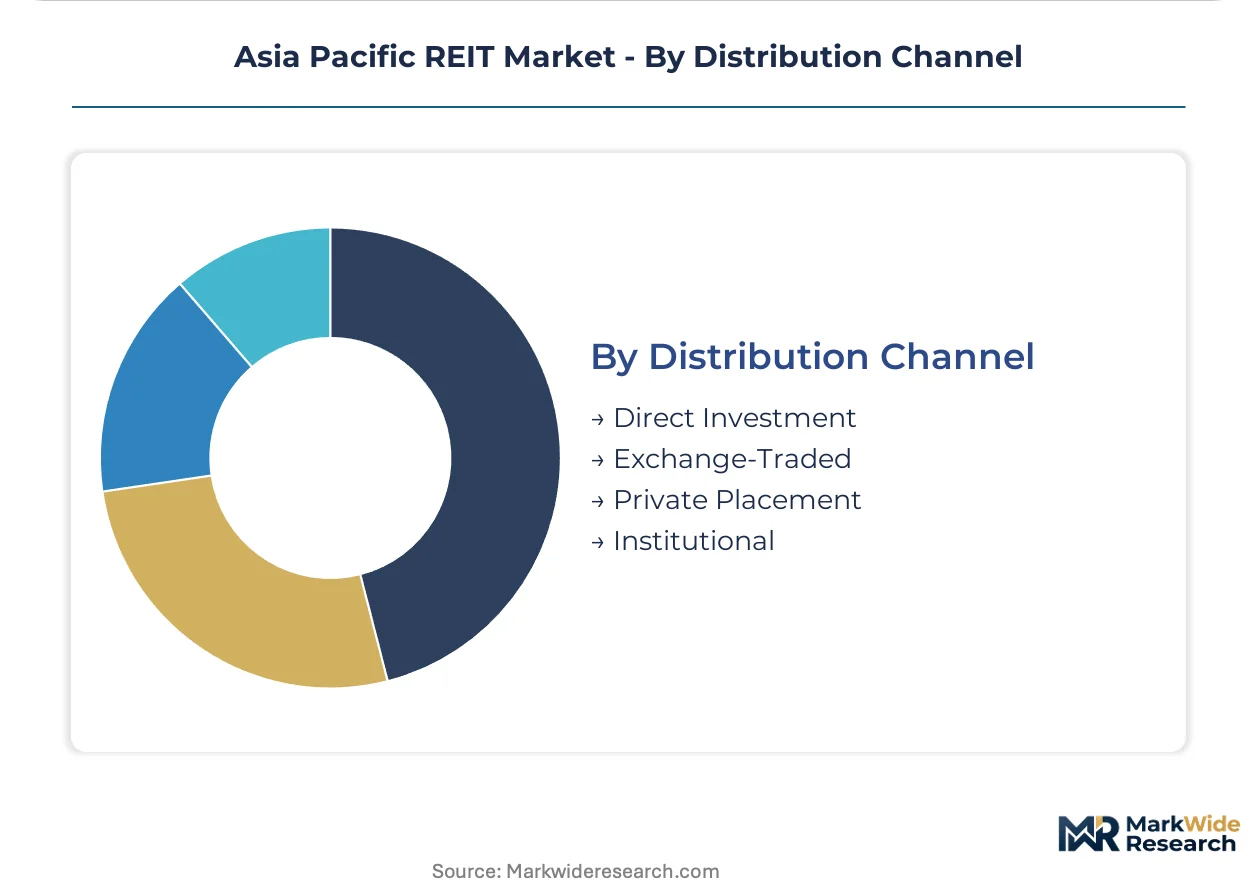
Distribution Channel:
Investor access mechanisms determine liquidity terms, minimum thresholds, and regulatory treatment.
- Direct Investment:Bilateral acquisitions of whole assets or platform stakes by sovereign wealth funds and pension managers. Sydney and Tokyo logistics parks transact primarily through this channel.
- Exchange-Traded:Listed REITs on Singapore Exchange, Tokyo Stock Exchange, and Australian Securities Exchange provide retail and institutional liquidity. MAS and ASIC disclosure requirements govern these vehicles.
- Private Placement:Unlisted trusts and club deals targeting accredited investors with longer hold periods. Japan's FSA regulates these under investment management frameworks.
- Institutional:Separately managed accounts and pooled vehicles for superannuation and sovereign fund allocations. Australia's APRA prudential standards shape these structures.
Exchange-traded vehicles dominate retail access while institutional channels capture the steepest expansion in large-format alternative assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows from Australian superannuation funds into Japanese logistics assets are reshaping cross-border investment patterns across the Asia Pacific corridor. Singapore serves as the primary listing venue for regional REITs seeking institutional liquidity. Regulatory divergence between METI disclosure standards and MAS leverage caps creates compliance complexity for multi-jurisdictional sponsors.
Japan
Tokyo's Grade-A office stock attracts yield-seeking pension capital from Australian and Canadian funds. METI's enhanced governance codes and green building certification requirements are tightening disclosure thresholds for listed J-REITs. The Greater Tokyo logistics corridor, particularly Saitama and Chiba prefectures, is seeing development premiums compress as e-commerce fulfillment demand outpaces supply response.
Singapore
MAS leverage caps at 50% of deposited property are constraining gearing for Core-Plus strategies while directing flows into stabilized Core assets. The downtown commercial core faces yield compression against rising interest rate sensitivity. Industrial and data center premiums in Jurong and Changi logistics clusters are attracting sovereign wealth fund placement outside exchange-traded structures.
Australia
Sydney-Melbourne corridor demand concentrates superannuation allocations into stabilized logistics and business park assets. ASIC and APRA frameworks govern stapled structures and wholesale fund access, creating compliance layering for cross-border sponsors. Last-mile distribution centers in Brisbane and Perth are drawing development-led capital as vacancy rates tighten below historical averages.
South Korea
Seoul Capital Area office assets face hybrid work normalization pressures while logistics parks in Incheon and Gyeonggi Province attract institutional rotation. The country's national financial regulator enforces leverage and distribution requirements that shape K-REIT structuring. Data center colocation demand from cloud hyperscalers is outpacing supply in Pangyo and Songdo clusters.
India
Mumbai-Delhi logistics corridors offer underpenetrated warehouse infrastructure for value-add development strategies. SEBI regulations govern InvIT and REIT listing requirements with distribution mandates that attract yield-focused capital. Industrial and logistics assets in Bangalore and Hyderabad are seeing pension fund allocation as vacancy compression accelerates rental growth.
Asia Pacific REIT Market Competitive Landscape
Listed leaders compete with private specialists across capital access and liquidity preferences, creating a bifurcated ownership structure where exchange-traded vehicles serve retail and institutional blocks while bilateral placements capture premium logistics and data center scale. The market consolidates around three strategic archetypes: diversified platform operators with multi-country footprints, specialized industrial and alternative asset developers, and domestic-focused commercial incumbents. Competitive positioning hardens through portfolio rebalancing toward certified green assets and direct institutional placement bypassing exchange liquidity premiums.
Within the diversified platform tier, Link REIT and Goodman Group exemplify cross-border scale strategies spanning Hong Kong retail and mainland China logistics or Australian-Japanese industrial development pipelines. Ascendas REIT occupies a specialized position in Singapore-India business park and logistics corridors. These three entities represent distinct archetypes—retail-logistics hybrid, development-led industrial, and Asia-South Asia corridor specialist—each responding differently to METI disclosure standards and MAS sustainability-linked financing rules.
| Leading Market Players |
|---|
| Link REIT |
| Goodman Group |
| Ascendas REIT |
| Nippon Building Fund |
| Scentre Group |
| CapitaLand Integrated Commercial Trust |
| NTT Global Data Center REIT |
| Centurion |
| Japan Real Estate Investment Corporation |
| Others |
Pricing and Supply Chain Analysis
Scale economies in Singapore's institutional-grade logistics clusters compress operating expense ratios while simultaneously elevating price floors for entry-level sponsors. Capacity utilization above ninety percent in Sydney's last-mile distribution networks translates directly into yield premiums that smaller Australian REITs cannot match without development-led repositioning.
Pricing Analysis
Asset-generation pricing gaps separate stabilized Core portfolios from value-add development plays across the Asia Pacific corridor. Three-tier pricing structure across premium, standard, and economy levels stratifies by green certification grade, with GRESB-aligned assets in Tokyo commanding rent premiums over uncertified secondary stock. Pricing pressure stems from Australian superannuation fund yield mandates compressing cap rates on stabilized logistics. Retail investors exhibit highest price sensitivity through exchange-traded vehicles, while sovereign wealth funds accept liquidity discounts for direct placement in Sydney data centers.
Supply Chain Analysis
Development approval chokepoints in Australian state jurisdictions constrain supply response to logistics demand across the Sydney-Melbourne corridor. Geographic supply concentration centers on Japan's Greater Tokyo prefectures, Singapore's Jurong logistics cluster, and Australia's eastern seaboard. Raw material dependencies include structural steel from China, HVAC systems from South Korea, and data center cooling equipment from Japan. Single-source vulnerability runs through Japanese mechanical and electrical contractors for premium-grade fit-outs. Distribution runs through bilateral placement channels for institutional blocks and exchange-listed vehicles for retail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as METI disclosure standards and MAS sustainability-linked financing rules create interoperability requirements across multi-jurisdictional REIT structures. Ecosystem consolidation favors sponsors with integrated asset management and development capabilities spanning certification, financing, and institutional placement.
For Market Incumbents: Fortify portfolio resilience through backward integration into development pipelines and captive asset management platforms. Link REIT's dominance in Hong Kong retail and mainland China logistics demonstrates how cross-border scale absorbs regulatory fragmentation. Certification investment in Japan's green building standards creates defensive moats against yield compression from uncertified competitors. For New Entrants and Emerging Players: Anchor in India's underpenetrated Mumbai-Delhi logistics corridors where SEBI-regulated InvIT structures attract yield-focused capital. Southeast Asian value-add strategies in Vietnam and Indonesia offer white-space entry with lower institutional competition. Go-to-market positioning through bilateral sovereign wealth fund relationships bypasses exchange liquidity premiums and retail investor price sensitivity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial and data center developers with certified asset pipelines and direct institutional placement capabilities. Long-term viability rests on sponsors who control development land banks across multiple Asia Pacific jurisdictions. Acquisition target archetype: mid-cap logistics specialists with METI-compliant disclosure frameworks and MAS sustainability-linked financing access. Signal to watch: compression in development yield spreads between certified and uncertified assets as green building mandates tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Program | METI's tightening environmental standards create first-mover rent premiums in Tokyo Grade-A stock. |
| Direct Institutional Placement Channel | Bilateral sovereign wealth fund relationships bypass exchange liquidity premiums on Sydney logistics assets. |
| Development-Led Pipeline Expansion | Land bank control in Australia's Brisbane-Perth corridor captures vacancy compression as e-commerce demand outpaces supply. |
| Sustainability-Linked Financing Structure | MAS disclosure requirements attract ESG-mandated capital into certified Singapore industrial portfolios. |
| Cross-Border Platform Integration | Multi-jurisdictional asset management capabilities absorb regulatory divergence between Japan and Singapore frameworks. |
Research Methodology
A spread of perspectives from REIT portfolio managers, pension fund allocation heads, property development executives, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with J-REIT and S-REIT sponsors, Australian superannuation fund real estate directors, and Singapore sovereign wealth fund infrastructure teams. Secondary validation drew from METI disclosure filings, MAS regulatory circulars, ASIC stapled structure guidance, and APRA prudential standards for superannuation fund real estate allocations. Bottom-up asset-level cash flow modeling triangulated against top-down institutional capital flow estimates across the analysis window.
Segmentation dimensions modeled include property type, investment strategy, asset class, and distribution channel across the projection horizon. Analytical framework incorporated yield compression dynamics, leverage constraint impacts from MAS and APRA regulations, and certification premium effects from Japan's green building standards. CAGRs were derived from scenario-weighted probability distributions of institutional allocation shifts and supply response timelines. Industry-specific forecast inputs included e-commerce fulfillment demand elasticities and data center power density requirements for cloud hyperscaler colocation.
Decision-makers should treat outputs as directional under assumptions of sustained pension fund yield mandates and stable regulatory disclosure frameworks; material deviation in interest rate trajectories or green certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as METI enforcement intensity and MAS sustainability-linked financing adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Poland Facility Management Market
Real Estate
Africa Facility Management Market
Real Estate
Qatar Residential Real Estate Market
Real Estate
Global Log Cabins or Log Homes Market
Real Estate
Latin America Office Real Estate Market
Real Estate
North America Office Real Estate Market
Real Estate
Australia Co-Working Office Spaces Market
Real Estate
Green/Intelligent Buildings Market
Real Estate
Indonesia Residential Real Estate Market
Real Estate
UK Commercial Real Estate Market
Real Estate
United States Rental Rate for Residential Real Estate Market
Real Estate
Australia Flexible Office Space Market
Real Estate
Australia Luxury Residential Real Estate Market
Real Estate
Egypt Condominiums and Apartments Market
Real Estate
Condom Market
Real Estate
Indonesia Facility Management Market