
 US Property Management Software Market | 2026-2036
US Property Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Property Management Software Market Insights
The capital-intensity divergence between cloud-native entrants and legacy on-premises incumbents is unwinding competitive dynamics across the sector. AppFolio leverages AI-driven automation to dominate the mid-market multifamily segment. Yardi Voyager anchors enterprise portfolios through deep accounting functionality and verticalized module extensions. Buildium competes aggressively on price for independent landlords while navigating feature breadth limitations.
Property management software encompasses integrated platforms that automate rent collection, maintenance dispatch, lease administration, and financial reporting through centralized databases accessible via web or mobile interfaces. Cloud-based deployment leads segment composition due to lower upfront infrastructure requirements and automatic regulatory update delivery. SaaS models capture expanding margin pools as recurring revenue replaces perpetual licensing, while accounting functionality remains the stickiest module due to IRS compliance integration and audit trail requirements.
Fair Housing Act enforcement by HUD, state-level security deposit regulations, and emerging SEC climate disclosure rules for real estate investment trusts collectively shape product roadmaps and liability architectures. The CFPB's growing scrutiny of rental application fees and tenant screening algorithms is forcing platform providers to embed compliance checkpoints directly into workflow logic. Stakeholders must monitor how municipal rent control digitization in jurisdictions like San Francisco and Boston reshapes feature prioritization and pricing power.
Market Dynamics
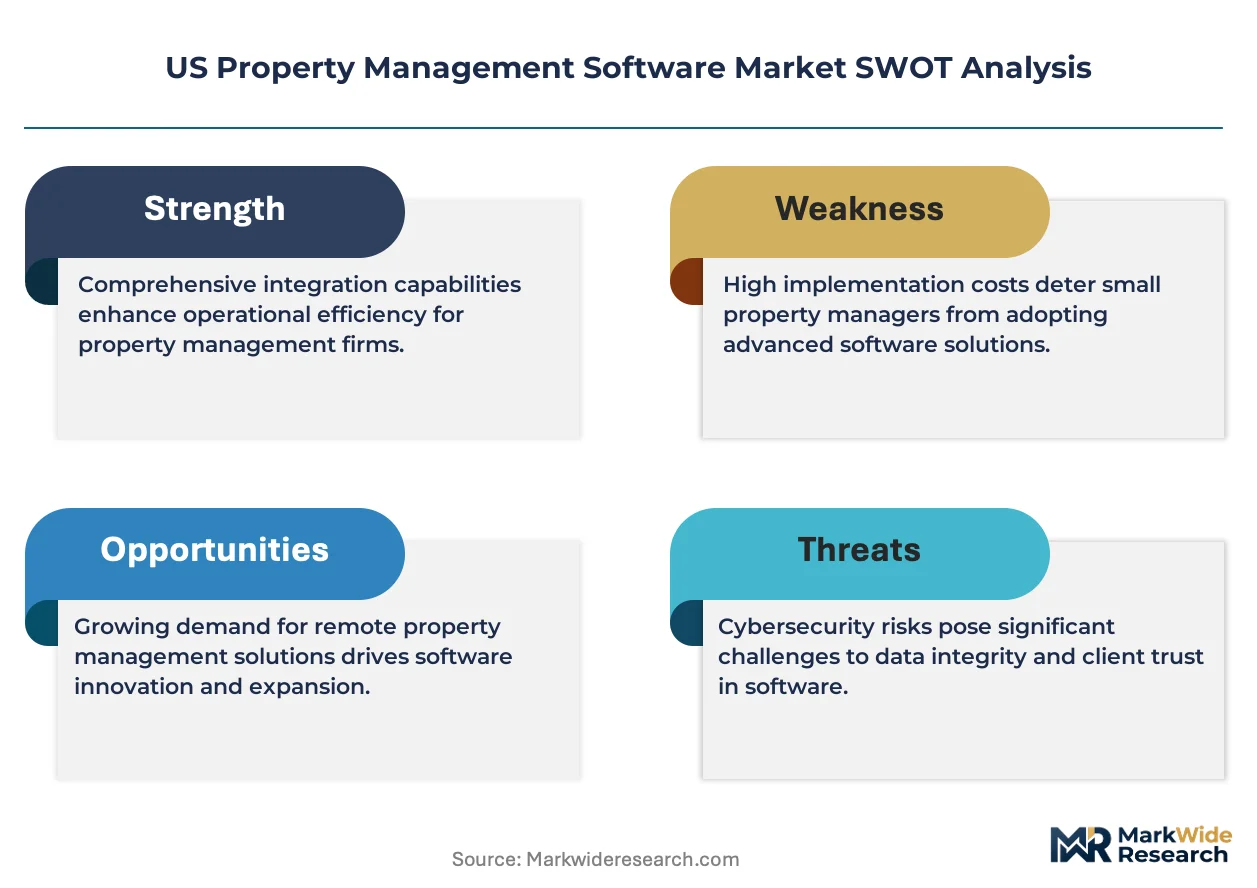
Mid-size multifamily operators across Texas and Florida are consolidating vendor relationships. This buyer concentration is compressing pricing power for point-solution providers while rewarding integrated SaaS platforms that embed accounting, compliance, and tenant-facing portals.
Growth Catalysts
- HUD Fair Housing Act digitization:Federal enforcement mandates are forcing property managers to document screening algorithms and disparate impact audits within software workflows.
- California rent control automation:Municipalities including San Francisco and Los Angeles require real-time rent increase calculations tied to CPI indexing.
- Cloud migration tailwinds:On-premises legacy systems face obsolescence as automatic security patching and remote access become operational necessities for distributed property portfolios.
Market Restraints
- Implementation cost barriers:Data migration from legacy Yardi or MRI systems to modern SaaS platforms requires six-figure professional services engagements.
- Vendor concentration risk:AppFolio and Yardi collectively control the majority of mid-market and enterprise installed bases, creating switching friction and integration dependencies.
- API standardization gaps:Lack of uniform data exchange protocols between property management platforms and smart building IoT ecosystems limits automation depth.
Strategic Opportunities
- SEC climate disclosure rules:Real estate investment trusts must track and report building-level emissions, creating demand for carbon accounting modules within property management stacks.
- CFPB rental application scrutiny:Proposed limits on tenant screening fees and algorithmic transparency requirements open white space for compliance-embedded workflow tools.
- Convergence of AI and maintenance dispatch:Predictive work order routing based on equipment sensor data remains underdeployed outside Class A multifamily assets.
Industry Challenges
- Certified property accountant scarcity:IRS compliance integration requires specialized staff who understand both GAAP and tax-specific real estate treatment.
- Legacy system integration complexity:Hybrid environments combining cloud front-ends with on-premises accounting databases create data synchronization failures and audit trail gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Property Management Software Market |
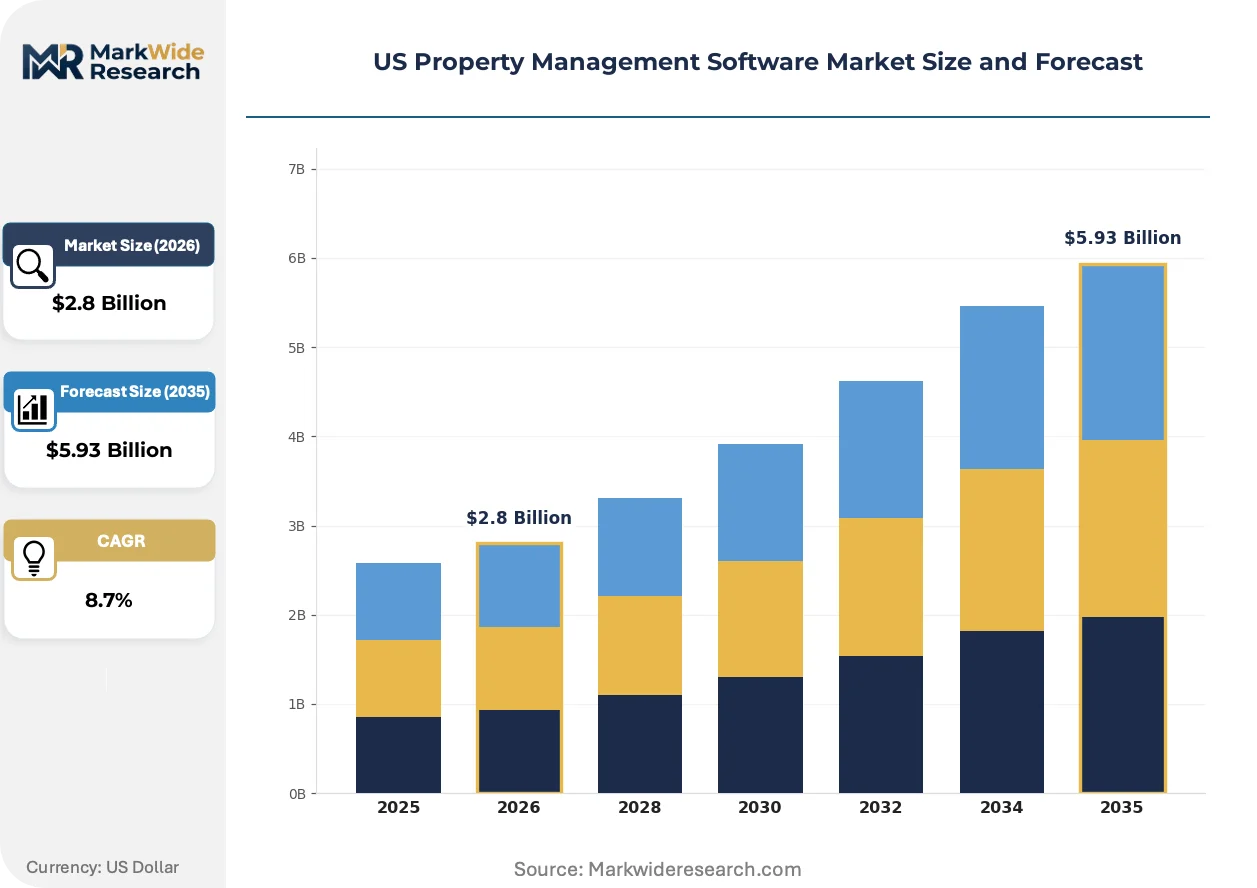
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Cloud-Based, Desktop, Mobile End User: Real Estate Firms, Property Managers, Landlords, Tenants Deployment: On-Premises, SaaS, Hybrid, Managed Services Functionality: Accounting, Maintenance Management, Tenant Communication, Rental Tracking |
| Companies Covered | AppFolio, Buildium, Yardi Voyager, Rent Manager, Rentec Direct, RealPage OneSite, MRI Software, Yardi Breeze, Entrata, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Property Management Software Market Trends and Innovations
Artificial intelligence is penetrating core operational workflows faster than regulatory frameworks can adapt. Platform providers are racing to embed predictive capabilities while navigating emerging algorithmic accountability requirements.
Machine learning rent pricing engines are bifurcating the revenue optimization landscape. Institutional multifamily owners in Phoenix and Atlanta deploy dynamic yield management tools that adjust lease rates daily. This capability is compressing margins for operators relying on static annual pricing cycles.
The CFPB's proposed rulemaking on tenant screening algorithms is reshaping product development priorities. Software providers must now build explainable AI features that document decision logic for fair housing audits. Mid-market firms in California face the steepest compliance curve due to overlapping state and municipal requirements.
Subscription fatigue among independent landlords is altering channel economics. Buyers increasingly reject tiered feature bundles in favor of modular pricing where accounting, marketing, and maintenance tools unbundle. Florida-based property managers demonstrate the strongest preference for à-la-carte procurement, forcing vendors to restructure go-to-market packaging.
US Property Management Software Market Segmentation
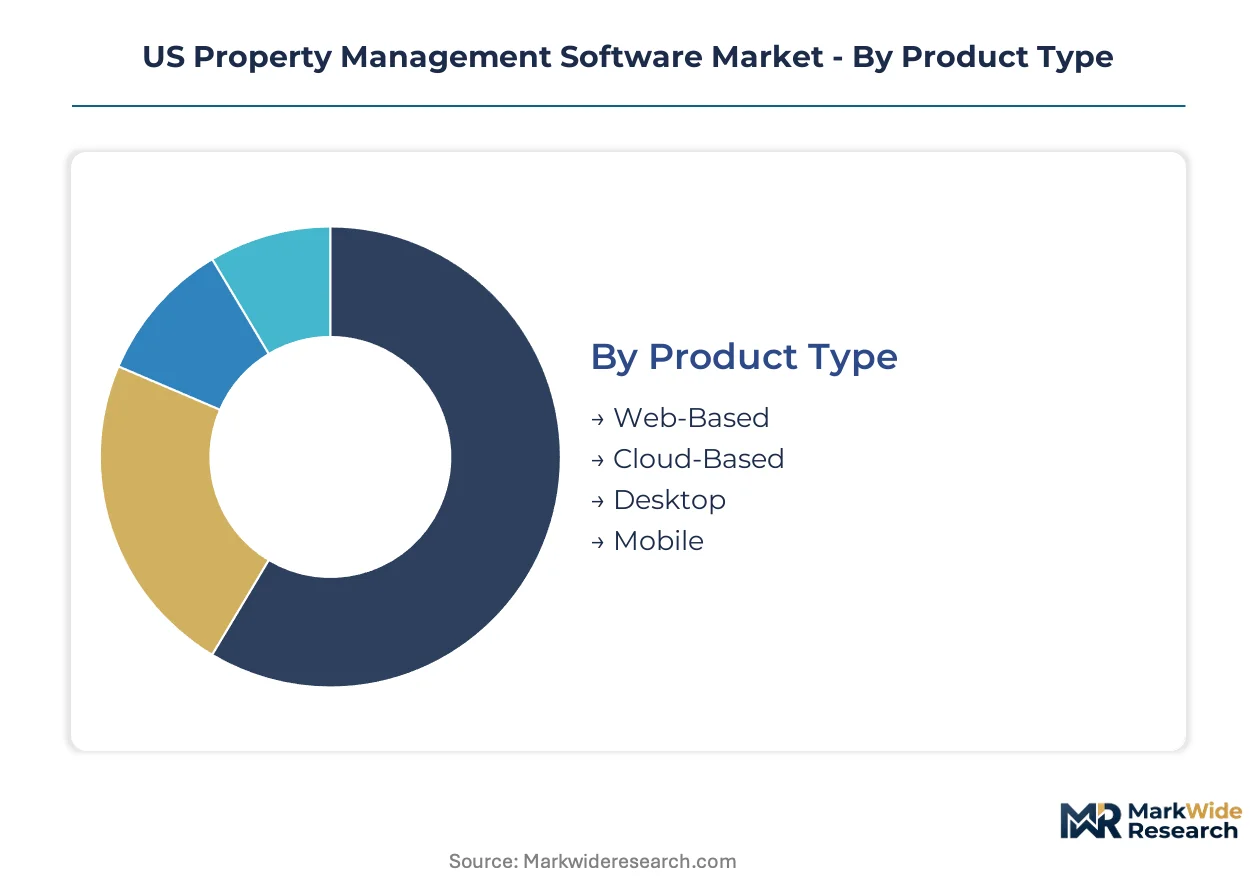
Segmentation in property management software reveals how buyer priorities diverge across operational scale and technical sophistication. Understanding these fault lines helps vendors align development roadmaps with where purchasing power is actually concentrating.
Product Type:
Cloud-based platforms dominate domestic procurement, while desktop and mobile-first architectures serve specific workflow niches in fragmented ownership structures.
- Cloud-Based:Centralized infrastructure with automatic security patching and multi-tenant database architecture. Texas and Florida multifamily operators drive concentrated demand as distributed portfolios require remote access without VPN dependency. Automatic regulatory update delivery reduces compliance labor for mid-size firms navigating California rent control digitization.
- Web-Based:Browser-accessible platforms built on responsive design frameworks with API-first connectivity. Independent landlords in secondary metros favor these for lower subscription floors and minimal IT overhead, though feature depth trails native cloud alternatives.
- Desktop:Legacy on-premises installations retaining installed bases among small portfolio holders with minimal staff mobility requirements.
- Mobile:Native iOS and Android applications optimized for field maintenance teams and tenant self-service portals.
Cloud-based deployments command the established base. The steepest expansion runs through mobile-first architectures serving maintenance dispatch workflows.
End User:
Procurement authority concentrates differently across these buyer types, with property managers controlling the largest aggregate spend but landlords representing the highest transaction volume.
- Property Managers:Third-party operators managing multifamily assets on behalf of institutional owners. California and New York compliance mandates force platform upgrades as HUD Fair Housing Act digitization requires documented screening algorithms.
- Real Estate Firms:Brokerage-affiliated property management divisions integrating leasing and management workflows. Phoenix and Atlanta institutional owners deploy these for dynamic yield management across Class A assets.
- Landlords:Individual owners with portfolios under fifty units driving modular pricing demand in Florida markets.
- Tenants:End-users accessing rent payment portals and maintenance request systems as embedded platform consumers rather than direct purchasers.
Property managers command the established base. The steepest expansion runs through landlord-facing tools with unbundled subscription economics.
Deployment:
Cost tier and internal IT capability determine deployment selection, with SaaS capturing mid-market migration and hybrid architectures serving enterprises with legacy accounting dependencies.
- SaaS:Fully managed multi-tenant subscriptions with zero infrastructure ownership. Mid-size Texas operators favor these for predictable opex conversion and automatic feature rollouts.
- Hybrid:Cloud front-ends synchronized with on-premises accounting databases. Enterprise portfolios with historical Yardi or MRI investments require these during extended migration windows.
- On-Premises:Self-hosted installations retaining relevance for security-sensitive government housing authorities.
- Managed Services:Vendor-operated private cloud instances with dedicated infrastructure and custom SLA terms.
SaaS deployments command the established base. The steepest expansion runs through hybrid configurations bridging legacy accounting migrations.
Functionality:
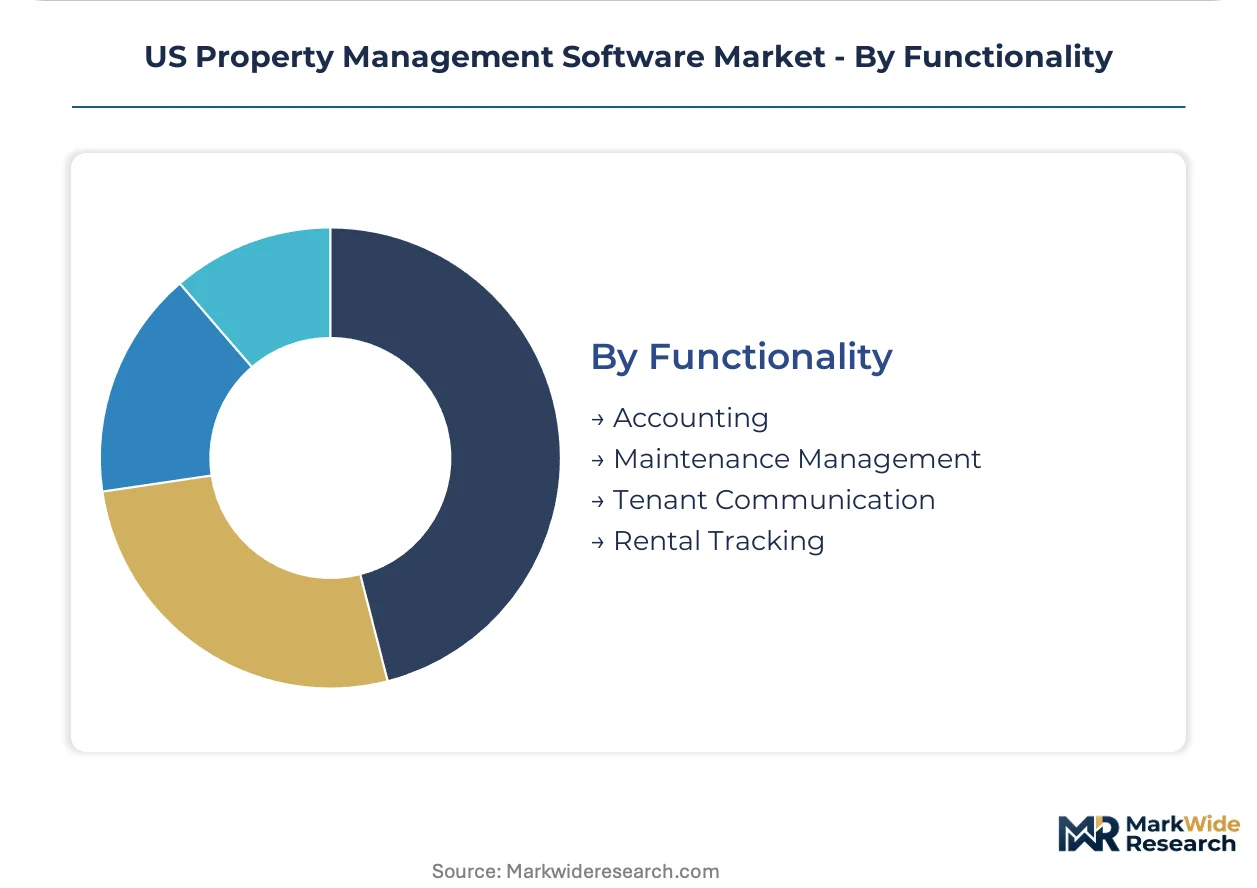
Module stickiness varies dramatically, with accounting functionality retaining users through IRS compliance integration while communication tools face higher churn.
- Accounting:GAAP-compliant general ledger with tax-specific real estate treatment and audit trail preservation. Certified property accountant scarcity makes this the stickiest module as IRS integration errors carry penalty exposure.
- Maintenance Management:Work order routing with vendor dispatch and spend tracking. Predictive capabilities based on equipment sensor data remain underdeployed outside Class A multifamily assets in Phoenix and Atlanta.
- Tenant Communication:Portal-based messaging and notification systems with mobile push delivery.
- Rental Tracking:Lease administration with rent escalation calculations tied to CPI indexing for California rent control compliance.
Accounting modules command the established base. The steepest expansion runs through maintenance management with predictive AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-markets. Independent landlords in Florida resist bundled subscriptions while Texas multifamily operators absorb premium pricing for compliance-integrated platforms. California buyers face the steepest cost escalation from overlapping regulatory mandates.
California
Multifamily operators in Los Angeles and San Francisco drive demand for automated rent control calculations tied to CPI indexing. State-level mandates from the California Department of Housing and Community Development require real-time compliance documentation. Silicon Valley technology corridors concentrate Class A asset owners deploying AI-driven yield management tools.
Texas
Dallas-Fort Worth and Houston mid-size property managers consolidate vendor relationships around integrated SaaS platforms. The Texas Department of Housing and Community Affairs enforces security deposit regulations that digitize reconciliation workflows. Austin's technology sector attracts institutional owners seeking cloud-native solutions for distributed portfolios.
Florida
Miami and Orlando independent landlords with under fifty units favor modular pricing over bundled subscriptions. The Florida Department of Business and Professional Regulation oversees property management licensing that increasingly requires software-based audit trails. Tampa Bay's growing multifamily market shows rising adoption of mobile-first maintenance dispatch tools.
New York
New York City property managers navigate overlapping state and municipal rent stabilization requirements that demand specialized compliance modules. The New York State Division of Housing and Community Renewal mandates digitized lease administration for rent-regulated units. Upstate secondary markets lag in cloud migration due to smaller portfolio scales and legacy system dependencies.
Illinois
Chicago multifamily operators balance compliance automation against implementation costs from legacy system migrations. The Illinois Department of Financial and Professional Regulation enforces property management licensing standards that increasingly reference software competency. Suburban Cook County shows emerging demand for hybrid deployments bridging on-premises accounting databases with cloud front-ends.
US Property Management Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US property management software sector. The market structure bifurcates between cloud-native platforms with AI automation capabilities and legacy incumbents with deep accounting functionality. Three strategic archetypes dominate: enterprise-suite providers, mid-market SaaS specialists, and price-competitive solutions for independent landlords. Competitive moves concentrate on M&A consolidation and vertical module extensions rather than geographic expansion.
Within the enterprise-suite tier, Yardi Voyager and RealPage OneSite exemplify deep accounting integration with verticalized extensions for institutional portfolios. AppFolio occupies a position as the mid-market multifamily specialist leveraging AI-driven automation. Buildium anchors the independent landlord segment with aggressive price positioning despite feature breadth constraints.
| Leading Market Players |
|---|
| AppFolio |
| Buildium |
| Yardi Voyager |
| Rent Manager |
| Rentec Direct |
| RealPage OneSite |
| MRI Software |
| Yardi Breeze |
| Entrata |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure economies at AWS, Microsoft Azure, and Google Cloud Platform compress unit economics for SaaS vendors while elevating price floors for on-premises alternatives. Texas and Florida mid-size operators absorb premium SaaS pricing for compliance automation, while Florida independent landlords force modular unbundling that fragments vendor revenue streams.
Pricing Analysis
Recurring subscription revenue from automated regulatory update delivery drives lifetime value far beyond initial deployment fees. Three-tier pricing structure across enterprise, mid-market, and independent landlord levels separates Yardi Voyager's deep accounting modules from AppFolio's AI-automation bundles and Buildium's stripped-down entry tiers. Price differentiation rests on compliance depth—California rent control automation commands 40-60% premiums over basic accounting packages. Cost compression in the independent landlord tier intensifies because subscription fatigue forces à-la-carte procurement. Florida landlords with under fifty units demonstrate highest price sensitivity; institutional multifamily owners in Phoenix and Atlanta show lowest sensitivity due to yield management ROI.
Supply Chain Analysis
API standardization gaps between property management platforms and smart building IoT ecosystems create integration chokepoints that slow predictive maintenance deployment. Software development labor concentrates in California, Texas, and Washington state technology corridors. Cloud infrastructure services draw from hyperscaler data centers in Virginia, Oregon, and Ohio. Raw material dependencies include semiconductor components for IoT sensors, fiber optic infrastructure for connectivity, and lithium-ion batteries for mobile field hardware. Single-source vulnerability runs through AWS dominance in multi-tenant hosting for mid-market SaaS vendors. Distribution runs through direct sales teams for enterprise accounts, digital self-serve channels for independent landlords, and value-added resellers for hybrid deployment migrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where compliance automation subscriptions and predictive maintenance modules expand faster than core accounting licenses. Recurring revenue from regulatory update delivery now exceeds perpetual license values for mid-market vendors.
For Market Incumbents: Fortify accounting module stickiness through IRS audit trail enhancements and certified property accountant training partnerships. Defend against modular unbundling by embedding compliance checkpoints that cannot be decoupled—California rent control automation and HUD Fair Housing Act documentation workflows create switching costs. Vertical integration into predictive maintenance AI, through sensor data partnerships or acquisition of IoT analytics specialists, closes the gap with RealPage's Class A asset capabilities. For New Entrants and Emerging Players: White-space in CFPB-compliant tenant screening explainability tools offers immediate penetration opportunity. Mid-size California operators face the steepest compliance curve from overlapping state and municipal mandates, making them the most penetrable segment for algorithmic transparency modules. Go-to-market through property management licensing continuing education providers embeds products into mandatory professional development channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors verticalized compliance modules over horizontal platform consolidation. Long-term viability across a five-to-ten year window favors vendors with embedded regulatory logic rather than generic workflow tools. Acquisition target archetype: AI-native maintenance dispatch specialists with proven sensor integration in Phoenix or Atlanta Class A assets. Signal to watch: municipal rent control digitization spreading beyond California and New York to Illinois and Washington jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Embedding | HUD Fair Housing Act digitization mandates create mandatory upgrade cycles for mid-market operators. |
| AI-Driven Maintenance Dispatch | Predictive work order routing based on equipment sensor data remains underdeployed outside Class A assets. |
| Carbon Accounting Integration | SEC climate disclosure rules for real estate investment trusts demand building-level emissions tracking. |
| API Standardization Leadership | Uniform data exchange protocols between platforms and smart building IoT ecosystems unlock automation depth. |
| Modular Pricing Restructuring | Florida landlord preference for à-la-carte procurement forces unbundling of accounting, marketing, and maintenance tools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with property management software executives, certified property accountants, multifamily asset managers, and CFPB compliance officers; and secondary validation through SEC filings of real estate investment trusts, HUD enforcement action databases, California Department of Housing and Community Development regulatory notices, and App Annie mobile platform analytics. Bottom-up triangulation across vendor-reported subscription metrics and top-down reconciliation against aggregate property management firm technology spend estimates anchored the market sizing.
Across the analysis window, forecasts modeled deployment model transitions, organization size tiers, vertical specialization depth, integration complexity levels, and regional regulatory stringency patterns. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including multifamily housing starts, institutional asset consolidation velocity, and state-level landlord-tenant law digitization timelines. Industry-specific inputs included cloud migration velocity indices and certified property accountant labor market scarcity metrics.
Material uncertainties—regulatory acceleration or delay in rent control digitization, CFPB rulemaking finalization on tenant screening algorithms, and hyperscaler pricing volatility for cloud infrastructure—sit outside the modeled envelope. Practitioners should keep alternative scenarios live as municipal compliance mandates evolve beyond California and New York into secondary markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Hungary Warehousing Sector Market
Property Management
Qatar Flexible Office Space Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Property Management Service Market
Property Management
Spain Warehousing Market
Property Management
United States Property Management Market
Property Management
Residential Property Management Market
Property Management
Real Estate Management Software Market
Property Management
Property Management Software Market
Property Management
South Korea Self-Storage Market
Property Management
Europe Self Storage Market
Property Management
Real Estate (Property) Management Market