
 Office Real Estate Market | 2026-2036
Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Office Real Estate Market Outlook
The EU Green Deal's building performance standards is hardening requirements for energy efficiency certifications across Class A office stock. Blackstone leverages its scale to retrofit legacy assets into compliant, high-performance workspaces. Brookfield anchors its European portfolio with net-zero carbon commitments that attract premium tenant pricing. Hines differentiates through in-house sustainability engineering that reduces operational carbon intensity.
Office real estate comprises purpose-built commercial structures designed for professional services, typically featuring floor plates of 15,000 to 40,000 square feet, centralized HVAC with smart building controls, and fiber-optic backbone infrastructure to support dense white-collar occupancy. Co-working space within property type segmentation represents the fastest-growing format as enterprise clients seek flexible term structures without capital deployment. Net lease structures command stronger investor yields by transferring operating expense volatility to tenants, while gross lease arrangements dominate in markets where landlords retain energy cost arbitrage opportunities.
EMA's environmental risk disclosure guidelines, the EU AI Act's building automation protocols, and REACH-compliant material standards collectively reshape development specifications and refinancing terms for office assets. France's CNIL enforces data protection mandates that influence smart building sensor deployments and tenant privacy architectures. Stakeholders must monitor how regulatory compliance costs transfer between landlords and tenants through lease structure negotiations.
Market Dynamics
The EU Green Deal's building performance standards are compressing lease renewals into Class A stock while retrofit capital stacks reshape lender risk appetites across institutional portfolios.
Growth Catalysts
- Hybrid work stabilization:Technology firms are expanding leased footprints as distributed team models mature, pulling demand toward flexible floor plates with embedded AV infrastructure.
- EU Green Deal retrofit mandates:Building performance standards are accelerating energy upgrade timelines, concentrating tenant demand in compliant assets with EPC A/B ratings.
- Frankfurt-Munich corridor tightness:Prime vacancy rates in Germany's financial and technology hubs remain compressed despite broader European supply overhang, supporting rent growth in certified stock.
Market Restraints
- Construction cost volatility:Steel and concrete input prices have compressed development yields, shelving speculative ground-up projects in secondary cities.
- Secondary market bifurcation:Obsolete Class B stock in peripheral locations faces stranded asset risk as tenant preferences polarize toward flight-to-quality.
- Interest rate sensitivity:Central bank policy transmission has widened cap rate spreads, freezing transaction velocity and extending hold periods for value-add strategies.
Strategic Opportunities
- Co-working enterprise pivot:Flexible term structures without capital deployment are capturing Fortune 500 satellite office demand previously served by traditional leases.
- Net lease structure expansion:Operating expense volatility transfer to tenants commands stronger investor yields in markets where underwriting favors income certainty.
- Smart building automation convergence:Sensor networks with AI-driven HVAC optimization are integrating with tenant experience platforms to command premium pricing.
Industry Challenges
- ESG data verification gaps:Carbon accounting inconsistencies across property management systems complicate green bond issuance and lender due diligence.
- Retrofit capital stack assembly:Blended finance structures combining green loans, grants, and equity remain operationally complex for mid-scale asset owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Real Estate Market |
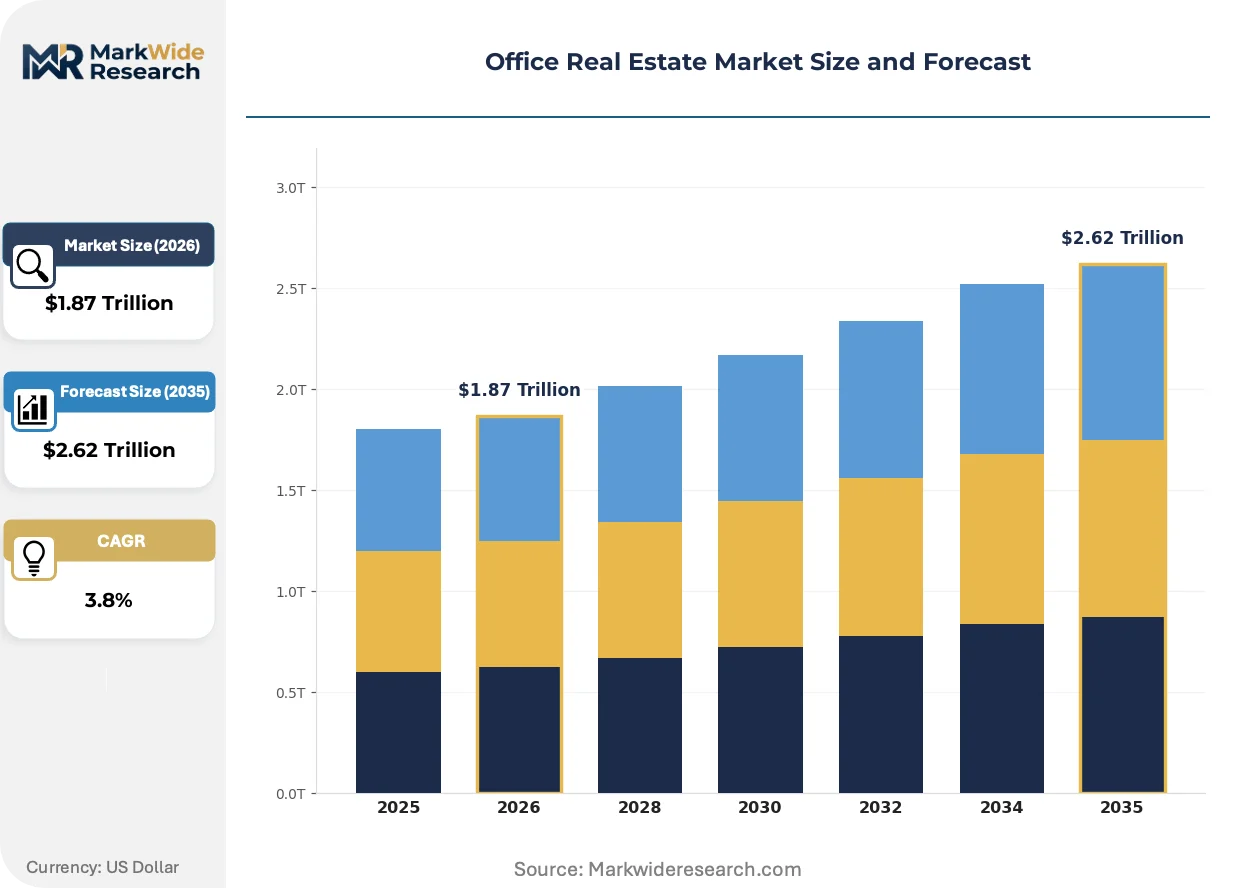
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $2.62 Trillion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: High-Rise, Mid-Rise, Low-Rise, Business Park, Co-Working Space Lease Structure: Gross Lease, Net Lease, Modified Gross Lease, Percentage Lease, Flexible Lease Tenant Industry: Technology Firms, Financial Services, Legal Services, Consulting Agencies, Creative Agencies Building Amenities: Fitness Center, Cafeteria, Conference Rooms, Parking Facilities, Security Services |
| Companies Covered | PGIM Real Estate, Nuveen Real Estate, Blackstone, Starwood Capital Group, Invesco Real Estate, Brookfield, CBRE Investment Management, LaSalle Investment Management, Hines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Real Estate Market Strategic Shifts
Building automation systems are converging with tenant wellness mandates, compressing the specification gap between operational efficiency and experiential amenities.
Smart building control platforms are integrating fiber-optic backbone infrastructure with centralized HVAC optimization to enable dense white-collar occupancy. Technology and professional services tenants are adopting these systems at accelerated procurement cycles, particularly for new leases above 15,000 square feet. The technology is integrating operational carbon intensity tracking with real-time space utilization analytics, compressing landlord reporting burdens for EU Green Deal compliance.
France's CNIL data protection mandates are reshaping sensor deployment architectures in smart office assets across the European Union. The regulation requires explicit consent frameworks for occupant tracking systems, forcing landlords to segment data collection between operational and tenant-facing functions. German and Dutch office developments are responding with privacy-by-design building automation specifications that pre-empt enforcement action.
Enterprise procurement patterns are pivoting from long-term gross leases to flexible term structures with embedded expansion options. Co-working operators and institutional landlords are capturing this demand rotation through membership-based models that unbundle traditional lease obligations. This behavioral shift is most visible in London and Berlin, where technology sector tenants are consolidating satellite offices into network-accessible flexible space portfolios.
Office Real Estate Market Segmentation
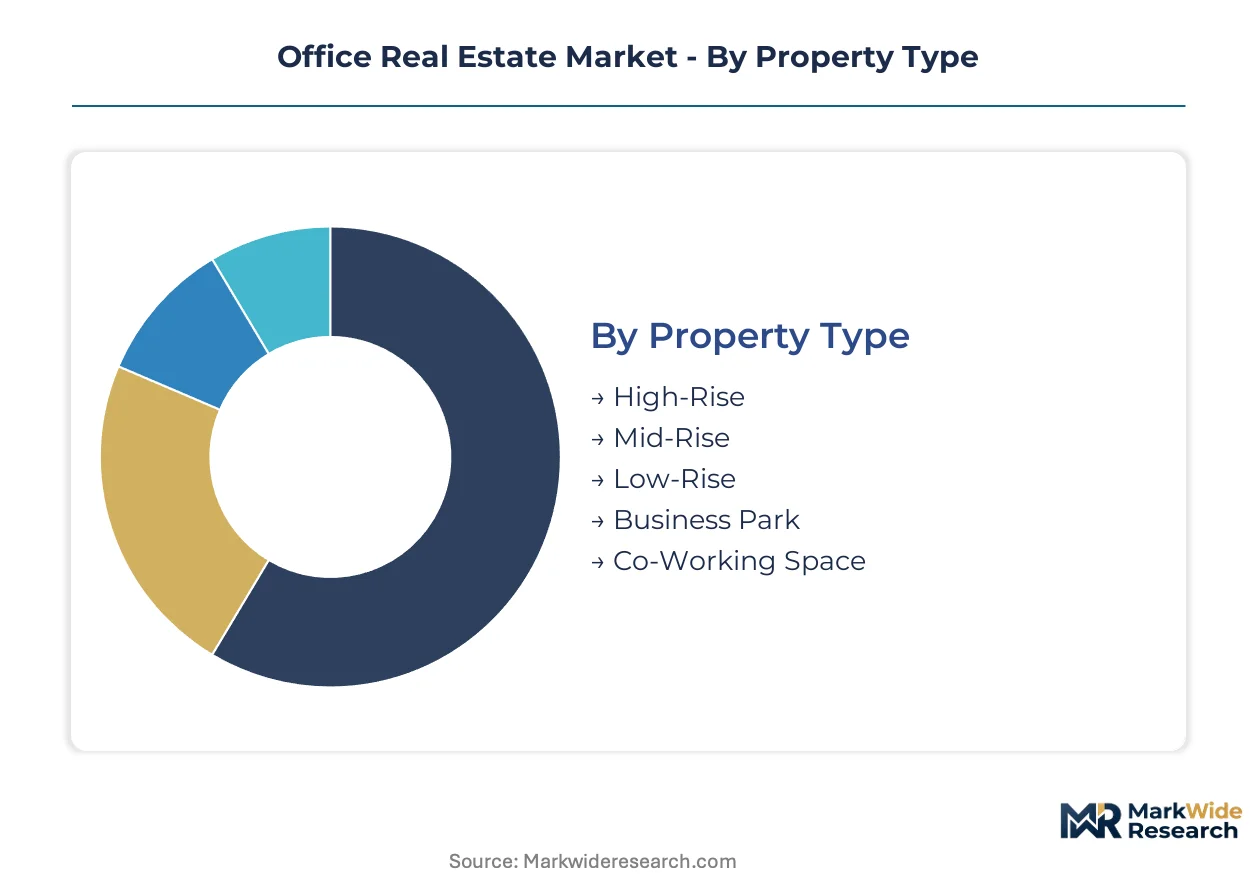
Office real estate segmentation reveals how certification burdens, lease economics, and tenant workflows concentrate value across distinct asset categories. Understanding these divisions exposes where capital deploys most efficiently and which specifications command premium pricing.
Property Type:
EU Green Deal building performance standards impose tiered certification requirements across structural categories, with high-rise and business park assets facing the most intensive EPC retrofit mandates.
- High-Rise:Structures exceeding twelve stories with centralized HVAC and fiber-optic backbone infrastructure. Frankfurt and Munich corridors concentrate demand for Class A high-rise stock as technology firms expand leased footprints for hybrid team anchoring.
- Co-Working Space:Flexible floor plate formats with embedded AV infrastructure and short-term membership models. Enterprise clients in London and Berlin are consolidating satellite offices into network-accessible portfolios, accelerating format adoption.
- Mid-Rise:Six-to-twelve story buildings common in secondary European cities. Mid-rise assets face stranded asset risk where EPC ratings lag retrofit timelines.
- Low-Rise:Suburban and peripheral market structures under six stories. Low-rise stock in obsolete Class B condition experiences tenant flight-to-quality polarization.
- Business Park:Campus-style developments with surface parking and lower density. Business parks in Germany's technology corridors attract net-zero carbon commitments from institutional landlords.
Leading the category by volume: High-Rise. Expanding most quickly: Co-Working Space.
Lease Structure:
Cost tier differentiation separates structures where landlords retain energy arbitrage from those transferring operational volatility to tenants.
- Net Lease:Operating expense obligations shift entirely to tenants, delivering income certainty to investors. Net lease structures command stronger yields in markets where underwriting prioritizes cash flow stability over appreciation.
- Gross Lease:Landlords absorb variable costs including utilities, maintenance, and property taxes. Gross lease arrangements dominate where landlords retain energy cost arbitrage opportunities in smart building controlled assets.
- Modified Gross Lease:Hybrid structures splitting specified expenses between parties. Modified gross terms accommodate mid-scale asset owners navigating EU Green Deal compliance cost transfers.
- Flexible Lease:Short-term structures with embedded expansion options and termination rights. Flexible leases capture Fortune 500 satellite office demand previously served by traditional ten-year commitments.
- Percentage Lease:Rent calculations incorporating tenant revenue performance. Percentage structures remain marginal in office markets, concentrated in retail-adjacent mixed-use developments.
Dominant by revenue stability: Net Lease. Steepest expansion trajectory: Flexible Lease.
Tenant Industry:
Application-specific fit-out requirements drive divergent specification patterns across professional services verticals.
- Technology Firms:Dense white-collar occupancy demanding floor plates of fifteen thousand to forty thousand square feet with smart building automation convergence. Technology tenants in Frankfurt and Munich are expanding leased footprints as hybrid models stabilize.
- Financial Services:Security-intensive operations with redundant fiber-optic infrastructure and trading floor specifications. Financial services concentration in Germany's financial corridor supports prime vacancy rate compression.
- Legal Services:Traditional lease preferences favoring long-term gross structures with private office density. Legal tenants lag adoption of flexible term structures, anchoring Class A core assets.
- Consulting Agencies:Project-based staffing models aligning with co-working procurement patterns. Consulting firms drive enterprise pivot toward membership-based space portfolios.
- Creative Agencies:Open-plan specifications with experiential amenity requirements including fitness and cafeteria integration. Creative tenants prioritize building amenities as workforce retention tools.
Highest rent per square foot: Financial Services. Gaining share fastest: Technology Firms.
Building Amenities:
Customer type segmentation distinguishes operational necessities from experiential differentiators in tenant retention strategies.
- Conference Rooms:AV-embedded meeting infrastructure supporting hybrid collaboration models. Technology and professional services tenants specify conference capabilities at accelerated procurement cycles for new leases above fifteen thousand square feet.
- Fitness Center:Wellness mandates integrated with building automation systems for operational efficiency. Fitness amenities compress the specification gap between carbon intensity tracking and experiential programming.
- Cafeteria:Food service infrastructure with supply chain and waste management compliance. Cafeteria operations face REACH-compliant material standards for equipment and furnishing specifications.
- Parking Facilities:Surface and structured capacity with electric vehicle charging integration. Parking ratios tighten in Germany's urban core assets where transit access substitutes for automobile dependency.
- Security Services:Access control and surveillance systems subject to France's CNIL data protection mandates. Security sensor deployments require explicit consent frameworks, forcing privacy-by-design architectures.
Most frequently specified: Conference Rooms. Fastest upgrade cycle: Fitness Center.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Munich anchor European office demand as technology firms expand leased footprints for hybrid workforce anchoring. The EU Green Deal's building performance standards are compressing tenant preferences toward EPC A/B certified stock across major metropolitan corridors.
Germany
Technology and financial services tenants are consolidating in Frankfurt's banking district and Munich's technology corridor. The EU Green Deal mandates EPC ratings for commercial stock by 2030, accelerating retrofit timelines for legacy assets. Prime vacancy rates in both cities remain compressed despite broader European supply overhang.
United Kingdom
Flexible lease structures are capturing Fortune 500 satellite office demand in London's West End and City fringe markets. The UK's MEES regulations prohibit sub-standard EPC ratings for new leases, hardening certification requirements. Technology sector tenants in Shoreditch and King's Cross are pivoting toward membership-based space portfolios.
France
Professional services firms are specifying smart building automation in Paris's La Défense and 9th arrondissement submarkets. CNIL data protection mandates require explicit consent frameworks for occupant tracking systems, forcing privacy-by-design architectures. Île-de-France developments are responding with segmented sensor deployments between operational and tenant-facing functions.
Netherlands
Enterprise clients are consolidating satellite offices into network-accessible flexible space in Amsterdam's Zuidas and Rotterdam's Kop van Zuid. REACH-compliant material standards reshape equipment specifications for fit-out and retrofit projects. Randstad corridor assets with net-zero carbon commitments command premium tenant pricing from institutional landlords.
Spain
Consulting agencies and creative firms are driving demand for experiential amenity packages in Madrid's AZCA and Barcelona's 22@ districts. The EU AI Act's building automation protocols influence development specifications for sensor networks and HVAC optimization. Mediterranean markets lag Northern European retrofit adoption, creating certification tier bifurcation.
Office Real Estate Market Competitive Environment
Premium-margin players sit above commodity-margin players across sustainability certification and tenant experience capabilities. The market structure consolidates around institutional capital platforms with scale advantages in green financing and retrofit execution. Three archetypes dominate: global asset managers with net-zero portfolio commitments, specialized office operators with flexible space platforms, and regional developers with local entitlement expertise. Competitive moves concentrate on green bond issuance for retrofit capital stacks and strategic partnerships with co-working operators for enterprise channel access.
Within the institutional capital tier, Blackstone, Brookfield, and Hines anchor market positioning through scale-driven sustainability engineering and tenant experience platform integration. Blackstone exemplifies the retrofit-focused archetype with legacy asset repositioning capabilities. Brookfield occupies a position emphasizing net-zero carbon commitments across European portfolios. Hines represents the in-house technical specialization model with operational carbon intensity reduction expertise. These entities sit within the premium-tier vector where ESG data verification and green financing access determine competitive differentiation.
| Leading Market Players |
|---|
| PGIM Real Estate |
| Nuveen Real Estate |
| Blackstone |
| Starwood Capital Group |
| Invesco Real Estate |
| Brookfield |
| CBRE Investment Management |
| LaSalle Investment Management |
| Hines |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal retrofit mandates are compressing tenant demand into EPC A/B certified stock, forcing landlords to absorb upfront capital costs or surrender pricing power in lease negotiations. This specification pressure reshapes capital stack assembly and compresses yields on non-compliant assets.
Pricing Analysis
Value-based pricing anchored to energy performance outcomes dominates Class A office markets, with landlords commanding rent premiums for net-zero carbon certified stock. Price differentiation separates EPC A/B rated assets from stranded Class B inventory, while gross lease structures in smart building controlled assets retain energy cost arbitrage. Pricing pressure stems from interest rate sensitivity widening cap rate spreads and freezing transaction velocity. Mid-scale asset owners face acute price sensitivity as retrofit financing costs erode operating margins.
Supply Chain Analysis
Workforce availability constraints in Germany, Poland, and Romania are tightening construction labor markets and extending retrofit project timelines. Steel and concrete input dependencies draw from integrated European mills and Turkish export capacity. Supply chain risk centers on single-source vulnerability for specialized HVAC automation components from German and Dutch manufacturers. Distribution runs through institutional capital platforms with direct contractor relationships, bypassing traditional general contracting tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Office real estate is consolidating around institutional platforms with green financing access, as EU Green Deal compliance costs force smaller owners into distressed sales or joint venture structures.
For Market Incumbents: To counter stranded asset risk in obsolete Class B stock, accelerate retrofit capital stack assembly combining green loans with grant funding. Deepen backward integration into in-house sustainability engineering capabilities to reduce operational carbon intensity and command tenant rent premiums. For New Entrants and Emerging Players: Launch via flexible space platforms targeting Fortune 500 satellite office demand in London and Berlin corridor markets. White-space opportunity concentrates in co-working enterprise pivot formats with embedded AV infrastructure and short-term membership models. For Investors and Strategic Acquirers: The window for entry favors mid-scale asset owners with local entitlement expertise and EPC upgrade pathways. Long-term viability hinges on green bond issuance capacity and retrofit execution scale. Monitor prime vacancy rate compression in Frankfurt and Munich as inflection indicator for rent growth sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Green Bond Issuance | Unlocks blended finance structures for EU Green Deal retrofit mandates across institutional portfolios. |
| Net-Zero Carbon Certification | Brookfield and Hines anchor European positioning through portfolio-wide decarbonization commitments. |
| Smart Building Automation Integration | Sensor networks with AI-driven HVAC optimization command premium tenant pricing from technology firms. |
| Flexible Space Platform Partnership | Co-working operators capture enterprise pivot demand previously served by traditional ten-year leases. |
| Retrofit Capital Stack Assembly | Blackstone leverages scale advantages to reposition legacy assets into compliant high-performance workspaces. |
Study Parameters
Regulatory filings, property transaction databases, and energy certification registries formed the secondary backbone, supplemented by primary interviews with asset managers, sustainability directors, tenant representation brokers, and construction procurement leads. Bottom-up and top-down triangulation validated market sizing across property type, lease structure, and tenant industry segmentation dimensions.
Bottom-up tenant demand modeling and top-down capital flow analysis converged across the analysis window. Segmentation dimensions included property type, lease structure, tenant industry, and building amenity specifications. CAGRs derived from historical transaction velocity patterns and forward-looking retrofit adoption curves, with inputs from central bank policy transmission effects and construction cost indices.
The model assumes a particular technology adoption path; alternative pathways for smart building automation convergence would alter the outlook. Forecasts reflect assumptions on hybrid work stabilization and EU Green Deal enforcement timelines. Material deviation in interest rate policy or EPC retrofit cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Flexible Office Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market