
 Canada Condominiums and Apartments Market | 2026-2036
Canada Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Condominiums and Apartments Market Analysis
Mass timber engineering is rewriting construction economics for mid-rise residential buildings across Canadian urban centers. Onni Group leverages prefabricated panel systems to compress project timelines in Vancouver and Toronto. Concert Properties Ltd anchors its pipeline with purpose-built rental assets in transit-oriented locations. Tridel differentiates through in-house manufacturing of building envelope components that reduce operational carbon intensity.
Canada condominiums and apartments comprise multi-unit residential structures ranging from four-storey wood-frame walk-ups to forty-storey concrete high-rises, engineered to National Building Code fire-resistance ratings and seismic design standards for occupant safety and structural longevity. High-rise product type commands premium pricing in supply-constrained downtown cores while mid-range price tier captures volume from first-time buyers priced out of detached housing. Townhouse configurations attract family demographics seeking ground-oriented density without single-family maintenance burdens.
Health Canada and the Canada Mortgage and Housing Corporation shape market access through national housing strategy funding thresholds and indoor air quality ventilation mandates. Provincial regulators in Ontario and British Columbia enforce energy step codes that tighten thermal performance requirements incrementally. Municipal zoning bylaws in Toronto and Vancouver determine permissible density and therefore project feasibility. Stakeholders must monitor how upcoming federal GST relief on rental construction interacts with local development charge escalations to preserve project pro formas.
Market Dynamics
Canada's National Building Code updates and provincial energy step codes are compressing permissible construction timelines while elevating material performance thresholds, forcing developers to front-load engineering decisions and lock supply chains earlier in project cycles.
Growth Catalysts
- Mass timber engineering:Prefabricated CLT and glulam systems slash on-site labor hours and enable six-storey wood-frame construction under amended NBC provisions, opening mid-rise density in Vancouver and Toronto suburbs previously zoned for concrete.
- Federal GST relief on purpose-built rental:The 2023 removal of federal sales tax on new rental construction improves project pro formas for institutional investors targeting transit-oriented sites in Montreal and Calgary.
- Young professional household formation:Demographic concentration in downtown cores sustains absorption rates for studio and one-bedroom product despite interest rate volatility.
Market Restraints
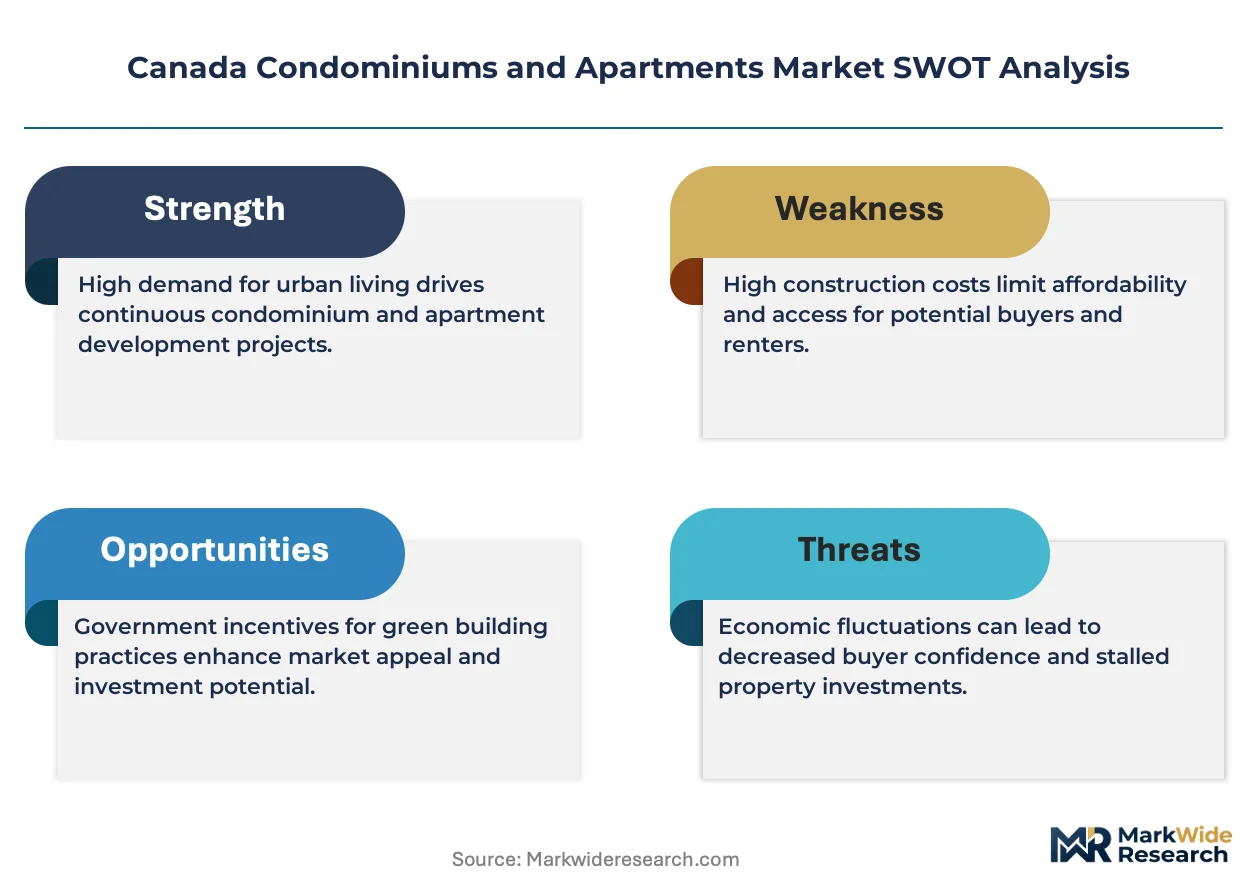
- Development charge escalation:Municipal infrastructure levies in Toronto and Vancouver have doubled since 2019, absorbing margin that would otherwise fund amenity upgrades or below-market units.
- Concrete supply concentration:Three producers control eighty percent of ready-mix supply in British Columbia's Lower Mainland, exposing projects to price volatility and allocation risk during peak pour seasons.
- Seismic design complexity:Vancouver's high seismic zone requirements mandate performance-based engineering that extends permitting timelines by four to six months versus comparable Toronto projects.
Strategic Opportunities
- Alberta secondary cities:Calgary and Edmonton zoning reforms permit four-storey wood-frame by-right in established neighborhoods, creating first-mover advantage for developers with prefabrication partnerships.
- Deep energy retrofits:Canada Mortgage and Housing Corporation's Greener Affordable Housing program subsidizes envelope and mechanical upgrades in 1970s rental stock, opening retrofit-as-investment models.
- Co-living and micro-unit formats:Unmet demand from international students and remote workers in Montreal and Ottawa supports specialized operators with furnished, short-lease product.
Industry Challenges
- Mass timber skilled labor scarcity:Certified CLT installers and fire-stopping specialists command premium wages, constraining project ramp rates in Ontario and Quebec.
- Energy step code compliance timelines:British Columbia's 2024 Step 4 thermal performance requirements demand earlier mechanical contractor engagement, compressing design-development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Condominiums and Apartments Market |
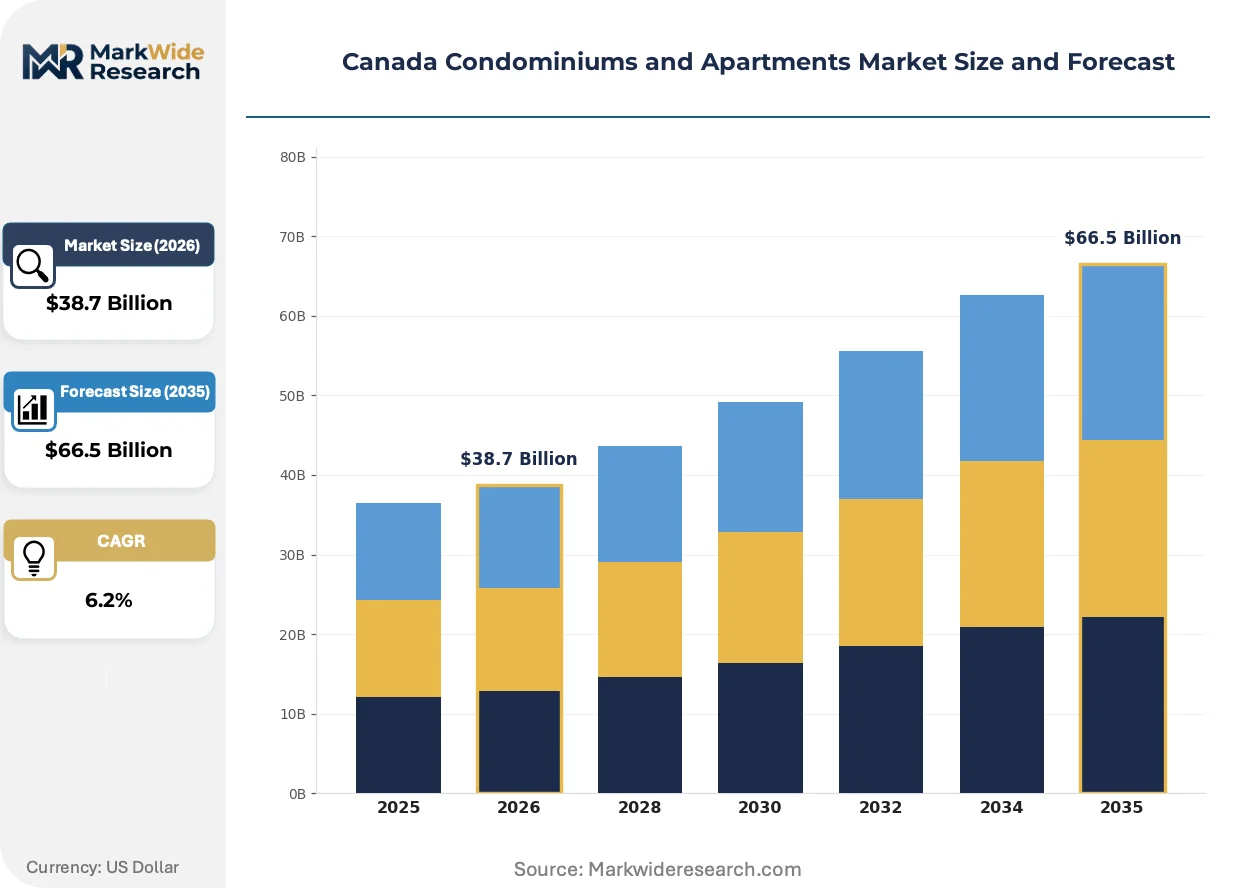
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $66.5 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-rise, Low-rise, Townhouse, Duplex Price Tier: Luxury, Mid-range, Budget, Affordable Ownership Model: Freehold, Leasehold, Shared Ownership, Timeshare Target Demographic: Young Professionals, Families, Retirees, Investors |
| Companies Covered | Onni Group, Concert Properties Ltd, The Minto Group, Aquilini Development, Bosa Properties, Tridel, InterRent REIT, Crestpoint Real Estate Investments Ltd, Mondev, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Condominiums and Apartments Market Emerging Trajectories
Construction methodology and procurement patterns are diverging sharply between high-rise concrete towers and mid-rise wood-frame product, with technology adoption curves splitting along building height and geographic seismic risk.
Cross-laminated timber and hybrid mass timber systems are collapsing the cost gap between four-storey stick-frame and eight-storey concrete construction in Ontario and British Columbia. Mid-rise developers in Ottawa and Victoria are specifying CLT floor plates to accelerate structural rough-in and reduce crane time. The technology is collapsing traditional height-to-cost curves that previously favored concrete above six storeys, enabling wood-frame competitive positioning in eight-to-twelve-storey zones.
Health Canada's 2023 indoor air quality ventilation mandates and British Columbia's Energy Step Code are tightening mechanical system specifications simultaneously. Developers must now specify heat-recovery ventilators and higher-efficiency filtration in all new rental stock, adding mechanical room footprint requirements. The policy shift most affects Vancouver's compact tower sites where floor plate efficiency directly determines unit counts.
Institutional capital is consolidating rental ownership through portfolio acquisitions rather than ground-up development, shifting developer business models toward fee-based construction management. Pension funds and REITs in Toronto and Montreal are underwriting long-hold assets with in-house property management capabilities. This capital rotation is most visible in Vancouver's downtown peninsula, where 2023-2024 transactions concentrated ownership among four institutional holders.
Canada Condominiums and Apartments Market Segmentation
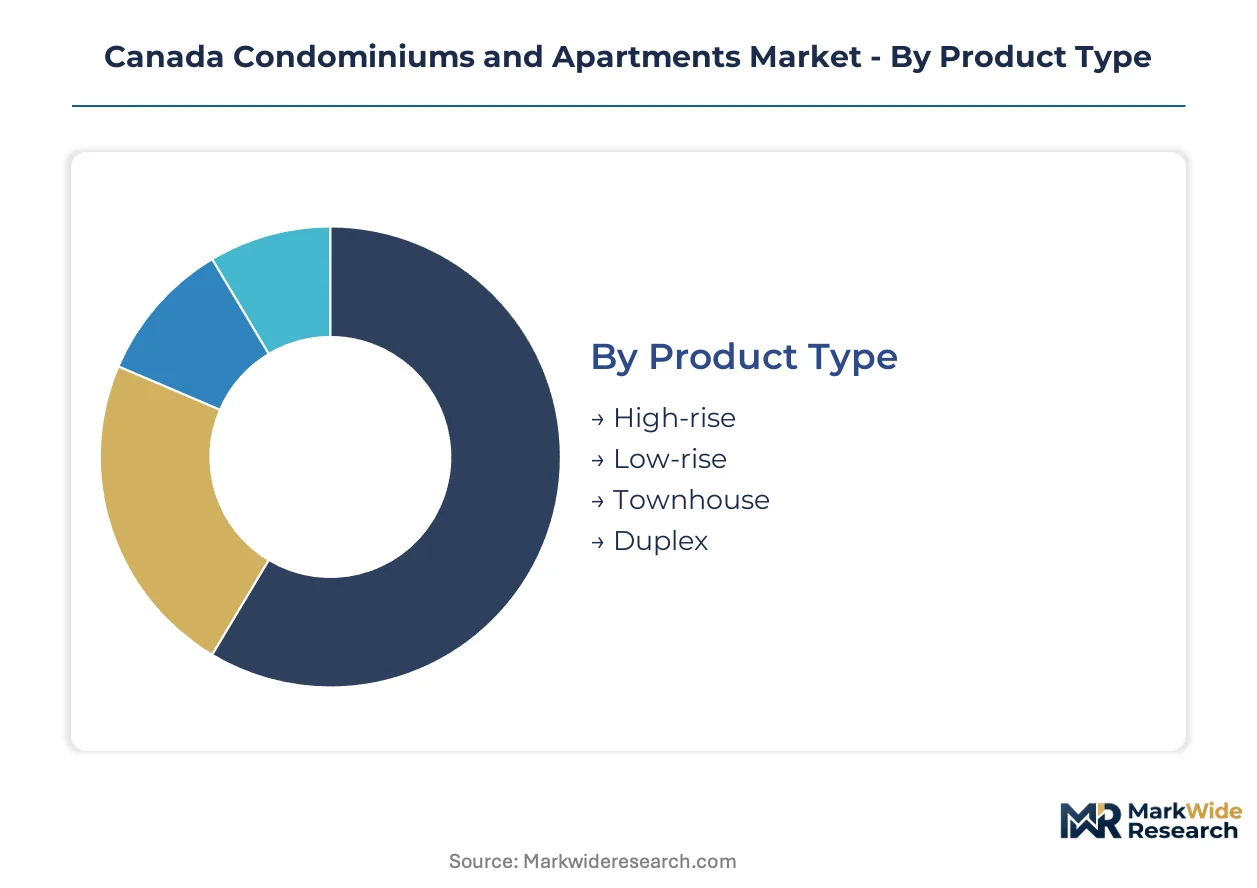
Segmentation in Canadian multi-unit residential development determines financing structures, municipal approval pathways, and marketing strategies. Product type and ownership model selections directly impact construction methodology, while price tier and demographic targeting shape absorption rates in supply-constrained markets.
Product Type:
Use-case spectrum spans downtown workforce housing to suburban family-oriented density, with structural systems and zoning entitlements varying sharply by height and configuration.
- High-rise:Concrete or steel-frame towers exceeding twelve storeys engineered to National Building Code seismic and fire-resistance standards. Demand concentrates in Vancouver's downtown peninsula and Toronto's core where land scarcity justifies vertical construction premiums and transit proximity supports unit absorption.
- Low-rise:Wood-frame structures up to six storeys leveraging amended NBC provisions for mid-rise density. British Columbia's Lower Mainland and Ontario's 905-region municipalities are absorbing this product fastest as mass timber engineering collapses cost premiums versus concrete alternatives.
- Townhouse:Ground-oriented multi-level units sharing party walls with individual exterior entrances. Ground-oriented density attracts family demographics in Calgary and Ottawa suburbs seeking maintenance-free alternatives to detached housing.
- Duplex:Two-unit structures on single lots, often created through lot severance or infill development. Toronto and Vancouver permit duplex by-right in formerly single-family zones, unlocking gentle density in established neighborhoods.
The dominant share belongs to High-rise, while Low-rise is closing the gap fastest as mass timber codes expand permissible height for wood-frame construction.
Price Tier:
Cost stratification aligns with location premiums, amenity packages, and finish specifications, with financing accessibility and investor yield requirements driving tier selection.
- Luxury:Units commanding top-quartile pricing per square foot with concierge services, premium appliances, and branded amenity programming. Vancouver's Coal Harbour and Toronto's Yorkville concentrate this inventory where international capital and executive relocation sustain absorption.
- Mid-range:Product targeting household incomes at regional medians with standard finishes and shared amenity provision. Greater Toronto Area suburban nodes and Montreal's Griffintown are expanding this tier fastest as first-time buyers exit detached housing markets.
- Budget:Entry-level condominiums with compact floor plates and minimal amenity load, often in emerging transit corridors. Edmonton and Calgary's LRT-adjacent sites absorb this product from young professionals prioritizing location over space.
- Affordable:Units with income-tested eligibility or below-market pricing secured through municipal inclusionary zoning or CMHC financing programs. Non-profit and co-operative developers in Ottawa and Halifax specialize in this segment with layered government subsidy stacks.
Mid-range captures the deepest buyer pool, though Affordable is expanding most quickly through federal National Housing Strategy commitments and provincial enabling legislation.
Ownership Model:
Title structure determines resident control, financing options, and long-term asset management responsibilities, with regulatory frameworks varying by province.
- Freehold:Fee-simple ownership of individual units with proportional common element interests, governed by condominium corporations under provincial legislation. Standard model across Ontario and British Columbia high-rise and townhouse developments.
- Leasehold:Long-term ground lease arrangements where residents own structures but lease land, common in Vancouver's University Endowment Lands and some First Nations development partnerships.
- Shared Ownership:Fractional title structures with rotating occupancy rights, emerging in recreational markets like Whistler and Collingwood where seasonal use patterns dominate.
- Timeshare:Deeded or right-to-use vacation ownership with fixed or floating week structures. Limited presence in Canadian markets compared to US sunbelt destinations, concentrated in Banff and Mont-Tremblant resort zones.
Freehold structures dominate transaction volume, while Leasehold is gaining share fastest in land-constrained Vancouver markets with institutional landholders.
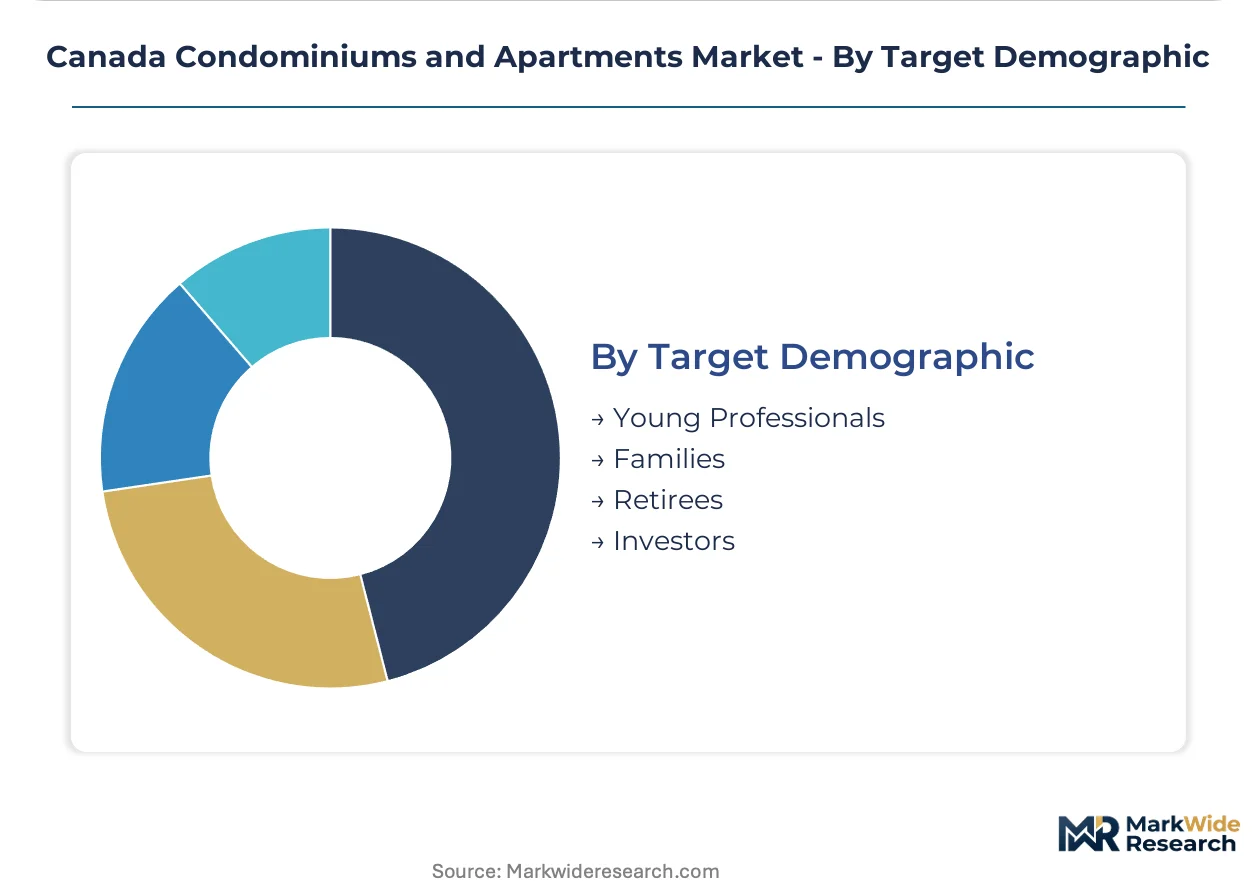
Target Demographic:
Household composition and life-stage requirements dictate unit sizing, location preferences, and amenity programming, with developers aligning product to migration and formation trends.
- Young Professionals:Studio and one-bedroom product in transit-oriented locations with co-working amenities and minimal parking provision. Toronto's King West and Montreal's Plateau absorb this demographic concentration.
- Families:Two and three-bedroom units with proximity to schools, parks, and family-oriented retail. Vancouver's Cambie Corridor and Calgary's inner suburbs are rezoning to accommodate this underserved demand.
- Retirees:Right-sized units with accessibility features, healthcare proximity, and low-maintenance living. Victoria and Ottawa retirement condominium pipelines are expanding to serve aging demographic bulges.
- Investors:Cash-flow-focused purchasers prioritizing rental yield potential and vacancy rate resilience. Toronto and Vancouver pre-construction sales rely heavily on this buyer segment for project capitalization.
Young Professionals anchor absorption in downtown cores, though Families are climbing the fastest as municipal zoning reforms enable larger units in transit-served neighborhoods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals concentrate in Ontario and British Columbia's major metros, driving absorption for compact units near transit corridors. Family households are expanding fastest in Alberta and Quebec as zoning reforms enable larger floor plates. Retiree demand anchors activity in Atlantic Canada and Vancouver Island markets.
Ontario
The Greater Toronto Area absorbs the highest condominium pre-construction sales volumes nationally, with first-time buyers exiting detached housing markets. Health Canada ventilation mandates and the National Building Code updates compress development timelines for mid-rise wood-frame projects. Ottawa's LRT corridor is rezoning for four-storey density, opening gentle infill opportunities previously restricted to single-family.
British Columbia
Vancouver's downtown peninsula and Burnaby's Metrotown cluster sustain premium pricing for concrete high-rise product despite interest rate headwinds. The province's Energy Step Code Step 4 thermal performance requirements demand earlier mechanical contractor engagement, extending design phases. Victoria's mid-rise pipeline is accelerating as mass timber engineering collapses cost premiums versus concrete alternatives.
Alberta
Calgary and Edmonton zoning reforms permit four-storey wood-frame by-right in established neighborhoods, creating first-mover advantage for prefabrication partnerships. The federal GST relief on purpose-built rental improves project pro formas for institutional investors targeting LRT-adjacent sites. Beltline and Inglewood districts are absorbing purpose-built rental product fastest among young professional demographics.
Quebec
Montreal's Griffintown and Plateau neighborhoods concentrate young professional demand for studio and one-bedroom product with minimal parking provision. The province's building code adoption of NBC mid-rise wood-frame provisions lags Ontario by eighteen months, compressing project timelines. Laval and Longueuil are expanding mid-range price tier inventory as first-time buyers exit Montreal's escalating downtown core.
Atlantic Canada
Halifax and Moncton are capturing retiree migration from Ontario and Quebec, driving right-sized unit demand with healthcare proximity. CMHC's Greener Affordable Housing program subsidizes envelope retrofits in 1970s rental stock across the region. Charlottetown's limited developable land is concentrating ownership among institutional holders pursuing long-hold assets.
Canada Condominiums and Apartments Market Vendor Landscape
Channel-controlling players compete with product-specialist players across Canada's multi-unit residential sector. Institutional capital is consolidating rental ownership through portfolio acquisitions rather than ground-up development, shifting developer business models toward fee-based construction management. Three strategic archetypes dominate: vertically integrated developers with in-house manufacturing capabilities, pension fund-backed platforms with long-hold asset strategies, and specialized mid-rise operators leveraging mass timber prefabrication. Competitive moves concentrate on transit-oriented site assembly and energy step code compliance partnerships.
Among Vancouver-based developers with scale-driven positioning, Onni Group and Concert Properties Ltd exemplify the channel-controlling archetype through portfolio breadth across multiple Canadian metros. Tridel anchors the product-specialist tier with differentiated positioning in building envelope component manufacturing. These three entities represent the dominant competitive configurations in a market where institutional capital rotation is compressing development margins and rewarding operational efficiency.
| Leading Market Players |
|---|
| Onni Group |
| Concert Properties Ltd |
| The Minto Group |
| Aquilini Development |
| Bosa Properties |
| Tridel |
| InterRent REIT |
| Crestpoint Real Estate Investments Ltd |
| Mondev |
| Others |
Supply Flow & Price Mechanics
British Columbia's Lower Mainland concrete producers command outsized pricing power over Vancouver high-rise projects, with three suppliers controlling ready-mix allocation during peak pour seasons and transmitting commodity volatility directly into construction pro formas. This concentration forces developers to lock supply contracts earlier in project cycles, compressing design-development flexibility and elevating material cost contingencies.
Pricing Analysis
Fixed-price contracts with quarterly steel and concrete indexation dominate Vancouver and Toronto high-rise procurement, with developers bearing commodity swing risk through completion. Price differentiation separates concrete-frame downtown towers from mass timber mid-rise product in Burnaby and Mississauga, where prefabrication partnerships reduce labor hour exposure. Cost compression in mid-range condominiums is intensifying as municipal development charges absorb margin that previously funded amenity upgrades. First-time buyers in Calgary and Edmonton exhibit highest price sensitivity, while institutional investors in Toronto's purpose-built rental segment prioritize yield stability over per-square-foot acquisition cost.
Supply Chain Analysis
Cross-laminated timber feedstock draws from Quebec and British Columbia forest products mills, with glulam beam production concentrated in Ontario manufacturing facilities. Structural steel and concrete admixtures rest on integrated North American supply networks, while mechanical ventilation equipment hinges on Asian component sourcing for heat-recovery ventilators. Single-source vulnerability concentrates in seismic-grade rebar certification, where domestic producers hold exclusive National Building Code approval for Vancouver high-rise applications. Distribution runs through developer-direct procurement for major projects, with regional distributors serving mid-rise wood-frame builders in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's condominium and apartment market sits in early-cycle expansion as mass timber engineering penetrates mid-rise zones previously reserved for concrete construction, with federal GST relief on rental product accelerating institutional capital deployment into purpose-built assets.
For Market Incumbents: Pre-empt margin erosion in Vancouver and Toronto concrete high-rise segments by securing captive CLT panel supply through Quebec mill partnerships, insulating project pipelines from ready-mix allocation risk. Deepen backward integration into building envelope component manufacturing to capture energy step code compliance premiums that municipal regulators are mandating across British Columbia and Ontario. For New Entrants and Emerging Players: Build out prefabrication partnerships targeting Calgary and Edmonton four-storey wood-frame by-right zoning reforms, where established neighborhood infill offers first-mover site assembly advantages. Alberta secondary cities represent the most penetrable geography, with LRT-adjacent parcels absorbing purpose-built rental product from young professional demographics underserved by incumbent development pipelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mass timber-enabled developers with in-house manufacturing capabilities over traditional concrete-centric platforms, as building code amendments displace structural systems across six-to-twelve-storey height bands. Long-term viability favors acquisition targets with secured timber feedstock and certified installer networks. The signal to watch is British Columbia Energy Step Code adoption velocity in Ontario and Quebec, which would accelerate mechanical system specification changes and reward early compliance investment.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Prefabrication Partnership | CLT panel supply agreements compress Vancouver project timelines by eliminating concrete pour sequencing constraints. |
| Energy Step Code Compliance Investment | Early mechanical contractor engagement secures Step 4 thermal performance certification ahead of British Columbia mandate expansion. |
| Transit-Oriented Site Assembly | LRT-adjacent parcel accumulation in Calgary Beltline positions developers for federal GST relief capture on rental product. |
| Building Envelope Manufacturing Integration | In-house component production reduces operational carbon intensity and differentiates Toronto pre-construction marketing. |
| Purpose-Built Rental Portfolio Acquisition | Institutional ownership consolidation in Vancouver downtown peninsula captures long-hold yield from constrained supply dynamics. |
Methodological Framework
The analysis maps high-rise concrete, mid-rise mass timber, townhouse, and duplex product segments, each validated through development executives, municipal planning officers, and institutional investment directors. Primary interviews with general contractors, CLT installers, and CMHC program administrators combined with secondary validation against National Building Code amendment records, provincial energy step code adoption timelines, and municipal zoning bylaw databases. Bottom-up project pipeline enumeration and top-down construction value triangulation anchored market sizing.
Assumptions held federal GST relief on rental construction and mass timber height allowances fixed at announced policy settings, while interest rate trajectories and municipal development charge escalations varied across sensitivity scenarios. Segmentation modeling spanned product type, price tier, ownership structure, and target demographic dimensions. CAGRs derived from project absorption rate analysis and construction cost forecasting, with inputs from concrete and engineered wood products pricing indices and demographic household formation projections.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by pension fund-backed platforms would shift outcomes through accelerated portfolio consolidation. Cross-checking against CMHC housing starts data and municipal building permit issuance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market