
 Taiwan Facility Management Services Market | 2026-2036
Taiwan Facility Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Facility Management Services Market Insights
The shift from single-source to multi-source vendor arrangements is recalibrating procurement strategies across Taiwan's industrial estates. ISS A/S leverages its integrated service platform to compete for bundled hard and soft service contracts in Kaohsiung's port logistics zone. CBRE Group anchors its position through technology-led asset tracking systems for commercial complexes in Taipei. AssetPlus Taiwan Limited specializes in localized compliance management for government building portfolios.
Facility management services encompass the coordinated planning, delivery, and oversight of building operations, maintenance, and workplace support functions, typically governed by ISO 41001 standards for facility management systems and Taiwan's own green building certification protocols. These services ensure operational continuity, regulatory compliance, and energy performance across built environments ranging from semiconductor cleanrooms to hospitality venues. Hard services currently dominate revenue contribution due to the specialized mechanical and electrical demands of Taiwan's science parks, while energy management represents the fastest-expanding segment as industrial plants face escalating electricity costs and carbon accountability requirements under the country's net-zero pathway. The delivery model landscape shows managed services gaining traction among corporate offices seeking outcome-based contracts rather than conventional time-and-materials arrangements.
Taiwan's Ministry of Economic Affairs enforces industrial safety standards through the Occupational Safety and Health Administration, while the Environmental Protection Administration administers building energy codes that directly shape service procurement specifications for large facilities. The Bureau of Energy under the Ministry of Economic Affairs further mandates energy management system compliance for designated energy users, creating structured demand for specialized facility management expertise. Stakeholders must monitor how forthcoming amendments to green building regulations will redefine minimum service thresholds and certification maintenance obligations.
Market Dynamics
ISO 41001 certification mandates and Taiwan's net-zero pathway are compressing vendor qualification timelines while elevating energy management system requirements across science park facilities.
Growth Catalysts
- Hsinchu Science Park expansion:Semiconductor cleanroom maintenance contracts are scaling as fabrication capacity adds specialized hard service demand.
- Green Building Label requirements:Taiwan's certification protocols mandate continuous energy performance monitoring, creating structured procurement for integrated facility management.
- Electricity cost escalation:Industrial rate pressures from Taipower are accelerating energy management system adoption among designated large energy users.
Market Restraints
- Skilled technician scarcity:Certified HVAC and electrical specialists concentrate in Taipei, leaving Taichung and Kaohsiung facilities exposed to wage inflation.
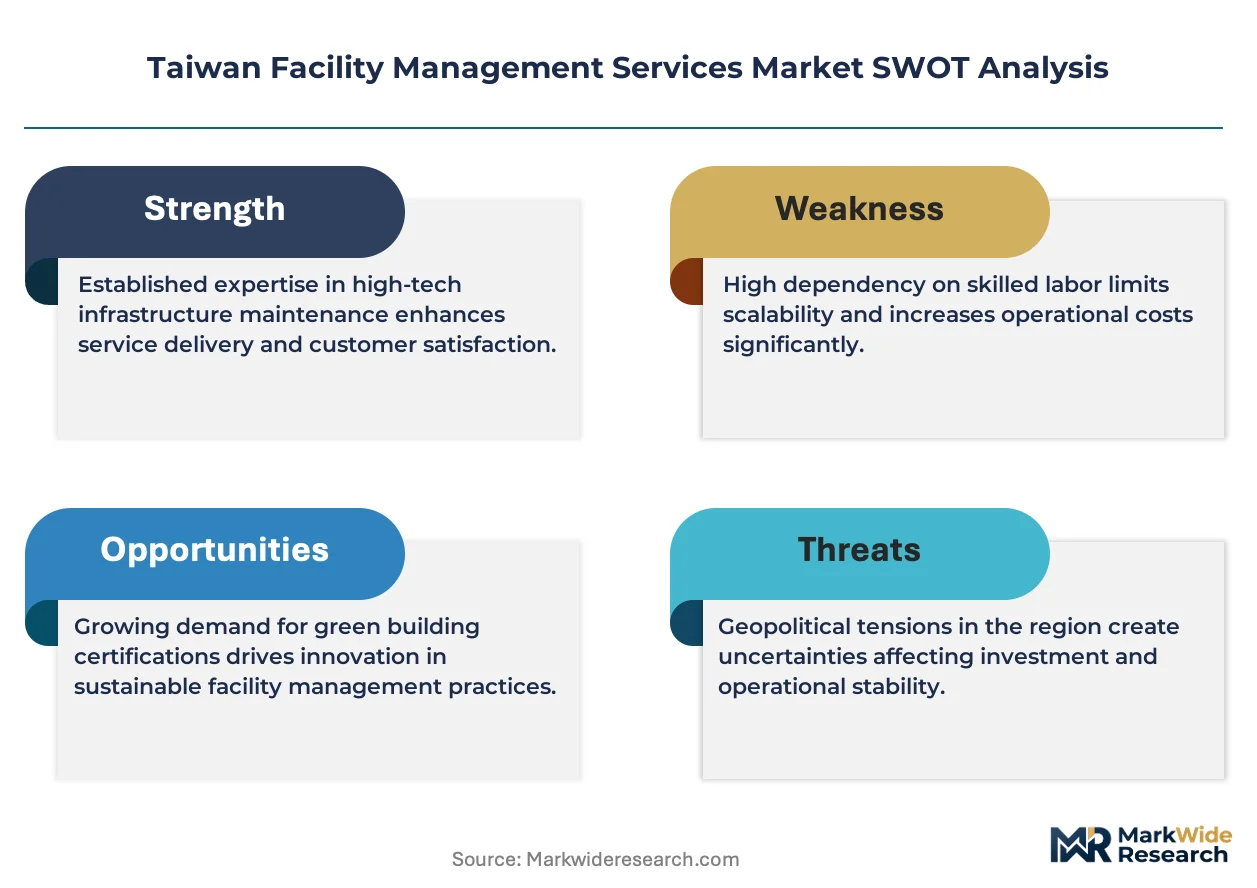
- Equipment import dependency:Advanced building automation systems and IoT sensors rely predominantly on Japanese and German suppliers, creating currency exposure.
- Green certification timeline friction:Taiwan's Environmental Protection Administration review cycles for building energy code compliance extend vendor onboarding by four to six months.
Strategic Opportunities
- Taichung precision machinery corridor:Automated factory retrofits are generating demand for predictive maintenance platforms that integrate with existing CNC equipment.
- Kaohsiung port logistics zone:Cold chain warehouse expansion is opening specialized refrigeration and environmental control service contracts.
- Carbon accounting convergence:Integration of ISO 50001 energy management with Taiwan's forthcoming carbon footprint disclosure rules is creating bundled compliance service demand.
Industry Challenges
- Multi-vendor integration complexity:Facilities mixing ISS A/S, CBRE Group, and local specialists face data silos across incompatible asset tracking platforms.
- Cleanroom certification maintenance:Semiconductor fabs require continuous ISO 14644 compliance verification, compressing response windows for mechanical failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Facility Management Services Market |
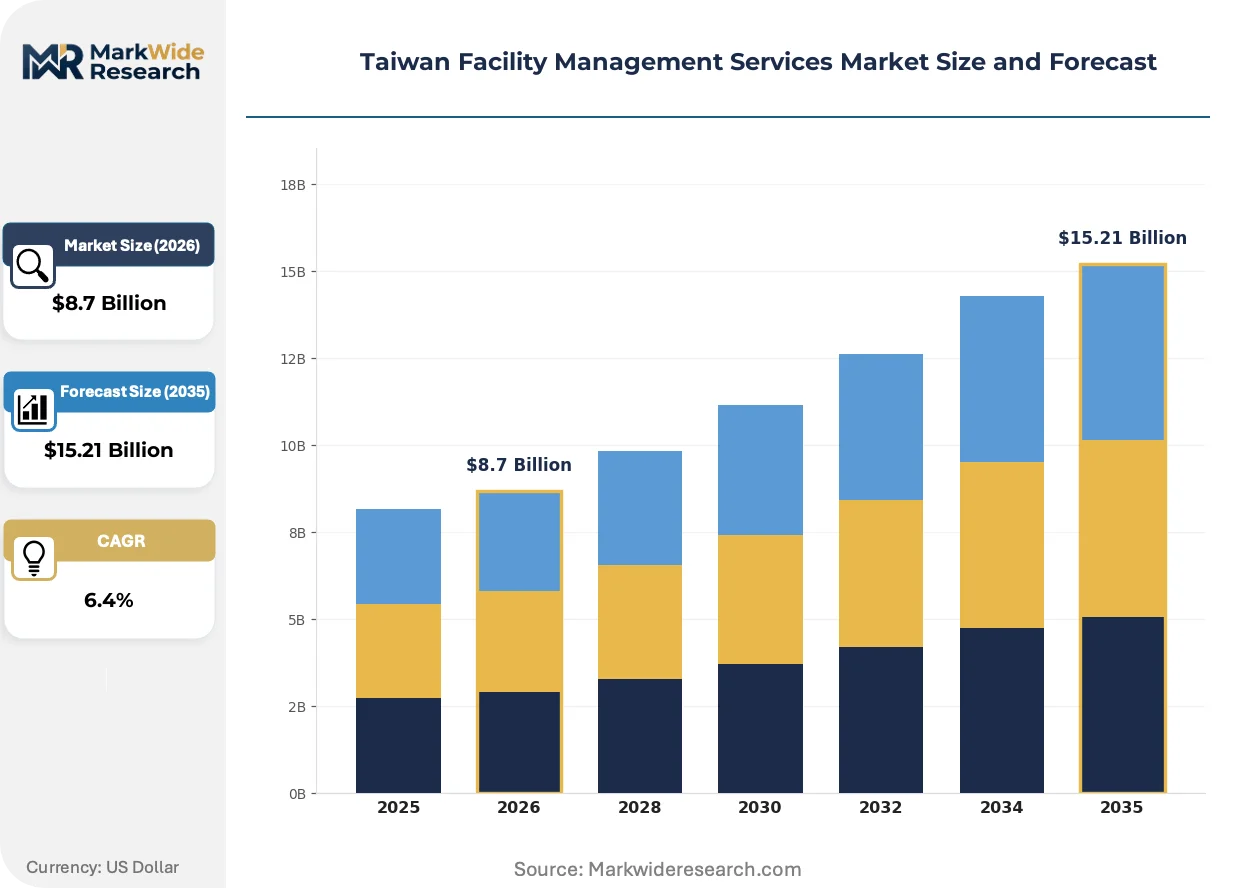
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hard Services, Soft Services, Security Services, Consulting Services, Energy Management Application Sector: Commercial Complexes, Educational Institutes, Government Buildings, Hospitality Venues, Logistics Centers Customer Category: Corporate Offices, Public Sector Entities, Industrial Plants, Retail Chains, Non-Profit Organizations Delivery Model: Onsite Services, Remote Monitoring, Managed Services, Contracted Maintenance, Partnership Solutions |
| Companies Covered | CBRE Group, Diversey Holdings Ltd, Jones Lang LaSalle IP, Inc, ISS A/S, Rentokil Initial Plc, Cushman & Wakefield Inc, AssetPlus Taiwan Limited, ABV Integrated Facility Services, G4S Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Facility Management Services Market Trends and Innovations
Digital twin deployment and predictive analytics are restructuring how Taiwan's industrial estates monitor asset health, shifting maintenance from reactive interventions to continuous optimization loops.
Building information modeling integrated with IoT sensor networks is electrifying facility oversight across Taipei's commercial complexes. Property managers in Xinyi District are deploying real-time energy dashboards that aggregate HVAC, lighting, and elevator performance into unified control interfaces. This convergence is compressing the traditional separation between hard services and energy management into single-platform contracts.
Taiwan's Bureau of Energy is tightening enforcement of the Energy Management System compliance mandate for designated large energy users. Industrial facilities consuming over 800 kiloliters of oil equivalent annually must now submit verified energy conservation implementation plans. Semiconductor cleanrooms in Hsinchu are responding by embedding continuous commissioning protocols into standard service level agreements.
Asset owners are unbundling long-term integrated contracts into modular service components with discrete performance metrics. Science park administrators are separating mechanical maintenance from energy optimization and workplace experience management into distinct procurement lots. This fragmentation is most pronounced in Taichung's precision machinery cluster, where factory operators prefer specialized vendors for each technical domain over single-source arrangements.
Taiwan Facility Management Services Market Segmentation
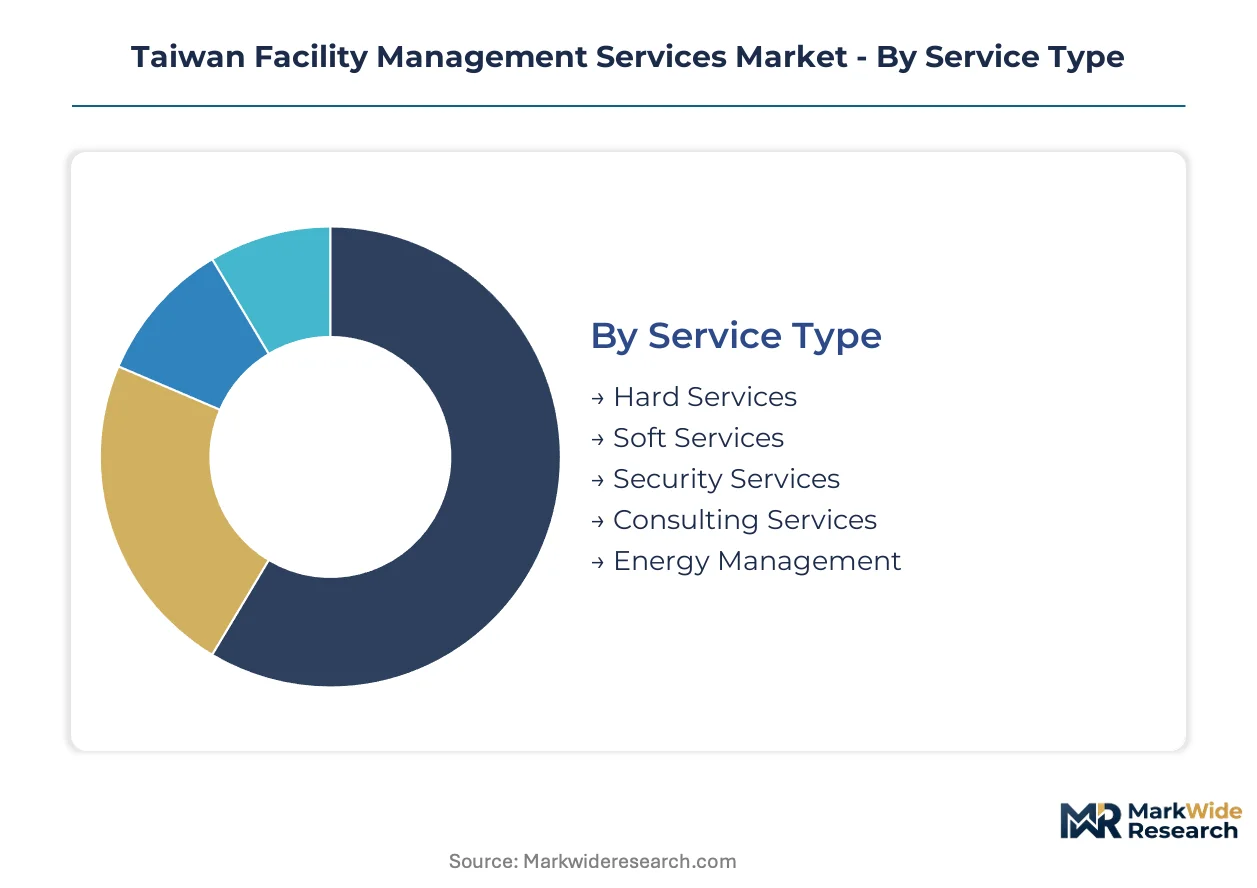
Segmentation in Taiwan's facility management market reveals how certification burdens concentrate differently across service types and customer categories. Procurement officers in Hsinchu Science Park weigh ISO 41001 compliance more heavily than retail operators in Taipei, creating divergent vendor qualification pathways.
Service Type:
ISO 41001 mandates and Taiwan's Green Building Label requirements impose distinct certification loads across service categories, with energy-intensive segments facing Bureau of Energy enforcement while soft services navigate lighter regulatory touchpoints.
- Hard Services:Mechanical, electrical, and HVAC maintenance operations governed by Occupational Safety and Health Administration standards. Demand clusters in Hsinchu Science Park semiconductor fabs where cleanroom uptime requirements compress response windows for equipment failures.
- Energy Management:Continuous commissioning, consumption analytics, and conservation implementation plans verified under Bureau of Energy mandates. Taichung precision machinery plants are expanding these contracts fastest as electricity rate pressures mount from Taipower adjustments.
- Soft Services:Cleaning, waste management, and workplace support functions with minimal specialized certification requirements.
- Security Services:Access control, surveillance, and personnel screening operations subject to facility-specific security protocols.
- Consulting Services:Advisory functions spanning green building certification preparation and energy audit documentation.
Leading the category by volume: Hard Services. Growing fastest: Energy Management.
Application Sector:
Cost tier stratification separates premium-certified facilities from standard-compliance buildings, with science park complexes absorbing service premiums that hospitality venues resist.
- Commercial Complexes:Integrated hard and soft service bundles for office towers and mixed-use developments. Xinyi District property managers are unbundling long-term contracts into modular components with discrete performance metrics.
- Government Buildings:Public procurement subject to localized compliance management requirements. AssetPlus Taiwan Limited anchors this segment through specialized regulatory navigation.
- Educational Institutes:Campus-wide maintenance contracts spanning laboratories, dormitories, and administrative facilities.
- Hospitality Venues:Guest experience-focused soft services combined with behind-the-scenes hard service coordination.
- Logistics Centers:Cold chain environmental control and warehouse automation maintenance in Kaohsiung port zone expansion areas.
Commercial Complexes generate the largest contract value. Logistics Centers are climbing the fastest on e-commerce fulfillment buildouts.
Customer Category:
Volume concentration patterns reveal how industrial plants consolidate spending through multi-year managed service agreements while retail chains fragment procurement across regional operators.
- Industrial Plants:Semiconductor fabrication and precision machinery facilities with 24/7 operational continuity requirements. These customers are shifting from single-source to multi-source vendor arrangements, recalibrating procurement strategies across Taiwan's industrial estates.
- Corporate Offices:Workplace experience management and employee amenity services in Taipei central business district towers. Outcome-based contracts are displacing conventional time-and-materials arrangements in this segment.
- Public Sector Entities:Government building portfolios with mandated localization requirements and extended procurement cycles.
- Retail Chains:Standardized service specifications across multiple storefront locations with centralized vendor management.
- Non-Profit Organizations:Cost-constrained facilities prioritizing essential maintenance over premium service tiers.
Industrial Plants command the deepest contract values. Corporate Offices are gaining share fastest on hybrid workplace repositioning.
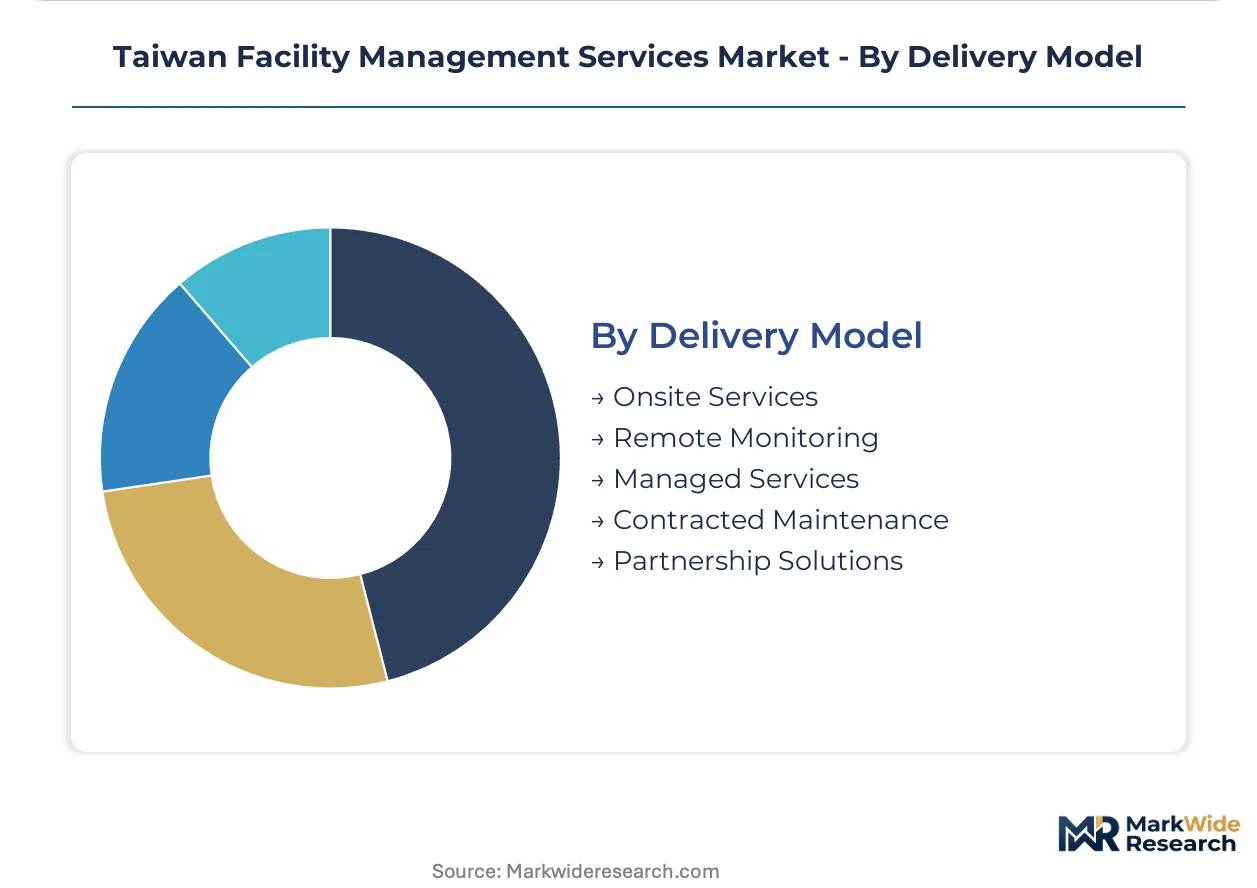
Delivery Model:
Margin structures diverge sharply between asset-heavy onsite deployment and technology-leveraged remote monitoring, with managed services capturing premium pricing through outcome guarantees.
- Managed Services:Outcome-based contracts with guaranteed uptime, energy reduction targets, or compliance maintenance. CBRE Group leverages technology-led asset tracking systems to anchor this model for Taipei commercial complexes.
- Remote Monitoring:IoT sensor networks and predictive analytics platforms enabling condition-based maintenance interventions. Digital twin deployment is restructuring how industrial estates monitor asset health through continuous optimization loops.
- Onsite Services:Dedicated personnel permanently stationed at client facilities with immediate response capability.
- Contracted Maintenance:Scheduled preventive and corrective maintenance performed on defined intervals.
- Partnership Solutions:Collaborative arrangements between international platforms and local specialists for bundled service delivery.
Onsite Services still dominates transaction count. Managed Services shows the steepest expansion trajectory on risk-transfer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's industrial silicon supply chains anchor facility management demand across its science parks and manufacturing corridors. Bureau of Energy mandates and Green Building Label protocols compress vendor qualification timelines while elevating technical service requirements.
Hsinchu Science Park
Semiconductor cleanroom maintenance contracts scale rapidly as fabrication capacity expands. Taiwan's Environmental Protection Administration enforces building energy codes that mandate continuous commissioning protocols. TSMC and UMC facilities drive specialized hard service demand for ISO 14644 compliance verification.
Taichung Precision Machinery Corridor
Automated factory retrofits generate predictive maintenance platform demand for CNC-integrated systems. Bureau of Energy compliance mandates accelerate energy management system adoption among designated large energy users. Foxconn and Giant Manufacturing facilities concentrate contract value for mechanical and electrical specialists.
Kaohsiung Port Logistics Zone
Cold chain warehouse expansion opens specialized refrigeration and environmental control service contracts. Occupational Safety and Health Administration standards govern industrial safety protocols across logistics estates. Yang Ming Marine Transport and Evergreen Marine facilities anchor demand for integrated hard and soft service bundles.
Taipei Central Business District
Commercial complex managers unbundle long-term contracts into modular components with discrete performance metrics. Green Building Label requirements drive technology-led asset tracking system procurement. Xinyi District towers and Nangang Software Park facilities represent premium-tier service demand concentration.
Tainan Science Park
Biotechnology and optoelectronics manufacturing clusters expand outsourced maintenance under net-zero pathway compliance. Taiwan's Ministry of Economic Affairs enforces energy management system mandates for designated energy users. Southern Taiwan Science Park Administration facilities drive localized vendor development.
Taiwan Facility Management Services Market Competitive Landscape
Global majors compete with regional champions across technology integration and compliance specialization. The vendor base organizes into three tiers: integrated international platforms, localized regulatory specialists, and domain-specific technical contractors. Two strategic archetypes dominate: technology-led asset trackers and compliance-focused local navigators. Competitive moves center on strategic partnerships for bundled delivery and portfolio diversification into energy management outcomes.
Among integrated international platforms, CBRE Group and ISS A/S exemplify the technology-led archetype, occupying positions that emphasize outcome-based contracts and multi-service bundling. AssetPlus Taiwan Limited represents the localized compliance specialist tier, anchoring government and public sector portfolios through regulatory navigation capabilities. Jones Lang LaSalle IP, Inc sits within the premium commercial segment, reflecting the shift toward modular procurement with discrete performance metrics across Taipei's central business district towers.
| Leading Market Players |
|---|
| CBRE Group |
| Diversey Holdings Ltd |
| Jones Lang LaSalle IP, Inc |
| ISS A/S |
| Rentokil Initial Plc |
| Cushman & Wakefield Inc |
| AssetPlus Taiwan Limited |
| ABV Integrated Facility Services |
| G4S Limited |
| Others |
Pricing and Supply Chain Analysis
Semiconductor fabrication facilities in Hsinchu Science Park anchor contract value concentration, compressing vendor margins through multi-source procurement mandates while elevating premiums for ISO 41001-certified service bundles. Pricing power fragments across service tiers as science park administrators unbundle integrated contracts into discrete mechanical, energy, and workplace modules.
Pricing Analysis
Warranty and continuous commissioning bundling separates premium facility management contracts from transactional maintenance arrangements in Taiwan's industrial estates. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 41001 certification status and cleanroom uptime guarantee stringency. Price differentiation hinges on Bureau of Energy compliance verification and response window compression for semiconductor fab failures. Pricing pressure stems from skilled technician scarcity in Taichung and Kaohsiung, forcing wage pass-throughs that squeeze mid-tier vendor margins. Corporate offices in Taipei Xinyi District exhibit lowest price sensitivity on outcome-based managed services, while logistics operators in Kaohsiung prioritize cost minimization over performance guarantees.
Supply Chain Analysis
Dual-sourcing requirements for building automation systems and IoT sensors mandate Japanese and German supplier qualification alongside Taiwanese distribution partners. Equipment import dependency concentrates supply chain risk in Yokogawa, Siemens, and Schneider Electric channels, with currency exposure amplifying cost volatility. Raw material and component procurement draws from precision HVAC units, cleanroom filtration media, and predictive analytics software licensing. Single-source vulnerability persists for specialized cleanroom certification equipment where ISO 14644 compliance verification tools face limited qualified vendors. Distribution runs through science park procurement consortia and government tender platforms, with channel control consolidating around integrated international platforms possessing localized regulatory navigation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled technician scarcity across Taiwan's central and southern industrial corridors props pricing for certified hard service vendors, creating supply-constrained conditions that favor incumbents with established training pipelines. Capacity bottlenecks in HVAC and electrical specialist certification compress competitive entry timelines.
For Market Incumbents: Deploy predictive maintenance platform integration to defend contract renewals against modular unbundling pressures from science park procurement officers. Anchor multi-year agreements through embedded continuous commissioning protocols that align with Bureau of Energy tightening enforcement. Deepen backward integration into technician training partnerships with Taichung and Kaohsiung vocational institutes to mitigate wage inflation exposure. Threat substitution from remote monitoring platforms demands counter-investment in digital twin deployment capabilities. For New Entrants and Emerging Players: Regional logistics operators in Kaohsiung port zone expansion areas represent the most penetrable white-space target, with cold chain environmental control contracts showing limited incumbent saturation. Specialized refrigeration expertise gaps in Yang Ming and Evergreen Marine facilities create entry pathways for technical contractors possessing port security clearance. Target carbon accounting convergence services bundling ISO 50001 with Taiwan's forthcoming footprint disclosure rules as the primary go-to-market angle. Partnership with local compliance specialists accelerates regulatory navigation speed to market. For Investors and Strategic Acquirers: The window for entry favors technology-led asset tracking platforms with proven science park deployment records and modular contract unbundling capabilities. Long-term viability centers on vendors capturing energy management outcome premiums as electricity rate pressures intensify across designated large energy users. Acquisition target archetype: mid-scale predictive maintenance specialists with CNC-integrated platform deployments in Taichung precision machinery corridor. Watch Bureau of Energy amendment announcements as the signal indicating acceleration or deceleration in compliance-driven procurement restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Pipeline Investment | Addresses skilled HVAC and electrical specialist scarcity compressing vendor margins in Taichung. |
| Predictive Maintenance Platform Deployment | Enables CNC-integrated continuous optimization loops for precision machinery corridor factories. |
| Carbon Accounting Service Bundling | Captures ISO 50001 and Taiwan footprint disclosure convergence demand from designated energy users. |
| Multi-Source Vendor Qualification | Aligns procurement positioning with Hsinchu Science Park administrator unbundling preferences. |
| Digital Twin Asset Tracking Integration | Supports real-time energy dashboard deployment for Xinyi District commercial complex contracts. |
Research Methodology
Regulatory filings from Taiwan's Bureau of Energy, Environmental Protection Administration enforcement records, and science park procurement databases formed the secondary backbone for demand quantification. Primary interviews with facility management directors at semiconductor fabs, commercial complex property managers in Taipei, and procurement officers at precision machinery plants triangulated against secondary validation. Bottom-up contract value aggregation and top-down sectoral spending estimates reconciled through cross-reference with Occupational Safety and Health Administration compliance cost disclosures.
Bottom-up modeling segmented the market across service type, application sector, customer category, and delivery model dimensions throughout the forecast period. CAGRs derived from regression analysis of historical contract value trajectories adjusted for electricity rate escalation and green building certification expansion schedules. Forecast inputs incorporated Bureau of Energy designation thresholds for large energy users and ISO 41001 adoption curves across government building portfolios.
Caveats apply where Bureau of Energy mandate amendments or Green Building Label protocol revisions could materially shift the outlook for compliance-driven procurement. Deviation in skilled technician training pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Indonesia Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Panama Facility Management Market