
 Germany Insulin Infusion Pump Market | 2026-2036
Germany Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Insulin Infusion Pump Market Insights
Hospital procurement for insulin infusion pumps is consolidating around larger integrated care networks and university medical centers across Germany. Medtronic leverages its long-standing installed base in academic hospitals to sustain service contracts and training dependencies. Ypsomed anchors its position through Swiss-German manufacturing proximity and specialized pen-pump hybrid systems. Insulet Corporation competes via its tubeless patch platform, appealing to home care settings and younger patient demographics seeking discretion.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous cannula at calibrated basal rates and bolus doses, typically maintaining glycemic control within 70-180 mg/dL target ranges for Type 1 and advanced Type 2 diabetes patients. The device combines a reservoir, pumping mechanism, infusion set, and electronic controller with alarm functions for occlusion, low battery, and empty reservoir conditions. Smart pump technology leads segment value due to integrated continuous glucose monitoring interoperability and automated insulin adjustment algorithms, while patch pumps represent the fastest-growing product type as patient preference shifts toward wearable, tubeless form factors. Subcutaneous delivery mode dominates volume given its established safety profile, though intra-abdominal applications attract specialized pediatric and gastroparesis cases where conventional absorption fails.
BfArM oversees medical device registration and post-market surveillance under Germany's implementation of the EU Medical Devices Regulation, while CE marking remains mandatory for market access and reimbursement eligibility through statutory health insurers. The German Diabetes Association publishes care standards that influence pump prescription thresholds and technology upgrade cycles. Stakeholders must monitor how DiGA (digital health applications) fast-track approvals reshape software-integrated pump reimbursement and whether BfArM strengthens cybersecurity requirements for wireless-enabled devices.
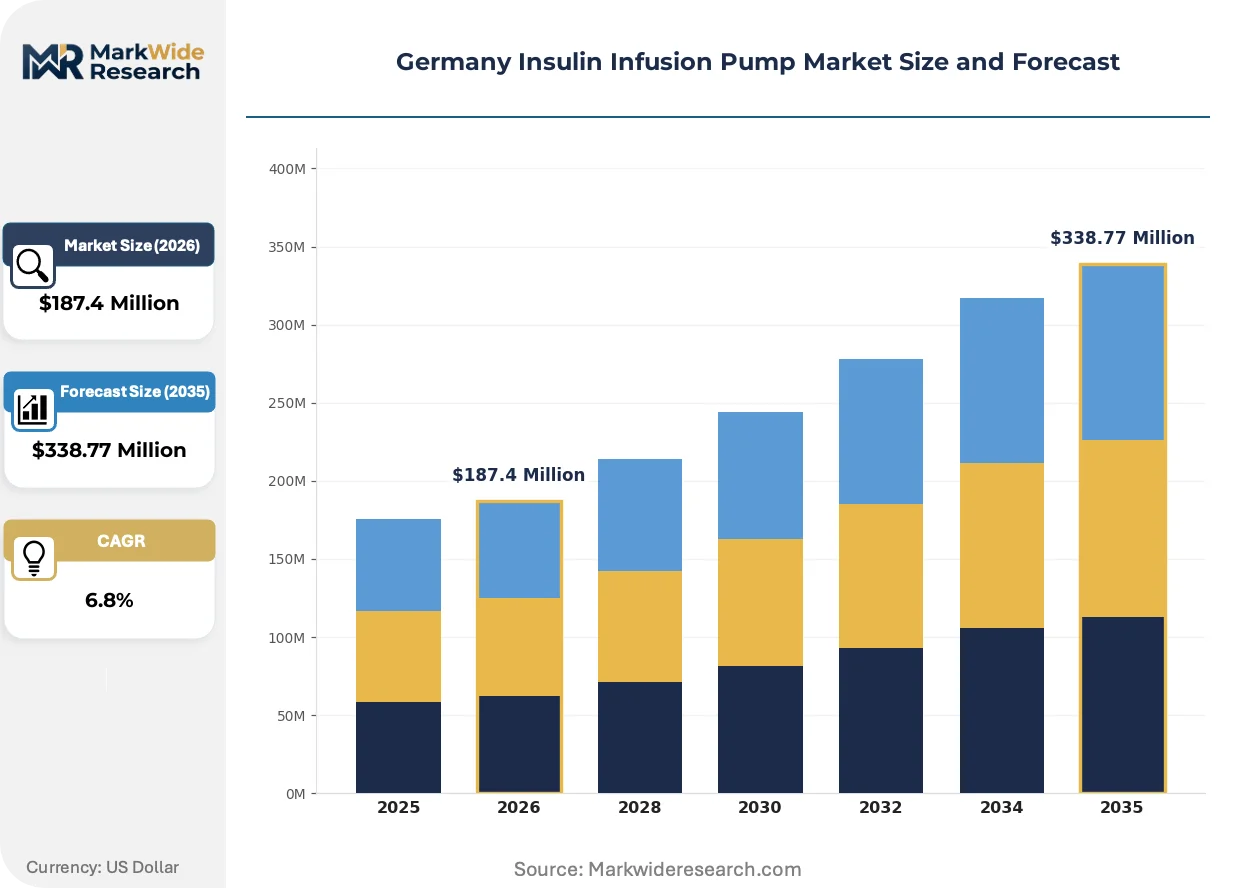
Market Dynamics
Hospital procurement consolidation under integrated care networks is compressing vendor margins while accelerating standardization of smart pump platforms across Germany's university medical centers.
Growth Catalysts
- EU Medical Devices Regulation (MDR):BfArM's tightened post-market surveillance mandates accelerate replacement cycles for legacy pump systems in academic hospitals.
- Bavaria's diabetes center density:Concentrated specialized care infrastructure in Munich and Erlangen generates concentrated demand for advanced hybrid closed-loop systems.
- Tubeless patch pump technology:Miniaturized wearable form factors attract younger Type 1 diabetes patients seeking discretion in daily insulin management.
Market Restraints
- Reimbursement compression:Statutory health insurers impose strict prescription thresholds that limit pump access to advanced Type 2 cases with documented hypoglycemia history.
- Swiss-German supply concentration:Manufacturing proximity advantages for Ypsomed create asymmetric dependency risks for German distributors seeking alternative sourcing.
- CGM interoperability fragmentation:Proprietary data protocols between pump and continuous glucose monitoring systems force costly dual-vendor lock-in for integrated care networks.
Strategic Opportunities
- North Rhine-Westphalia home care expansion:Aachen and Düsseldorf regional insurers pilot remote monitoring reimbursement codes for patch pump patients.
- DiGA fast-track pathway:BfArM's digital health application approval streamlines software-integrated pump algorithm updates outside hardware replacement cycles.
- Algorithm-integrated dosing:Machine learning-driven bolus prediction converges with existing pump hardware to reduce physician calibration burden.
Industry Challenges
- Cybersecurity certification timelines:BfArM's evolving wireless device security requirements extend type-approval durations for Bluetooth-enabled pumps.
- Pediatric endocrinologist scarcity:Specialized training gaps in Berlin and Hamburg academic centers constrain pump initiation capacity for adolescent patient volumes.
- Legacy EMR integration friction:Proprietary data formats from incumbent pump vendors resist seamless incorporation into hospital-wide electronic medical record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Insulin Infusion Pump Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Patch, Continuous Delivery Mode: Subcutaneous, Intravenous, Intra-abdominal, Others End User: Hospitals, Home Care, Clinics, Ambulatory Care Technology: Smart Pumps, Wireless, Manual, Hybrid |
| Companies Covered | Medtronic, Insulet Corporation, Ypsomed, Ascensia Diabetes Care, Tandem Diabetes Care, F. Hoffmann-La Roche, Abbott Laboratories, DexCom, Medtrum Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Insulin Infusion Pump Market Trends and Innovations
Algorithm-driven insulin delivery is compressing the gap between automated glycemic control and physician-directed care, reshaping how German diabetes centers configure their technology portfolios.
Tubeless patch pump systems are decentralizing insulin delivery from hospital-based initiation toward primary care and home settings. General practitioners in Baden-Württemberg now manage pump starts for stable Type 1 patients previously requiring endocrinology referral. This shift compresses specialist capacity constraints while expanding addressable patient populations beyond academic center catchments.
BfArM's implementation of EU MDR post-market surveillance requirements is forcing systematic clinical follow-up data collection from all active pump patients. Manufacturers must now submit real-world performance evidence annually, raising compliance costs but accelerating defect detection. Smaller vendors lacking dedicated German regulatory affairs teams face disproportionate resource strain relative to established market participants.
Younger patient demographics are demanding smartphone-native pump control interfaces that bypass dedicated handheld controllers. Endocrinology practices in Hamburg report rising appointment requests specifically citing mobile app compatibility as a device selection criterion. This preference shift pressures vendors to accelerate software development cycles and abandon hardware-controller dependencies that previously anchored service revenue models.
Germany Insulin Infusion Pump Market Segmentation
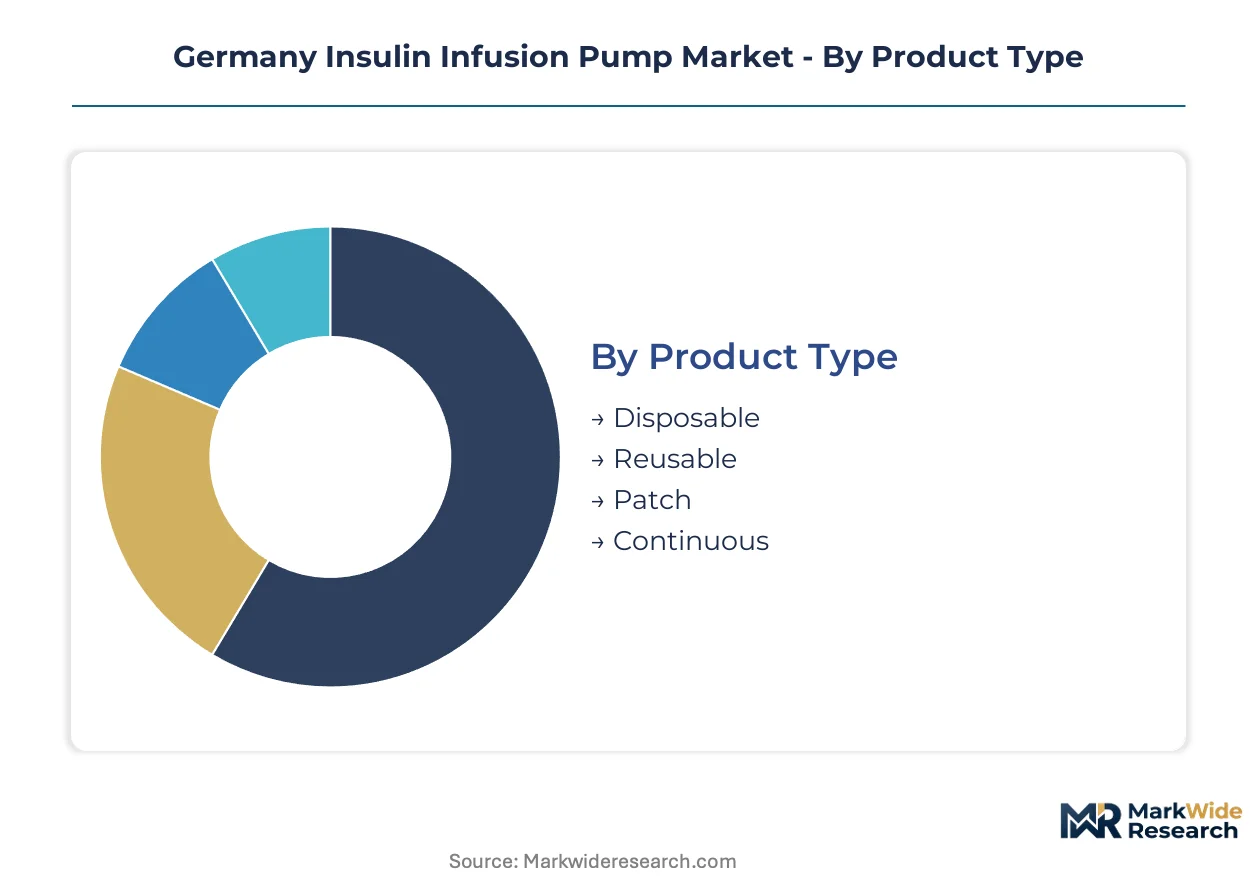
Insulin infusion pump segmentation in Germany reflects divergent clinical workflows across academic hospitals, regional diabetes centers, and expanding home care networks. Technology differentiation and reimbursement eligibility create distinct commercial corridors for vendors targeting specific care settings.
Product Type:
Form factor specifications determine patient adherence profiles and replacement economics across German reimbursement tiers.
- Patch:Tubeless wearable systems attach directly to skin via adhesive, eliminating tubing entanglement risks. Bavarian pediatric centers in Munich report rising demand among adolescent patients prioritizing discretion during school and sports activities.
- Smart Pumps:Closed-loop systems integrate continuous glucose monitoring with algorithmic basal rate adjustment. University hospitals in Erlangen and Heidelberg standardize on these platforms for hybrid closed-loop therapy initiation.
- Disposable:Single-use reservoir and infusion set combinations reduce infection risk for immunocompromised patients. North Rhine-Westphalia home care services favor these for remote patient monitoring pilots.
- Reusable:Durable pump bodies with replaceable reservoirs dominate established Type 1 patient populations. Berlin and Hamburg endocrinology practices maintain large installed bases requiring long-term service contracts.
- Continuous:Extended-wear systems minimize set change frequency for patients with needle anxiety. Baden-Württemberg diabetes centers deploy these for newly diagnosed patients transitioning from multiple daily injections.
Patch pumps lead on scale; smart pumps lead on momentum.
Delivery Mode:
Route of administration selection depends on insulin absorption kinetics and patient-specific physiological barriers.
- Subcutaneous:Abdominal or thigh tissue infusion via Teflon or steel cannula remains the established standard. Over 90% of German pump patients utilize this mode across all care settings.
- Intra-abdominal:Surgical port systems bypass subcutaneous absorption variability in gastroparesis cases. Specialized centers at Charité Berlin manage these complex implantations.
- Intravenous:Hospital-only applications for critical care glycemic management during surgery or DKA episodes. University medical centers maintain limited inventories for ICU protocols.
- Others:Intraperitoneal and intramuscular experimental routes remain confined to clinical trial populations. BfArM oversight restricts commercial availability pending safety documentation.
Subcutaneous delivery anchors volume; intra-abdominal applications command premium reimbursement.
End User:
Care setting economics shape procurement scale and decision-making authority concentration.
- Hospitals:University medical centers and integrated delivery networks negotiate multi-year fleet contracts. Procurement consolidation under larger networks compresses vendor margins while accelerating platform standardization.
- Home Care:Remote monitoring reimbursement pilots in Aachen and Düsseldorf expand patch pump prescribing authority to general practitioners. This decentralization alleviates pediatric endocrinologist capacity constraints.
- Clinics:Specialized diabetes centers in Bavaria concentrate advanced hybrid closed-loop system expertise. These facilities generate concentrated demand for training-intensive technology platforms.
- Ambulatory Care:Outpatient surgical centers manage pump-assisted perioperative glycemic control. Limited penetration reflects reimbursement ambiguity for non-endocrinology settings.
Hospitals dominate procurement value; home care settings are expanding most quickly.
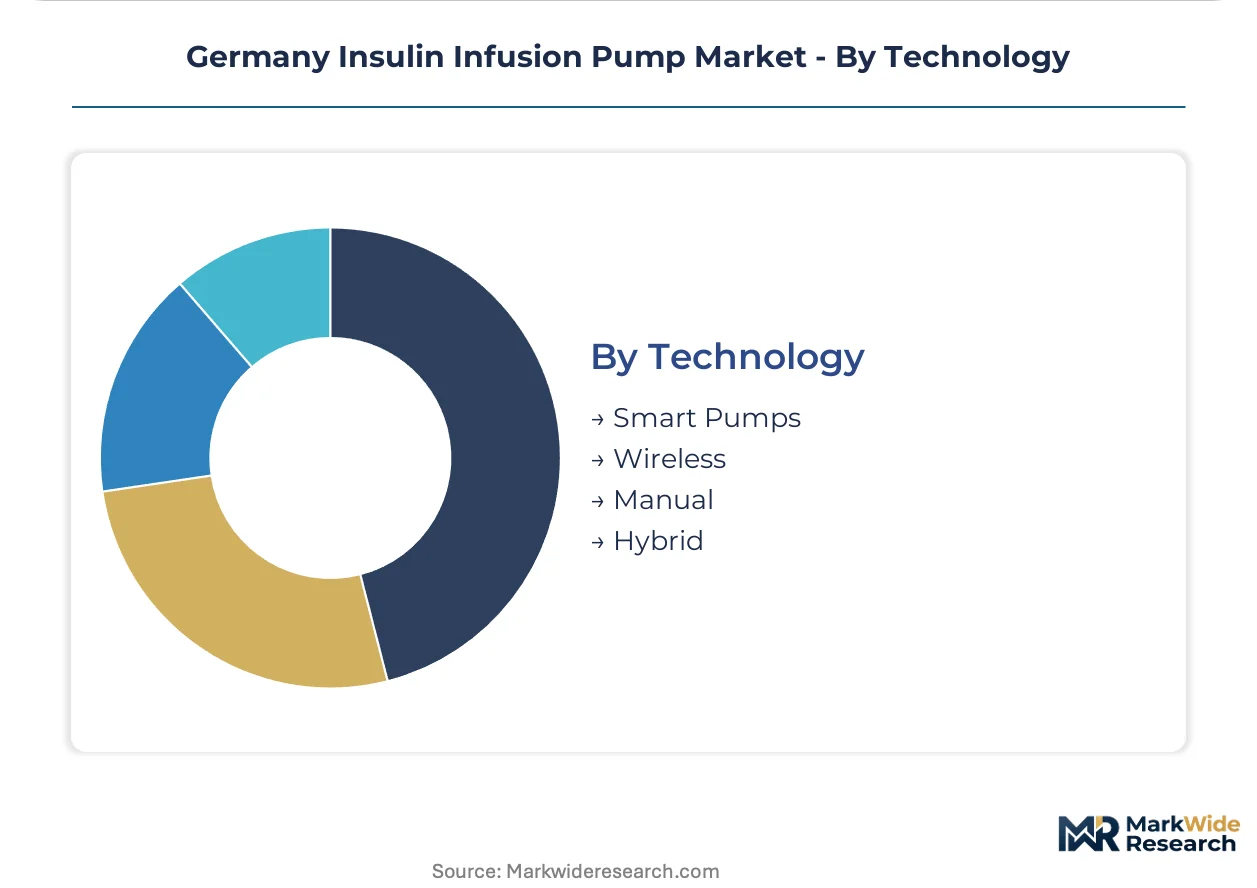
Technology:
Connectivity and automation capabilities differentiate reimbursement tiers and clinical utility profiles.
- Smart Pumps:Integrated CGM interoperability with predictive low glucose suspend algorithms defines the premium segment. BfArM's DiGA fast-track pathway accelerates software update approvals for these systems.
- Wireless:Bluetooth-enabled smartphone control interfaces attract younger demographics in Hamburg and Berlin practices. Cybersecurity certification timelines under evolving BfArM requirements extend type-approval durations.
- Hybrid:Semi-automated systems requiring patient-confirmed bolus inputs balance automation with physician oversight. These platforms dominate transitional care for patients graduating from manual pumps.
- Manual:Basic programmable pumps without CGM integration persist in cost-sensitive segments and legacy installations. Replacement cycles accelerate under EU MDR post-market surveillance mandates.
Smart pumps capture the highest value per unit; wireless connectivity features gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's insulin infusion pump demand outpaces neighboring Switzerland in absolute volume, though Swiss-German manufacturing proximity creates asymmetric supply dependencies for distributors seeking alternative sourcing routes across Central European markets.
Bavaria
Specialized diabetes centers in Munich and Erlangen generate concentrated demand for advanced hybrid closed-loop systems. BfArM's post-market surveillance mandates accelerate replacement cycles for legacy pumps in academic hospitals. The Munich metropolitan cluster anchors Bavaria's pediatric endocrinology capacity, driving tubeless patch pump adoption among adolescent patients prioritizing discretion during school activities.
North Rhine-Westphalia
Regional insurers in Aachen and Düsseldorf pilot remote monitoring reimbursement codes for patch pump patients. The EU Medical Devices Regulation implementation tightens clinical follow-up requirements for all active pump users. Düsseldorf's integrated care networks consolidate procurement under larger delivery systems, compressing vendor margins while standardizing smart pump platforms.
Baden-Württemberg
General practitioners now manage pump starts for stable Type 1 patients previously requiring endocrinology referral. Germany's statutory health insurance framework imposes strict prescription thresholds limiting pump access to advanced Type 2 cases. Stuttgart's medical technology corridor supports decentralized insulin delivery expansion from hospital-based initiation toward primary care settings.
Berlin-Brandenburg
Charité Berlin maintains specialized expertise for complex intra-abdominal surgical port implantations in gastroparesis cases. BfArM's evolving cybersecurity requirements extend type-approval durations for Bluetooth-enabled pumps. The capital region's pediatric endocrinologist scarcity constrains pump initiation capacity for adolescent patient volumes despite rising demand.
Hamburg
Endocrinology practices report rising appointment requests citing smartphone-native pump control compatibility as device selection criteria. The DiGA fast-track pathway streamlines software-integrated pump algorithm updates outside hardware replacement cycles. Hamburg's younger patient demographics pressure vendors to abandon hardware-controller dependencies that previously anchored service revenue models.
Germany Insulin Infusion Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's insulin infusion pump procurement tiers. The vendor base clusters around three strategic archetypes: established medical technology conglomerates with long-standing installed bases, Swiss-German manufacturing specialists leveraging geographic proximity advantages, and tubeless wearable innovators targeting home care decentralization. Competitive positioning hinges on CGM interoperability certification and BfArM regulatory compliance velocity rather than hardware differentiation alone. M&A activity concentrates on algorithm-integrated dosing capabilities, while strategic partnerships address EMR integration friction in university medical center workflows.
Among the named participants, Medtronic anchors the established conglomerate tier through academic hospital service contracts, while Ypsomed exemplifies Swiss-German manufacturing proximity advantages. Insulet Corporation occupies a position within the tubeless wearable specialist archetype, appealing to home care settings and younger demographics seeking discretion. These three entities represent distinct competitive vectors: installed base dependency, supply chain geography, and form factor innovation.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Ypsomed |
| Ascensia Diabetes Care |
| Tandem Diabetes Care |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| DexCom |
| Medtrum Technologies |
| Others |
Pricing and Supply Chain Analysis
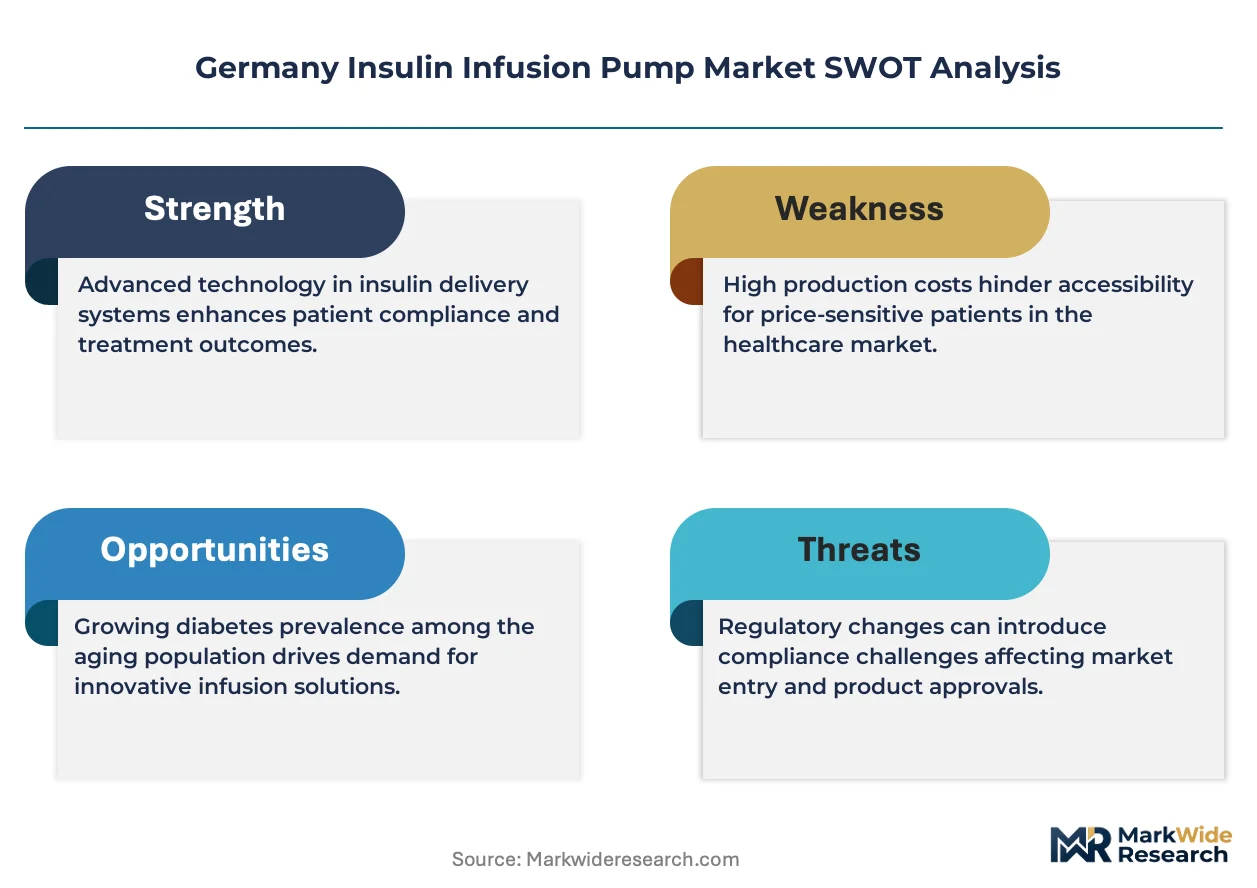
Specialized biomedical engineering talent concentration in Baden-Württemberg and Bavaria feeds labor-cost differentials that widen pricing-tier spreads between premium smart pump systems and economy manual alternatives. BfArM compliance overhead concentrates among established vendors, compressing mid-tier pricing flexibility while elevating entry thresholds for new participants.
Pricing Analysis
Capacity additions in Swiss manufacturing corridors are reshaping price floors for German distributors seeking alternative sourcing beyond Ypsomed's established supply position. Three-tier pricing structure across premium, standard, and economy levels reflects BfArM certification grade and CGM interoperability depth. Pricing pressure stems from statutory health insurer reimbursement compression limiting pump access to documented hypoglycemia cases. Home care settings exhibit highest price sensitivity; university medical centers prioritize interoperability over unit cost.
Supply Chain Analysis
CE marking and BfArM quality system certification gating restricts component sourcing to audited suppliers in Switzerland, Germany, and Ireland. Precision micro-pump mechanisms draw from Swiss micromachining specialists; electronic controllers source from German automotive-tier suppliers. Single-source vulnerability concentrates in adhesive patch materials for tubeless systems. Distribution runs through specialized diabetes care distributors with BfArM logistics licensing rather than general medical device wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's insulin infusion pump market functions as a stable compounder anchored by irreversible Type 1 diabetes prevalence and technology upgrade cycles mandated under EU MDR post-market surveillance.
For Market Incumbents: Acquire algorithm-integrated dosing capabilities to defend against software-native entrants exploiting DiGA fast-track pathways. Backward integration into CGM sensor manufacturing reduces dual-vendor lock-in costs for integrated care networks. Prioritize BfArM cybersecurity certification velocity to compress type-approval timelines for Bluetooth-enabled platforms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pediatric patch pumps opens white-space targeting in Bavarian and North Rhine-Westphalia home care networks. General practitioner-managed pump starts in Baden-Württemberg represent the most penetrable care setting. Partner with regional insurers piloting remote monitoring reimbursement codes to establish prescriber relationships before specialist channel expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap pump vendors lacking dedicated German regulatory affairs infrastructure. Long-term viability over the next decade hinges on software-integrated platform economics displacing hardware-replacement revenue models. Watch BfArM's evolving wireless device security requirements as the inflection signal for compliance-cost divergence between established and emerging players.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | BfArM oversight under EU MDR mandates systematic clinical follow-up data submission annually. |
| Hospital System Partnership | Integrated delivery network consolidation in Düsseldorf compresses vendor margins while accelerating platform standardization. |
| Software Companion Development | Smartphone-native control interfaces attract Hamburg's younger demographics seeking discretion. |
| Reimbursement Strategy | DiGA fast-track approvals reshape software-integrated pump algorithm update economics outside hardware cycles. |
| Backward Integration | In-house CGM sensor production reduces proprietary protocol lock-in costs for university medical centers. |
Research Methodology
Multiple input streams — hospital procurement databases, GPO contracts, and BfArM registration filings — were reconciled against primary interviews with diabetes center clinicians, biomedical engineers, and statutory health insurer formulary directors. Secondary validation drew from EU MDR implementation guidance, German Diabetes Association care standards, and medical device trade flow records. Bottom-up patient population estimates and top-down reimbursement expenditure analysis were triangulated to constrain forecast variance.
Historical shipment patterns were cross-referenced against panel input from pump manufacturers and distribution channel partners. Segmentation dimensions modeled include product form factor, delivery mode, end-user care setting, and technology connectivity tier. CAGRs were derived from replacement cycle analysis under EU MDR mandates and algorithm adoption diffusion curves. Forecast inputs incorporated BfArM compliance cost trajectories and regional insurer pilot program expansion rates.
The model assumes a particular technology adoption path; alternative pathways for fully automated closed-loop systems would alter the outlook. Forecasts reflect assumptions regarding BfArM regulatory velocity and statutory health insurance reimbursement stability. A model refresh is warranted upon material change in cybersecurity certification timelines or DiGA pathway eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Mexico Diabetes Medication Market