
 Denmark Data Center Construction Market | 2026-2036
Denmark Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Construction Market Insights
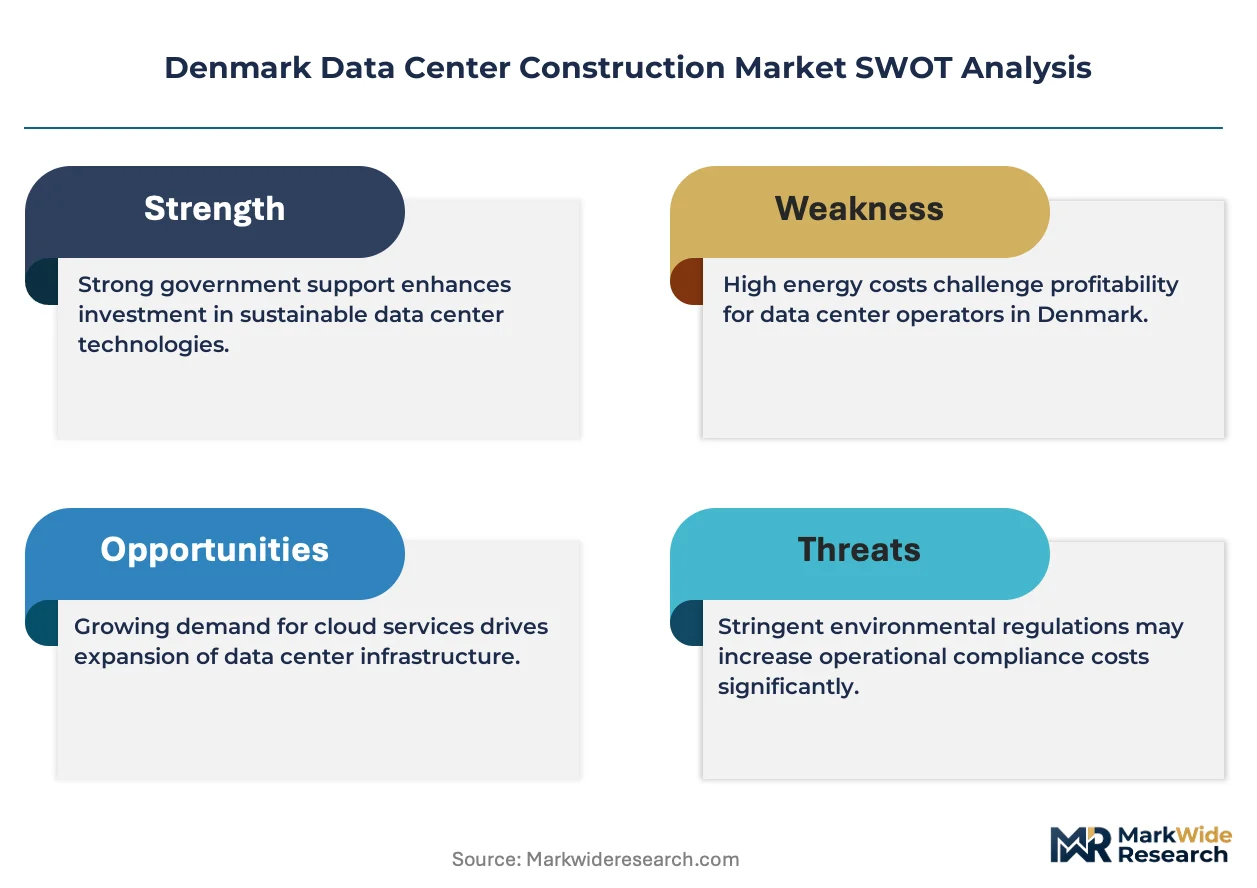
The EU Energy Efficiency Directive is recalibrating the cost-of-entry calculus for new data center projects across Denmark. Bulk Infrastructure leverages its vertically integrated fiber and power infrastructure to secure large-scale sites near renewable energy sources. MT Hojgaard Holding anchors its position through heavy civil capabilities that reduce subcontractor dependency on concrete and steel packages. Ramboll differentiates via engineering consultancy strength in low-carbon cooling design.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing servers, storage, and networking equipment, typically requiring power densities of 5-30 kW per rack and precision cooling within ±1°C tolerance. The primary purpose is to create controlled environments that ensure continuous IT operations with 99.999% uptime reliability. Hyperscale data centers dominate capital deployment due to single-project values exceeding $500 million, while edge data centers represent the fastest-growing installation category as latency-sensitive applications proliferate. Cooling systems command disproportionate engineering attention because Denmark's temperate climate enables free-air cooling for substantial annual hours, shifting margin pools toward advanced heat-reuse integrations.
The Danish Energy Agency enforces efficiency benchmarks that shape facility design standards, while municipal planning authorities under the Danish Building Act control zoning timelines that directly affect project economics. BREEAM certification requirements from the Building Research Establishment increasingly filter procurement eligibility for hyperscale tenants. Stakeholders must monitor how forthcoming EU sustainability disclosure rules will alter tenant due-diligence criteria and capital access conditions.
Market Dynamics
Hyperscale cloud providers are compressing project timelines through pre-certified modular designs, while Denmark's streamlined permitting under the Danish Building Act accelerates site activation. This dual velocity is restructuring contractor selection criteria toward firms with integrated engineering-fabrication capabilities.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for heat reuse and PUE thresholds below 1.3 are driving investment in advanced cooling infrastructure across Danish facilities.
- Free-air cooling:Denmark's temperate maritime climate enables economizer operation for over 4,000 annual hours, slashing mechanical cooling energy consumption.
- Odense cluster:Concentrated submarine cable landings and excess renewable generation capacity are attracting contiguous hyperscale campus developments.
Market Restraints
- Steel and copper volatility:Prefabricated data hall modules depend on imported structural steel and busbar copper, exposing project budgets to commodity price swings.
- Specialized contractor scarcity:Denmark's limited pool of certified mission-critical electrical contractors creates bottleneck risk for concurrent multi-site deployments.
- Grid interconnection queues:Energinet's connection approval timelines for 100MW+ loads extend 18-24 months, constraining rapid capacity scaling.
Strategic Opportunities
- Zealand secondary markets:Ringsted and Køge offer lower land costs with Copenhagen fiber latency, enabling edge and regional cloud nodes.
- Liquid cooling retrofit:Existing air-cooled facilities face stranded asset risk, creating upgrade demand for direct-to-chip and immersion systems.
- CSRD alignment services:Upcoming EU sustainability disclosure rules position engineering consultancies to monetize carbon accounting and ESG documentation.
Industry Challenges
- Mission-critical MEP talent:Denmark produces fewer than 50 specialized data center mechanical and electrical engineers annually, forcing reliance on imported expertise.
- BREEAM-DK certification timelines:The Building Research Establishment's local adaptation requires 8-12 months for full assessment, compressing design-to-groundbreaking schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Construction Market |
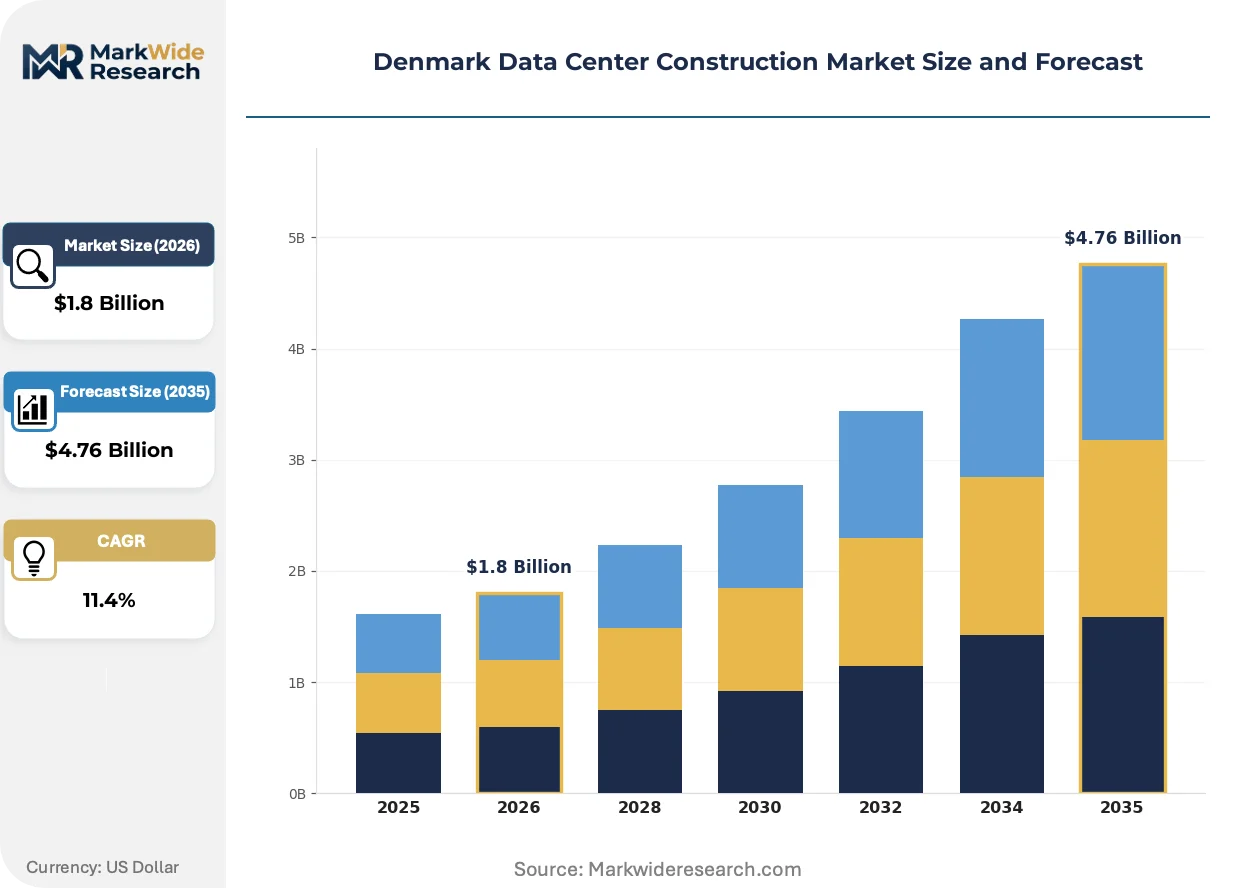
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Facilities, Hyperscale Data Centers, Edge Data Centers, Colocation Centers Technology: Cooling Systems, Power Supply Units, Racks, Security Solutions End User: IT Service Providers, Cloud Service Providers, Telecommunications Companies, Enterprises Installation: Onshore, Offshore, Urban, Suburban |
| Companies Covered | Bulk Infrastructure, Mercury Engineering, MT Hojgaard Holding, COWI A/S, GlobalConnect, Ramboll, Coromatic Group AB, Per Aarsleff A/S, NS Nordic AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Construction Market Trends and Innovations
Denmark's data center construction sector is pivoting toward thermal integration with district heating networks and prefabrication methodologies that compress on-site labor requirements. These shifts are redefining contractor capabilities and project economics.
Direct liquid cooling is converging with heat pump systems to capture server waste heat at 60-80°C for municipal district heating injection. Copenhagen Utility and Aarhus-based heating cooperatives are piloting these integrations at operational facilities. This thermal capture is enabling operators to monetize waste streams while satisfying EU Energy Efficiency Directive reuse mandates.
The Danish Building Act's 2023 amendments introduced fast-track zoning for renewable-coupled industrial facilities. Municipal planning authorities in Fredericia and Esbjerg have adopted standardized environmental impact templates, cutting approval cycles from 14 months to 7 months for qualifying projects. Hyperscale tenants are now prioritizing these pre-approved zones in site selection algorithms.
Build-operate-transfer contracting is displacing traditional design-bid-build arrangements for campus-scale developments. Danish pension funds and infrastructure investors are deploying capital through 15-20 year leaseback structures, transferring construction risk to specialized operators. This capital structure is most visible in Odense, where institutional ownership now underpins three of four active hyperscale projects.
Denmark Data Center Construction Market Segmentation
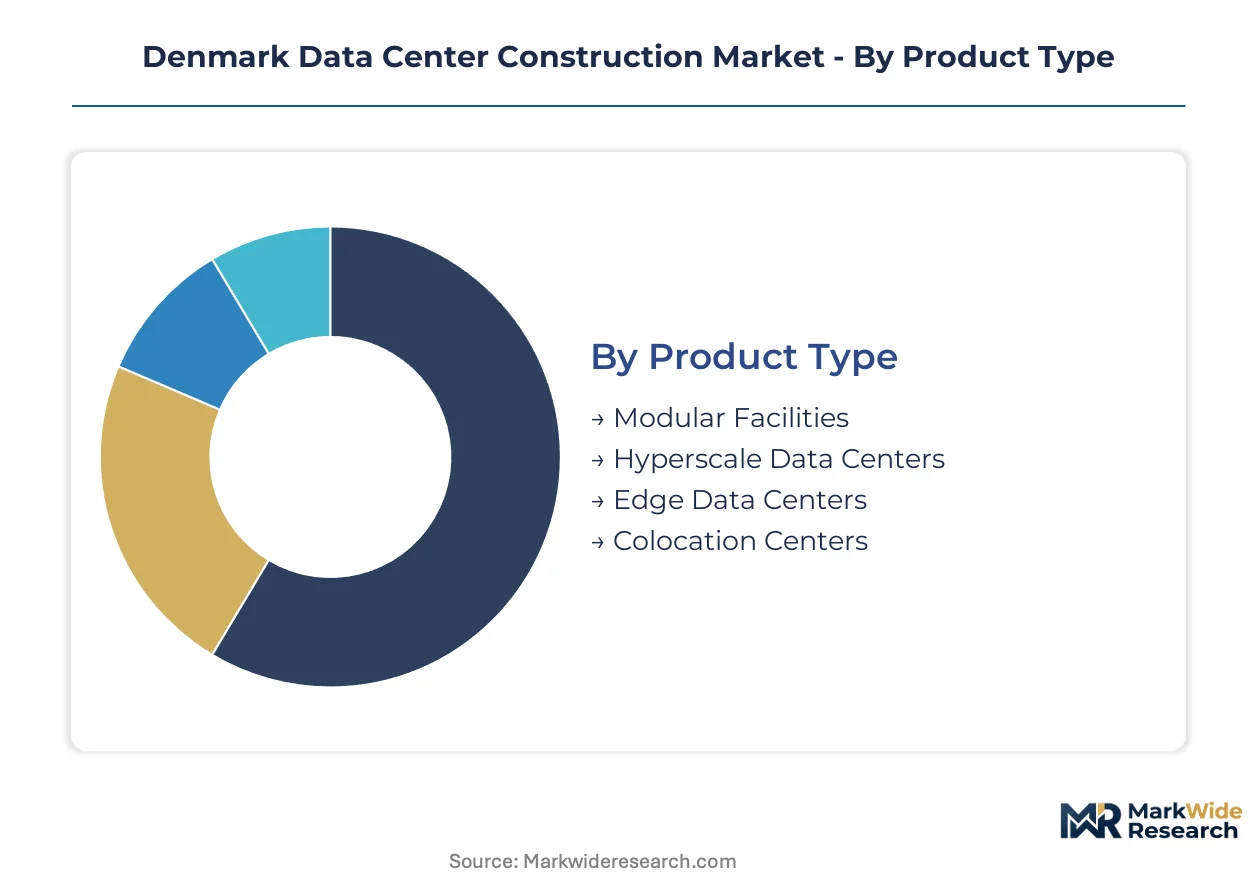
Segmentation in Denmark's data center construction market reveals how facility scale, cooling technology, and end-user requirements reshape procurement patterns. Understanding these divides exposes where capital concentrates and where specialized engineering capabilities command premium pricing.
Product Type:
Facility architecture determines power density specifications, construction timelines, and the balance between prefabrication and on-site assembly.
- Hyperscale Data Centers:Single-campus developments exceed 50MW of IT load with standardized designs that compress construction schedules to 18-24 months. Copenhagen and Odense attract these deployments due to submarine cable proximity and Energinet grid capacity.
- Modular Facilities:Factory-integrated power and cooling modules reduce on-site labor by 40% versus stick-built alternatives. Danish contractors with in-house fabrication capabilities capture margin that would otherwise flow to German or Dutch suppliers.
- Edge Data Centers:Sub-10MW facilities positioned within 20ms latency of population centers. Ringsted and Køge on Zealand island emerge as secondary markets with lower land costs than Copenhagen.
- Colocation Centers:Multi-tenant shell-and-core construction with flexible white space partitioning. BREEAM-DK certification requirements filter tenant eligibility and extend design phases.
Hyperscale data centers lead on scale; edge data centers lead on momentum.
Technology:
Engineering intensity and capital allocation vary sharply across mechanical, electrical, and security subsystems.
- Cooling Systems:Free-air economizers and liquid cooling loops dominate Danish specifications due to 4,000+ annual hours of ambient cooling availability. Direct-to-chip systems capture waste heat at 60-80°C for district heating injection.
- Power Supply Units:Uninterruptible power supply and switchgear configurations must achieve 99.999% uptime reliability. Copper busbar pricing volatility exposes project budgets to commodity market swings.
- Racks:Structural containment systems with integrated cable management and airflow baffles. Higher power densities above 30kW per rack drive demand for liquid-cooled rack architectures.
- Security Solutions:Physical access control, perimeter detection, and biometric authentication systems. Financial services tenants impose the most stringent multi-layer security specifications.
Cooling systems absorb the largest engineering focus; power supply units carry the greatest commodity risk.
End User:
Tenant type dictates redundancy tiers, sustainability commitments, and lease structure preferences that cascade into construction specifications.
- Cloud Service Providers:Hyperscale operators demand rapid deployment with pre-certified designs and long-term leaseback arrangements. These tenants drive build-operate-transfer contracting models across Odense developments.
- IT Service Providers:Regional and managed service operators seeking 2-5MW incremental capacity with shorter contract terms. Price sensitivity pushes these users toward colocation rather than dedicated facilities.
- Telecommunications Companies:Edge positioning for 5G core and content delivery networks with strict latency requirements. Submarine cable landing proximity in Esbjerg and Blåvand shapes site selection.
- Enterprises:Financial services and pharmaceutical firms with compliance-driven security and resilience specifications. EU sustainability disclosure rules elevate due-diligence intensity for these tenants.
Cloud service providers anchor capital deployment; enterprises impose the most complex certification requirements.
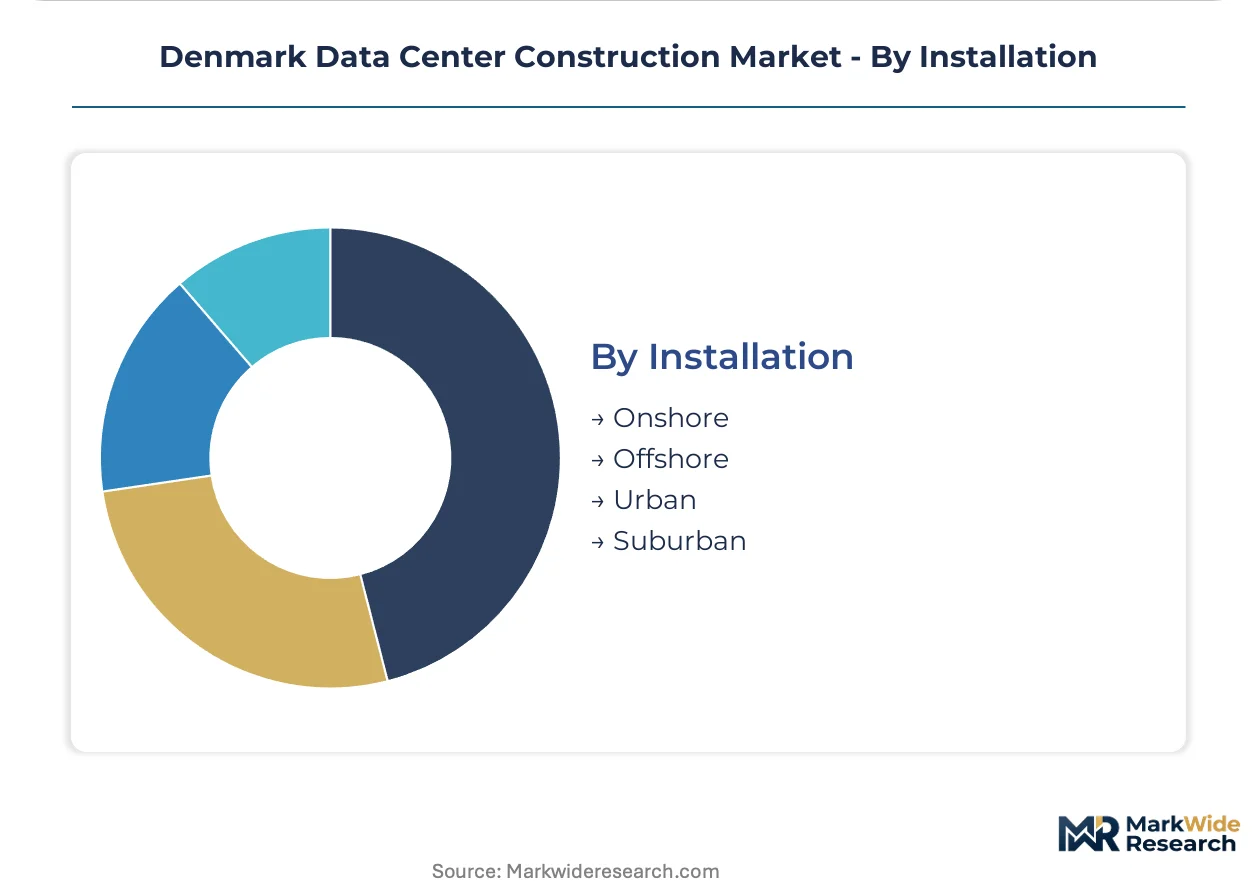
Installation:
Geographic positioning determines grid access, fiber latency, permitting velocity, and land cost structures.
- Urban:Copenhagen and Aarhus locations with existing fiber density and district heating integration potential. Land scarcity and municipal zoning constraints limit greenfield expansion.
- Suburban:Ringsted, Køge, and Fredericia benefit from fast-track permitting under Danish Building Act amendments while maintaining sub-10ms latency to Copenhagen. These zones attract regional cloud and edge deployments.
- Onshore:Continental Denmark deployments with standard grid interconnection procedures. Energinet queue timelines of 18-24 months for 100MW+ loads constrain rapid scaling.
- Offshore:Near-shore artificial island or platform concepts for direct renewable coupling. These remain pre-commercial with significant regulatory and engineering uncertainty.
Suburban installations offer the fastest approval cycles; urban locations command premium pricing for heat-reuse integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's specialized mission-critical MEP talent concentrates in Copenhagen and Odense, where hyperscale demand has outpaced domestic engineering program output and forced reliance on imported expertise.
Capital Region
Copenhagen anchors the largest data center construction cluster with submarine cable landings and district heating integration potential. The Danish Building Act's fast-track zoning applies to renewable-coupled industrial facilities in this zone. Frederiksberg and Høje-Taastrup municipalities host active hyperscale campus developments leveraging existing fiber density.
Southern Denmark
Odense attracts contiguous hyperscale developments through concentrated submarine cable infrastructure and excess renewable generation capacity. The Danish Energy Agency enforces efficiency benchmarks shaping facility design standards across Funen island. Bulk Infrastructure operates large-scale sites near renewable energy sources in this corridor.
Central Denmark Region
Aarhus-based heating cooperatives pilot thermal capture integrations at operational facilities, capturing server waste heat for municipal district heating injection. BREEAM-DK certification requirements from the Building Research Establishment filter procurement eligibility. Randers and Silkeborg offer secondary positioning with lower land costs than eastern clusters.
Region Zealand
Ringsted and Køge emerge as secondary markets with Copenhagen fiber latency and lower land acquisition costs. The Danish Building Act amendments introduced standardized environmental impact templates cutting approval cycles. These zones attract regional cloud nodes and edge deployments targeting sub-10ms latency requirements.
Denmark Data Center Construction Market Competitive Landscape
The competitive structure tilts toward vertically integrated infrastructure specialists with captive power and fiber assets. Market concentration reflects high capital barriers and specialized MEP capability requirements. Two archetypes dominate: engineering consultancies with low-carbon cooling design strength, and heavy civil contractors with in-house concrete and steel fabrication. Competitive moves center on build-operate-transfer leaseback structures and pre-certified modular design partnerships.
Among Denmark-based contractors, MT Hojgaard Holding anchors the heavy civil segment through reduced subcontractor dependency on structural packages. Bulk Infrastructure exemplifies the vertically integrated archetype with control over fiber and power infrastructure near renewable sources. Ramboll occupies a position within the engineering consultancy tier, differentiating through low-carbon cooling design capabilities.
| Leading Market Players |
|---|
| Bulk Infrastructure |
| Mercury Engineering |
| MT Hojgaard Holding |
| COWI A/S |
| GlobalConnect |
| Ramboll |
| Coromatic Group AB |
| Per Aarsleff A/S |
| NS Nordic AS |
| Others |
Pricing and Supply Chain Analysis
Prefabricated modular construction is compressing project delivery timelines while simultaneously concentrating procurement power among contractors with captive fabrication capabilities. This production-method transition rewards Danish firms with in-house steel and concrete packages, reshaping margin distribution across the value chain.
Pricing Analysis
Design-build contracting bundles engineering, procurement, and construction into single-source arrangements that dominate hyperscale campus developments. Price differentiation rests on BREEAM-DK certification tier and heat-reuse integration depth, with district heating-connected facilities commanding substantial premiums. Cost compression in standard air-cooled specifications is intensifying because German and Dutch module suppliers compete aggressively for Danish volume. Regional cloud operators exhibit highest price sensitivity, while hyperscale cloud providers prioritize speed-to-market over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for prefabricated power modules, bypassing traditional distribution layers. Manufacturing concentrates in Germany, the Netherlands, and Denmark itself for structural steel and electrical switchgear. Copper busbar and specialized cooling fluids draw from concentrated European smelter and chemical production networks. Single-source vulnerability in certified mission-critical electrical contractors creates bottleneck exposure for concurrent multi-site deployments. Distribution runs through vertically integrated infrastructure specialists with captive fiber and grid interconnection assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's data center construction market functions as a geographic-arbitrage play, capturing surplus renewable capacity and streamlined permitting velocity unavailable in Germany or the Netherlands. The Danish Building Act's fast-track zoning delivers 7-month approval cycles versus 18-24 month queues common across continental Europe.
For Market Incumbents: Lock in long-term leaseback arrangements with institutional capital providers before pension fund allocation saturates Odense and Copenhagen corridors. Secure captive production capacity for prefabricated electrical modules to defend against German supplier price aggression. Deepen backward integration into concrete and steel fabrication to reduce exposure to commodity volatility.
For New Entrants and Emerging Players: Edge computing deployments for 5G core networks represent the most penetrable buyer archetype, with Ringsted and Køge offering lower land costs than saturated primary markets. Target regional cloud operators seeking sub-10MW incremental capacity with build-to-suit contracting. Differentiate through CSRD-aligned carbon accounting services that hyperscale tenants increasingly mandate.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale engineering consultancies with liquid cooling design capabilities and district heating integration expertise. The 5-10 year viability window favors acquisition of firms with pre-certified modular design partnerships and Energinet grid allocation commitments. Monitor Energinet interconnection queue progression as the critical inflection signal for capacity scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Reuse Integration | Direct liquid cooling coupled with district heating injection satisfies EU Energy Efficiency Directive mandates while generating incremental revenue streams. |
| Prefabricated Module Fabrication | In-house production of power and cooling modules captures 40% labor cost reduction versus stick-built alternatives. |
| Build-Operate-Transfer Structuring | 15-20 year leaseback arrangements with Danish pension funds transfer construction risk while securing long-term offtake. |
| Fast-Track Zoning Acquisition | Pre-approved zones under Danish Building Act amendments compress approval cycles from 14 months to 7 months. |
| Mission-Critical MEP Talent Acquisition | Specialized electrical and mechanical engineering capabilities address domestic output of fewer than 50 qualified graduates annually. |
Research Methodology
Bottom-up facility-scale modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with data center developers, mission-critical MEP contractors, municipal planning authorities, and institutional infrastructure investors were validated against secondary sources including Energinet grid interconnection databases, Danish Building Act regulatory filings, BREEAM certification registries, and hyperscaler capital expenditure disclosures. Triangulation across these channels ensures dimensional consistency between projected construction volumes and verified supply-side constraints.
Historical trendline analysis of project completion timelines, permitting velocity, and capital deployment patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include facility scale tier, cooling technology architecture, end-user type, and geographic installation cluster. CAGRs were derived from fitted growth curves applied to verified base-year construction values, incorporating inputs from district heating integration adoption rates and modular construction penetration assumptions.
Underlying measurement precision varies by segment; hyperscale developments carry tighter precision than edge facility projections due to greater disclosure transparency. Forecasts reflect documented assumptions regarding Energinet queue progression, copper price stabilization, and sustained EU Energy Efficiency Directive enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Brazil Infrastructure Sector Market