
 Fogging Machine Market | 2026-2036
Fogging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fogging Machine Market Analysis
Chinese manufacturers of thermal fogging equipment is rebalancing production capacity toward battery-powered and electrostatic platforms. pulsFOG leverages its German engineering heritage to dominate precision agriculture applications across Europe. Curtis Dyna-Fog anchors North American supply through its long-standing institutional relationships with vector control agencies. IGEBA competes on manufacturing scale, sustaining broad distribution across emerging markets for public health campaigns.
A fogging machine generates aerosolized droplets through thermal, ultra-low volume, or electrostatic processes, typically producing particles between 5 and 50 microns for targeted deposition on surfaces or in atmospheres. Thermal foggers heat oil-based solutions to create dense visible mist for outdoor pest suppression and vector control operations. Battery-powered foggers now represent the fastest-expanding product category as operators prioritize cordless mobility and reduced fuel emissions in indoor disinfection and horticulture settings. ULV cold fogging technology captures concentrated margin pools in healthcare and hospitality end-use segments where particle precision determines efficacy against airborne pathogens.
EPA registration requirements govern antimicrobial claims and device efficacy in the United States, while REACH and CE marking frameworks in Europe restrict chemical formulations and electromagnetic compatibility for fogging equipment sold across EU member states. India's CDSCO and BIS standards increasingly influence product specifications for disinfection devices deployed in healthcare and agricultural programs. Stakeholders must monitor evolving chemical registration timelines and battery safety certifications as regulatory divergence between major markets intensifies compliance complexity for multinational suppliers.
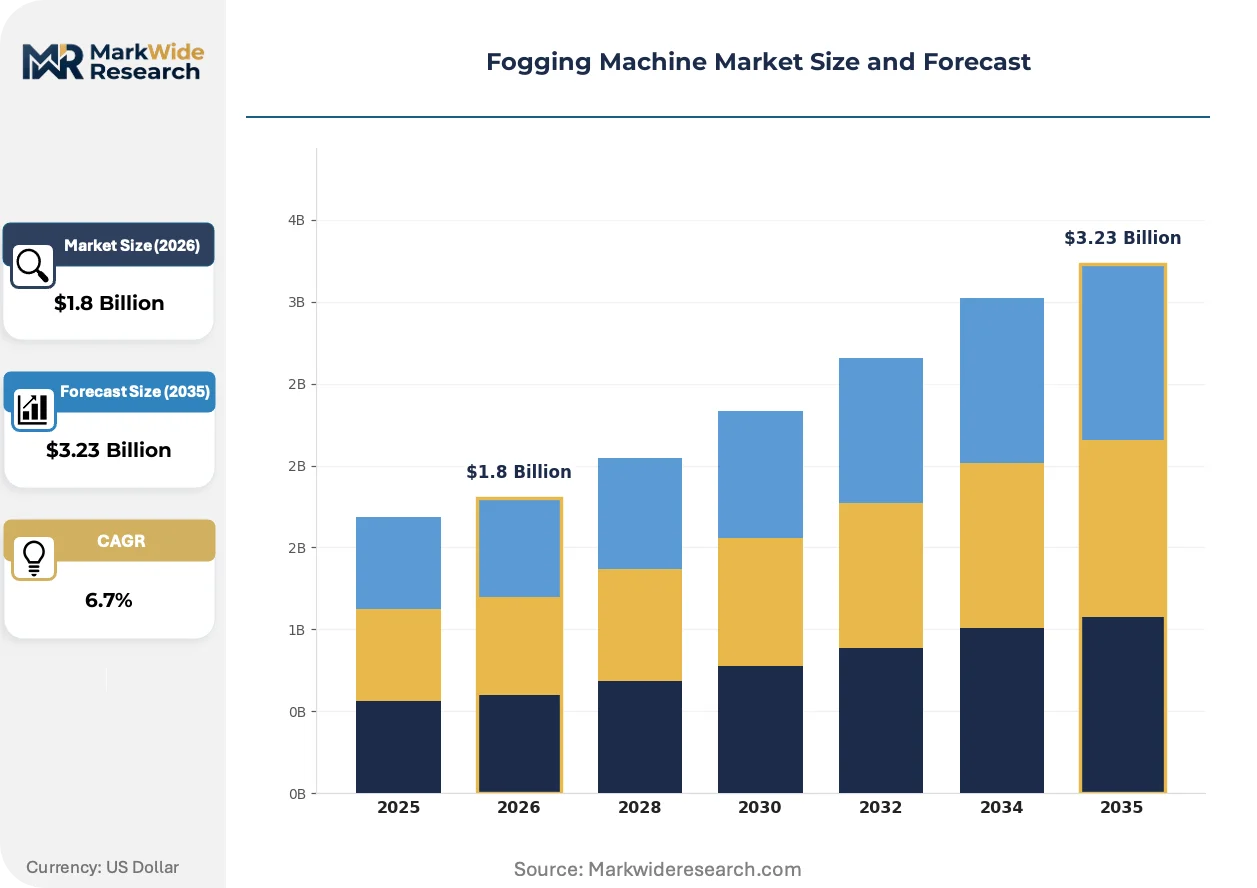
Market Dynamics
Battery-powered fogging platforms are compressing thermal fogger margins while EPA antimicrobial device registrations tighten compliance timelines for all US market entrants.
Growth Catalysts
- Vector control mandates:Brazil's Ministry of Health sustains procurement volumes for dengue and Zika suppression campaigns in municipalities across São Paulo and Minas Gerais.
- REACH chemical restrictions:European ECHA frameworks on biocidal products are accelerating formulation reformulation toward oil-free carriers compatible with electrostatic delivery.
- ULV precision agriculture:Vineyard operators in France and Italy deploy cold fogging for targeted pesticide application, reducing chemical runoff into watersheds.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings constrain margin stability for cordless platform manufacturers dependent on Chinese cathode supply.
- Thermal fogger obsolescence risk:Oil-based solution dependency limits indoor deployment as hospitality and healthcare sectors enforce zero-VOC protocols.
- CE marking electromagnetic compliance:Radio frequency certification for connected fogging units extends European market entry timelines by eight to fourteen months.
Strategic Opportunities
- Indian healthcare expansion:CDSCO registration pathways for disinfection devices remain underpenetrated by foreign suppliers despite government hospital procurement scaling.
- Electrostatic-battery convergence:Combined platforms enable charged droplet adhesion on vertical surfaces, opening food processing and pharmaceutical cleanroom applications.
- Direct-to-municipality channels:Vector control agencies in sub-Saharan Africa are bypassing distributor networks for tender-based procurement of WHO-prequalified equipment.
Industry Challenges
- EPA efficacy data requirements:Antimicrobial device registration demands standardized kill-rate studies that extend development cycles and strain smaller engineering teams.
- Electrostatic calibration expertise:Field technicians require training on voltage optimization and grounding protocols that most distributor service networks currently lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fogging Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Foggers, Thermal Foggers, ULV Foggers, Battery-Powered Foggers End User: Agriculture, Healthcare, Hospitality, Pest Control Technology: Electrostatic, Conventional, Induction, Micro-Ultra Low Volume Application: Public Health, Pest Management, Disinfection, Horticulture |
| Companies Covered | pulsFOG, Fogmaster Corporation, Curtis Dyna-Fog, TFI Thermal Fogging Innovations, SM Bure, IGEBA, PESTWORKER, Airofog Machinery, Vectorfog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fogging Machine Market Emerging Trajectories
Equipment electrification and regulatory chemical restrictions are forcing simultaneous hardware and formulation redesign across all major supply bases.
Battery-powered cold fogging is electrifying indoor disinfection workflows. Hospitality chains and hospital facilities procurement teams specify cordless units for overnight sanitization cycles without ventilation downtime. This shift is compressing thermal fogger replacement demand in developed markets while opening premium pricing tiers for lithium-ion platforms with swappable cell architectures.
REACH biocidal product authorization timelines are extending market entry windows for new antimicrobial formulations. European ECHA compliance costs now exceed fifty thousand euros per active substance dossier, forcing consolidation among chemical suppliers. ULV equipment manufacturers with pre-certified carrier solutions capture disproportionate share in German and Dutch healthcare tenders.
Service unbundling is disrupting traditional distributor relationships. Large agricultural cooperatives in California and Queensland now lease fogging equipment with per-hectare chemical supply contracts rather than capital purchase. This consumption-based model shifts technical support burdens to manufacturers while compressing dealer margins and accelerating direct OEM engagement with end-users.
Fogging Machine Market Segmentation
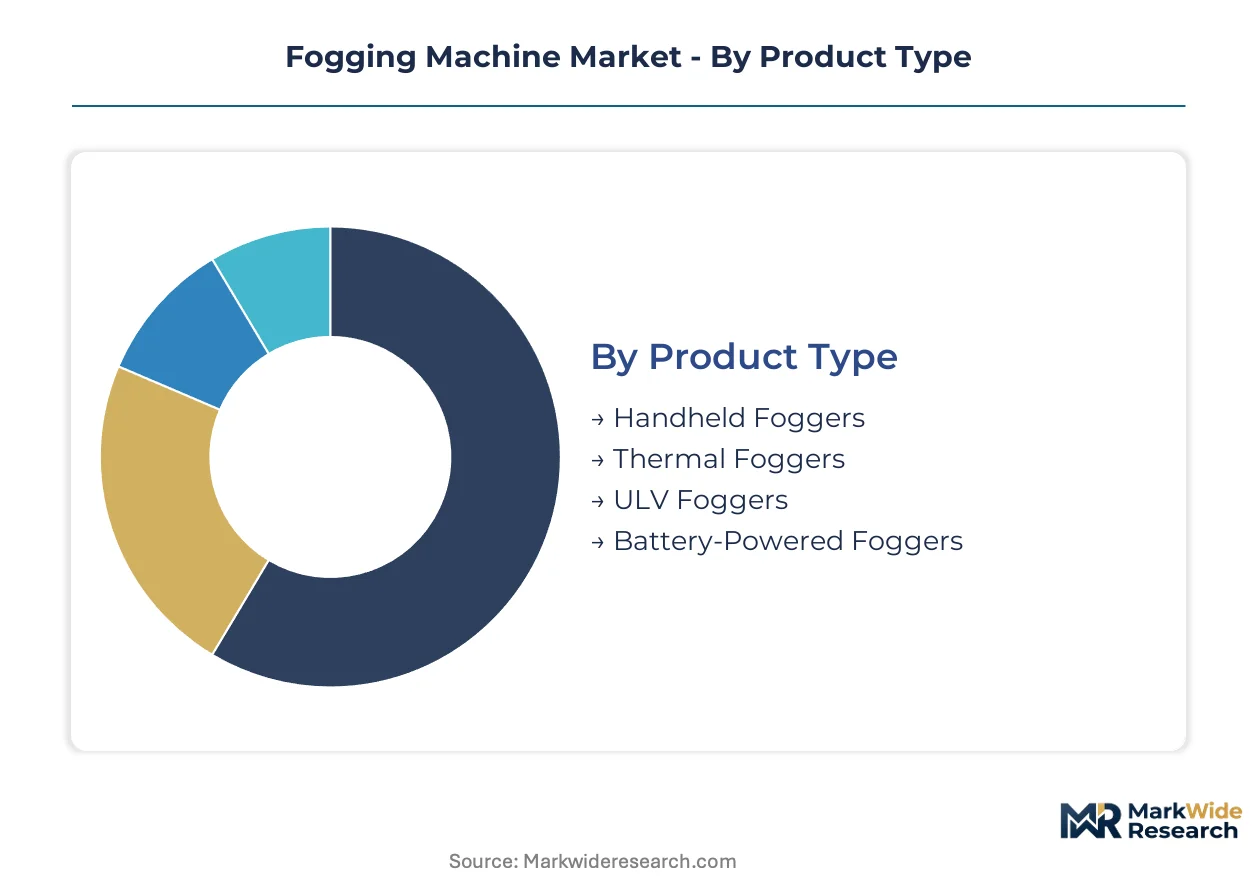
Equipment specification and certification pathways diverge sharply across fogging platforms, with thermal systems requiring EPA combustion safety approvals while battery-powered units face lithium-ion transport regulations. End-use application dictates droplet size precision requirements, creating tiered compliance burdens that reshape supplier positioning across agricultural, healthcare, and public health verticals.
Product Type:
EPA antimicrobial device registrations apply selectively across thermal and battery platforms, while CE electromagnetic compliance creates divergent European entry timelines for oil-based versus electrostatic systems.
- Handheld Foggers:Portable units under ten kilograms enable operator mobility in confined indoor spaces. Demand concentrates in hospitality housekeeping departments across São Paulo and Mumbai, where overnight disinfection protocols prioritize maneuverability over tank capacity. OSHA ventilation requirements constrain deployment in US healthcare settings without supplementary air monitoring.
- Thermal Foggers:Oil-based solution heating generates dense aerosol plumes for outdoor vector suppression. Procurement volumes from Brazil's Ministry of Health sustain manufacturing scale, though tightening zero-VOC protocols in European hospitality are compressing indoor applicability. REACH carrier restrictions force reformulation toward vegetable-derived oils.
- ULV Foggers:Cold fogging technology produces precise 5-20 micron droplets for targeted deposition. French vineyard operators deploy units for pesticide reduction programs.
- Battery-Powered Foggers:Lithium-ion cordless platforms eliminate fuel emissions and ventilation downtime. Swappable cell architectures command premium pricing in German hospital procurement.
Thermal foggers sit at the top of the volume ranking, with battery-powered foggers climbing the fastest.
End User:
Customer procurement sophistication varies dramatically, with vector control agencies demanding WHO prequalification while agricultural cooperatives prioritize per-hectare operating economics over capital expenditure.
- Agriculture:Vineyard and greenhouse operators in Italy and California deploy precision droplet systems for integrated pest management. Leasing models with bundled chemical supply contracts are displacing capital purchases among Queensland cooperatives.
- Healthcare:Hospital infection control departments specify ULV precision for airborne pathogen suppression. CDSCO registration requirements in India create compliance barriers for foreign suppliers despite government procurement scaling.
- Hospitality:Hotel chains mandate cordless overnight sanitization cycles without guest room ventilation downtime. Battery platform specifications dominate RFP criteria in Dubai and Singapore luxury properties.
- Pest Control:Professional applicators in Florida and Texas sustain thermal fogger replacement demand for mosquito abatement contracts. EPA efficacy data requirements strain smaller operator technical resources.
Pest control sits at the top of the volume ranking, with healthcare climbing fastest on infection control investment.
Technology:
Patent thickets and calibration expertise requirements create defendable competitive positions for electrostatic and micro-ULV platforms, while conventional technology faces commoditization pressure.
- Electrostatic:Charged droplet adhesion enables vertical surface coverage with reduced chemical volume. Food processing facilities in the Netherlands and pharmaceutical cleanrooms in Switzerland specify grounded calibration protocols that most distributor networks cannot support.
- Conventional:Mechanical atomization without electrical charging dominates entry-level agricultural applications. Price compression from Chinese manufacturers limits margin expansion.
- Induction:Electromagnetic droplet generation reduces nozzle clogging in high-viscosity formulations. Brazilian sugarcane operators adopt units for fungicide application.
- Micro-Ultra Low Volume:Sub-10 micron particle systems target respiratory pathogen transmission in healthcare settings. ECHA biocidal authorization timelines extend market entry for new carrier formulations.
Conventional technology sits at the top of the volume ranking, with electrostatic platforms gaining share fastest on premium application expansion.
Application:
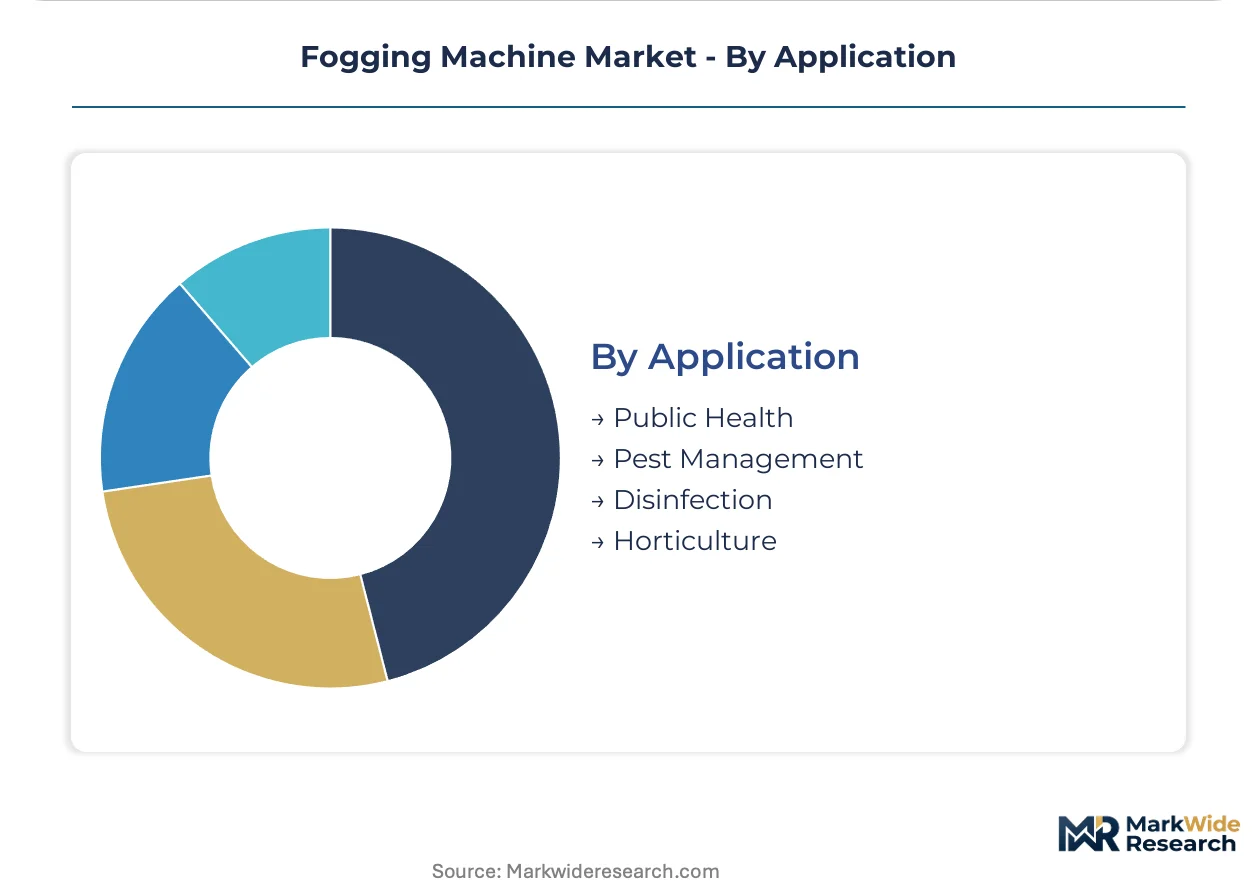
Regulatory intensity escalates from horticultural pest management through public health vector control to healthcare disinfection, with antimicrobial claim verification creating tiered compliance costs.
- Public Health:Municipal dengue and Zika suppression campaigns in Minas Gerais and sub-Saharan Africa sustain thermal fogger procurement. WHO prequalification requirements filter supplier eligibility for tender-based procurement.
- Pest Management:Professional mosquito and rodent control services in the southern United States prioritize equipment durability and field serviceability.
- Disinfection:Post-pandemic protocols in German hospitals and UAE hospitality properties specify particle size documentation for insurance liability coverage. EPA kill-rate study requirements extend development cycles for antimicrobial device registrations.
- Horticulture:Greenhouse operators in the Netherlands deploy precision fogging for humidity control and foliar feeding. Water quality regulations constrain chemical runoff into watershed protection zones.
Pest management sits at the top of the volume ranking, with disinfection applications expanding most quickly on permanent protocol institutionalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence in antimicrobial device compliance is redirecting production investment toward jurisdictions with streamlined certification pathways. Manufacturers are arbitraging cost-of-compliance gaps between EPA registration timelines in the United States and accelerated CDSCO pathways in India.
United States
Vector control agencies in Florida and Texas sustain thermal fogger replacement cycles for mosquito abatement contracts. EPA antimicrobial device registrations impose standardized kill-rate study requirements that extend development timelines for new entrants. Houston-based pest control operators now specify battery-powered platforms for indoor residential applications.
Germany
Hospital infection control departments in Bavaria and North Rhine-Westphalia procure ULV precision systems for airborne pathogen suppression. ECHA biocidal product authorization timelines exceed fifty thousand euros per active substance dossier, forcing formulation consolidation among chemical suppliers. Stuttgart-area vineyard operators deploy cold fogging for integrated pest management programs.
Brazil
The Ministry of Health sustains municipal procurement volumes for dengue and Zika suppression campaigns across São Paulo and Minas Gerais. ANVISA registration requirements for disinfection devices remain less stringent than EPA equivalents, attracting Asian manufacturers seeking Latin American market entry. Campinas industrial clusters host assembly operations for thermal fogging equipment.
India
Government hospital procurement scaling in Maharashtra and Karnataka is outpacing foreign supplier CDSCO registration completions. BIS standards for battery-powered disinfection devices are tightening electromagnetic compatibility requirements. Pune-based agricultural cooperatives are adopting leasing models with bundled chemical supply contracts.
China
Manufacturers in Guangdong and Zhejiang provinces are rebalancing capacity from thermal toward battery-powered and electrostatic platforms. GB standards for lithium-ion transport safety are constraining export certification timelines. Shenzhen industrial parks concentrate electrostatic fogging module production for European OEM supply.
Fogging Machine Market Vendor Landscape
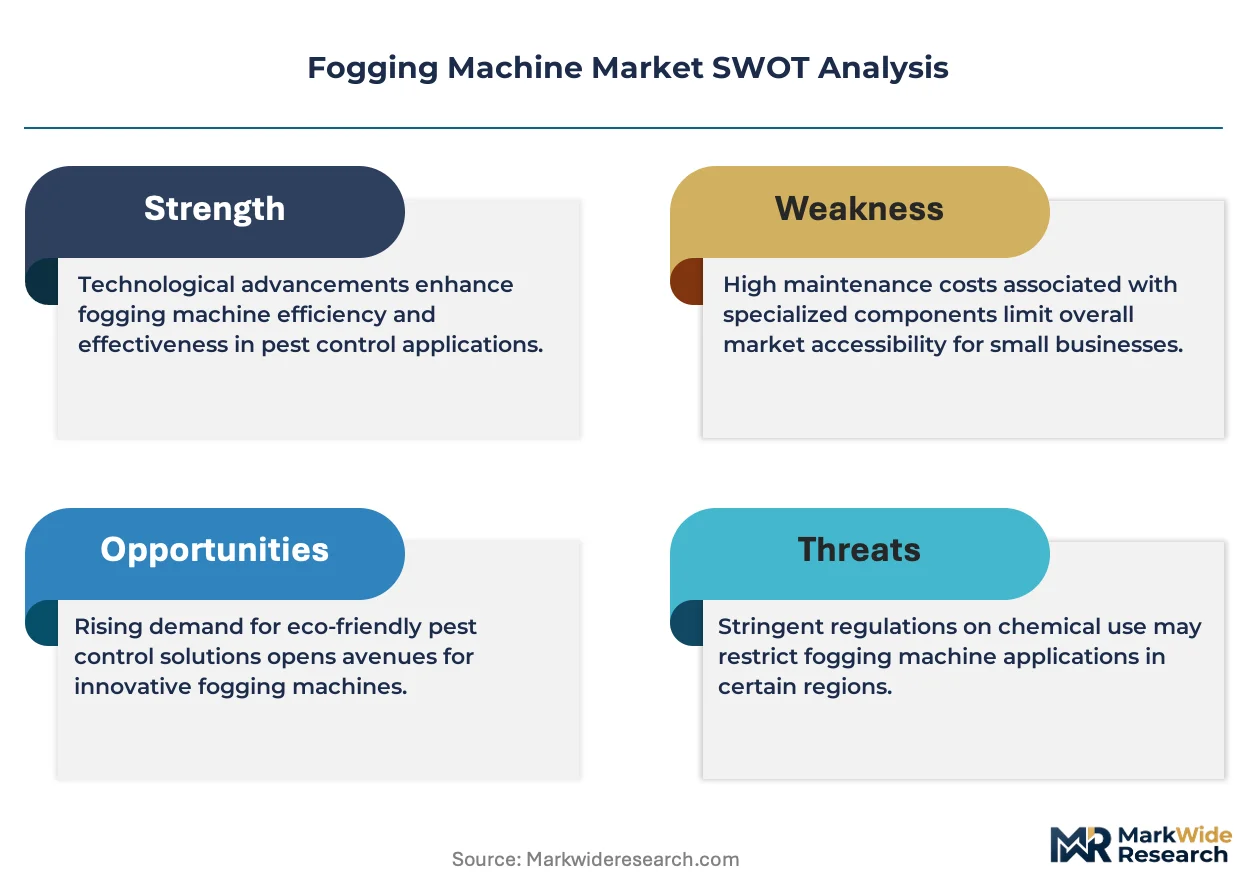
Established producers occupy the standard tier; emerging entrants pursue cordless mobility and electrostatic convergence. The vendor base stratifies between precision agriculture specialists and public health campaign suppliers. Three archetypes dominate: German-engineered precision platforms, North American vector control incumbents, and Chinese scale manufacturers. Competitive moves concentrate on direct OEM engagement with agricultural cooperatives and accelerated battery platform certification.
Within the precision-tier, pulsFOG exemplifies German-engineered heritage positioning for vineyard and greenhouse applications. Curtis Dyna-Fog occupies a position as the North American incumbent with institutional vector control relationships. IGEBA anchors the scale-driven archetype with broad emerging market distribution for public health campaigns.
| Leading Market Players |
|---|
| pulsFOG |
| Fogmaster Corporation |
| Curtis Dyna-Fog |
| TFI Thermal Fogging Innovations |
| SM Bure |
| IGEBA |
| PESTWORKER |
| Airofog Machinery |
| Vectorfog |
| Others |
Supply Flow & Price Mechanics
Vector control agencies in Brazil and municipal procurement offices across sub-Saharan Africa concentrate demand into tender-based bulk purchasing, compressing margins through volume aggregation while favoring suppliers with direct OEM relationships over distributor intermediaries.
Pricing Analysis
Distributor margins in developed markets absorb 25-35 points before equipment reaches end-users, though direct-to-municipality channels in emerging economies are collapsing this layer. Three-tier pricing structure across precision agriculture, healthcare certification-grade, and entry-level thermal platforms separates German-engineered ULV systems from Chinese battery-powered units from legacy oil-based equipment. Cost compression in cordless platforms is intensifying because lithium-ion cell volatility feeds through to bill-of-materials instability. Agricultural cooperatives in Queensland and California exhibit highest price sensitivity through leasing model adoption, while German hospital procurement teams prioritize swappable cell architectures over unit economics.
Supply Chain Analysis
Workforce availability for electrostatic module assembly concentrates in Shenzhen industrial parks and Guangdong province manufacturing zones, where technical labor pools support precision nozzle production. Supply draws from Chinese lithium-ion cathode processing, German precision pump engineering, and Brazilian thermal fogger component forging. Single-source vulnerability sits with concentrated battery cell supply from Zhejiang and Jiangsu provinces. Distribution runs through WHO-prequalified equipment registries for public health campaigns, agricultural cooperative leasing networks, and direct OEM engagement with hospitality procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through electrostatic-battery convergence platforms that command premium positioning while thermal fogger commoditization forces cost discipline on legacy portfolios.
For Market Incumbents: To counter battery-powered platform erosion from Chinese scale manufacturers, deepen backward integration into lithium-ion cell architectures and captive supply of electrostatic charging modules. Anchor channel control through direct tender engagement with Brazil's Ministry of Health and sub-Saharan African vector control agencies, bypassing distributor margin capture. For New Entrants and Emerging Players: Electrostatic calibration expertise for food processing cleanrooms represents the most penetrable white-space target, as incumbent distributor networks lack voltage optimization training infrastructure. CDSCO registration completion for Indian government hospital procurement outpaces foreign supplier filings, creating first-mover access to Maharashtra and Karnataka scaling programs. Pursue per-hectare leasing contracts with Queensland agricultural cooperatives to displace capital purchase models. For Investors and Strategic Acquirers: Precision agriculture OEMs are the most active acquirer in this space, seeking electrostatic module capabilities for vineyard and greenhouse integration. Five-to-ten year viability hinges on chemical formulation certification moats rather than hardware commoditization. Signal to monitor: EPA antimicrobial device registration backlog duration as indicator of competitive entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic-Battery Platform Convergence | Opens pharmaceutical cleanroom and food processing verticals through charged droplet adhesion protocols. |
| Direct-to-Municipality Channel Development | Bypasses distributor margin capture in Brazilian dengue suppression and sub-Saharan vector control tenders. |
| CDSCO Registration Acceleration | Captures Indian government hospital procurement scaling ahead of foreign competitor compliance completion. |
| Leasing Model with Bundled Chemical Supply | Shifts California and Queensland agricultural cooperatives from capital purchase to consumption-based contracts. |
| REACH-Compliant Formulation Pre-Certification | Secures German and Dutch healthcare tender preference as ECHA authorization timelines extend. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with vector control procurement officers, hospital infection control directors, agricultural cooperative technical managers, and OEM product development leads with secondary validation through EPA antimicrobial device registration databases, ECHA biocidal product authorization filings, ANVISA equipment registries, and WHO prequalification lists. Bottom-up equipment shipment analysis triangulated against top-down chemical formulation demand modeling.
Segment-weighting applied product type, end-use vertical, technology platform, and geographic regulatory cluster dimensions across the analysis window. CAGRs derived from equipment replacement cycle analysis, chemical consumption intensity ratios, and procurement budget elasticity by buyer archetype. Forecast inputs incorporated lithium-ion cell price trajectory assumptions and EPA registration timeline duration estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical authorization delays, CDSCO regulatory pathway acceleration, and battery raw material supply concentration shifts. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Trenchers Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Winch Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Construction Pump Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Compressed Earth Block Machine Market