
 Bulldozer Market | 2026-2036
Bulldozer Market Size, Share, and Industry Trends Forecast 2026-2036
Bulldozer Market Intelligence
Equipment leasing networks across North America and Southeast Asia are reconfiguring how contractors access bulldozer capacity without capital commitment. Caterpillar leverages its captive finance arm to control fleet placement and residual value management. Komatsu competes through telematics-integrated maintenance contracts that extend machine availability. Shantui anchors volume in domestic Chinese projects while building export presence in Central Asian mining.
A bulldozer is a tracked or wheeled tractor equipped with a front-mounted blade for pushing soil, rock, and debris, typically powered by diesel engines ranging from 80 to 850 horsepower depending on application class. Crawler configurations dominate mining and heavy civil work where ground pressure below 35 kPa prevents sinkage on unimproved terrain. Electric drive technology is gaining fastest in underground mining segments where ventilation cost reduction justifies premium capital outlay. GPS grading systems now sit at the margin pool center as contractors demand precision earthwork with reduced labor inputs.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe enforce diesel particulate limits that push manufacturers toward exhaust aftertreatment and alternative powertrains. China's MEE enforces National VI-equivalent standards that constrain engine imports while favoring domestic suppliers. ISO 5006 visibility standards and emerging ISO remote-operation protocols will reshape cab design and operator certification requirements. Stakeholders must monitor regulatory divergence between emission jurisdictions and assess which technology pathways offer transferable compliance across multiple markets.
Market Dynamics
Emission compliance deadlines are compressing engine development cycles while simultaneously elevating equipment costs, forcing fleet operators to reassess replacement timelines and financing structures across mining and heavy civil sectors.
Growth Catalysts
- Underground ventilation economics:Electric drive systems reduce diesel particulate exposure and ventilation infrastructure costs in confined mining environments. Australian hard-rock operators are retrofitting existing fleets with battery-electric powertrains.
- EPA Tier 4 Final enforcement:US emission mandates for off-road diesel equipment are accelerating scrappage of pre-2014 machines and creating replacement demand in construction and forestry applications.
- Central Asian mining corridors:Kazakhstan and Uzbekistan copper-gold developments are importing high-horsepower crawler units for pit development and haul road maintenance.
Market Restraints
- Aftertreatment cost inflation:Diesel oxidation catalysts, selective catalytic reduction systems, and diesel particulate filters now constitute 18-25% of engine bill-of-materials, squeezing margin pools for mid-tier manufacturers.
- Steel and hydraulics supply concentration:High-grade plate steel and precision hydraulic valve production clusters in China and Germany expose OEMs to input volatility and logistics disruption.
- Electric infrastructure gap:Remote mining sites lack grid connectivity and charging infrastructure necessary for battery-electric machine deployment at scale.
Strategic Opportunities
- Western China infrastructure corridors:State-backed rail and highway projects through Xinjiang and Tibet require specialized high-altitude bulldozer configurations with derated engine mappings.
- Telematics-integrated service contracts:Remote condition monitoring enables predictive maintenance revenue streams and machine availability guarantees that differentiate aftermarket offerings.
- EU Stage V retrofit pathways:European emission standards create certified repowering demand for older machines, opening remanufacturing and engine-swap service markets.
Industry Challenges
- Powertrain engineering talent scarcity:The convergence of diesel aftertreatment, battery-electric, and fuel-cell architectures demands hybrid skill sets spanning mechanical and electrical engineering disciplines that remain underrepresented in vocational pipelines.
- ISO 5006 visibility compliance:Revised cab sightline standards require structural redesign of engine hoods and ROPS structures, extending certification timelines and retooling capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulldozer Market |
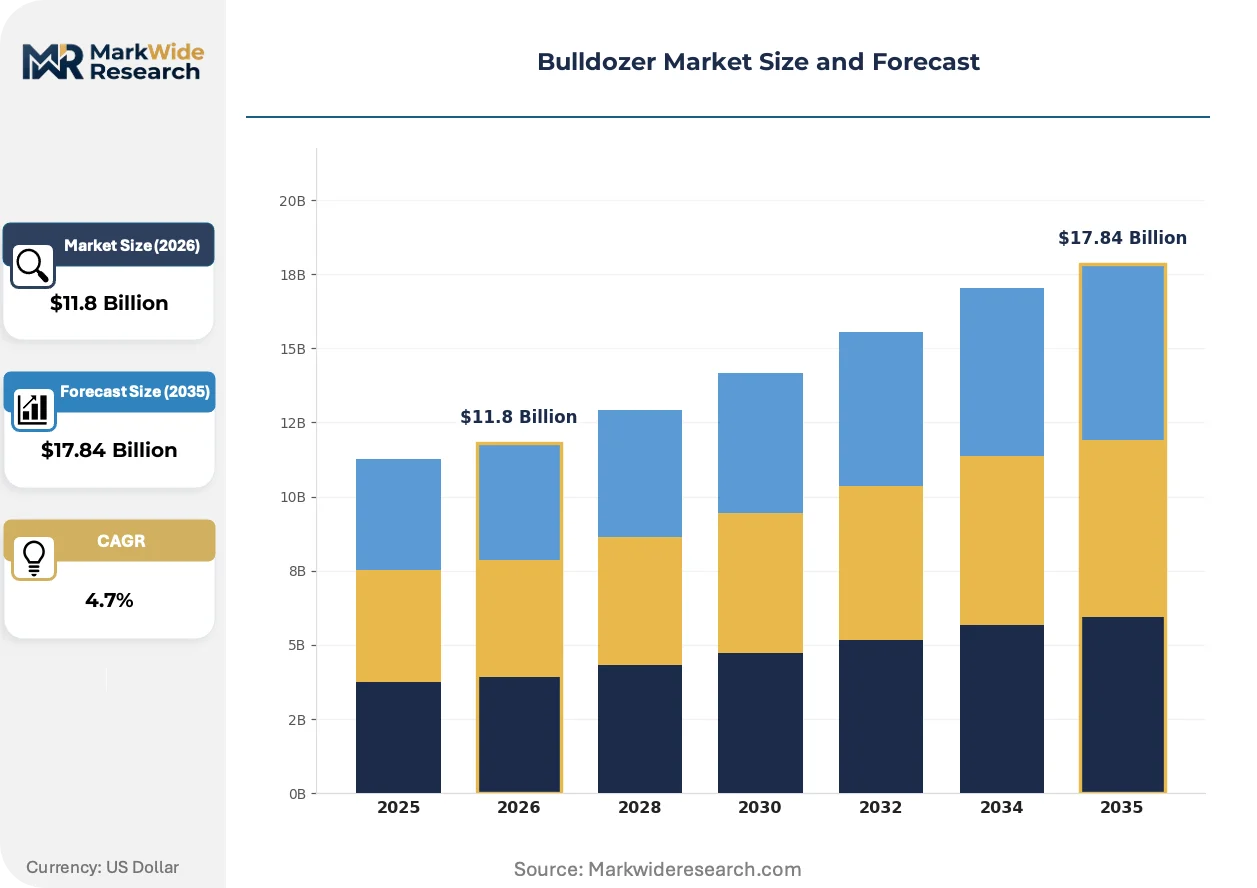
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler, Wheel, Mini, Swamp, High-Speed Technology: Diesel Engine, Electric Drive, Hydraulic System, GPS Grading, Remote Control Application: Construction, Mining, Forestry, Quarrying, Land Reclamation End User: Contractors, Government Departments, Infrastructure Developers, Agricultural Firms |
| Companies Covered | Liebherr, Case, Caterpillar, ACCO, LiuGong, Komatsu, John Deere, Fiat Allis, Shantui, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulldozer Market Strategic Shifts & Innovations
Digital twin technology and autonomous control systems are redefining operator productivity metrics and fleet management economics across earthmoving operations, compressing the traditional boundaries between machine control and site-level optimization.
Telematics platforms is virtualizing machine performance data into cloud-based analytics that enable real-time fuel consumption benchmarking and operator behavior scoring. Large mining contractors in Chile and Australia are mandating OEM-installed connectivity hardware as a procurement precondition. This virtualization of operational intelligence is compressing the information asymmetry between equipment lessors and fleet operators, enabling usage-based pricing models.
EU Stage V particulate number limits are forcing exhaust aftertreatment architecture changes that increase under-hood thermal management complexity. European OEMs are integrating active regeneration cycles and thermal insulation packages that extend engine compartment service intervals. Underground mining segments in Poland and Sweden are responding with dedicated low-emission machine variants that qualify for ventilation cost subsidies.
Contractor procurement preferences are gravitating toward availability-based service agreements that transfer uptime risk to OEMs or their financing affiliates. North American equipment lessors are unbundling maintenance from capital leases and offering standalone service contracts with guaranteed response-time clauses. This behavioral shift is most pronounced in pipeline construction and renewable energy site preparation, where schedule certainty outweighs capital ownership preferences.
Bulldozer Market Segmentation
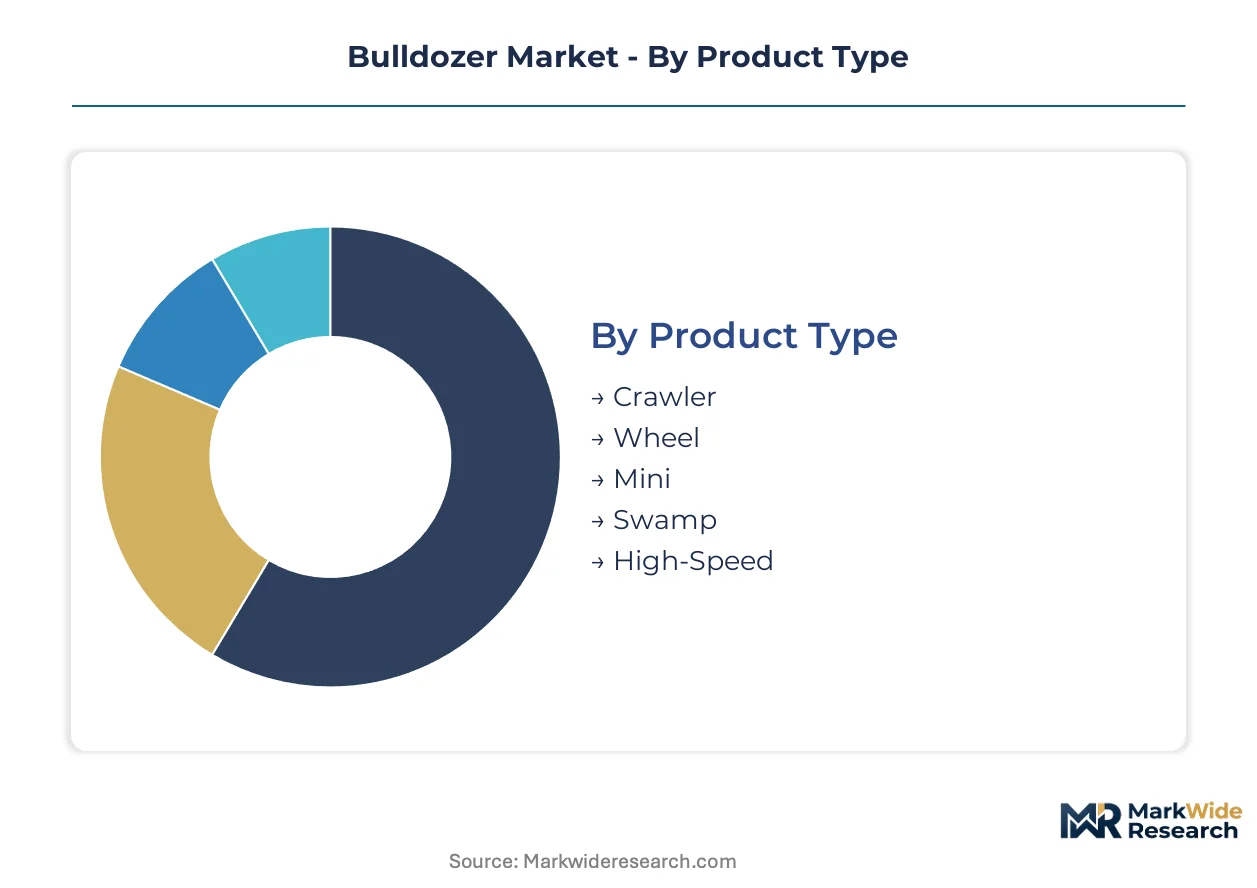
Segmentation reveals how equipment specifications align with duty cycles and capital recovery timelines across mining, civil, and forestry applications. Fleet operators match product configurations to terrain constraints and emission compliance requirements, creating distinct replacement rhythms and aftermarket service opportunities.
Product Type:
Crawler units turn over slowest in heavy mining fleets where 15,000-hour rebuild cycles extend economic life, while mini and high-speed configurations cycle faster in rental pools and seasonal construction.
- Crawler:Tracked chassis with ground pressure below 35 kPa enables operation on unimproved terrain in Australian iron ore and Chilean copper pits. Mining operators in Kazakhstan and Uzbekistan are expanding orders for 400+ horsepower units for haul road maintenance and pit development.
- Mini:Compact frames under 80 horsepower serve urban demolition and residential site preparation where maneuverability constraints dominate. Chinese contractors in dense western provincial cities favor these units for infrastructure corridor work in restricted spaces.
- Wheel:Rubber-tired configurations achieve 35-50 km/h transport speeds between dispersed civil sites, reducing lowboy logistics costs for North American pipeline contractors.
- Swamp:Wide track shoes and sealed undercarriages distribute weight across marshy substrates in land reclamation and wetland construction across the US Gulf Coast and Southeast Asian deltas.
- High-Speed:Modified transmission ratios and enhanced suspension systems support rapid site-to-site movement in European road maintenance and emergency response fleets.
Crawler configurations anchor the volume base while mini units gain share at the steepest rate in urban equipment rental networks.
Technology:
Cost tiers separate established diesel architectures from emerging electric and autonomous systems that command premium positioning and specialized infrastructure.
- Diesel Engine:EPA Tier 4 Final and EU Stage V aftertreatment systems now constitute 18-25% of engine bill-of-materials, elevating upfront costs while extending service intervals through electronic fuel mapping.
- Electric Drive:Battery-electric powertrains eliminate diesel particulate exposure and reduce ventilation infrastructure demands in Australian and Polish underground hard-rock mines. Swedish operators qualify for ventilation cost subsidies with dedicated low-emission variants.
- Hydraulic System:Precision valve clusters from German and Chinese suppliers enable load-sensing implement control that reduces fuel consumption in repetitive grading cycles.
- GPS Grading:Satellite-guided blade control systems compress earthwork labor inputs and surface tolerance variance in precision site preparation for renewable energy installations.
- Remote Control:ISO-compliant teleoperation protocols enable hazardous material handling and slope stabilization work without cab exposure to rockfall or unstable ground.
Diesel engines retain the largest installed base while electric drive systems climb the fastest in underground mining segments where ventilation economics justify capital premiums.
Application:
Volume concentrates in construction and mining where machine utilization rates and fleet standardization support manufacturer service contract economics.
- Construction:Highway, dam, and urban infrastructure projects in China's western provinces require specialized high-altitude configurations with derated engine mappings for thin-air operation.
- Mining:Open-pit and underground extraction operations in Australia, Chile, and Central Asia drive demand for high-horsepower crawler units with reinforced undercarriages and extended warranty coverage.
- Forestry:Land clearing and road building in North American timber belts utilize grapple-equipped variants with protective guarding against stump and debris impact.
- Quarrying:Aggregate extraction sites favor mid-size crawler units for bench maintenance and stockpile management where production continuity depends on machine availability.
- Land Reclamation:Coastal restoration and mine closure projects in the US and Europe employ swamp configurations for sensitive terrain work where ground disturbance minimization is specified.
Construction applications anchor the volume base while mining gains share at the steepest rate in fleet replacement cycles driven by emission compliance deadlines.
End User:
Customer type determines procurement structure, with contractors favoring operating leases and government entities specifying domestic content and certification requirements.
- Contractors:North American and Southeast Asian construction firms are shifting toward availability-based service agreements that transfer uptime risk to OEM financing affiliates.
- Government Departments:State-backed infrastructure agencies in China and Central Asia specify equipment procurement through centralized tenders with local assembly requirements.
- Infrastructure Developers:Rail and highway corridor projects across Kazakhstan and Uzbekistan import high-horsepower units through multilateral financing structures.
- Agricultural Firms:Land consolidation and irrigation projects in arid regions utilize medium-duty crawler units for field leveling and drainage system installation.
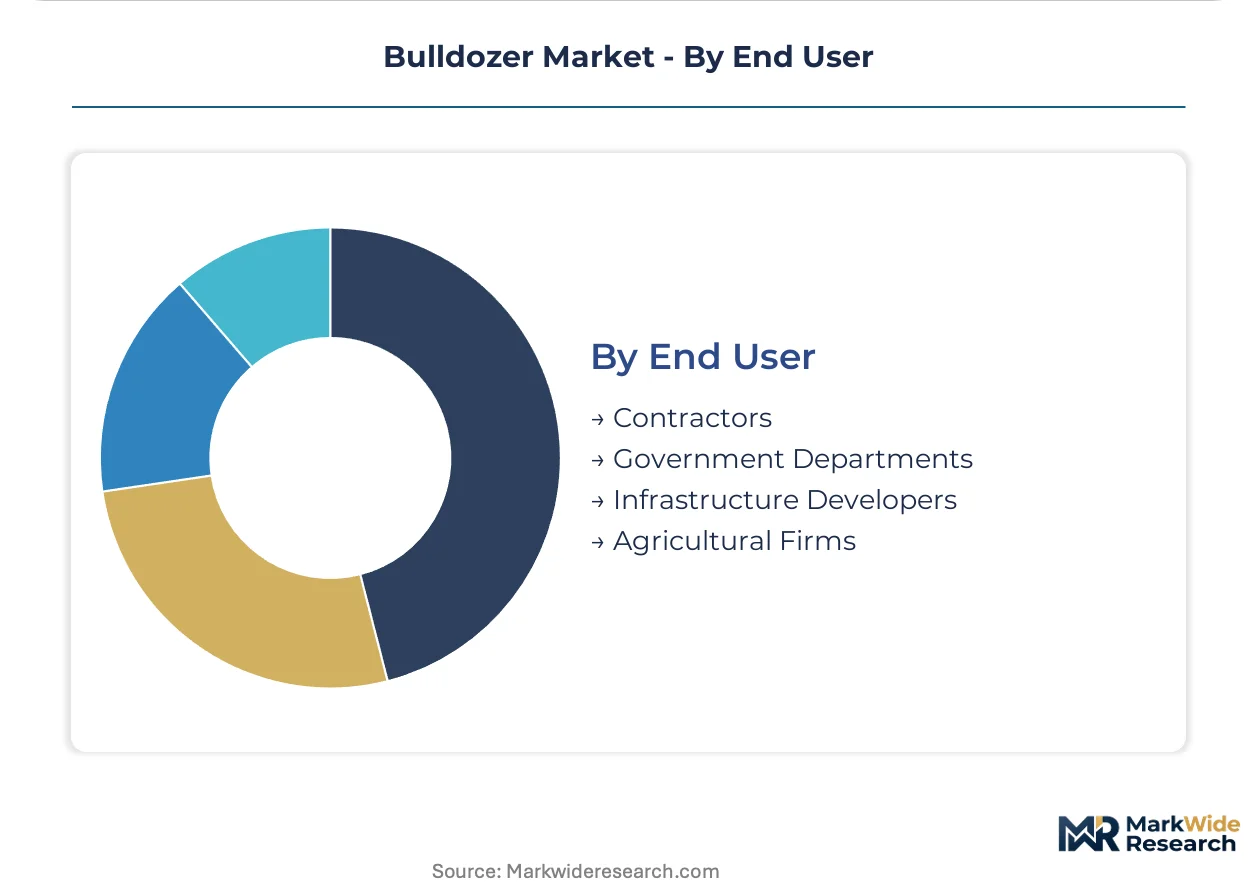
Contractors anchor the volume base while infrastructure developers gain share at the steepest rate in state-backed corridor investments across Central Asian mining regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australian mining corridors where high-horsepower crawler units command 15-20% premiums over equivalent equipment in North American civil markets. Equipment lessors in Chile and Kazakhstan absorb currency volatility through dollar-denominated service contracts. Chinese manufacturers leverage domestic steel and hydraulic component clusters to undercut European OEMs on baseline configurations.
United States
Pipeline contractors across Texas and the Mountain West states favor wheel configurations for rapid site-to-site deployment on dispersed renewable energy projects. EPA Tier 4 Final enforcement accelerates scrappage of pre-2014 machines in forestry and construction fleets. Caterpillar's captive finance arm dominates fleet placement in the Permian Basin oilfield services corridor.
Australia
Iron ore operators in Western Australia's Pilbara region expand orders for 400+ horsepower crawler units with extended warranty coverage. Battery-electric retrofit programs qualify for state ventilation cost subsidies in underground hard-rock mines. Komatsu anchors aftermarket service contracts through telematics-integrated availability guarantees across Queensland coal developments.
China
State-backed rail and highway corridors through Xinjiang and Tibet provinces require specialized high-altitude bulldozer configurations with derated engine mappings. MEE National VI-equivalent standards constrain imported engine architectures while favoring domestic suppliers like Weichai and Yuchai. Shantui leverages Shandong Province manufacturing clusters to capture volume in western provincial infrastructure tenders.
Germany
EU Stage V particulate number limits force exhaust aftertreatment redesigns that elevate equipment costs for mid-tier manufacturers. Precision hydraulic valve production concentrates in Baden-Württemberg industrial corridors around Stuttgart. Liebherr anchors European premium positioning through integrated remanufacturing services for older machine repowering.
Chile
Copper pit development in the Atacama Desert drives demand for reinforced undercarriage crawler units with ground pressure below 35 kPa. Mining contractors mandate OEM-installed connectivity hardware as procurement preconditions for fleet standardization. Centralized equipment lessors in Santiago structure dollar-indexed operating leases to hedge peso volatility.
Bulldozer Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in hydraulic valve and high-grade steel supply. The vendor base organizes around three archetypes: diversified industrial conglomerates with captive finance arms, specialized earthmoving OEMs with regional manufacturing footprints, and state-backed Chinese producers with domestic volume anchors. Consolidation pressure intensifies as emission compliance costs squeeze mid-tier manufacturers without scale economies in aftertreatment engineering. Strategic moves center on telematics-integrated service contract expansion and backward integration into precision hydraulic component production.
Among diversified industrial conglomerates, Caterpillar and Komatsu exemplify platform integrators with financing affiliates that control residual value management and fleet placement. John Deere occupies a position bridging agricultural and construction equipment with shared powertrain architectures. Within the state-backed tier, Shantui and LiuGong represent volume-driven Chinese producers leveraging domestic infrastructure demand to fund export expansion into Central Asian mining corridors.
| Leading Market Players |
|---|
| Liebherr |
| Case |
| Caterpillar |
| ACCO |
| LiuGong |
| Komatsu |
| John Deere |
| Fiat Allis |
| Shantui |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese steel plate and hydraulic component production compresses supplier margins while enabling aggressive export pricing for baseline crawler configurations. This utilization imbalance forces mid-tier OEMs toward either premium customization strategies or volume-driven domestic market capture.
Pricing Analysis
The customization-premium spread widens most sharply between EPA Tier 4 Final-certified machines and standard export configurations. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with aftertreatment complexity and telematics bundling as primary differentiation drivers. Pricing pressure stems from Chinese manufacturers leveraging domestic input cost advantages in Central Asian tenders. Rental fleet operators exhibit highest price sensitivity, while Australian mining contractors prioritize availability guarantees over capital outlay.
Supply Chain Analysis
Export-control regimes on precision hydraulic valve manufacturing equipment constrain technology transfer to emerging producers, entrenching German and Chinese supplier dominance. High-grade plate steel production clusters in China, Germany, and Japan, with precision hydraulic components drawing from Baden-Württemberg and Shandong industrial corridors. Single-source vulnerability concentrates in specialized undercarriage casting capacity. Distribution runs through OEM captive finance arms and independent equipment lessors with regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in emission-compliant repowering services and electric-drive retrofit segments, as regulatory deadlines splinter replacement cycles across fleet vintages and geographies.
For Market Incumbents: Build captive financing moats through telematics-integrated availability guarantees that lock in aftermarket revenue streams. Deepen backward integration into precision hydraulic component production to insulate margin pools from German and Chinese supplier volatility. Counter emerging Chinese entrants in Central Asian mining corridors by anchoring service infrastructure ahead of equipment placement. For New Entrants and Emerging Players: Pursue EU Stage V retrofit certification as a white-space entry point, targeting European quarrying and landfill operators with repowered older machines. Battery-electric underground mining segments in Australia and Poland present the most penetrable niche, with ventilation cost subsidies lowering effective customer acquisition costs. Lead with remote condition monitoring bundled into lease pricing to differentiate from capital-sale incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric-drive development programs, favoring scaled players with captive R&D amortization bases. Target aftermarket service networks with embedded fleet data assets as acquisition profiles, particularly those with Australian or Chilean mining contractor relationships. Watch EPA enforcement variance across US states as the signal for replacement demand timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Integrated Service Contract Expansion | Caterpillar and Komatsu use connectivity hardware to guarantee machine availability and capture aftermarket revenue. |
| Backward Integration into Hydraulic Components | OEMs reduce exposure to German and Chinese valve supplier concentration by developing in-house precision manufacturing. |
| Electric Drive Platform Development | Battery-electric architectures address underground ventilation economics while qualifying for Australian and Polish subsidies. |
| Central Asian Mining Corridor Market Entry | Shantui and LiuGong leverage domestic cost structures to capture volume in Kazakhstan and Uzbekistan copper-gold developments. |
| EU Stage V Repowering Certification | Liebherr anchors European positioning through certified engine-swap services for older machine compliance. |
Research Approach
Desk research of trade customs data, OEM technical documentation, and mining contractor procurement disclosures preceded structured interviews with fleet maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork across Australian iron ore operations, Chilean copper pits, and Chinese western provincial infrastructure sites combined with secondary validation from EPA enforcement records and EU Stage V certification databases. Bottom-up equipment shipment analysis triangulated against top-down mining capital expenditure tracking.
Assumptions held fixed include prevailing emission compliance deadlines and current steel plate input cost trajectories, while electric-drive adoption rates and Central Asian project timelines were varied across sensitivity scenarios. Segmentation modeling spanned product type, technology architecture, application intensity, and end-user procurement structure. CAGRs derived from equipment replacement cycle analysis and fleet age distribution overlays, with underground ventilation economics and infrastructure corridor investment intensity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in mining commodity prices, construction credit availability, or currency volatility in resource-dependent economies would shift the trajectory. Material shifts in EPA enforcement stringency, EU carbon border adjustment scope, or Chinese domestic stimulus targeting would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Cable Winches Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
North America Crane Rental Market