
 Cow Milking Machine Market | 2026-2036
Cow Milking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cow Milking Machine Market Outlook
Distributor networks for dairy equipment are rewriting procurement pathways across European and North American farm supply chains. Fullwood Packo leverages long-standing dealer relationships in the UK and Ireland to sustain replacement part revenue streams. GEA Group Aktiengesellschaft anchors large-parlour installations through direct sales teams serving industrial-scale cooperatives. DeLaval competes on software-integrated herd management, differentiating its robotics with data analytics subscriptions that extend customer lifetime value.
A cow milking machine is an electromechanical system employing vacuum pressure, pulsation cycles, and automated cluster attachment to extract milk hygienically while monitoring yield, conductivity, and udder health parameters. These systems serve commercial dairy operations by reducing labour dependency, enforcing milk quality standards, and generating herd-level performance data for farm management decisions. Robotic milking systems command premium positioning due to capital intensity and software complexity, while bucket milking machines occupy entry-level segments among smallholder cooperatives. Pipeline milking systems dominate mid-scale dairy farms where throughput requirements outpace manual capacity but robotics remain uneconomical.
EMA veterinary medicine guidelines and EU F-Gas Regulation shape equipment specifications for antimicrobial residue control and refrigerant transitions in milk cooling attachments. FDA Grade A Pasteurized Milk Ordinance requirements in the United States enforce sanitary design standards for all equipment contacting raw milk, creating compliance barriers for non-certified imports. Stakeholders must monitor evolving carbon border adjustments and refrigerant phase-down timelines to align product roadmaps with compliance windows.
Market Dynamics
EU F-Gas Regulation phase-downs are compressing refrigerant choices for milk cooling attachments, forcing manufacturers to redesign thermal systems while dairy cooperatives in the Netherlands and Germany accelerate robotic procurement to offset climbing labour costs.
Growth Catalysts
- Herd size expansion:Dairy cooperatives in Denmark and Germany are scaling automated parlour retrofits across medium-scale farms to manage larger cattle populations without proportional labour increases.
- EU F-Gas Regulation:Mandatory refrigerant phase-downs are accelerating demand for low-global-warming-potential cooling systems in milk storage attachments, creating replacement cycles.
- Antimicrobial residue protocols:EMA veterinary medicine guidelines are enforcing stricter equipment sanitation standards, driving upgrade demand for compliant milking clusters and pipeline systems.
Market Restraints
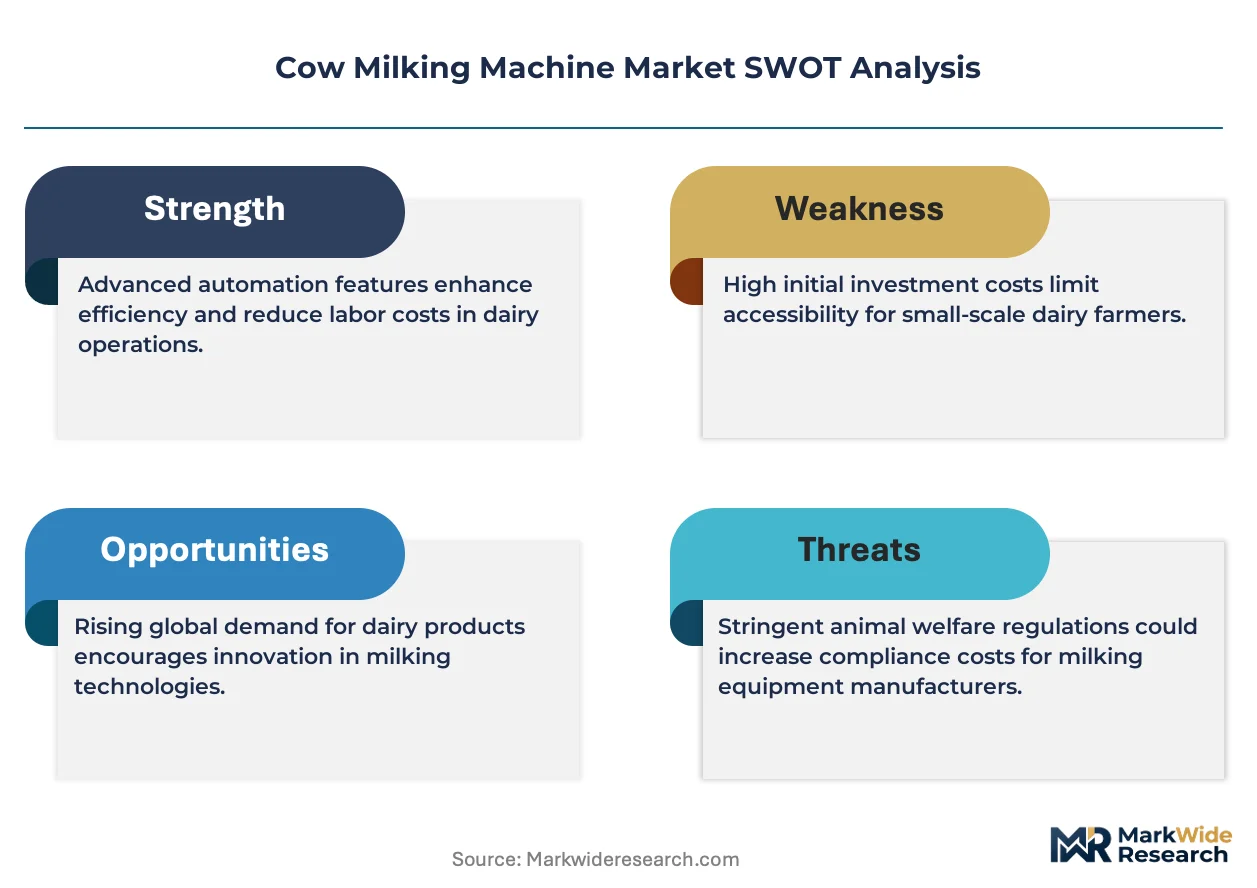
- Stainless steel input volatility:Grade 316L stainless steel price swings compress margin buffers for parlour fabricators dependent on consistent alloy supply.
- Technical limitation:Robotic teat attachment algorithms still fail in suboptimal barn lighting, constraining deployment in older farm infrastructure without LED retrofits.
- Substitution threat:Manual milking persists among smallholder cooperatives in price-sensitive segments where capital intensity of automation remains prohibitive.
Strategic Opportunities
- Data monetization:Herd management software subscriptions bundled with robotic milking systems generate recurring revenue streams extending customer lifetime value.
- Regulatory tailwind:EU Green Deal farm sustainability incentives subsidize energy-efficient milk cooling retrofits in the Netherlands and Denmark.
- Channel innovation:Direct-to-farm service contracts bypass traditional distributor markups, capturing margin in replacement part and maintenance revenue.
Industry Challenges
- Skill scarcity:Veterinary-trained technicians capable of calibrating conductivity sensors and pulsation algorithms command premium wages, constraining service network expansion.
- Integration friction:Retrofitting automated clusters into legacy pipeline milking systems requires custom plumbing adapters, extending installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cow Milking Machine Market |
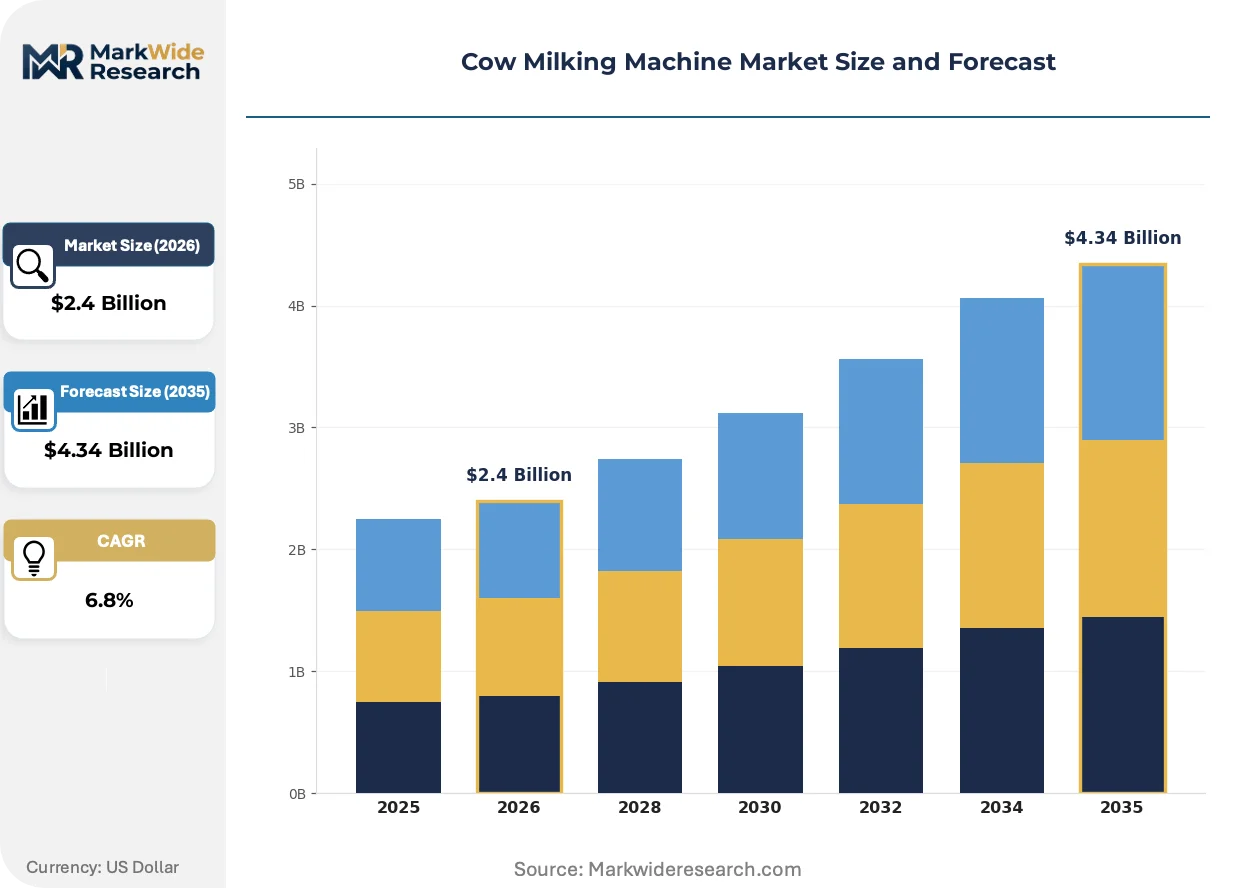
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Milking Machines, Pipeline Milking Systems, Robotic Milking Systems, Portable Milking Machines End User: Dairy Farms, Livestock Farms, Cooperatives, Individual Farmers Technology: Vacuum Technology, Pulsation Technology, Automatic Milking, Digital Monitoring Installation: Fixed Systems, Mobile Systems, Semi-Automatic Systems, Fully Automatic Systems |
| Companies Covered | Fullwood Packo, Agrimac Machinery BV, GEA Group Aktiengesellschaft, Afimilk Ltd., AMS-Galaxy, Lely, BouMatic Robotics B.V., S.A. Christensen & Co., DeLaval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cow Milking Machine Market Strategic Shifts
Vacuum pump electrification and precision sensor miniaturization are compressing energy footprints while expanding real-time udder health monitoring capabilities across commercial dairy operations.
Variable-speed vacuum pumps with brushless DC motors are collapsing energy consumption benchmarks in mid-scale parlour installations. Dairy cooperatives in Denmark are deploying these systems to meet EU Green Deal efficiency targets. The technology is collapsing the operational cost gap between conventional pipeline systems and full robotic automation.
EU F-Gas Regulation mandates are forcing refrigerant transitions in milk cooling attachments from HFCs to natural alternatives. Equipment manufacturers must recertify thermal systems under updated pressure vessel directives. German dairy cooperatives are absorbing these compliance costs through cooperative procurement pools.
Outcome-based service contracts are displacing traditional equipment ownership models among medium-scale farms. DeLaval and GEA Group are piloting milk-yield-guaranteed leasing arrangements in the Netherlands. Danish farm supply chains show the fastest uptake of performance-linked payment structures tied to somatic cell count reductions.
Cow Milking Machine Market Segmentation
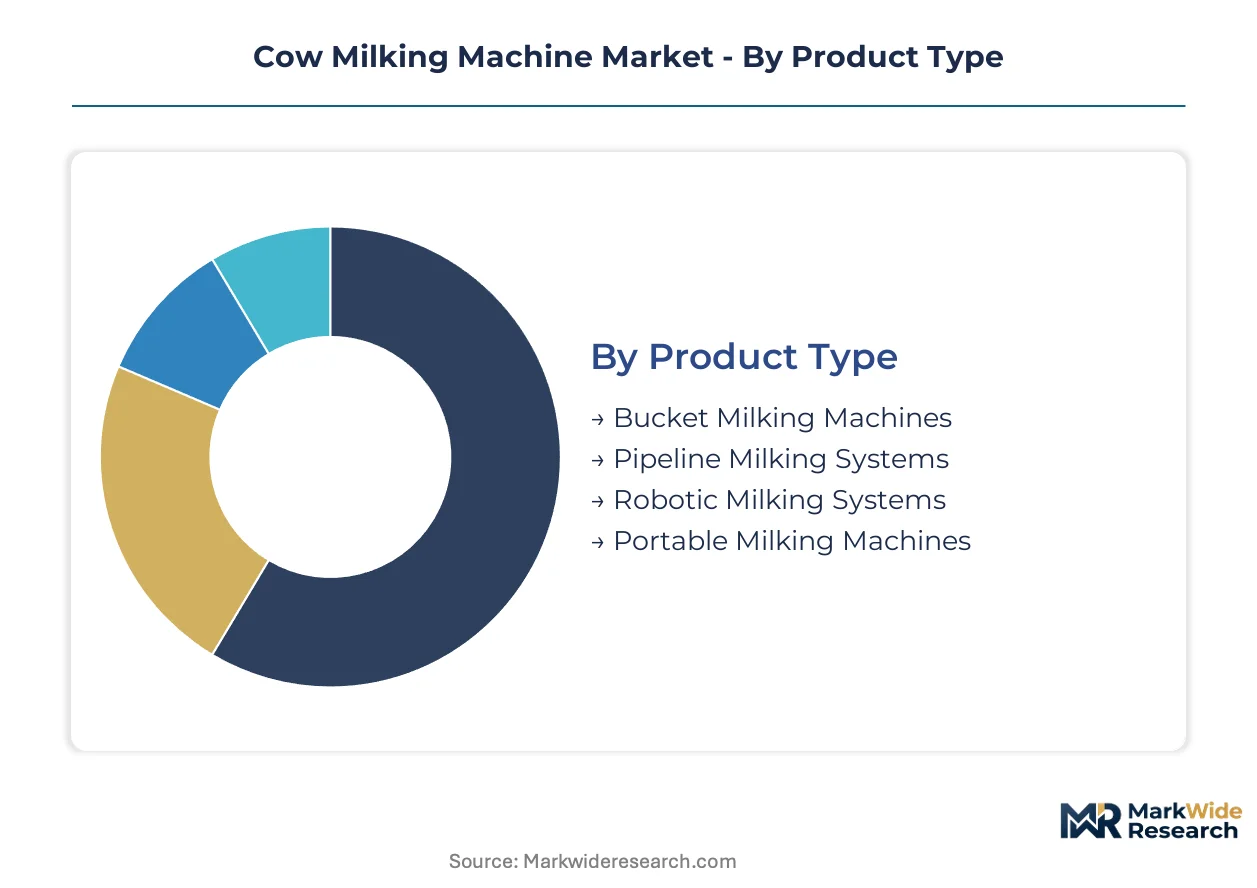
Equipment segmentation in the cow milking machine market reveals distinct capital-labour trade-offs across farm scales. Technology tiers separate price-sensitive smallholders from data-driven cooperatives pursuing herd management automation. Understanding these divides clarifies where replacement cycles concentrate versus where greenfield adoption accelerates.
Product Type:
Mature pipeline systems dominate installed base volumes while robotic platforms emerge as the premium growth corridor.
- Bucket Milking Machines:Entry-level portable units employing single-cow vacuum extraction with manual cluster attachment. Demand concentrates among individual farmers in Eastern European markets where herd sizes remain below 30 head and capital constraints block pipeline investment.
- Pipeline Milking Systems:Fixed stainless steel infrastructure routing milk through sanitary tubing to central cooling tanks, serving as the workhorse technology for mid-scale operations. Dairy cooperatives in Denmark prioritize these systems for parlour retrofits where throughput requirements outpace manual capacity but robotics remain uneconomical.
- Robotic Milking Systems:Autonomous units with computer vision teat identification and yield monitoring software commanding premium positioning.
- Portable Milking Machines:Mobile vacuum units for pasture-based or small-batch extraction scenarios.
Pipeline systems handle the majority of throughput; robotic milking systems are gaining share fastest among cooperatives with expanding herd sizes.
End User:
Customer type segmentation tracks operational scale and procurement sophistication from fragmented smallholders to consolidated cooperatives.
- Dairy Farms:Commercial operations with dedicated milking infrastructure and veterinary protocols, representing the core equipment demand base.
- Livestock Farms:Mixed-use operations where dairy represents secondary revenue, driving demand for versatile portable equipment.
- Cooperatives:Pooled procurement entities in the Netherlands and Germany leveraging collective bargaining for robotic system discounts and maintenance contracts.
- Individual Farmers:Subsistence and semi-commercial operators maintaining manual methods where automation capital intensity proves prohibitive.
Cooperatives deploy the highest equipment density per farm; individual farmers show the steepest expansion trajectory as microfinance instruments spread.
Technology:
Technology layers stack from mechanical vacuum foundations through sensor-enabled digital monitoring, with each tier adding capital cost and data output.
- Vacuum Technology:Core pressure-differential extraction mechanism using 40-50 kPa stable vacuum with airflow regulation. German parlour fabricators are retrofitting variable-speed brushless DC pumps to collapse energy consumption benchmarks and meet EU Green Deal efficiency targets.
- Pulsation Technology:Cyclic liner compression simulating calf suckling rhythm through pneumatic or electronic pulsators. Demand concentrates in automated parlour retrofits across medium-scale Danish farms where precise pulsation ratios reduce teat stress and somatic cell count penalties.
- Automatic Milking:Sensor-triggered cluster attachment and removal without human intervention.
- Digital Monitoring:Cloud-connected yield, conductivity, and udder health telemetry generating herd management datasets.
Vacuum systems underpin the installed base; digital monitoring expands most quickly as data monetization models mature.
Installation:
Installation architecture spans fixed infrastructure investments through mobile flexibility, with automation intensity determining labour substitution economics.
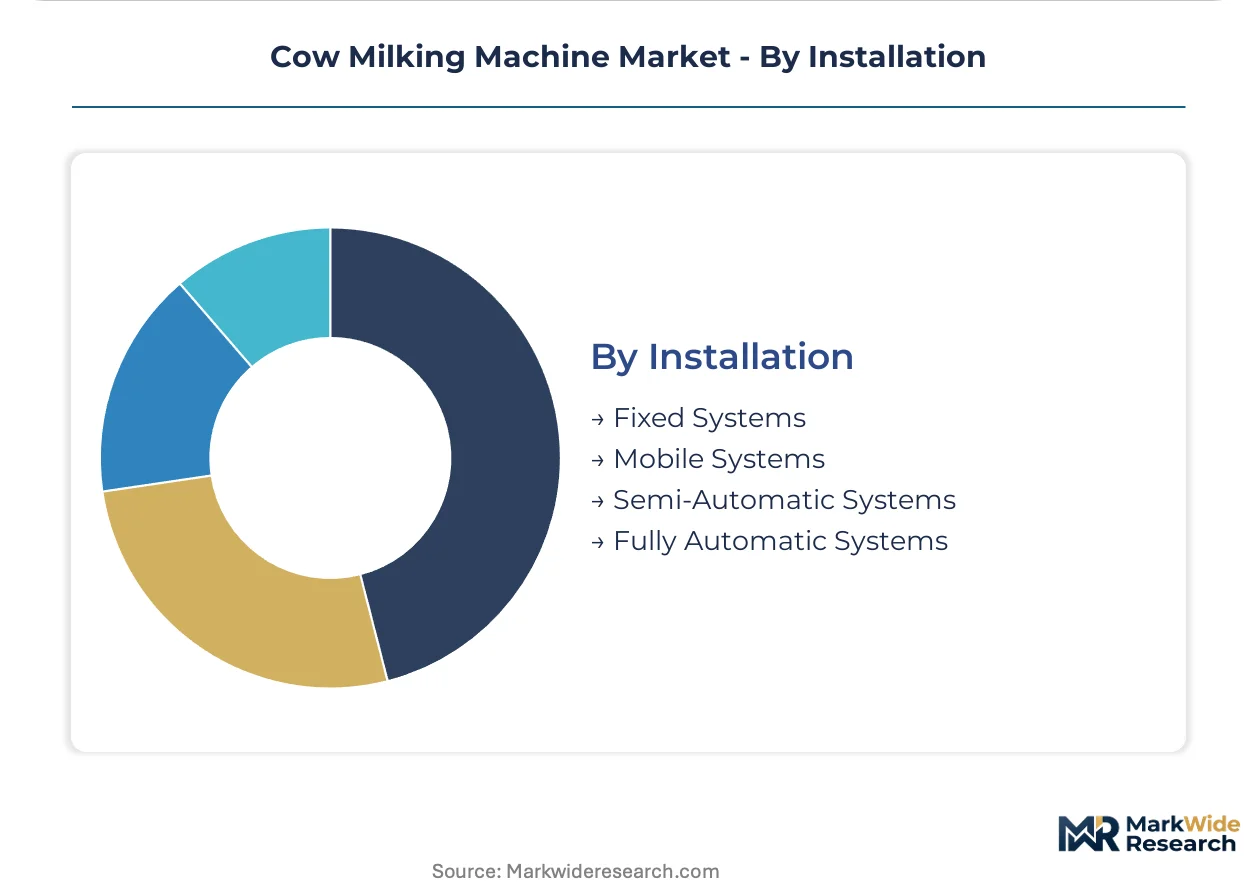
- Fixed Systems:Permanent parlour construction with concrete pits, stainless steel stalls, and embedded vacuum lines. Dairy cooperatives in the Netherlands anchor large-parlour installations through direct procurement channels serving industrial-scale operations.
- Mobile Systems:Trailer-mounted or skid-based equipment relocatable between barns or pastures. Livestock farms in seasonal grazing regions deploy these units to follow herd movements without duplicate infrastructure investment.
- Semi-Automatic Systems:Hybrid configurations requiring manual cluster attachment with automated milk flow monitoring and take-off.
- Fully Automatic Systems:Unattended robotic operation with integrated cleaning cycles and remote diagnostics.
Fixed systems absorb the largest capital deployment; fully automatic configurations are climbing the fastest as labour scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dairy cooperatives command 15-20% pricing premiums over Dutch counterparts for equivalent robotic configurations, reflecting divergent procurement consolidation and subsidy capture rates. This asymmetry compresses margin structures for equipment vendors operating across both markets.
Netherlands
Dairy cooperatives in Friesland and Gelderland are pooling procurement for robotic milking systems to leverage collective bargaining power. EU Green Deal farm sustainability incentives subsidize energy-efficient milk cooling retrofits, accelerating replacement cycles. The Eindhoven-Tilburg corridor hosts precision sensor suppliers feeding component demand for automated cluster attachments.
Germany
Large-parlour installations dominate in Lower Saxony and Bavaria where industrial-scale cooperatives absorb premium automation costs. EMA veterinary medicine guidelines enforce stricter equipment sanitation standards, driving upgrade demand for compliant milking clusters. The Münsterland dairy cluster anchors robotic system deployment through cooperative procurement pools absorbing F-Gas Regulation compliance costs.
Denmark
Medium-scale farms across Jutland prioritize automated parlour retrofits where throughput requirements outpace manual capacity. EU F-Gas Regulation phase-downs accelerate demand for low-global-warming-potential cooling in milk storage attachments. The Herning-Viborg corridor concentrates pipeline system installations serving expanding herd sizes without full robotic capital commitment.
United States
Wisconsin and California dairy operations drive demand for Grade A Pasteurized Milk Ordinance-compliant equipment with sanitary design certifications. FDA enforcement of antimicrobial residue protocols shapes equipment specifications for milk quality monitoring. The Central Valley corridor anchors large-scale parlour installations where labour scarcity intensifies automation urgency.
China
Modern dairy complexes in Inner Mongolia and Heilongjiang are importing European robotic systems for herd management automation. National standards under GB certification frameworks enforce equipment safety and hygiene benchmarks for imported machinery. The Hohhot dairy cluster concentrates automated parlour deployment serving state-backed farm consolidation programs.
Cow Milking Machine Market Competitive Environment
Integrated system architects and component specialists split the market along capital intensity and software complexity vectors. Consolidation pressure concentrates among mid-scale parlour fabricators facing stainless steel input volatility and certification cost escalation. Three archetypes dominate: full-stack robotics vendors bundling hardware-software-service, stainless steel infrastructure fabricators supplying pipeline installations, and precision sensor specialists enabling retrofit digitization. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors secure component supply and service network coverage.
Within the full-stack robotics tier, DeLaval and GEA Group Aktiengesellschaft exemplify integrated platform positioning, while Fullwood Packo occupies a position among UK-Ireland focused infrastructure fabricators leveraging established dealer relationships. Lely and BouMatic Robotics B.V. represent Dutch-origin specialists in autonomous milking configurations. These named entities anchor competitive dynamics without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Fullwood Packo |
| Agrimac Machinery BV |
| GEA Group Aktiengesellschaft |
| Afimilk Ltd. |
| AMS-Galaxy |
| Lely |
| BouMatic Robotics B.V. |
| S.A. Christensen & Co. |
| DeLaval |
| Others |
Value Chain & Pricing Dynamics
The Münsterland dairy cluster anchors European robotic milking system fabrication, where cooperative procurement pools compress supplier margins while concentrated OEM capacity in Lower Saxony sustains premium pricing for configured-to-order installations. Stainless steel input volatility from German mills feeds directly into parlour fabricator quotations, creating asymmetric cost pass-through across standard versus customized equipment tiers.
Pricing Analysis
Configured-to-order robotic installations command 15-20% premiums over standard pipeline configurations, with price differentiation resting on software integration depth and CE-marked sanitary certification tiers. Three-tier pricing structure across premium robotics, standard automated parlours, and economy bucket units stratifies buyer segments. Pricing pressure stems from cooperative procurement consolidation in the Netherlands and Germany, where collective bargaining erodes list-price realization. Individual farmers in Eastern Europe exhibit highest price sensitivity, while Dutch dairy cooperatives absorb premium automation costs through EU Green Deal subsidy capture.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for Danish and German parlour fabricators, easing working capital strain amid stainless steel price volatility. Component sourcing concentrates in Germany, Denmark, and the Netherlands, with precision sensors from the Eindhoven-Tilburg corridor and vacuum pumps from Bavarian motor specialists. Grade 316L stainless steel, electronic pulsator assemblies, and refrigerant cooling units constitute critical input dependencies. Single-source vulnerability sits with brushless DC vacuum motor suppliers, where limited qualified vendors constrain substitution options. Distribution runs through agricultural equipment dealer networks in the UK and Ireland, supplemented by direct sales teams serving industrial-scale cooperatives in continental Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor fragmentation creates acquisition opportunities as stainless steel margin compression and certification cost escalation force mid-scale parlour fabricators toward strategic exits. Herd size expansion across medium-scale Danish and German farms generates demand niches for retrofit specialists and digital monitoring enablers.
For Market Incumbents: Harden software-integrated service revenue streams against emerging sensor-specialist entrants offering retrofit digitization at lower capital thresholds. Deepen backward integration into precision sensor supply through captive relationships with Eindhoven-Tilburg corridor component suppliers. Anchor large-parlour installations through direct procurement channels serving industrial-scale cooperatives, insulating margin from distributor markup compression. For New Entrants and Emerging Players: Establish a beachhead in portable milking machine segments serving livestock farms with seasonal grazing patterns, where incumbent robotics vendors lack tailored offerings. Target microfinance-enabled individual farmers in Eastern Europe through equipment-as-a-service models that bypass capital intensity barriers. Deploy outcome-based leasing arrangements with yield-guaranteed structures to differentiate from traditional equipment ownership models. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative procurement concentration and regulatory compliance cost escalation will structurally favor scaled platform vendors over fragmented fabricators. Acquisition targets should exhibit installed base density in Denmark or the Netherlands with undermonetized aftermarket service potential. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for replacement cycle acceleration in milk cooling attachments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive sourcing from Eindhoven-Tilburg precision component clusters secures margin and delivery reliability. |
| Outcome-Based Service Contract Rollout | Yield-guaranteed leasing in Dutch cooperatives displaces traditional equipment ownership economics. |
| CE-Marked Sanitary Certification Investment | EMA guideline compliance creates enforceable differentiation against non-certified import competition. |
| Cooperative Procurement Pool Participation | Direct engagement with Friesland and Gelderland collectives bypasses distributor markup capture. |
| Variable-Speed Vacuum Pump Platform Launch | Brushless DC electrification meets EU Green Deal efficiency targets while collapsing operational cost gaps. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across dairy farm managers, cooperative procurement officers, veterinary equipment technicians, and parlour installation contractors. Secondary validation drew from EMA veterinary medicine guideline publications, EU F-Gas Regulation implementation documents, SEC filings of listed equipment manufacturers, and agricultural machinery trade association statistics. Bottom-up equipment shipment tallies by product tier were triangulated against top-down dairy herd size expansion data across the Netherlands, Germany, and Denmark.
Calibration against historical replacement cycle timing and regulatory compliance deadline clustering anchored the projection framework. Segmentation dimensions modeled include product type, farm scale tier, technology layer, and regional subsidy eligibility pattern. CAGRs were derived from equipment penetration rate trajectories correlated with labour cost indices and herd consolidation trends. Forecast inputs incorporated EU Green Deal incentive allocation schedules and F-Gas refrigerant phase-down enforcement pathways.
Sensitivities concentrate around stainless steel alloy price volatility, cooperative procurement consolidation pace, and robotic teat attachment algorithm reliability improvements. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and subsidy continuation. Macroeconomic contraction affecting farm credit availability, accelerated refrigerant regulation timelines, or breakthroughs in computer vision accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market