
 Garden and Orchard Tractors Market | 2026-2036
Garden and Orchard Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Garden and Orchard Tractors Market Foresight
China's expanding tractor manufacturing footprint is reshaping competitive dynamics in compact and utility tractor categories. John Deere leverages its vertically integrated supply chain to dominate premium specialty tractor sales in North American horticulture. Kubota Corporation anchors its position through R&D intensity focused on sub-compact diesel platforms for Japanese and Southeast Asian vineyard applications. Mahindra & Mahindra competes aggressively on manufacturing scale, exporting cost-optimized utility tractors to African and Latin American small-scale farming segments.
Garden and orchard tractors are self-propelled agricultural machines typically ranging from 15 to 75 horsepower, designed for narrow-row cultivation, mowing, tilling, and material handling in confined spaces where full-size farm equipment cannot operate. Compact tractors with hydrostatic transmissions and three-point hitch systems serve as the primary workhorse for vineyard inter-row maintenance and nursery bed preparation. Diesel-powered units still occupy the largest revenue share among fuel types, though electric variants are capturing margin pools in European landscaping fleets driven by municipal noise ordinances and urban emissions zones. Specialty tractors configured for ultra-narrow vineyard rows represent the fastest-growing product category as global wine producers mechanize labor-intensive canopy management tasks.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by national type-approval authorities are tightening particulate matter and NOx limits, compelling engine downsizing and after-treatment adoption across diesel tractor lineups. China's MIIT implements domestic emission benchmarks that increasingly align with European protocols, affecting export-oriented manufacturers supplying Asian markets. ISO 3776 and OECD tractor safety codes establish rollover protection and braking performance baselines that influence product design costs and market access timelines. Stakeholders must monitor battery energy density improvements and charging infrastructure build-outs to assess when electric platforms achieve total-cost parity against diesel in high-utilization orchard operations.
Market Dynamics
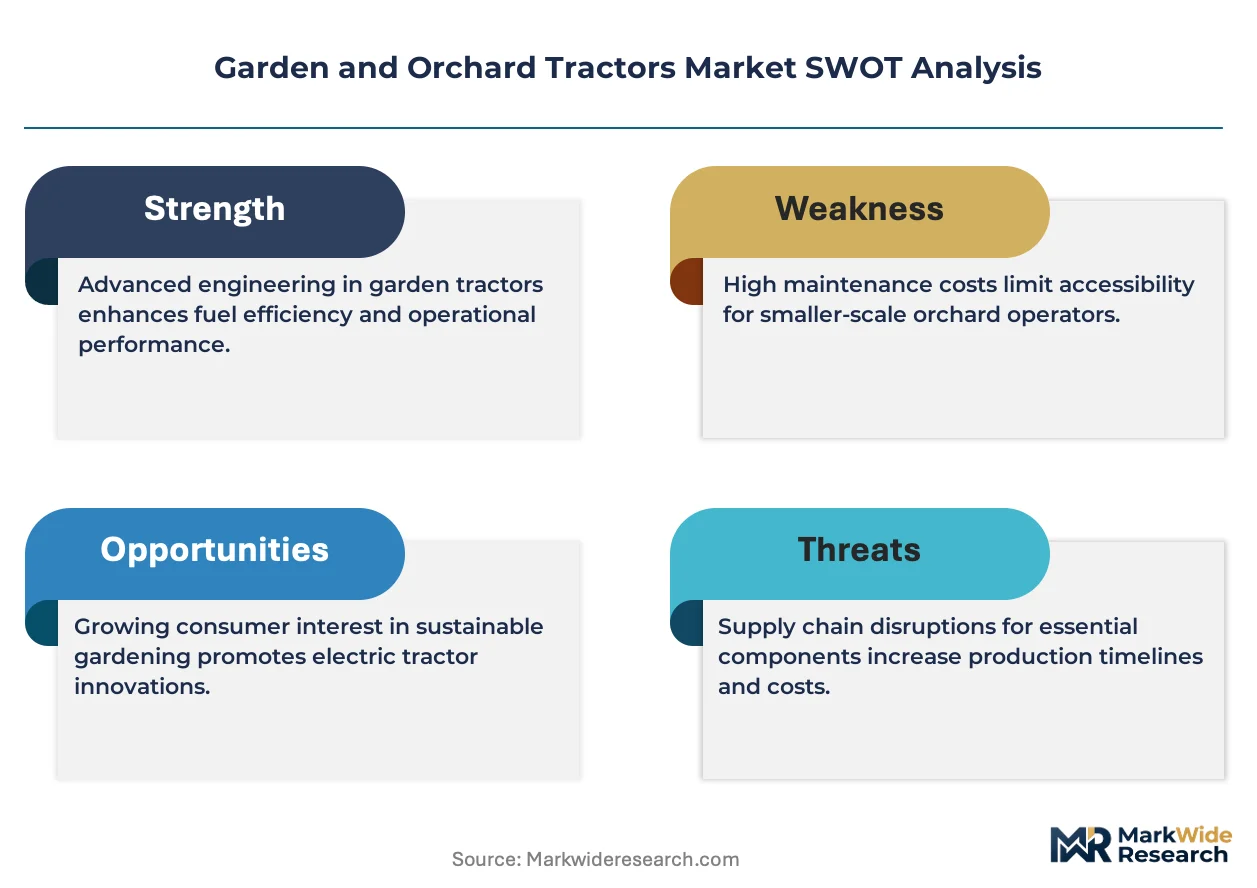
EPA Tier 4 Final and EU Stage V emissions standards are compressing diesel powertrain economics while battery energy density improvements accelerate electric platform viability for high-utilization orchard operations.
Growth Catalysts
- Narrow-row vineyard mechanization:Wine producers in Germany's Rhine Valley and California's Central Valley are replacing manual canopy management with specialty tractors configured for ultra-narrow inter-row spacing.
- EU Stage V compliance:National type-approval authorities across Europe are enforcing stricter particulate matter limits, compelling fleet operators to retire pre-Stage V equipment ahead of natural replacement cycles.
- Municipal landscaping electrification:Urban emissions zones and noise ordinances in European cities are mandating zero-emission equipment for municipal grounds maintenance contracts.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems required by EPA Tier 4 Final are adding material cost burdens to sub-50 horsepower platforms where price elasticity is highest.
- Battery supply concentration:Lithium-ion cell production for electric tractor powertrains remains concentrated in East Asian manufacturing hubs, exposing European and North American assemblers to raw material volatility and logistics bottlenecks.
- Charging infrastructure gaps:Rural orchard and vineyard operations lack the three-phase electrical capacity and fast-charging hardware needed to support continuous-duty electric fleet deployment.
Strategic Opportunities
- Precision agriculture integration:RTK-GPS guidance systems and variable-rate application controllers are converging with compact tractor platforms to enable autonomous inter-row spraying and mowing.
- Indian small-farm mechanization:Cost-optimized utility tractors below 25 horsepower face underpenetrated demand among India's fragmented horticulture holdings where manual labor availability is contracting.
- US Inflation Reduction Act credits:Clean vehicle and alternative fuel infrastructure tax incentives are improving total-cost-of-ownership calculations for electric tractor adopters in California nut-growing regions.
Industry Challenges
- Mechatronics skill scarcity:Dealer service networks lack technicians trained in high-voltage battery systems and power electronics diagnostics required for electric tractor maintenance.
- ISO 3776 compliance timelines:Rollover protection structure redesign and braking performance validation are extending product development cycles for new platform introductions.
- Legacy fleet interoperability:Proprietary CAN bus protocols and implement control architectures are complicating precision agriculture retrofits on installed bases of mechanically governed diesel units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden and Orchard Tractors Market |
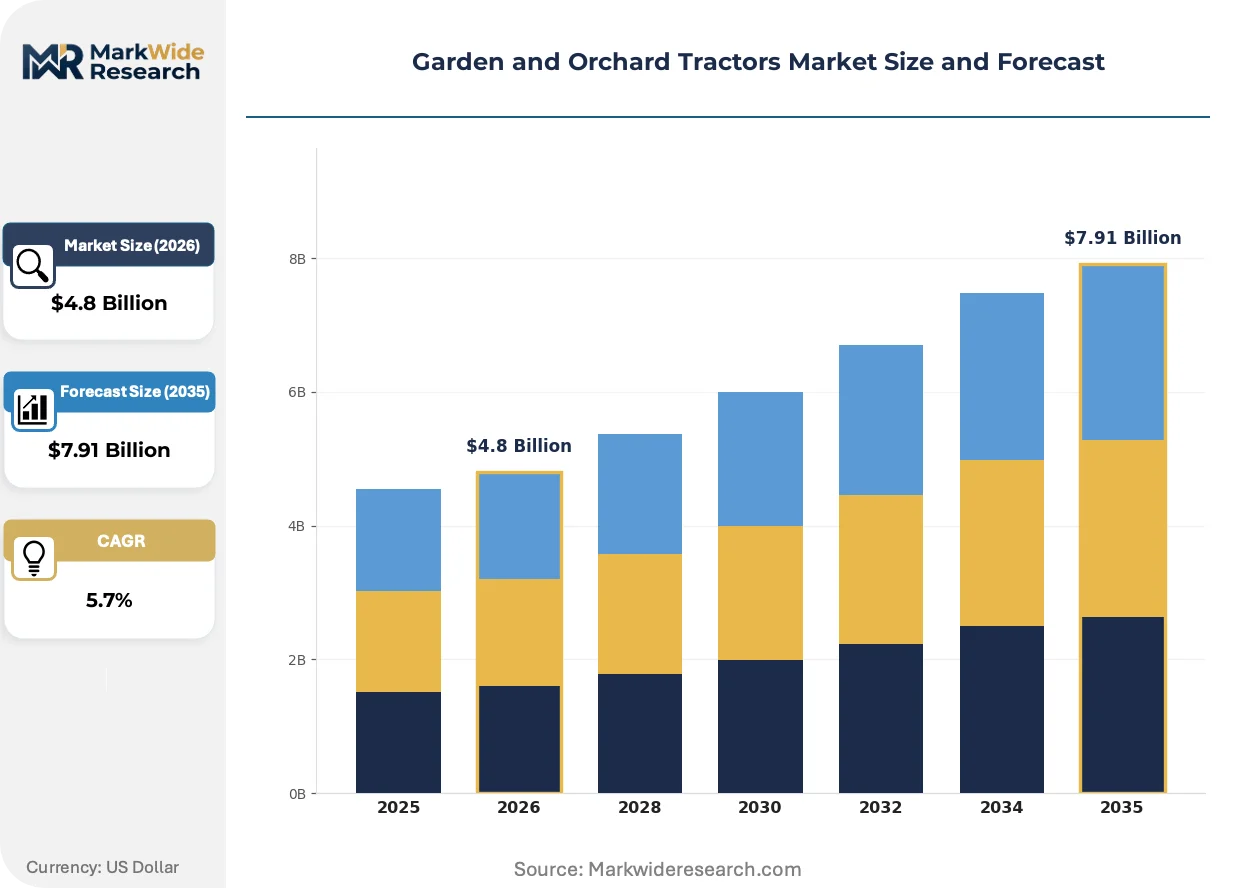
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Sub-Compact Tractors, Utility Tractors, Specialty Tractors, Lawn Tractors Fuel Type: Diesel, Gasoline, Electric, Propane, Biodiesel Application: Horticulture, Viticulture, Landscaping, Grounds Maintenance, Small-Scale Farming End User: Nursery Operators, Vineyards, Landscaping Companies, Estate Managers, Private Garden Owners |
| Companies Covered | John Deere, CNH Industrial, Kubota Corporation, AGCO Corporation, Mahindra & Mahindra, Claas KGaA, Yanmar Co., Ltd., Deutz-Fahr, Husqvarna AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden and Orchard Tractors Market Shifts & Advancements
Telematics-enabled fleet management and autonomous guidance systems are digitizing operator workflows in confined-space horticulture, while regulatory pressure on emissions and safety standards accelerates hardware refresh cycles.
Telematics platforms integrating engine diagnostics, geofencing, and maintenance scheduling are digitizing fleet oversight for nursery and vineyard operators. Large California nut growers are deploying these systems across 50-plus unit fleets to optimize utilization rates and preempt downtime. The technology is digitizing traditional asset management by replacing paper logbooks and reactive service models with predictive analytics.
EU Stage V emission standards enforced by Germany's KBA and France's CNIL-equivalent type-approval bodies are mandating diesel particulate filter regeneration protocols and onboard diagnostics. Engine manufacturers are downsizing displacement and adding after-treatment hardware, compressing power density in compact tractor classes. Specialty vineyard configurations in France's Champagne region and Italy's Piedmont are absorbing compliance costs through premium pricing.
Equipment-as-a-service contracting is displacing outright purchase for municipal landscaping fleets facing capital budget constraints. European cities including Amsterdam and Copenhagen are procuring electric tractors through multi-year service agreements bundling maintenance and battery replacement. The model is most visible in urban emissions zones where operating cost predictability outweighs ownership economics for seasonal utilization patterns.
Garden and Orchard Tractors Market Segmentation
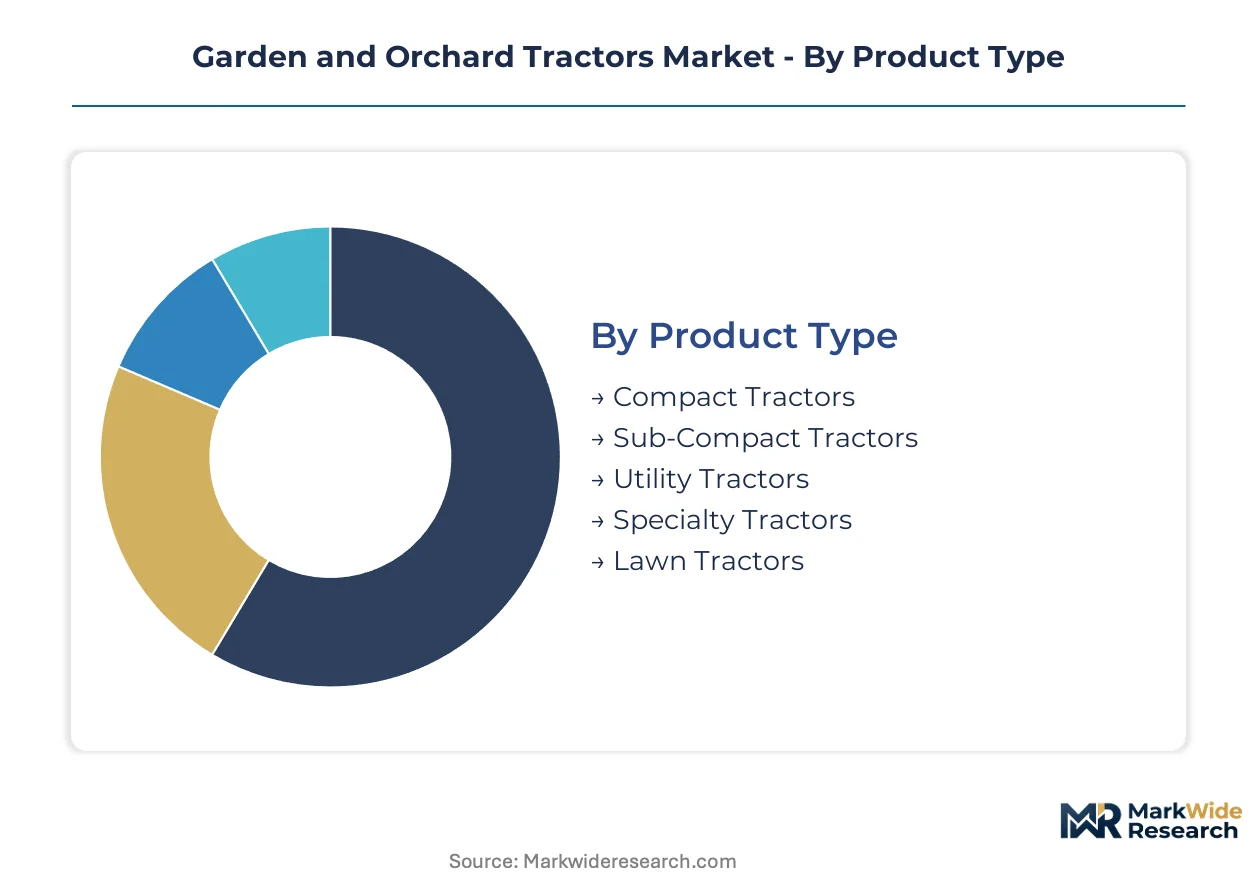
Garden and orchard tractor procurement decisions hinge on inter-row clearance dimensions, duty-cycle intensity, and fuel infrastructure availability at the point of use. Segmentation reveals how equipment specifications diverge across vineyard slope gradients, nursery bed configurations, and municipal contract terms.
Product Type:
Equipment scale spans from estate lawn maintenance to commercial orchard mechanization, with horsepower ratings and three-point hitch capacity determining implement compatibility.
- Compact Tractors:Units rated 20-45 horsepower with hydrostatic transmissions dominate vineyard inter-row spraying and nursery bed preparation. California Central Valley nut growers and Germany's Rhine Valley wine producers standardize procurement on this class for canopy management tasks.
- Specialty Tractors:Ultra-narrow configurations with offset seating and reduced overall width address steep-slope viticulture and high-density planting systems. French Champagne houses and Italian Piedmont estates absorb premium pricing for Stage V-compliant platforms with precision guidance integration.
- Sub-Compact Tractors:Below-20-horsepower platforms serve hobby farms and estate grounds with limited implement requirements.
- Utility Tractors:45-75 horsepower range supports material handling and heavy tillage in diversified small-scale operations.
- Lawn Tractors:Light-duty mowing platforms for residential and estate turf maintenance with minimal PTO demands.
The dominant share belongs to Compact Tractors, while Specialty Tractors are closing the gap fastest.
Fuel Type:
Powertrain economics diverge sharply between high-utilization commercial operations and seasonal municipal fleets, with regulatory pressure reshaping total-cost calculations.
- Diesel:Compression-ignition engines with particulate filter after-treatment retain torque density advantages for continuous-duty tillage and material handling. EPA Tier 4 Final compliance costs compress margins on sub-50-horsepower platforms where Indian and Chinese manufacturers compete aggressively.
- Electric:Battery-electric platforms with lithium-ion packs and onboard chargers capture municipal landscaping contracts in Amsterdam and Copenhagen emissions zones. Noise ordinances and operating-cost predictability offset capital premiums for seasonal utilization patterns.
- Gasoline:Spark-ignition engines dominate residential and light commercial segments with lower first-cost barriers.
- Propane:LPG conversions address indoor warehouse and greenhouse applications where exhaust emissions are constrained.
- Biodiesel:B20-B100 compatible engines serve sustainability-mandated institutional fleets and organic-certified operations.
Diesel retains the largest installed base, though Electric platforms are expanding most quickly in urban contract segments.
Application:
Operational environments dictate traction requirements, implement interfaces, and operator protection specifications across terrain and crop architectures.
- Viticulture:Narrow-row canopy management and steep-slope operations demand specialized stability systems and precision guidance. Mechanization penetration in Germany, France, and Italy drives replacement cycles as labor availability contracts.
- Horticulture:Nursery bed preparation, container handling, and greenhouse logistics require compact turning radii and PTO versatility. North American propagation operations invest in telematics-enabled fleet management for asset utilization optimization.
- Landscaping:Municipal and commercial grounds maintenance contracts specify emissions compliance and noise thresholds for urban deployment.
- Grounds Maintenance:Estate, institutional, and recreational turf management prioritizes operator comfort and seasonal reliability.
- Small-Scale Farming:Diversified holdings combine tillage, mowing, and material handling in single-platform procurement decisions.
Viticulture commands premium pricing per unit, while Horticulture generates the steepest volume expansion trajectory.
End User:
Procurement authority and capital access separate commercial fleet operators from residential purchasers, with financing structures and service dependencies varying accordingly.
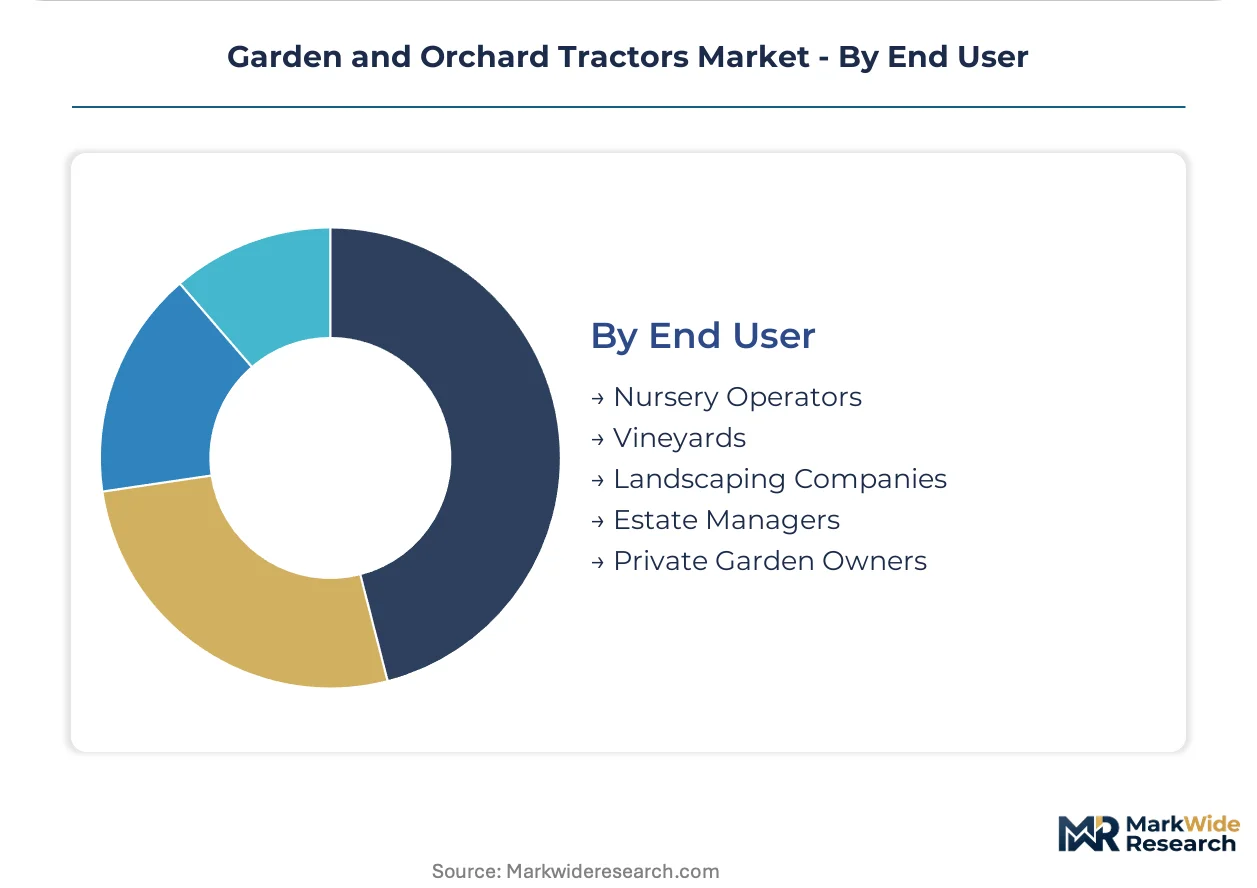
- Vineyards:Wine producers from California to Champagne deploy 50-plus unit fleets with equipment-as-a-service contracting and predictive maintenance protocols. Telematics integration enables utilization rate benchmarking across multiple sites.
- Nursery Operators:Container and field propagation specialists in the Netherlands and Pacific Northwest standardize on compact diesel platforms with three-point hitch versatility for bed preparation and irrigation installation.
- Landscaping Companies:Municipal and commercial contractors face emissions zone compliance and seasonal cash flow constraints favoring lease structures.
- Estate Managers:Institutional and private property oversight combines aesthetic requirements with operational reliability demands.
- Private Garden Owners:Residential purchasers prioritize dealer proximity and financing accessibility over specification optimization.
Vineyards absorb the highest equipment value per hectare, while Landscaping Companies are gaining procurement volume fastest through municipal electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses and Japanese precision manufacturers anchor the supply base for compact powertrain systems, while vineyard mechanization clusters in Western Europe and California drive specification refinement.
United States
California's Central Valley nut growers and Washington's Yakima Valley orchardists deploy 50-plus unit fleets with telematics integration. EPA Tier 4 Final compliance costs compress margins on sub-50-horsepower platforms where price elasticity is highest. The San Joaquin Valley corridor concentrates replacement demand as labor availability contracts.
Germany
Rhine Valley wine producers mechanize canopy management tasks with ultra-narrow specialty configurations. KBA type-approval authorities enforce EU Stage V diesel particulate filter protocols that extend product validation timelines. Baden-Württemberg's precision engineering cluster supplies hydrostatic transmission systems to domestic assemblers.
France
Champagne houses and Burgundy estates absorb premium pricing for Stage V-compliant vineyard tractors with precision guidance integration. ANSM-equivalent national regulators coordinate with EU type-approval frameworks for agricultural machinery safety codes. The Grand Est region drives replacement cycles as steep-slope viticulture mechanization accelerates.
Italy
Piedmont and Tuscany wine producers standardize procurement on narrow-row configurations for high-density planting systems. National agricultural machinery associations align domestic certification with OECD tractor safety standards. The Emilia-Romagna manufacturing belt produces compact transmission components for European OEM supply chains.
China
MIIT emission benchmarks increasingly align with European protocols, affecting export-oriented manufacturers supplying Asian horticulture markets. Yangtze River Delta fabrication clusters produce cost-optimized utility platforms for Southeast Asian vineyard applications. Domestic nursery operators in Shandong Province expand mechanized bed preparation equipment procurement.
Garden and Orchard Tractors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying transmissions, axles, and after-treatment hardware. The vendor base stratifies across three tiers: diversified agricultural machinery conglomerates with captive engine production, compact tractor specialists focused on sub-75-horsepower segments, and contract assemblers serving private-label distributors. Capacity expansion in Indian and Chinese manufacturing hubs and strategic partnerships for electric powertrain development represent the dominant competitive vectors reshaping positioning.
Among diversified machinery conglomerates, John Deere and CNH Industrial exemplify platform integrators with vertically controlled supply chains. Kubota Corporation anchors the compact-specialist archetype through concentrated R&D allocation to sub-compact diesel architectures. These three entities occupy positions that reflect divergent geographic emphases and powertrain technology bets across diesel compliance and electrification pathways.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| Kubota Corporation |
| AGCO Corporation |
| Mahindra & Mahindra |
| Claas KGaA |
| Yanmar Co., Ltd. |
| Deutz-Fahr |
| Husqvarna AB |
| Others |
Supply & Pricing Matrix
East Asian lithium-ion cell manufacturing concentration funnels battery cost volatility directly into European and North American electric tractor assemblers, compressing margin pools at the OEM tier while channel partners capture service-attach premiums. This upstream feedstock chokepoint amplifies pricing power asymmetries between battery suppliers and platform integrators.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across diesel-powered compact and utility tractor lineups, with after-treatment hardware costs forcing three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with Stage V-compliant specialty vineyard configurations commanding premiums in French and German markets. Cost compression in sub-50-horsepower diesel platforms is intensifying because Indian and Chinese manufacturers compete aggressively on manufacturing scale. Small-scale farming segments in Africa and Latin America exhibit highest price sensitivity, while California nut growers and Champagne houses demonstrate lowest sensitivity due to labor substitution economics.
Supply Chain Analysis
High-grade steel forgings and precision-machined transmission housings draw from German, Japanese, and Italian metalworking clusters, with hydrostatic transmission systems anchored in Baden-Württemberg's engineering belt. Lithium-ion cell production, rare-earth permanent magnets for electric motors, and semiconductor power modules constitute critical component dependencies. Single-source vulnerability concentrates in East Asian battery cell manufacturing, exposing European assemblers to raw material volatility and logistics bottlenecks. Distribution runs through authorized dealer networks with captive parts warehousing, though equipment-as-a-service contracting is displacing traditional wholesale channels for municipal landscaping fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance contracts and battery replacement service agreements are expanding faster than hardware unit sales, repositioning garden and orchard tractor markets as recurring-revenue platforms. This service-attach layer captures margin pools that hardware commoditization erodes.
For Market Incumbents: Pre-empt Chinese cost-optimized utility tractor exports by backward integration into compact transmission production in India and Southeast Asian manufacturing hubs. Defend dealer network exclusivity through high-voltage technician certification programs that emerging entrants cannot replicate quickly. Anchor position with R&D allocation to RTK-GPS guidance and autonomous inter-row spraying systems before precision agriculture retrofits commoditize. For New Entrants and Emerging Players: India's fragmented horticulture holdings below 25 horsepower represent the most penetrable white-space target, where manual labor contraction outpaces incumbent distribution reach. Target municipal electrification mandates in Amsterdam, Copenhagen, and California emissions zones with battery-electric platforms bundled with charging infrastructure partnerships. Pursue equipment-as-a-service contracting to bypass capital budget constraints that block outright purchase decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compact tractor specialists lacking electric powertrain development programs. Five-to-ten-year viability hinges on battery energy density improvements achieving total-cost parity against diesel in high-utilization orchard operations. Acquisition targets should demonstrate installed telematics penetration above threshold levels or captive dealership density in California and Rhine Valley clusters. Monitor quarterly cell chemistry cost curves and three-phase rural grid expansion timelines as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Development | Battery energy density improvements enable zero-emission vineyard configurations compliant with Amsterdam and Copenhagen municipal mandates. |
| Telematics Fleet Management Integration | RTK-GPS guidance and predictive maintenance protocols optimize utilization rates for California Central Valley nut growers operating 50-plus unit fleets. |
| Backward Integration into Transmission Manufacturing | Captive hydrostatic transmission production in Baden-Württemberg engineering clusters defends margin position against Chinese cost competition. |
| Equipment-as-a-Service Contracting Model | Multi-year service agreements bundling maintenance and battery replacement address municipal capital budget constraints in European emissions zones. |
| High-Voltage Technician Certification Programs | Dealer network capability in battery systems and power electronics diagnostics creates service-attach stickiness that emerging entrants cannot replicate. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across vineyard operations, nursery management, municipal procurement offices, and compact tractor manufacturing. Primary interviews captured input from fleet managers at California nut-growing cooperatives, Rhine Valley wine producers, Dutch propagation specialists, and German KBA type-approval authorities. Secondary validation drew from EPA Tier 4 Final filings, EU Stage V homologation databases, OECD tractor safety code documentation, and customs records tracking utility tractor trade flows. Bottom-up unit economics triangulated against top-down regional demand aggregation.
Calibration anchored volume and value outputs to observed replacement cycles in Germany's Rhine Valley orchard belt and California's Central Valley nut-growing regions. Segmentation dimensions modeled span product type, fuel architecture, application environment, and end-user procurement authority. CAGRs derived from regression analysis against historical fleet expansion rates, labor availability indices, and regulatory compliance timelines. Industry-specific inputs included battery energy density improvement curves and three-phase rural electrical capacity build-out projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese cost-optimized manufacturers or rapid charging infrastructure deployment by European utilities would shift outcomes. Quarterly review of cell chemistry cost curves, dealer technician certification completion rates, and municipal electrification contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Rice Mill Machine Market