
 Compact Tractor Market | 2026-2036
Compact Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Tractor Market Analytics
Landscaping companies is shifting toward higher-horsepower compact tractors as commercial grounds maintenance contracts expand across suburban corridors. John Deere leverages its dealer network density to anchor Midwest and Southeast demand. Kubota sustains Japanese engineering credibility while competing aggressively on hydrostatic transmission refinement. Mahindra specializes in price-accessible utility configurations that occupy entry-level segments in price-sensitive rural markets.
A compact tractor denotes a powered agricultural or grounds-keeping vehicle typically ranging from 15 to 60 horsepower, designed for maneuverability on small-to-medium acreage where full-size equipment proves impractical; these machines integrate three-point hitch systems and power take-off shafts to operate mowers, tillers, loaders, and backhoe attachments across property maintenance, light tillage, and material handling tasks. The 25-50 HP power rating band leads unit volume as it balances capability with fuel efficiency for mixed-use owners. Hydrostatic transmission configurations capture margin pools from homeowners and landscaping companies prioritizing operator ease over mechanical simplicity. Sub-compact models face pressure from powered lawn equipment below and compact models above, squeezing their structural position in the product hierarchy.
EPA Tier 4 Final standards and the European Stage V framework compel engine redesigns that add cost but also create technology leadership openings for compliant manufacturers. OSHA agricultural safety directives and ISO 5704 power take-off guarding standards shape product liability exposure and export market access requirements. Stakeholders must monitor electrification feasibility against diesel infrastructure persistence and decide whether battery platform investments align with rural charging limitations.
Market Dynamics
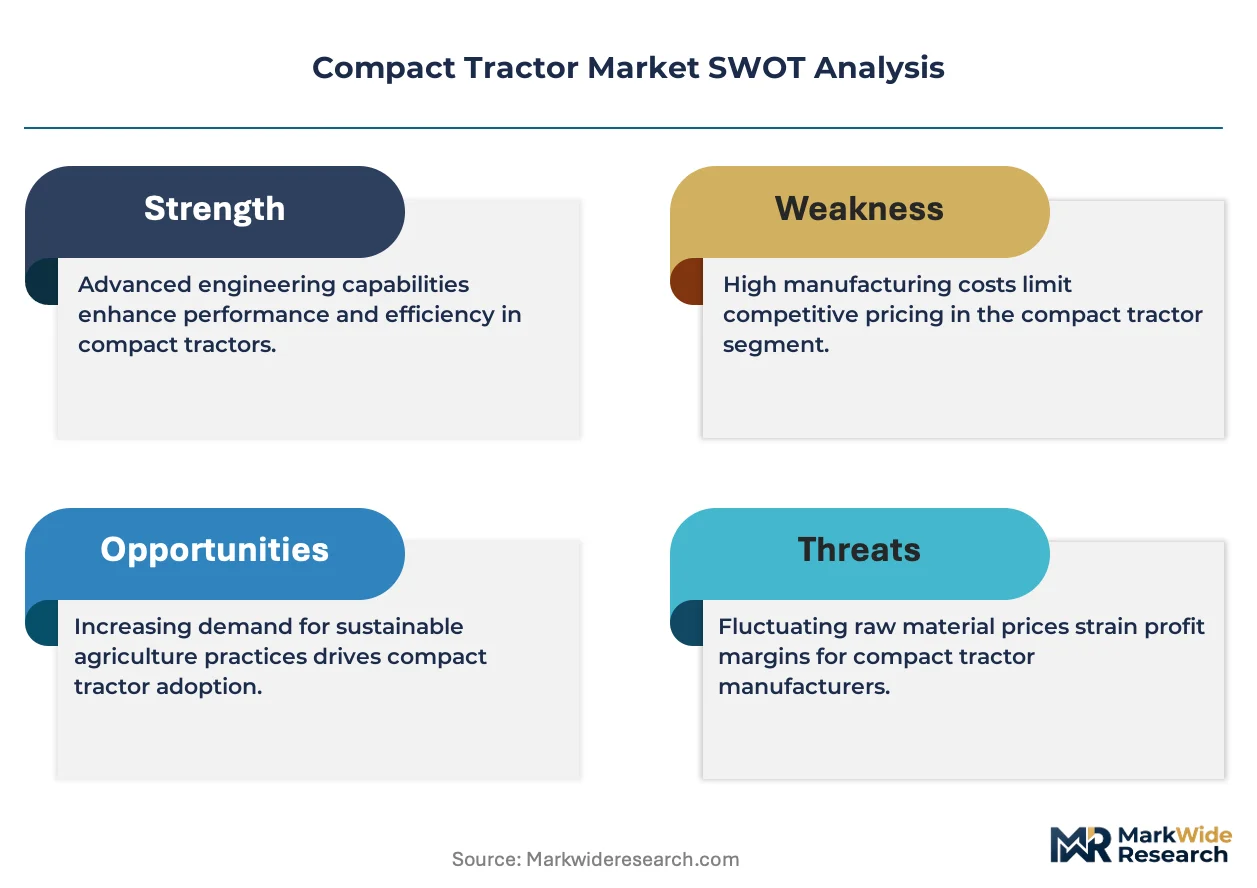
EPA Tier 4 Final emissions standards and European Stage V regulations are forcing engine architecture redesigns across the compact tractor supply base, compressing margins for non-compliant manufacturers while creating technology leadership openings for early adopters of cleaner diesel and electrified powertrains.
Growth Catalysts
- Commercial Landscaping Contracts:Municipal and corporate grounds maintenance agreements are expanding across suburban corridors, pulling fleet purchases toward higher-horsepower compact equipment capable of sustained daily operation.
- EPA Tier 4 Final Compliance:Emissions mandates in the United States are accelerating R&D investment in after-treatment systems and alternative fuels, rewarding manufacturers with certified engine platforms.
- Hobby Farm Proliferation:Rural property owners in the United States Midwest are acquiring 10-50 acre parcels, generating replacement demand for maneuverable equipment between lawn tractors and full-scale agricultural machinery.
Market Restraints
- Emissions Hardware Cost Burden:Diesel particulate filters and selective catalytic reduction systems add $3,000-$5,000 to unit production costs, pressuring entry-level price points.
- Battery Energy Density Limitations:Current lithium-ion chemistries deliver insufficient runtime for all-day agricultural tasks, constraining electrification to sub-compact and intermittent-use applications.
- Steel and Aluminum Input Volatility:Chassis and implement fabrication depends on commodity metals subject to tariff and supply disruptions, compressing gross margins unpredictably.
Strategic Opportunities
- Telematics-Enabled Fleet Management:GPS tracking and usage analytics allow landscaping contractors to optimize equipment utilization and schedule predictive maintenance, creating recurring software revenue streams.
- India Rural Mechanization:Government subsidy programs for smallholder farm equipment present volume opportunities for cost-optimized utility configurations below 35 horsepower.
- Brazil Agroforestry Expansion:Coffee and fruit orchard operations require narrow-profile compact tractors for inter-row cultivation, opening specialized chassis design segments.
Industry Challenges
- Diesel Technician Shortage:High-pressure common rail and emissions after-treatment systems demand specialized diagnostic capabilities that rural dealer networks struggle to staff.
- Electrification Infrastructure Mismatch:Rural property electrical service limitations and absence of fast-charging networks constrain battery-electric tractor deployment despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Tractor Market |
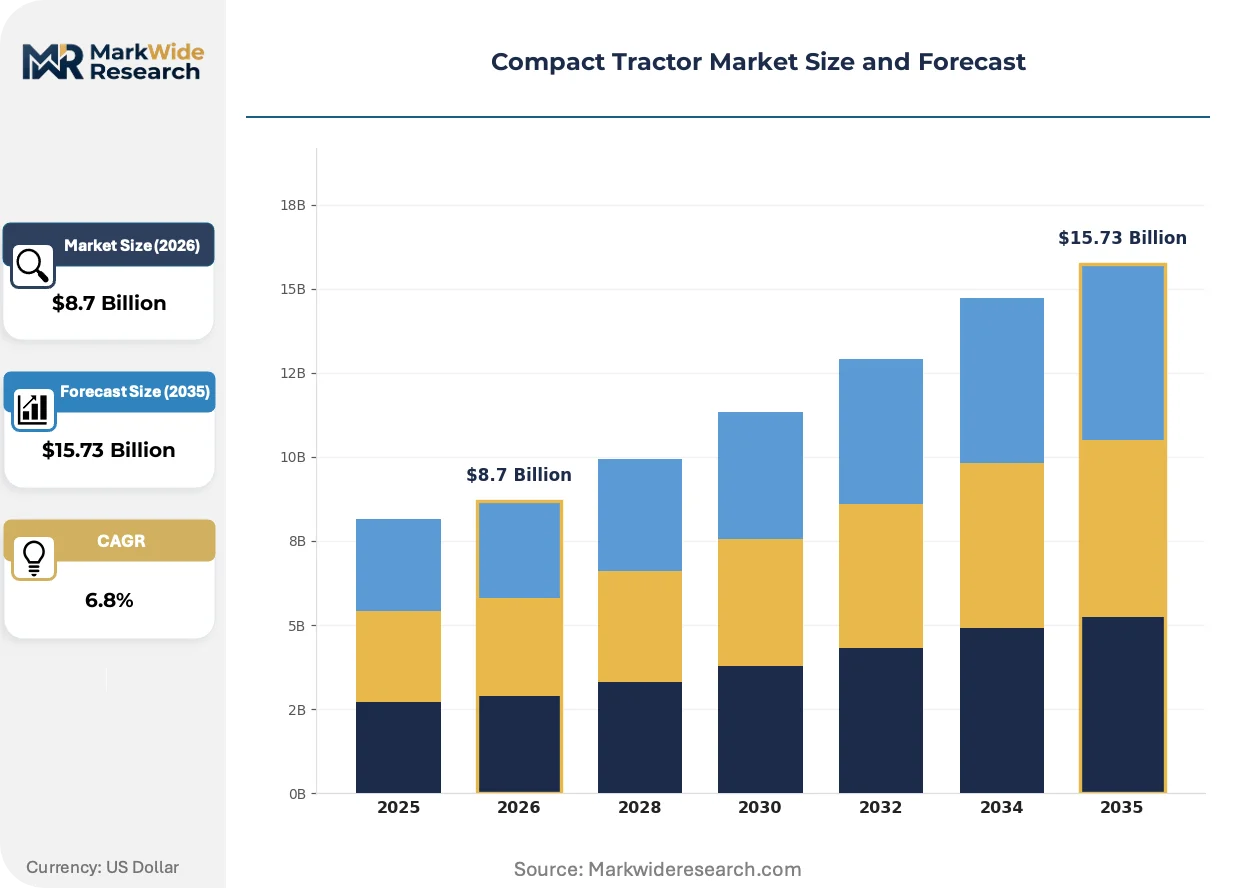
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sub-Compact, Compact, Utility, Garden End User: Agricultural Sector, Landscaping Companies, Municipalities, Homeowners Power Rating: Less than 25 HP, 25-50 HP, 51-75 HP, 76-100 HP Transmission Type: Manual, Hydrostatic, Power Shuttle, Gear Drive |
| Companies Covered | New Holland, Case IH, John Deere, Massey Ferguson, KIOTI, Kubota, Yanmar, TYM, Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Tractor Market Evolving Landscape
Powertrain electrification, precision agriculture integration, and autonomous operation capabilities are converging to redefine equipment value propositions, shifting buyer evaluation criteria from horsepower ratings to total cost of ownership and connectivity-enabled productivity metrics.
Hydrostatic transmission configurations are overtaking gear-driven alternatives in the 25-50 horsepower segment as landscaping contractors and hobby farm owners prioritize operator ease and reduced training requirements over mechanical efficiency. Fleet buyers specify hydrostatic units for reduced operator fatigue during repetitive tasks. This shift is compressing demand for manual transmission expertise in dealer service departments while expanding margin pools for integrated drive system suppliers.
European Stage V emissions frameworks are compelling engine downsizing and turbocharging strategies that maintain power density while reducing particulate output. Manufacturers are responding with compacted graphite iron blocks and variable geometry turbochargers. The 40-60 horsepower utility segment faces the steepest compliance cost escalation, accelerating consolidation among independent engine suppliers unable to amortize certification investments.
Equipment-as-a-service contracting models are displacing traditional capital purchase arrangements among mid-size landscaping operations seeking to convert fixed asset burdens into variable operating expenses. Subscription pricing bundles maintenance, telematics, and seasonal attachment swaps. This transformation is most visible in the United States Southeast, where private equity-backed grounds maintenance rollups prioritize balance sheet flexibility over equipment ownership.
Compact Tractor Market Segmentation
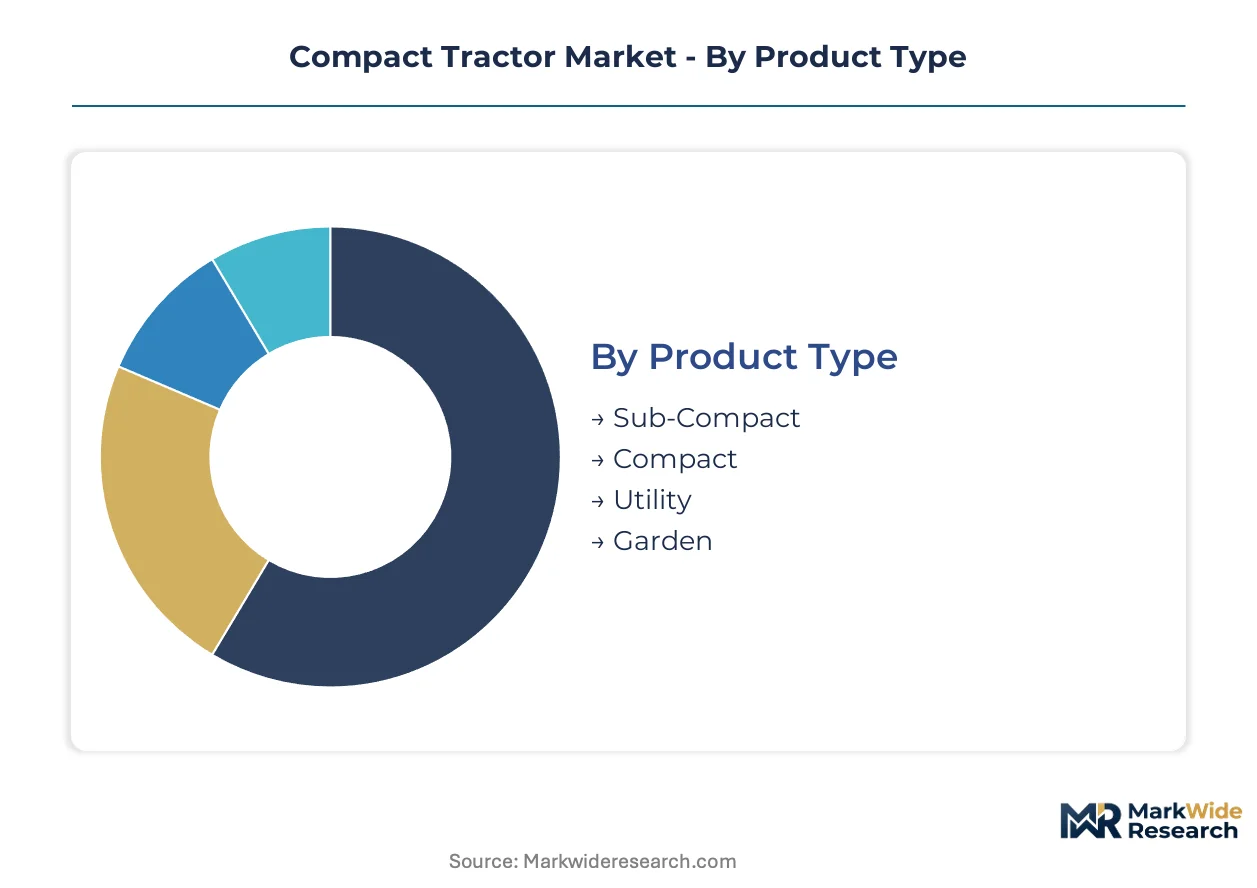
Compact tractor segmentation reveals distinct equipment life cycles across power classes and buyer profiles. Replacement timing varies sharply between commercial fleets operating on depreciation schedules and rural property owners holding machines for fifteen-plus years.
Product Type:
Upgrade cycles compress toward five-to-seven-year intervals for revenue-generating fleets, while hobbyist owners stretch replacement decisions across decades of accumulated repair tolerance.
- Compact:These units span 25-60 horsepower with three-point hitch standardization and mid-frame loader compatibility. Landscaping contractors in the United States Southeast specify this class for sustained daily mowing and material handling where sub-compact frames lack hydraulic capacity. Fleet standardization around compact footprints reduces attachment inventory duplication across multi-machine operations.
- Utility:Heavy-frame construction accommodates backhoe and auger implements across 40-60 horsepower ranges. Agricultural sector buyers in the United States Midwest select utility configurations for rotational tillage and hay handling on fifty-acre diversified operations. The EPA Tier 4 Final compliance burden falls heaviest here, compressing independent manufacturer participation.
- Sub-Compact:Narrow chassis designs below 25 horsepower target driveway maintenance and light mowing on five-to-ten-acre rural residential parcels.
- Garden:Lawn-and-garden hybrid configurations with limited PTO output serve decorative landscaping and snow removal for homeowners prioritizing maneuverability over implement versatility.
Volume placements concentrate in Compact; the faster expansion belongs to Utility as commercial operators size up for attachment flexibility.
End User:
Cost tier stratification separates capital-rich fleet buyers from price-sensitive rural property owners, with municipalities occupying a middle band governed by procurement cycle rigidity.
- Landscaping Companies:Commercial grounds maintenance operations standardize on hydrostatic transmission units with quick-attach loader systems for seasonal attachment rotation. These buyers negotiate fleet pricing through regional dealer networks and specify telematics integration for utilization tracking across dispersed job sites.
- Agricultural Sector:Smallholder and hobby farm operators in the United States Midwest drive replacement demand as aging baby boomers exit farming and successor generations acquire mechanized equipment. This segment tolerates higher per-unit prices for dealer proximity and parts availability.
- Municipalities:Public works departments issue RFPs on multi-year cycles, prioritizing domestic content requirements and service network density over specification optimization.
- Homeowners:Rural residential buyers on five-to-twenty-acre parcels select sub-compact and garden configurations through retail financing programs, with purchase timing tied to property acquisition rather than equipment failure.
Margin pools concentrate in Landscaping Companies; the steepest volume climb belongs to Agricultural Sector hobby farm expansion.
Power Rating:
Application requirements dictate horsepower selection, with mixed-use owners gravitating toward mid-range ratings that preserve fuel efficiency across intermittent task diversity.
- 25-50 HP:This band captures the broadest cross-section of compact tractor demand, balancing PTO output for rotary cutters and tillers with chassis maneuverability in confined spaces. Landscaping contractors specify this range for crew versatility across residential and commercial contracts without requiring operator reclassification.
- Less than 25 HP:Sub-compact power outputs suit mowing and light material handling where full three-point hitch capability remains secondary to transport speed and garage storage dimensions.
- 51-75 HP:Utility-class ratings accommodate continuous PTO operation for hay equipment and moderate loader work on small commercial farms.
- 76-100 HP:Upper compact ranges approach agricultural tractor territory, selected for specialty orchard and vineyard configurations requiring narrow profiles with substantial hydraulic flow.
Unit economics favor 25-50 HP; the expanding application set belongs to 51-75 HP as small-scale commercial operators mechanize.
Transmission Type:
Operator skill availability and task repetition frequency determine transmission selection, with hydrostatic configurations capturing margin from labor-constrained commercial buyers.
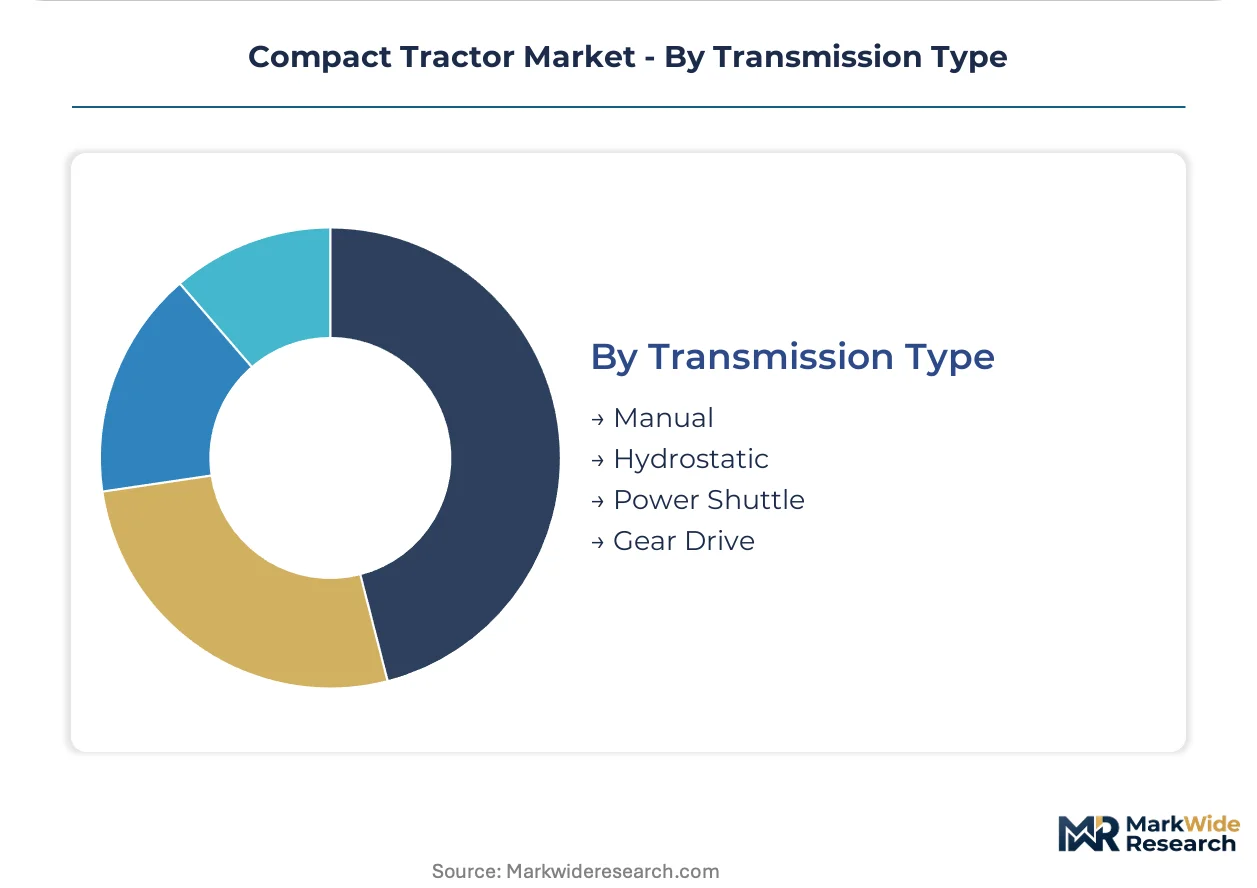
- Hydrostatic:Infinitely variable speed control eliminates clutch operation and gear selection, reducing training requirements for seasonal landscaping labor. These transmissions command price premiums of fifteen to twenty-five percent over mechanical alternatives while compressing service department expertise requirements.
- Manual:Synchronized gear boxes retain mechanical efficiency advantages and lower acquisition costs for price-sensitive agricultural buyers comfortable with traditional operation protocols.
- Power Shuttle:Directional reversibility without clutch disengagement suits loader-intensive applications where repetitive forward-reverse cycles dominate task profiles.
- Gear Drive:Unsynchronized mechanical transmissions persist in entry-level utility configurations where capital constraints outweigh operator convenience priorities.
Revenue concentration sits with Hydrostatic; the technology transition momentum favors Power Shuttle for loader-heavy commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rural Enterprise Zones in the United States Midwest concentrate compact tractor demand through property tax abatements for agricultural equipment purchases. Hobby farm proliferation across ten-to-fifty-acre parcels generates replacement cycles distinct from commercial fleet patterns. Dealer network density in Iowa, Illinois, and Ohio shapes brand accessibility and service response times.
United States
Commercial landscaping contracts across suburban Atlanta, Dallas-Fort Worth, and Phoenix corridors pull fleet purchases toward hydrostatic transmission units. EPA Tier 4 Final emissions standards compress margins for non-compliant engine suppliers while rewarding certified platform holders. Dealer concentration in the Corn Belt states of Iowa, Indiana, and Ohio anchors parts availability and trade-in liquidity for agricultural buyers.
Germany
European Stage V regulations accelerate after-treatment system adoption among vineyard and orchard operators in the Rhine Valley. The country's national agricultural regulator enforces strict power take-off guarding certifications under harmonized EU machinery directives. Stuttgart and Munich industrial clusters host precision hydraulics suppliers feeding compact transmission assembly lines.
India
Smallholder mechanization subsidies under the government's agricultural credit guarantee scheme expand addressable demand below thirty-five horsepower. The Bureau of Indian Standards mandates emission compliance timelines that lag Euro norms by four to six years, creating export platform flexibility. Manufacturing concentrates in Maharashtra and Gujarat where component vendor ecosystems support cost-optimized utility configurations.
Brazil
Coffee and fruit agroforestry operations in Minas Gerais and São Paulo states require narrow-profile chassis for inter-row cultivation. ANVISA agricultural machinery safety protocols align with Mercosur technical regulations, streamlining cross-border certification. Campinas and Piracicaba host regional assembly operations serving Latin American orchard and sugarcane segments.
Japan
Domestic demand concentrates in precision rice farming and municipal grounds maintenance on constrained island geography. METI energy efficiency standards push hydraulic system refinement rather than full electrification given rural grid limitations. Osaka and Nagoya manufacturing bases export compact powertrain components to Southeast Asian assembly plants.
Compact Tractor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line agricultural equipment houses commanding premium positioning while regional assemblers compete on price-accessible utility configurations. The market structure tilts toward consolidated leadership in North America and Western Europe, with fragmented competition across emerging Asian and Latin American markets. Three archetypes dominate: heritage agricultural brands with dense dealer networks, Asian industrial conglomerates leveraging manufacturing scale, and emerging market specialists optimizing for subsidy-program price points. Competitive moves center on telematics platform integration and strategic partnerships for battery-electric powertrain development.
Within the heritage brand tier, John Deere and Kubota exemplify dealer-network-dependent market presence, with the former anchoring Midwest agricultural demand and the latter sustaining Japanese engineering credibility in hydrostatic transmission refinement. Mahindra occupies a distinct position as an emerging market specialist, with its Mumbai-based corporate structure supporting price-accessible utility configurations. These three companies represent the primary competitive anchors across premium, engineering-focused, and value-tier positioning respectively.
| Leading Market Players |
|---|
| New Holland |
| Case IH |
| John Deere |
| Massey Ferguson |
| KIOTI |
| Kubota |
| Yanmar |
| TYM |
| Mahindra |
| Others |
Value Network & Pricing Analysis
Steel price indices and aluminum commodity benchmarks cascade through compact tractor supply chains, compressing entry-level margins while amplifying pricing power for manufacturers with captive foundry operations and long-term ore contracts.
Pricing Analysis
Lead-time premiums reward buyers securing hydrostatic transmission units from dealer inventory, while spot-market discounts apply to manual-transmission configurations held in regional distribution centers. Three-tier pricing structure across premium hydrostatic, standard power shuttle, and economy gear-drive levels separates fleet buyers from hobby farm operators. Pricing pressure stems from EPA Tier 4 Final after-treatment hardware costs that add three-to-five thousand dollars per unit. Landscaping contractors exhibit lowest price sensitivity due to telematics-enabled productivity gains, while rural residential buyers in the Midwest demand entry-level configurations.
Supply Chain Analysis
Welding technician shortages in Iowa, Illinois, and Ohio constrain chassis fabrication throughput, forcing manufacturers to prioritize higher-margin utility configurations over sub-compact lines. Engine supply concentrates in Japan and India, with hydraulic component sourcing anchored in Germany and Italy. Diesel particulate filters and selective catalytic reduction systems draw from specialized ceramic substrate suppliers in Japan and the United States. Single-source vulnerability in emissions after-treatment ceramics exposes assemblers to supply disruption. Distribution runs through authorized dealer networks with parts depots in Corn Belt states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compact tractor manufacturing sits in a powertrain transition phase, with electrified platforms displacing high-pressure common rail diesel architectures as battery energy density improves and rural charging infrastructure expands.
For Market Incumbents: Deepen backward integration into emissions after-treatment component manufacturing to capture margin pools currently flowing to specialized ceramic substrate suppliers. Expand certified service technician training programs in rural dealer networks to address the diesel diagnostic skills shortage threatening customer retention. Threat: battery-electric entrants with simplified drivetrains bypassing after-treatment complexity entirely.
For New Entrants and Emerging Players: Launch via direct-to-fleet subscription models targeting private equity-backed landscaping rollups in the United States Southeast, converting capital expenditure to operating expense. White-space targets include narrow-profile orchard configurations for Brazilian coffee operations and cost-optimized sub-thirty-five-horsepower units for Indian smallholder subsidy programs. Most penetrable segment: telematics-naive municipal fleets seeking usage analytics.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier hydraulic system specialists with established foundry relationships in Maharashtra and Gujarat, positioned for volume scaling under Indian agricultural credit guarantee schemes. Long-term viability hinges on five-to-ten-year electrification transition pacing aligned with rural grid infrastructure buildout. Signal to watch: lithium-iron-phosphate battery pack cost curves crossing diesel powertrain total cost of ownership thresholds for intermittent-use applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | GPS tracking and predictive maintenance software create recurring revenue streams from landscaping fleet operators. |
| Emissions Certification Investment | EPA Tier 4 Final and European Stage V compliance opens technology leadership positioning against non-certified competitors. |
| Orchard-Specific Chassis Design | Narrow-profile configurations capture Brazilian coffee and fruit agroforestry expansion in Minas Gerais and São Paulo states. |
| Dealer Network Density Expansion | Service proximity in Iowa, Illinois, and Ohio anchors parts availability and trade-in liquidity for agricultural buyers. |
| Battery-Electric Powertrain Partnership | Strategic alliances with lithium-ion pack suppliers address rural charging limitations while meeting regulatory pressure. |
Research Methodology
Multi-period observation of fleet replacement cycles, hobby farm parcel acquisition rates, and emissions compliance timelines anchored the trend analysis, supplemented by interviews with compact tractor product managers, regional dealer principals, landscaping fleet procurement directors, and agricultural cooperative equipment specialists. Secondary validation drew from EPA certification databases, European Stage V type-approval records, United States Census Bureau agricultural land use surveys, and Bureau of Indian Standards mechanization subsidy disbursement reports. Bottom-up unit shipment estimates triangulated against top-down manufacturer revenue disclosures.
Input-output matrices mapped horsepower segment demand to chassis fabrication capacity, engine platform availability, and hydraulic component supply across the projection horizon. Segmentation dimensions modeled included power rating tier, transmission configuration, end-user archetype, and regional regulatory cluster. CAGRs were derived from curve-fitting historical replacement patterns against projected fleet expansion and hobby farm formation rates. Industry-specific forecast inputs incorporated diesel technician training pipeline data and rural electrical service upgrade timelines.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powertrains would alter the outlook if lithium-ion energy density improvements accelerate or rural fast-charging networks expand faster than baseline assumptions. Forecasts reflect documented assumptions regarding emissions enforcement stringency, commodity metal price volatility, and subsidy program continuity. Material deviation in battery cost curves, technician training graduation rates, or agricultural credit guarantee funding levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
North America Agricultural Machinery Market