
 Crawler Tractors Market | 2026-2036
Crawler Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Tractors Market Analysis
The crawler tractor market is pivoting between premium precision-agriculture configurations and commodity-grade construction models, with engine sophistication and telematics capability splitting the value chain. Caterpillar leverages its dealer network density to sustain aftermarket revenue streams across North American mining corridors. Komatsu anchors its position through in-house powertrain production and autonomous haulage integration. Shantui Construction Machinery competes on manufacturing scale and domestic supply chain control within China's infrastructure build-out.
A crawler tractor is a self-propelled tracked vehicle engineered to deliver high tractive effort at low ground pressure, typically operating at drawbar pulls exceeding 80 percent of vehicle weight on soils with bearing capacities below 1.5 kg/cm². Its primary purpose spans earthmoving, land clearing, and material pushing across terrain where wheeled equipment would sink or slip. Heavy duty crawler units dominate mining and large-scale civil engineering where margin pools concentrate in aftermarket parts and rebuild services. Electric technology within the crawler segment is gaining traction in urban construction zones with emissions restrictions, though diesel-hydraulic architectures still occupy the bulk of forestry and agricultural applications.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by ECHA member authorities are mandating selective catalytic reduction and diesel particulate filters on engines above 56 kW, raising manufacturing costs but creating aftermarket retrofit demand. China's MIIT implements GB 36886 non-road emission standards that parallel European test cycles, pressuring domestic producers like SANY and Zoomlion to accelerate engine partnerships. Stakeholders must monitor how battery-electric powertrains perform in high-torque drawbar applications before committing capital away from proven diesel-hydraulic platforms.
Market Dynamics
Emissions compliance deadlines are compressing product development cycles across the crawler tractor sector, forcing simultaneous retooling of engine architectures and telematics platforms while mining operators in Australia and Chile accelerate fleet replacement schedules.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V mandates:These emissions frameworks are triggering wholesale engine upgrades across all horsepower classes, generating replacement demand for non-compliant legacy units in North American and European mining corridors.
- Deep ore access projects:Mining operators in Australia's Pilbara region and Chile's Atacama are deploying heavy-duty crawler fleets to exploit lower-grade deposits that require greater earthmoving intensity.
- State-backed infrastructure procurement:China's MIIT-directed programs sustain bulk orders for high-horsepower units, anchoring manufacturing scale for domestic producers.
Market Restraints
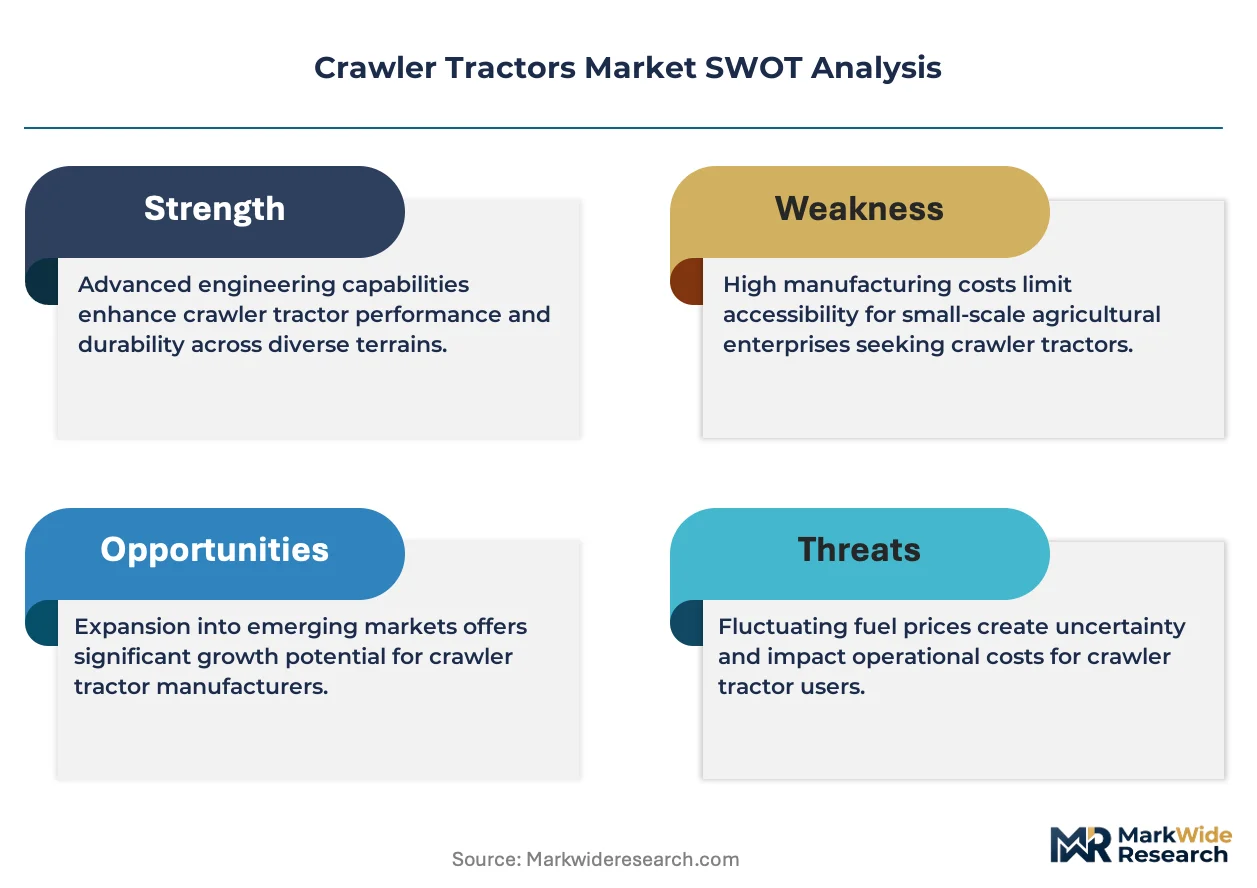
- Selective catalytic reduction and diesel particulate filter costs:The hardware and urea infrastructure required for EPA Tier 4 Final and EU Stage V compliance adds manufacturing cost without commensurate pricing power in commodity construction segments.
- Engine supply concentration:A limited cohort of certified powertrain suppliers controls access to compliant diesel engines above 250 kW, creating bottleneck risk for mid-tier OEMs.
- Battery-electric torque limitations:Current lithium-ion architectures cannot sustain the continuous high-drawbar applications required in forestry and large-scale mining without unacceptable weight penalties.
Strategic Opportunities
- Urban construction electrification:Municipal emissions restrictions in European and Chinese cities are creating first-mover openings for battery-electric crawler units in confined-site earthmoving.
- Autonomous haulage integration:Convergence of crawler tractors with autonomous haulage ecosystems presents aftermarket service and fleet optimization revenue streams.
- Telematics-enabled outcome pricing:Equipment-as-a-service models leveraging real-time utilization data are penetrating mining procurement frameworks in Australia and Canada.
Industry Challenges
- Emissions certification timelines:The GB 36886 test cycle alignment with European protocols is compressing development schedules for Chinese producers seeking export qualification.
- Powertrain engineering talent scarcity:The intersection of diesel aftertreatment expertise and electric drivetrain development is creating recruitment friction across OEM engineering departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Tractors Market |
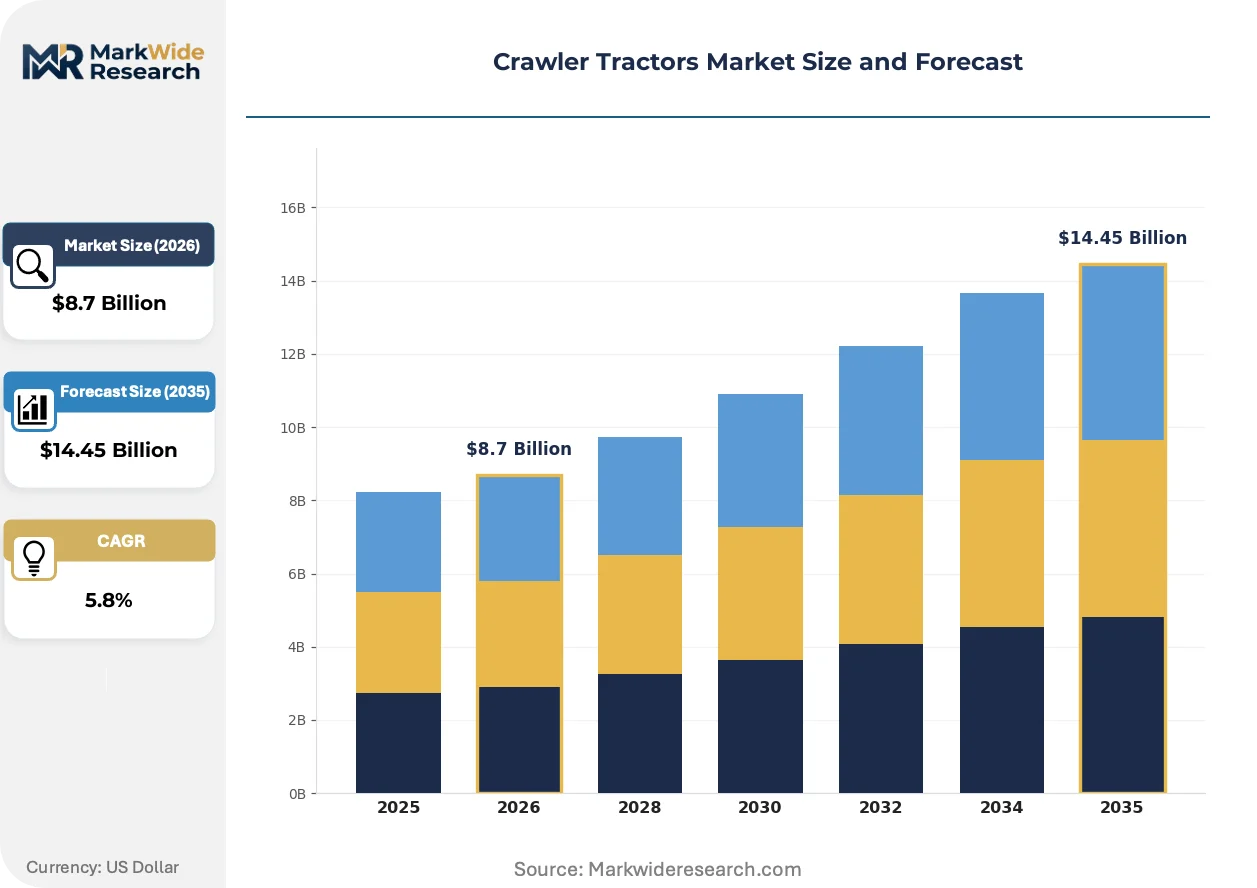
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Crawler, Mini Crawler, Heavy Duty Crawler, Hybrid Crawler End User: Agriculture, Construction, Mining, Forestry Technology: Hydraulic, Electric, Diesel, Biofuel Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Caterpillar, Komatsu, John Deere, Liebherr, Shantui Construction Machinery, Hitachi Construction Machinery, Volvo Construction Equipment, SANY Heavy Industry, Zoomlion Heavy Industry Science & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Tractors Market Emerging Trajectories
Telematics integration and powertrain electrification are bifurcating the crawler tractor value chain, with premium mining configurations adopting autonomous-ready architectures while agricultural and forestry segments prioritize proven diesel-hydraulic reliability.
Hydrogen fuel cell range-extender systems are expanding into heavy-duty crawler applications where battery weight compromises tractive performance. Mining operators in Chile's copper belt are piloting fuel-cell auxiliary units to maintain continuous operation during multi-shift cycles. This architecture is expanding into segments previously considered unreachable for pure-electric alternatives.
EU Stage V enforcement by ECHA member authorities is mandating real-world emissions monitoring through portable measurement systems, extending compliance obligations from factory certification to in-field operation. Construction contractors in Germany and France are retrofitting existing fleets with telematics-linked emissions logging to satisfy municipal contract requirements. The policy is compressing residual values for non-compliant used equipment.
Consolidated procurement by mining majors is displacing fragmented dealer networks in high-volume segments. Rio Tinto and BHP are negotiating direct fleet agreements with OEMs, bypassing traditional distribution channels in Australia's mining corridors. This concentration is forcing distributor margin compression and service capability specialization.
Crawler Tractors Market Segmentation
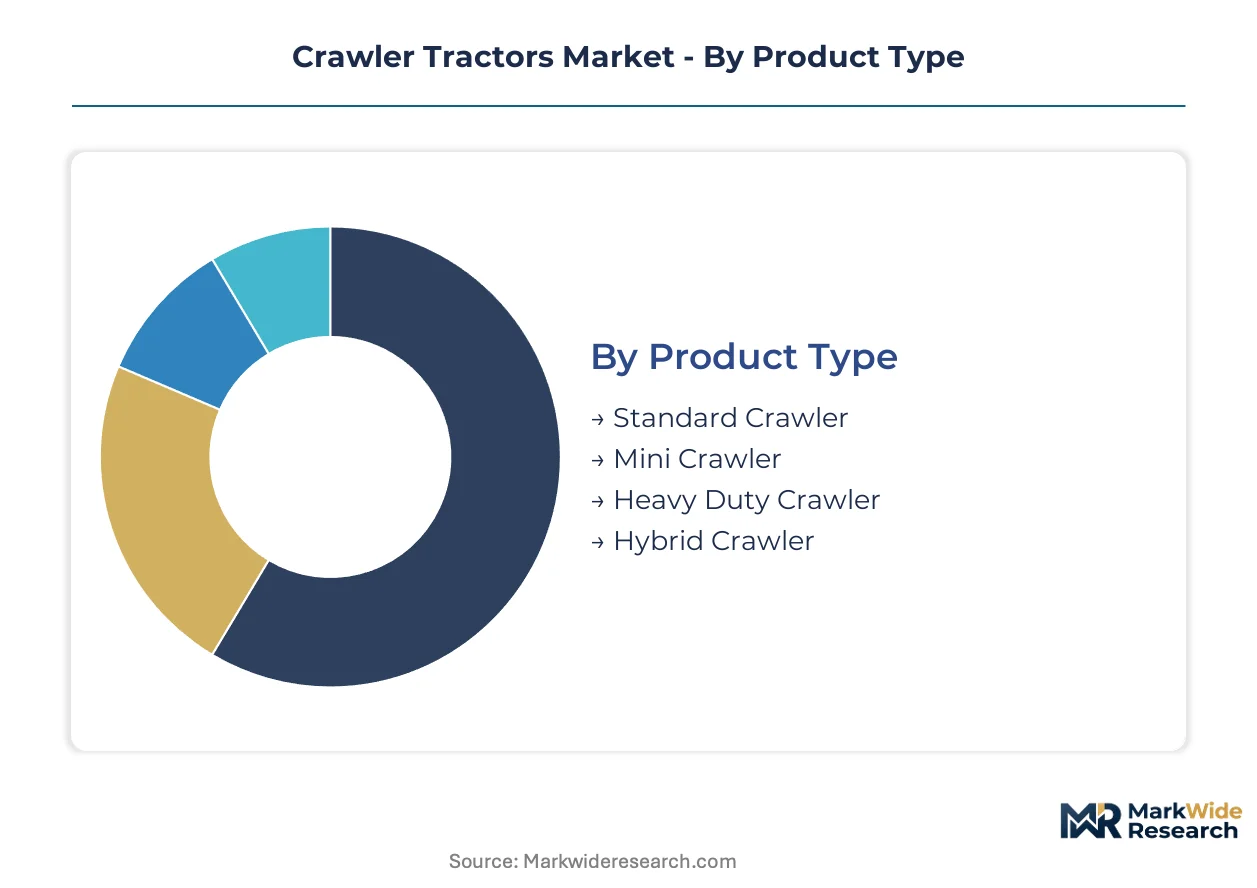
Crawler tractor segmentation reveals how engineering specifications, regulatory pressure, and terrain economics fragment manufacturing priorities across power classes and duty cycles. Equipment buyers select configurations based on ground pressure limits, emissions zone restrictions, and aftermarket service density rather than upfront unit cost alone.
Product Type:
Supply concentration in heavy-duty powertrain manufacturing favors established OEMs with in-house engine certification capability, while mini and hybrid variants attract specialized component suppliers.
- Standard Crawler:Diesel-hydraulic architectures dominate this mid-horsepower category, delivering 80-150 kW output for general earthmoving and land clearing. Demand concentrates in China's state-backed infrastructure corridors where bulk procurement sustains manufacturing scale for domestic producers like Shantui and SANY.
- Heavy Duty Crawler:Units exceeding 250 kW drawbar rating incorporate selective catalytic reduction and diesel particulate filters to meet EPA Tier 4 Final and EU Stage V mandates. Australia's Pilbara mining operators and Chile's Atacama copper belt deploy these configurations for continuous high-torque applications in low-bearing-capacity soils.
- Mini Crawler:Sub-50 kW machines serve confined urban construction sites with reduced ground pressure footprints.
- Hybrid Crawler:Diesel-electric architectures target municipal emissions zones where battery-only range remains insufficient for full-shift operation.
Today's leader: Heavy Duty Crawler. Tomorrow's challenger: Hybrid Crawler.
End User:
Application economics split procurement patterns between long-cycle mining contracts and seasonal agricultural demand, with construction and forestry occupying intermediate positions on capital intensity and utilization rates.
- Mining:Multi-shift continuous operation at drawbar pulls exceeding 80 percent of vehicle weight defines this segment's engineering requirements. Australia's BHP and Rio Tinto negotiate direct fleet agreements with OEMs, bypassing traditional distribution channels and compressing dealer margins while concentrating aftermarket revenue with manufacturer service divisions.
- Construction:Municipal emissions restrictions in European and Chinese cities are accelerating electrification pilots for confined-site earthmoving, though diesel-hydraulic platforms still dominate highway and heavy civil projects where refueling infrastructure is dispersed.
- Agriculture:Precision farming configurations prioritize telematics integration and GPS-guided implement control over raw power output.
- Forestry:Continuous high-torque drawbar applications in remote terrain sustain demand for proven mechanical powertrains with field-serviceable architectures.
Mining commands capital deployment; construction is gaining share fastest in electrification-adjacent procurement.
Technology:
Powertrain engineering talent scarcity at the intersection of diesel aftertreatment and electric drivetrain development is constraining how quickly OEMs can diversify beyond established hydraulic architectures.
- Diesel:EPA Tier 4 Final and EU Stage V compliance has compressed product development cycles for engines above 56 kW, mandating selective catalytic reduction hardware and urea infrastructure that raises manufacturing cost without commensurate pricing power in commodity construction segments.
- Hydraulic:Proven architectures dominate forestry and agricultural applications where field serviceability and parts availability outweigh efficiency gains from electrification.
- Electric:Lithium-ion battery systems are penetrating urban construction zones with emissions restrictions, though current architectures cannot sustain continuous high-drawbar mining applications without unacceptable weight penalties.
- Biofuel:Hydrotreated vegetable oil compatibility offers a compliance pathway for existing diesel platforms in jurisdictions with renewable fuel mandates.
Diesel retains installed base dominance; electric is climbing the fastest in municipal procurement frameworks.
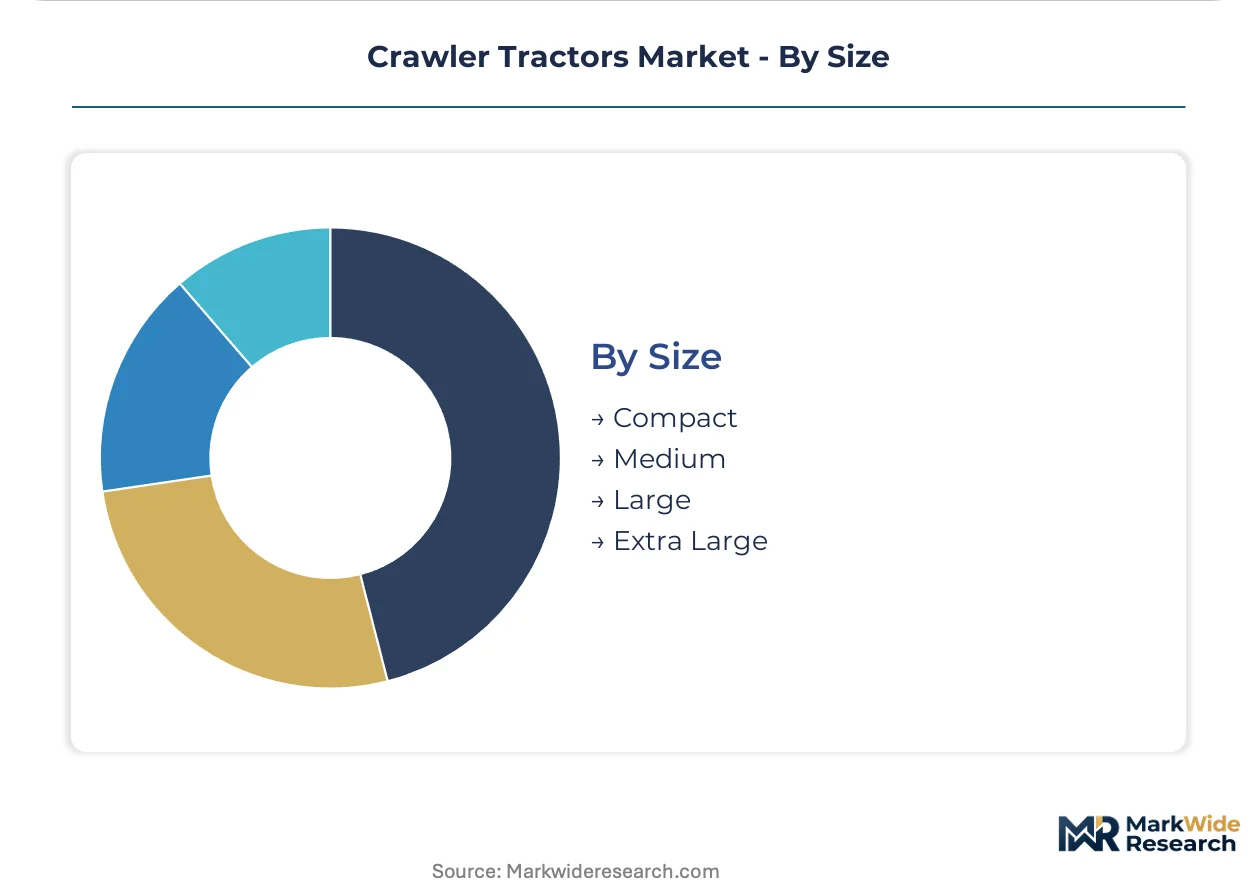
Size:
Ground pressure requirements and transport logistics shape how size categories map to end-use economics, with extra-large units requiring specialized low-loader permits and on-site assembly.
- Large:Units in the 15-30 tonne operating weight class balance tractive performance with highway transportability, serving mining overburden removal and major civil earthmoving where mobilization costs must be recovered across multiple project phases. China's MIIT-directed infrastructure programs sustain bulk orders for this configuration.
- Extra Large:Exceeding 30 tonnes, these machines require disassembly for transport and on-site reassembly, anchoring aftermarket parts and rebuild service revenue for OEMs with dense dealer networks in Australia's mining corridors.
- Compact:Sub-5 tonne machines serve landscaping and utility trenching with trailer-tow mobility.
- Medium:The 5-15 tonne range covers general construction and agricultural drainage applications.
Large units anchor manufacturing scale; extra large commands margin concentration in aftermarket services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powertrain engineering talent clusters in Germany's industrial belt and China's Yangtze River Delta anchor crawler tractor development. Mining corridors in Australia and Chile concentrate heavy-duty fleet deployment. Regulatory enforcement in North America and Europe compresses product certification timelines.
United States
EPA Tier 4 Final mandates drive replacement demand across mining and construction fleets. The agency's selective catalytic reduction requirements for engines above 56 kW raise manufacturing costs but create aftermarket retrofit opportunities. Texas shale plays and Arizona copper belts deploy heavy-duty units for continuous earthmoving operations.
Germany
EU Stage V enforcement by ECHA member authorities mandates real-world emissions monitoring through portable measurement systems. The KBA oversees type approval for non-road mobile machinery entering European markets. Bavaria's industrial corridor hosts engineering centers developing autonomous haulage integration for mining applications.
China
MIIT-directed infrastructure programs sustain bulk procurement of high-horsepower units through state-backed construction consortia. GB 36886 non-road emission standards parallel European test cycles, pressuring domestic producers to accelerate engine partnerships. Shandong Province's manufacturing belt concentrates production scale for crawler tractor assembly.
Australia
BHP and Rio Tinto negotiate direct fleet agreements with OEMs, bypassing traditional distribution channels in the Pilbara mining corridor. The country's national environmental regulator enforces diesel emissions standards aligned with European protocols. Western Australia's iron ore deposits require crawler fleets capable of operating on soils with bearing capacities below 1.5 kg/cm².
Chile
Copper belt operators in the Atacama deploy heavy-duty crawler configurations for lower-grade ore deposits requiring greater earthmoving intensity. The national mining regulator oversees equipment certification for high-altitude operations. Antofagasta's mining cluster pilots hydrogen fuel cell range-extender systems to maintain continuous multi-shift cycles.
Crawler Tractors Market Vendor Landscape
Top-tier vendors anchor premium mining and precision-agriculture configurations, while mid-tier specialists compete on manufacturing scale and domestic supply chain control. The vendor base stratifies across three tiers: integrated powertrain producers with in-house engine certification, regional fabricators leveraging local procurement relationships, and emerging entrants targeting electrification niches. Two dominant competitive moves define current positioning: direct fleet agreements with mining majors displacing traditional dealer networks, and strategic partnerships between OEMs and certified engine suppliers to secure compliant powertrain access above 250 kW.
Within the integrated powertrain tier, Caterpillar and Komatsu exemplify archetypes of dealer network density and autonomous haulage integration respectively. Shantui Construction Machinery occupies a position representing manufacturing scale and domestic supply chain control within China's infrastructure build-out.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| John Deere |
| Liebherr |
| Shantui Construction Machinery |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| SANY Heavy Industry |
| Zoomlion Heavy Industry Science & Technology |
| Others |
Supply Flow & Price Mechanics
Captive powertrain production at Caterpillar and Komatsu anchors both supply security and aftermarket pricing power across heavy-duty mining configurations. This backward integration into engine certification and dealer service networks insulates premium tiers from commodity cost compression while exposing mid-tier OEMs to selective catalytic reduction hardware margin squeeze.
Pricing Analysis
Bundled aftermarket service contracts dominate mining procurement in Australia's Pilbara region, while unbundled equipment-only transactions prevail in China's state-backed infrastructure corridors. Price differentiation rests on EPA Tier 4 Final certification tier and telematics integration depth, with autonomous-ready configurations commanding substantial premiums over standard diesel-hydraulic units. Cost compression in mid-horsepower construction segments is intensifying because domestic Chinese producers leverage manufacturing scale without commensurate emissions hardware burdens. Mining majors exhibit the lowest price sensitivity, prioritizing uptime guarantees and rebuild service density over upfront unit cost.
Supply Chain Analysis
Dual-sourcing mandates from BHP and Rio Tinto require OEMs to qualify multiple certified engine suppliers above 250 kW, fragmenting powertrain procurement across Germany, Japan, and the United States. The supply chain draws from high-strength steel forgings, electronic control modules, and urea dosing systems as critical inputs. Single-source vulnerability concentrates in selective catalytic reduction catalyst substrates, where a limited cohort of suppliers controls access to EPA-compliant architectures. Distribution runs through manufacturer-direct fleet agreements for mining majors and traditional dealer networks for construction and agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crawler tractor market reads as a late-cycle quality story where mining operators in Australia and Chile are trading up to autonomous-ready configurations with integrated telematics, displacing price-competitive standard units from procurement shortlists.
For Market Incumbents: To counter hydrogen fuel cell range-extender pilots in Chile's Atacama copper belt, accelerate in-house electric drivetrain development and secure exclusive service contracts with mining majors through outcome-based uptime guarantees. Channel control through dense dealer networks in North American mining corridors remains essential for capturing aftermarket rebuild revenue. For New Entrants and Emerging Players: EU Stage V enforcement in Germany and France opens a window for battery-electric crawler units in urban construction zones with municipal emissions restrictions. Target confined-site earthmoving contractors in European cities with trailer-tow compact configurations and telematics-linked emissions logging as a differentiated compliance service. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because mining fleet concentration is compressing dealer margins and forcing capability specialization. The long-term viability window favors targets with certified rebuild facilities in Australia's Pilbara or Chile's Antofagasta cluster. Watch hydrogen fuel cell auxiliary unit adoption rates as the inflection signal for powertrain technology transition.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Integration | Rio Tinto's direct fleet agreements with OEMs bypass traditional distribution channels in Australia's mining corridors. |
| Powertrain Electrification Partnership | Collaborations between OEMs and battery suppliers address torque limitations in high-drawbar mining applications. |
| Emissions Certification Investment | GB 36886 alignment with European test cycles accelerates export qualification timelines for Chinese producers. |
| Telematics Platform Development | Real-time utilization data enables equipment-as-a-service models penetrating Australian and Canadian mining procurement. |
| Aftermarket Service Network Expansion | Dense rebuild facilities in Western Australia capture margin concentration from extra-large unit deployments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Pilbara mining operations, OEM procurement teams, aftermarket service heads, and plant engineers with secondary validation against SEC filings, customs trade records, EPA certification databases, and MIIT infrastructure procurement disclosures. Bottom-up unit shipment tallies and top-down equipment spending estimates were triangulated to anchor volume projections.
Segment-weighted modeling distributed crawler tractor demand across power class, end-use application, and technology architecture over the projection horizon. Powertrain engineering capacity, emissions compliance timelines, and mining capital expenditure cycles served as industry-specific forecast inputs. CAGRs were derived from fitted growth curves against historical replacement patterns and regulatory deadline impacts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt battery-electric torque breakthroughs or extended diesel platform exemptions in forestry applications. Deviation in Chinese state-backed infrastructure procurement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Crop Sprayers Market