
 Hydrogen Powered Tractor Market | 2026-2036
Hydrogen Powered Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Powered Tractor Market Outlook
ISO 19880-1 certification for gaseous hydrogen fueling protocols is redrawing competitive entry barriers for OEMs seeking commercial scale. John Deere leverages its precision agriculture ecosystem to integrate fuel cell powertrains with existing fleet management software. H2Trac B.V. specializes in purpose-built hydrogen tractor architectures rather than retrofit platforms. Ballard Power Systems anchors the propulsion supply chain through captive fuel cell stack production for agricultural OEMs.
A hydrogen powered tractor converts chemical energy from compressed or liquid hydrogen into electrical power via proton exchange membrane fuel cells, typically delivering 100-300 kW continuous output for heavy tillage and harvesting operations. The technology eliminates tailpipe emissions while maintaining diesel-comparable torque profiles and refueling intervals under 15 minutes. Conventional tractors occupy the dominant revenue position due to retrofit compatibility with existing implement interfaces, though autonomous tractors represent the fastest-expanding segment as precision farming demands unmanned field operations. Fuel cell technology captures the primary margin pool given stack durability requirements and thermal management complexity, while hydrogen storage systems compete on tank gravimetric density and TUV certification cycles.
The EPA's Tier 4 Final and upcoming Tier 5 emissions standards for off-road equipment compress the diesel tractor upgrade window, while the EU F-Gas Regulation and CE machinery directives mandate zero-emission alternatives in protected agricultural zones. Germany's KBA enforces hydrogen system type approval for mobile machinery, shaping product development timelines for European market access. Stakeholders must monitor hydrogen fuel station density in agricultural corridors and the resolution of fuel cell stack warranty terms under high-dust operating conditions.
Market Dynamics
The EPA's Tier 5 emissions trajectory is compressing diesel tractor replacement cycles while EU F-Gas Regulation mandates force zero-emission procurement decisions across protected agricultural zones.
Growth Catalysts
- EU Green Deal decarbonization mandates:The framework's binding targets for farm machinery emissions are accelerating OEM fuel cell platform investment across German, French, and Dutch agricultural corridors.
- Compressed hydrogen refueling infrastructure:Germany's hydrogen corridor network enables 15-minute refueling intervals matching diesel operational tempo for large-scale tillage contractors.
- Precision agriculture integration:Fuel cell powertrains are being bundled with autonomous field management systems, creating bundled procurement incentives for 500+ hectare operations.
Market Restraints
- Platinum group metal cost volatility:Fuel cell stack catalyst requirements expose OEMs to palladium and platinum price swings that compress manufacturing margins.
- Hydrogen production concentration:Gray hydrogen from natural gas reforming dominates current supply, limiting lifecycle emissions advantages until electrolyzer capacity scales.
- ISO 19880-1 certification barriers:The gaseous hydrogen fueling protocol standard creates 18-24 month approval timelines that delay commercial deployment for new market entrants.
Strategic Opportunities
- Autonomous tractor segments:Unmanned field operations in North American large-scale farming present first-mover positioning for fuel cell-powered autonomous platforms.
- CE machinery directive compliance services:Technical consultancy supporting zero-emission machinery certification represents adjacent revenue streams for engineering firms.
- Hydrogen storage system convergence:Integration of 700-bar composite tanks with thermal management systems opens specialization niches for tank gravimetric density leaders.
Industry Challenges
- Fuel cell stack warranty under high-dust conditions:Agricultural particulate exposure degrades membrane electrode assembly durability, forcing OEMs to renegotiate warranty terms or develop enhanced filtration.
- Legacy implement interface compatibility:Hydrogen powertrain torque curves and hydraulic output specifications must match existing attachment ecosystems without performance degradation.
- Cross-functional talent scarcity:The intersection of agricultural engineering, fuel cell electrochemistry, and precision software development creates recruitment bottlenecks for R&D teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Powered Tractor Market |
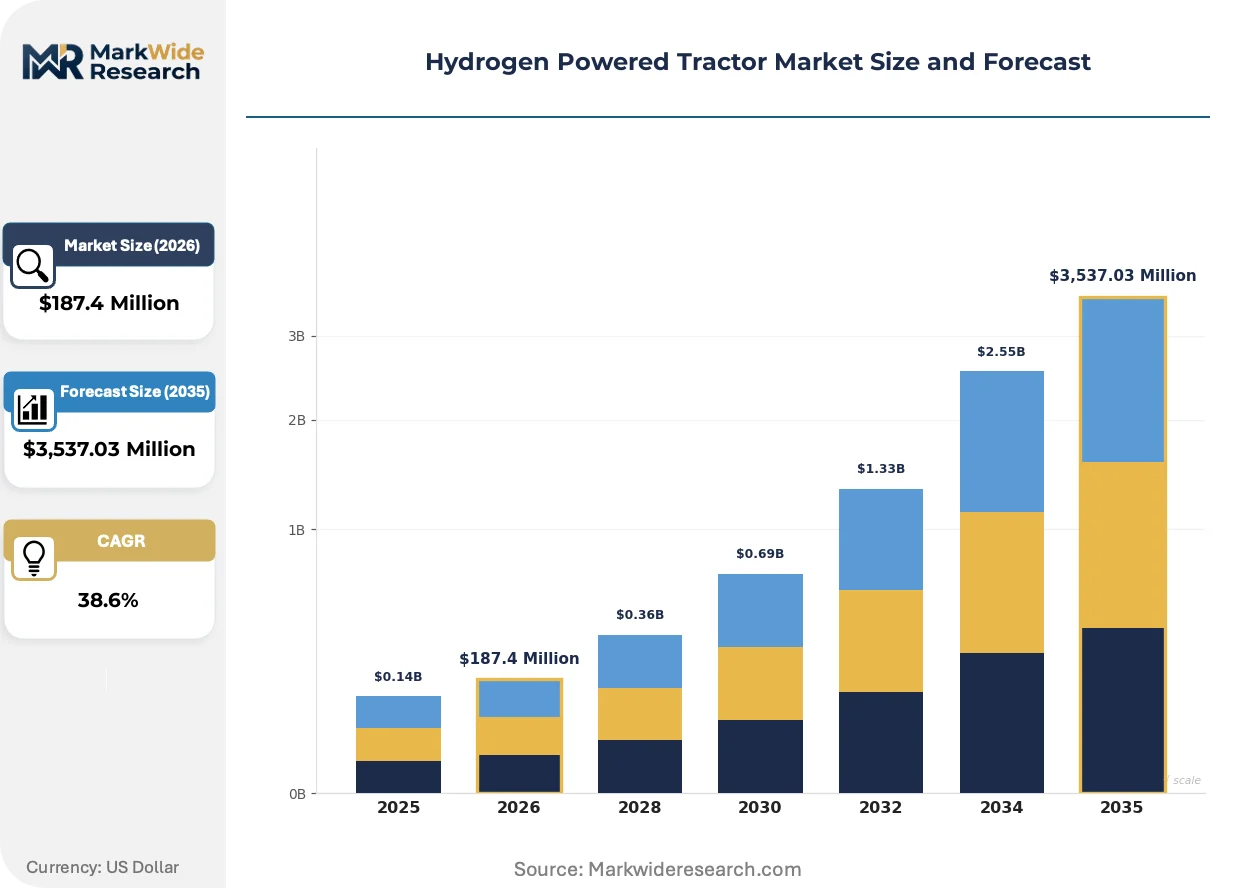
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Tractors, Autonomous Tractors, Electric Tractors, Hybrid Tractors Application: Agricultural Operations, Turf Management, Vineyards, Greenhouses End User: Farmers, Agricultural Cooperatives, Landscaping Companies, Government Agencies Technology: Fuel Cells, Hydrogen Storage, Batteries, Power Electronics |
| Companies Covered | John Deere, CNH Industrial, Kubota Corporation, AGCO Corporation, H2Trac B.V., Ballard Power Systems, Hyundai Motor Company, Fendt, New Holland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Powered Tractor Market Strategic Shifts
Proton exchange membrane fuel cell architectures are actively fragmenting the propulsion supply chain as agricultural OEMs internalize stack production capabilities.
Modular fuel cell stack designs are decomposing the traditional tiered supplier structure in agricultural powertrains. Large-scale farming cooperatives in Germany and the Netherlands are specifying integrated fuel cell-electric drivetrains for replacement cycles. This technology convergence is decomposing the historical separation between engine manufacturers and implement OEMs, forcing captive stack production investments.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is accelerating refrigerant system redesigns in tractor thermal management. OEMs must eliminate hydrofluorocarbon-based cooling circuits to maintain CE marking compliance for 2027 model years. German manufacturers are responding fastest, leveraging KBA hydrogen type approval frameworks to front-load compliant product launches ahead of enforcement windows.
Cooperative procurement consortia are consolidating equipment purchasing power across 1,000+ hectare farming operations in the US Midwest and Canadian prairies. These buying groups are unbundling traditional dealer service packages and negotiating direct fuel cell powertrain warranties with OEM technical teams. The behavior shift is most pronounced in North Dakota and Saskatchewan grain belts, where fuel station density planning now precedes fleet procurement decisions.
Hydrogen Powered Tractor Market Segmentation
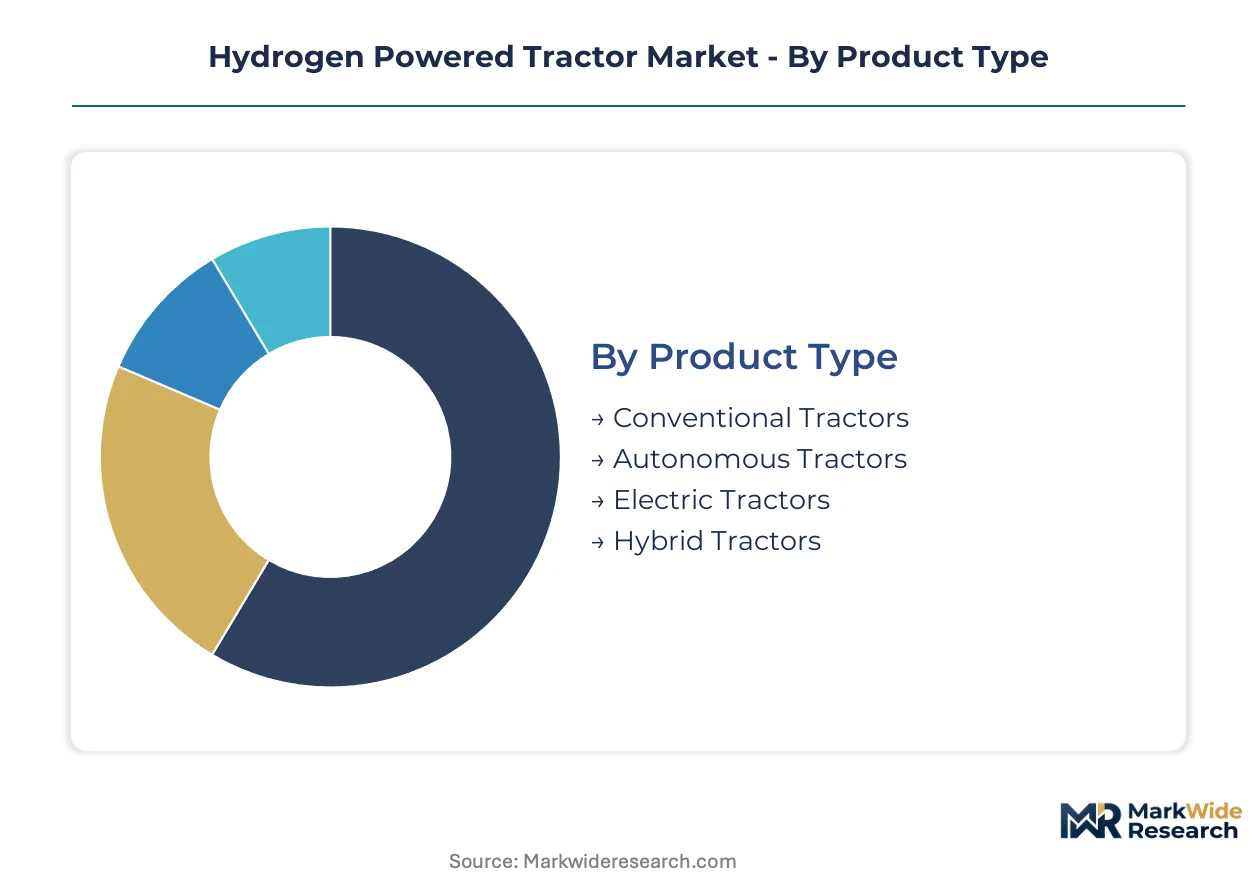
Segmentation in the hydrogen powered tractor market reveals divergent deployment strategies across powertrain architectures and operational environments. Understanding these divisions exposes where fuel cell technology delivers immediate operational value versus where battery-electric alternatives compete on capital cost.
Product Type:
German and Dutch procurement patterns favor autonomous platforms for export corridor contracts, while North American grain belt operators prioritize conventional retrofit-compatible units for domestic fleet integration.
- Conventional Tractors:Retain diesel-comparable torque curves and hydraulic interfaces for seamless implement attachment. Demand concentrates in Saskatchewan and North Dakota grain operations where 500+ hectare farms require immediate fleet replacement compatibility without infrastructure overhaul.
- Autonomous Tractors:Integrate fuel cell powertrains with precision agriculture software stacks for unmanned field operations. German large-scale cooperatives along the hydrogen corridor network are specifying these for nighttime tillage cycles where refueling intervals under 15 minutes sustain continuous operation.
- Electric Tractors:Battery-dominant architectures suit greenhouse and vineyard applications with shorter duty cycles and overnight charging availability.
- Hybrid Tractors:Combine fuel cell range extension with battery buffering for variable-load operations in mixed terrain.
Conventional tractors hold the largest share; momentum sits with autonomous platforms.
Application:
Margin concentration varies sharply by operational intensity and emissions sensitivity, with protected zones commanding premium pricing for zero-emission compliance.
- Agricultural Operations:Heavy tillage and harvesting demand 100-300 kW continuous output with diesel-matching refueling tempo. The EU F-Gas Regulation's protected zone mandates are accelerating procurement decisions in German organic farming corridors.
- Turf Management:Municipal and sports field maintenance requires low-noise operation with moderate power draw. Dutch municipal fleets are bundling hydrogen turf equipment with regional refueling infrastructure investments.
- Vineyards:Narrow-gauge fuel cell units navigate terraced terrain with zero tailpipe emissions preserving grape quality.
- Greenhouses:Enclosed-environment operations prioritize water vapor exhaust from fuel cells over battery thermal management complexity.
Agricultural operations dominate volume; vineyards are expanding most quickly on regulatory pressure.
End User:
Procurement authority is consolidating toward cooperative buying groups with direct OEM negotiation leverage, displacing traditional dealer-mediated sales.
- Farmers:Individual owner-operators below 200 hectares face capital cost barriers, though German KBA-backed leasing programs are improving access.
- Agricultural Cooperatives:1,000+ hectare buying groups in the US Midwest and Canadian prairies unbundle service packages and negotiate direct fuel cell warranties. These consortia now precede fleet decisions with hydrogen station density planning.
- Landscaping Companies:Municipal contract requirements for zero-emission equipment are reshaping equipment replacement timelines.
- Government Agencies:Research demonstration programs and procurement mandates for state-owned agricultural land.
Agricultural cooperatives command the steepest expansion trajectory; government agencies anchor pilot deployment.
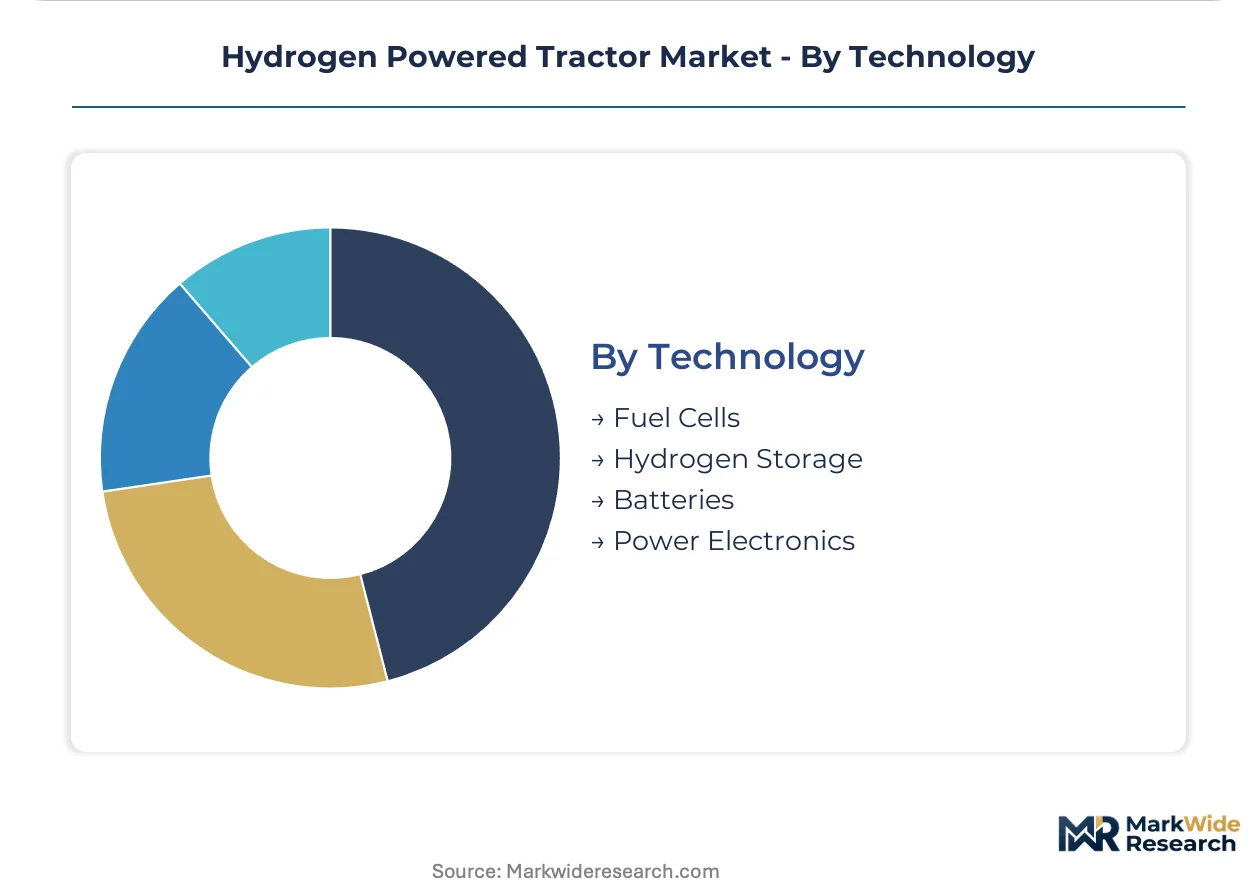
Technology:
Supply chain control is fragmenting as OEMs internalize stack production to capture margin and manage warranty exposure under high-dust agricultural conditions.
- Fuel Cells:Proton exchange membrane architectures deliver 100-300 kW with platinum group metal catalyst dependency exposing manufacturers to palladium price volatility. Stack durability under agricultural particulate exposure remains the critical warranty negotiation point.
- Hydrogen Storage:700-bar composite tank systems compete on gravimetric density and TUV certification cycles. Thermal management integration with fuel cell waste heat recovery is emerging as a specialization niche.
- Batteries:Lithium-ion buffer systems for hybrid architectures and autonomous tractor power management.
- Power Electronics:Inverter and motor control systems adapting diesel-comparable torque curves to electric drivetrains.
Fuel cells capture the primary margin pool; hydrogen storage systems are gaining share fastest on infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed hydrogen corridor investments in Germany are accelerating early commercial deployment of fuel cell tractors across European agricultural zones. Large-scale farming cooperatives in North America are consolidating procurement power for zero-emission fleet transitions. Precision agriculture integration is reshaping equipment replacement timelines in high-value crop regions worldwide.
Germany
The KBA enforces hydrogen system type approval for mobile machinery, creating regulatory clarity for OEM market entry. Germany's hydrogen corridor network enables 15-minute refueling intervals matching diesel operational tempo. Large-scale cooperatives in Lower Saxony and Schleswig-Holstein are specifying integrated fuel cell-electric drivetrains for nighttime tillage cycles.
United States
The EPA's Tier 5 emissions trajectory compresses diesel tractor replacement cycles across Midwest grain operations. Cooperative procurement consortia in North Dakota and Saskatchewan unbundle traditional dealer service packages for direct OEM negotiation. The US Midwest grain belt now precedes fleet decisions with hydrogen station density planning.
Netherlands
Dutch municipal fleets are bundling hydrogen turf equipment with regional refueling infrastructure investments. The EU F-Gas Regulation mandates zero-emission alternatives in protected agricultural zones. Greenhouse operations in Westland cluster specify fuel cell units for enclosed-environment water vapor exhaust advantages.
Canada
Prairie province farming cooperatives above 1,000 hectares negotiate direct fuel cell powertrain warranties with OEM technical teams. Canadian federal clean fuel regulations accelerate procurement decisions in Saskatchewan grain belts. The Saskatchewan-Alberta corridor is emerging as a concentration point for hydrogen infrastructure planning preceding equipment orders.
France
French organic farming corridors face EU F-Gas Regulation protected zone mandates accelerating zero-emission procurement. The country's national agricultural regulator enforces machinery emissions standards tightening through 2027. Vineyard operations in Bordeaux and Champagne regions specify narrow-gauge fuel cell units for terraced terrain navigation.
Hydrogen Powered Tractor Market Competitive Environment
Player mix skews toward diversified agricultural equipment conglomerates with captive fuel cell development capabilities. Market structure concentrates around OEMs with precision agriculture software ecosystems and tier-one propulsion suppliers with stack production scale. Two strategic archetypes dominate: legacy tractor manufacturers integrating fuel cell powertrains with existing fleet management platforms, and specialized fuel cell stack producers supplying agricultural propulsion systems. Competitive moves center on backward integration into stack production and strategic partnerships for hydrogen storage system certification.
Within the legacy equipment tier, John Deere leverages its precision agriculture ecosystem to anchor fuel cell powertrain integration with existing fleet management software. H2Trac B.V. exemplifies the purpose-built specialist archetype, concentrating on hydrogen-native tractor architectures rather than retrofit platforms. Ballard Power Systems occupies the propulsion supply chain anchor position through captive fuel cell stack production for agricultural OEMs.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| Kubota Corporation |
| AGCO Corporation |
| H2Trac B.V. |
| Ballard Power Systems |
| Hyundai Motor Company |
| Fendt |
| New Holland |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month ISO 19880-1 certification timelines compress inventory turnover for fuel cell stack manufacturers, concentrating pricing power with Ballard Power Systems and vertically integrated OEMs while forcing smaller entrants into extended working capital cycles. This lead-time structure privileges incumbents with captive certification expertise and established KBA type approval relationships in Germany.
Pricing Analysis
Certification level (ISO 19880-1/CE marking tier) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium autonomous platforms, standard conventional tractors, and economy retrofit kits dominates procurement contracts. Cost compression in standard-tier fuel cell stacks is intensifying because platinum group metal price volatility squeezes manufacturing margins. Agricultural cooperatives above 1,000 hectares exhibit lowest price sensitivity due to direct OEM negotiation leverage, while individual owner-operators below 200 hectares face acute capital barriers despite German KBA-backed leasing programs.
Supply Chain Analysis
Platinum group metal inventory cycles of 90-120 days tether fuel cell stack production to South African and Russian mining output volatility. Manufacturing concentrates in Germany, Japan, and South Korea for precision membrane electrode assembly production. The propulsion supply chain draws from Canadian graphite for bipolar plates, Japanese carbon fiber for 700-bar tank systems, and Belgian specialty polymers for gaskets. Single-source vulnerability in membrane electrode assembly coating equipment presents structural risk. Distribution runs through agricultural OEM captive service networks and cooperative procurement consortia in North Dakota and Saskatchewan grain belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU F-Gas Regulation protected zone mandates force zero-emission procurement decisions ahead of hydrogen infrastructure maturity. Penetration tailwinds from Germany's hydrogen corridor network and cooperative buying group consolidation create first-mover windows for positioned players.
For Market Incumbents: Fortify captive fuel cell stack production capabilities to control warranty exposure under high-dust agricultural conditions. Secure direct procurement relationships with 1,000+ hectare cooperative consortia before channel control consolidates further. Defend against H2Trac B.V.-style purpose-built specialists by accelerating precision agriculture software integration with fuel cell powertrain telemetry.
For New Entrants and Emerging Players: After-sales service unbundling by Midwest grain belt cooperatives creates entry space for independent fuel cell maintenance specialists. Target vineyard narrow-gauge segments in Bordeaux and Champagne where regulatory pressure outpaces incumbent product development. Pursue CE machinery directive compliance consultancy as a service-layer wedge before establishing manufacturing presence.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized fuel cell divisions lacking agricultural sector focus. Five-to-ten-year viability hinges on electrolyzer capacity scaling to displace gray hydrogen concentration. Watch hydrogen station density planning in Saskatchewan-Alberta corridor as inflection indicator for North American fleet procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel Cell Stack Production | John Deere and CNH Industrial capture margin pools previously ceded to Ballard Power Systems. |
| Hydrogen Corridor Infrastructure Partnership | German cooperatives in Lower Saxony secure 15-minute refueling intervals matching diesel tempo. |
| Autonomous Platform Software Integration | Precision agriculture bundling creates procurement lock-in for nighttime tillage cycle operations. |
| CE Machinery Directive Compliance Pre-Certification | Front-loaded product launches ahead of 2027 F-Gas Regulation enforcement windows secure market access. |
| Cooperative Procurement Consortium Direct Warranty | North Dakota and Saskatchewan buying groups disintermediate traditional dealer service margins. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fuel cell engineering directors, agricultural cooperative procurement leads, OEM platform development executives, and hydrogen infrastructure planners. Secondary validation drew from KBA type approval filings, EU F-Gas Regulation implementation guidance, EPA Tier 5 emissions trajectory documentation, and agricultural machinery trade customs data. Bottom-up equipment deployment estimates triangulated against top-down hydrogen corridor investment disclosures.
Across the projection horizon, volume and value outputs segmented by powertrain architecture, operational application, end-user procurement authority, and technology component layer. Growth trajectory derivation incorporated fuel cell stack durability testing under agricultural particulate exposure, platinum group metal price elasticity assumptions, and cooperative buying group penetration curves. Modeled inputs included hydrogen station density buildout schedules and KBA certification pipeline velocities.
Underlying assumptions cover electrolyzer capacity scaling timelines and EU Green Deal enforcement consistency, with deviation risk concentrated in gray hydrogen supply persistence and fuel cell stack warranty claim rates under high-dust field conditions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Garden Tractor Market