
 Combine Harvesters Market | 2026-2036
Combine Harvesters Market Size, Share, and Industry Trends Forecast 2026-2036
Combine Harvesters Market Intelligence
High-strength steel is realigning combine harvester chassis economics as manufacturers trade conventional carbon grades for lighter, fatigue-resistant alloys. Deere & Company leverages its foundry network to control alloy sourcing across North American production lines. CNH Industrial N.V. anchors European supply through its Raven precision agriculture division. AGCO Corporation competes on modular frame architectures that accommodate regional crop profiles without full redesign.
A combine harvester is a self-propelled machine that cuts, threshes, and cleans grain crops in a single pass, typically employing a cutter bar width of 20 to 45 feet and a threshing cylinder rotating at 700 to 1,200 RPM to separate grain from straw. Its primary commercial purpose is to reduce field losses below 2% while compressing harvest windows during weather-sensitive crop maturity periods. Self-propelled units command the dominant margin pool due to integrated powertrain and cab-environment premiums, while GPS-guided technology segments are gaining fastest as RTK correction signals enable sub-inch row tracking. Specialty configurations for rice and corn remain niche but carry pricing power in tropical belt markets where standard designs suffer clogging losses.
The EPA enforces Tier-4 Final emission limits on diesel engines above 56 kW, forcing turbocharger and after-treatment redesigns that add cost and service complexity to new machines. EU F-Gas Regulation and REACH chemical restrictions govern refrigerants in cab climate systems and hydraulic fluid formulations, creating compliance barriers for non-European exporters. India's CEA and BIS certification requirements for agricultural machinery safety and electromagnetic compatibility add testing layers for entrants targeting the subcontinent's cooperative procurement channels. Stakeholders must weigh engine platform consolidation against regional certification fragmentation when allocating R&D budgets.
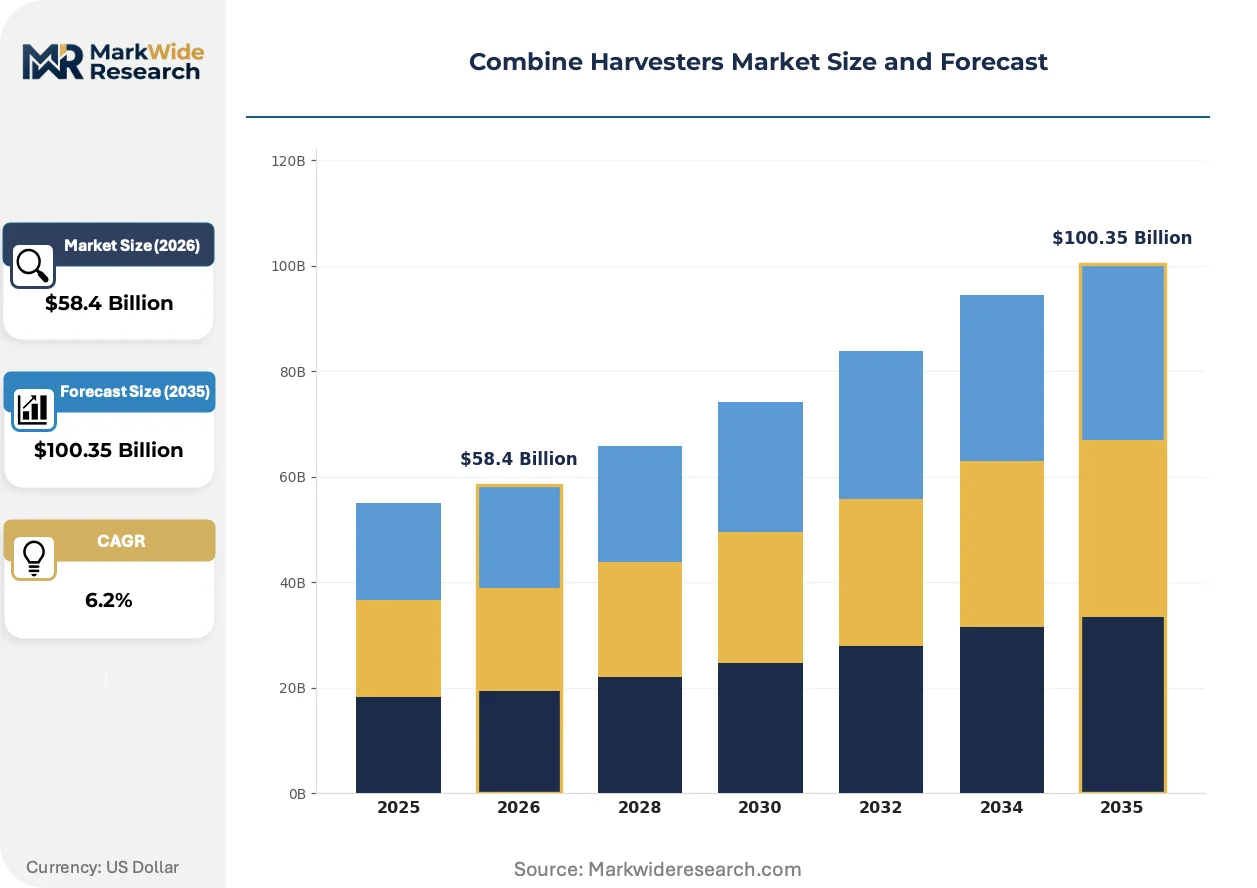
Market Dynamics
Precision agriculture hardware is compressing replacement cycles across grain-producing regions as fleet operators trade mechanical reliability for sensor-integrated platforms that enable real-time yield mapping and variable-rate input application.
Growth Catalysts
- EPA Tier-4 Final mandates:Diesel engine redesigns are forcing fleet turnover toward cleaner architectures, accelerating replacement demand among North American operators with aging pre-2015 machines.
- RTK-guided autosteering:Sub-inch accuracy is reducing operator fatigue and field overlap, pulling adoption among large-scale Iowa and Illinois cooperatives managing 10,000-plus acre operations.
- High-strength steel chassis:Lighter fatigue-resistant alloys are extending service intervals and reducing soil compaction, creating pull from Brazilian Cerrado operators facing weight restrictions on transport corridors.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add $15,000-$25,000 per unit, compressing margins on mid-range combine configurations.
- Hydraulic fluid formulation shifts:REACH-compliant bio-based alternatives suffer shorter change intervals and temperature sensitivity, creating operational friction for Eastern European exporters.
- Foundry capacity concentration:Premium alloy casting for threshing cylinders clusters in Germany and Japan, exposing supply chains to energy price volatility and shipping bottlenecks.
Strategic Opportunities
- Ukraine reconstruction demand:Post-conflict agricultural recovery will require 15,000-20,000 unit replacements, creating a concentrated procurement window for manufacturers with established Black Sea distribution.
- Rice-specific threshing configurations:Modified rotor geometries and moisture-resistant sieves address tropical belt clogging losses, unlocking premium pricing in Vietnam and Indonesia cooperative channels.
- EU F-Gas refrigerant phase-down:Low-GWP cab climate systems create compliance-driven upgrade cycles among German and French fleet operators under fleet decarbonization mandates.
Industry Challenges
- Mechatronics technician scarcity:Combines now integrate 40-plus sensors and CAN-bus networks, but vocational programs in the US Corn Belt and Brazil's Mato Grosso lag in producing diagnostic-capable service personnel.
- Electromagnetic compatibility certification:India's CEA testing protocols for GPS and telemetry systems add 8-12 month approval timelines, delaying market entry for precision-agriculture-equipped models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combine Harvesters Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Hybrid, Specialty, Self-Propelled Technology: GPS, Automation, IoT, Computer Vision End User: Farmers, Agricultural Cooperatives, Contractors, Large Scale Enterprises Size: Small, Medium, Large, Commercial |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, CLAAS KGaA mbH, Kubota Corporation, Mahindra & Mahindra Limited, SDF S.p.A., Iseki & Co., Ltd, Yanmar Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combine Harvesters Market Strategic Shifts & Innovations
Sensor fusion and edge computing are migrating from cab displays to embedded machine controllers, compressing the latency between field condition detection and actuator response while reducing dependence on cloud connectivity in remote harvest zones.
LiDAR-based obstacle detection is automating header height control and foreign-object rejection in real-time threshing operations. Large-scale Kansas and Nebraska operators are retrofitting 2018-2020 model year machines with aftermarket kits, creating a secondary hardware market alongside OEM integrated systems. This capability is automating night-shift harvesting previously limited by operator visibility constraints, effectively doubling daily machine utilization during compressed weather windows.
REACH chemical restrictions are forcing hydraulic fluid reformulation across EU-destined machines, with bio-based ester formulations replacing mineral oils in transmission and header lift circuits. The industrial consequence is accelerated seal degradation and shortened service intervals, particularly in high-temperature Southern European harvest conditions. Italian and Spanish dealers are responding with extended warranty packages that bundle fluid analysis and preventive seal replacement to maintain customer retention.
Cooperative procurement consolidation is displacing individual farm purchases across the Indo-Gangetic Plain, with Punjab and Haryana state agricultural departments aggregating 200-plus unit tenders. Equipment financiers are adapting with fleet-level underwriting models that weight collective credit risk over individual borrower profiles. This concentration is most visible in India's northwestern grain belt, where three state procurement agencies now account for 40 percent of annual combine placements.
Combine Harvesters Market Segmentation
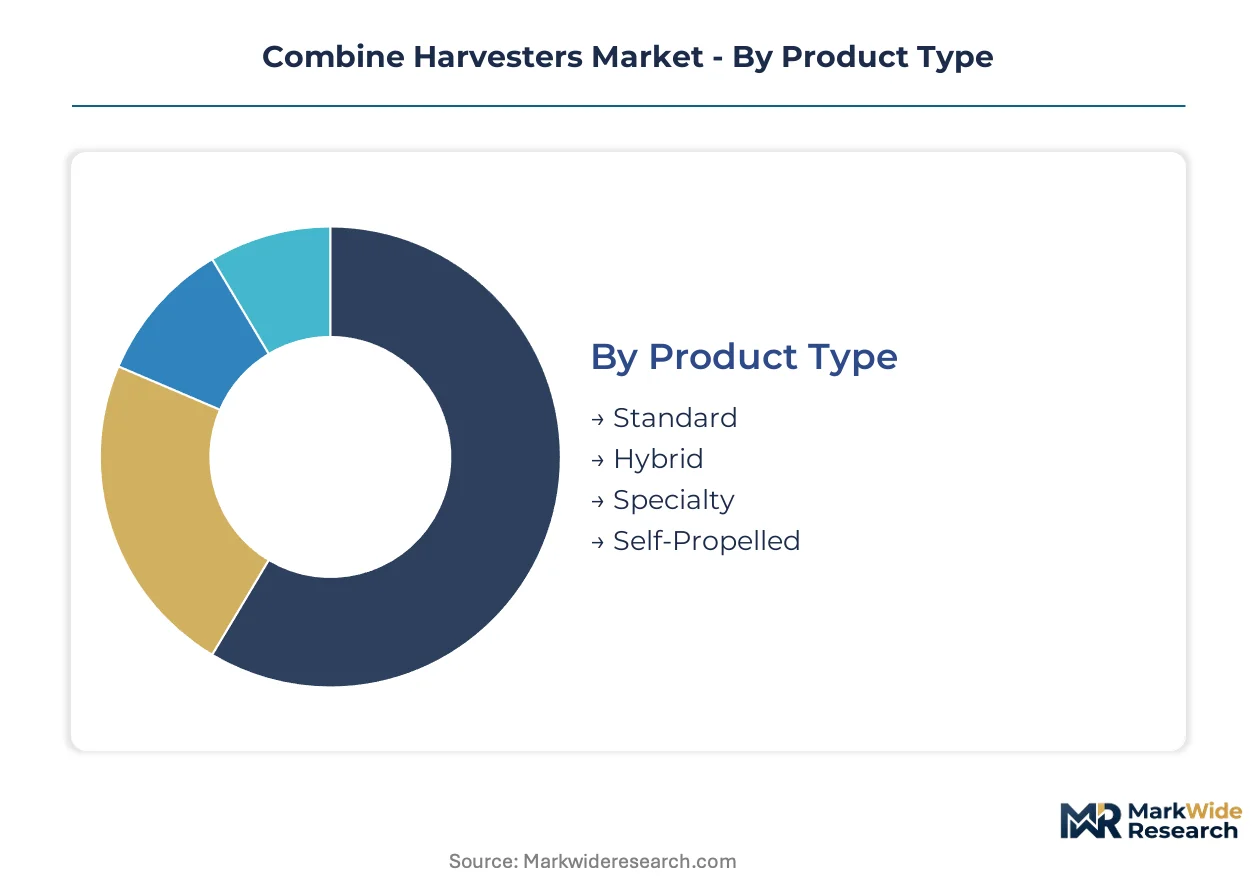
Combine harvester procurement patterns diverge sharply across operator scale and crop specialization, with certification requirements and precision-technology integration reshaping segment economics. Fleet operators now segment purchases by threshing capacity, automation tier, and regional compliance burden rather than traditional horsepower classifications.
Product Type:
EPA Tier-4 Final certification applies universally across all engine configurations, while EU F-Gas Regulation compliance varies by cab climate system specification and REACH chemical restrictions affect hydraulic formulations differentially by frame architecture.
- Self-Propelled:Integrated powertrain and cab-environment platforms dominate margin pools through unified engine-threshing-hydraulic architectures. Demand concentrates among Iowa and Illinois cooperatives managing 10,000-plus acre operations where RTK-guided autosteering reduces field overlap and operator fatigue.
- Specialty:Modified rotor geometries and moisture-resistant sieves address tropical belt clogging losses in rice and corn configurations. Vietnam and Indonesia cooperative channels unlock premium pricing where standard designs suffer harvest losses exceeding 5% in high-humidity conditions.
- Standard:Conventional threshing cylinder designs serve price-sensitive operators in Eastern European grain belts with established service networks.
- Hybrid:Dual-power architectures blending diesel and electric auxiliary systems target German and French fleet operators under fleet decarbonization mandates.
Leading the category by volume: Self-Propelled. Growing fastest: Specialty.
Technology:
Cost tier stratification separates retrofit-capable sensor packages from factory-integrated embedded controllers, with precision-agriculture premiums clustering in GPS and automation tiers while IoT and computer vision segments carry higher certification complexity for electromagnetic compatibility.
- GPS:RTK correction signals enable sub-inch row tracking across large-scale Kansas and Nebraska operations. Brazilian Cerrado operators facing weight restrictions on transport corridors prioritize GPS-integrated fleet management for logistics optimization.
- Automation:LiDAR-based obstacle detection automates header height control and foreign-object rejection, compressing latency between field condition detection and actuator response. Night-shift harvesting utilization doubles during compressed weather windows.
- IoT:CAN-bus telemetry architectures face India's CEA certification protocols adding 8-12 month approval timelines for telemetry-equipped models.
- Computer Vision:Edge-computing grain quality assessment migrates from cab displays to embedded controllers, reducing cloud dependence in remote harvest zones.
Volume concentration sits with GPS. Steepest expansion trajectory: Automation.
End User:
Customer type determines financing structure and fleet replacement cadence, with large-scale enterprises compressing replacement cycles toward sensor-integrated platforms while individual farmers and contractors prioritize mechanical reliability and aftermarket service accessibility.
- Large Scale Enterprises:Precision agriculture hardware adoption accelerates replacement cycles as yield mapping and variable-rate input application justify platform turnover. Punjab and Haryana state agricultural departments aggregate 200-plus unit tenders, displacing individual farm purchases across the Indo-Gangetic Plain.
- Agricultural Cooperatives:Fleet-level underwriting models weight collective credit risk over individual borrower profiles, with three state procurement agencies now accounting for 40 percent of annual combine placements in India's northwestern grain belt.
- Contractors:Seasonal utilization models prioritize transportability and rapid crop-change configuration across multiple client operations.
- Farmers:Individual ownership persists in fragmented land-holding regions with limited cooperative infrastructure.
Category leadership by unit volume: Large Scale Enterprises. Fastest share gain: Agricultural Cooperatives.
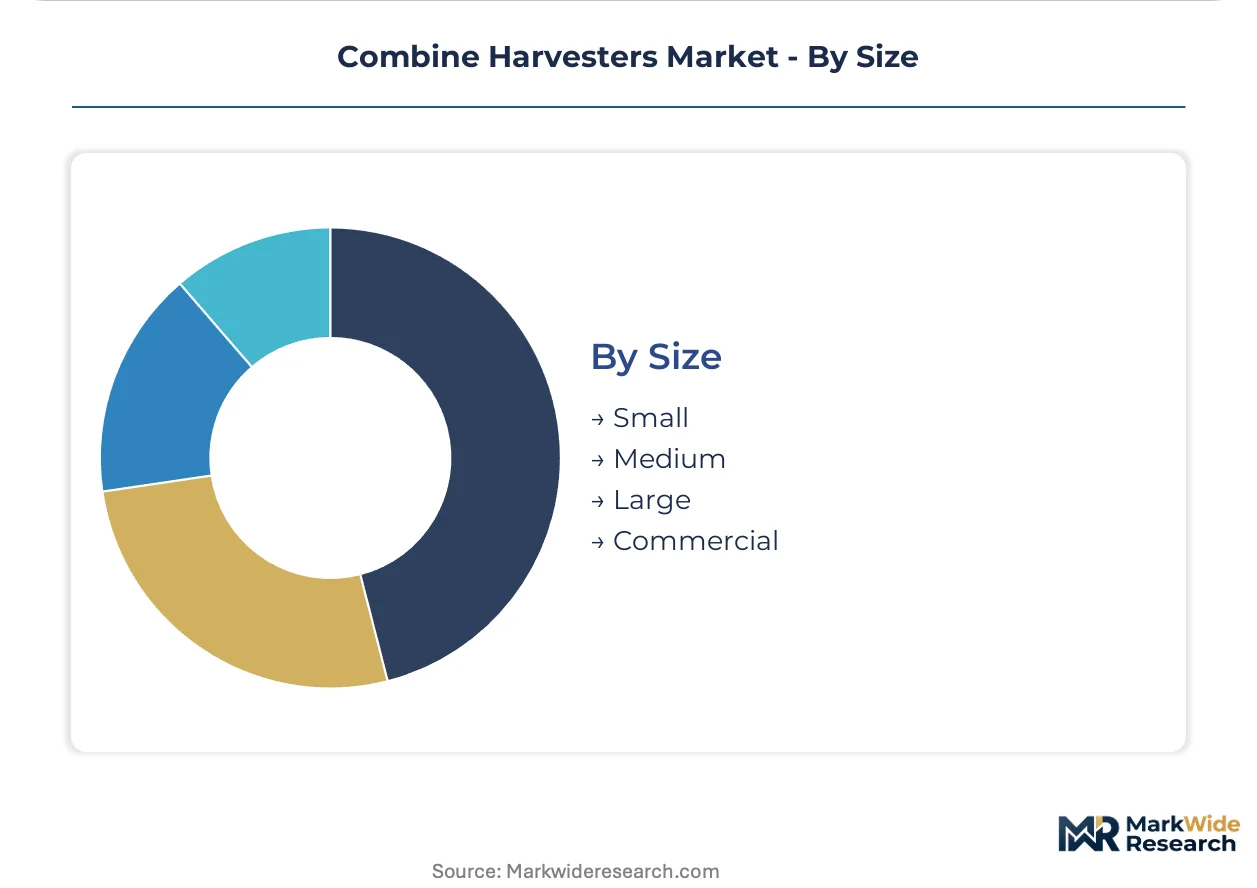
Size:
Application-driven segmentation aligns cutting width and threshing capacity with regional crop profiles and field geometry, with commercial and large configurations commanding premium pricing in expansive flatland operations while small and medium units serve terraced and fragmented holdings.
- Large:Cutter bar widths of 35 to 45 feet and threshing cylinders rotating at 700 to 1,200 RPM compress harvest windows during weather-sensitive crop maturity periods. US Corn Belt operators achieve field loss rates below 2% at sustained throughput.
- Commercial:Maximum capacity architectures target Black Sea distribution networks positioning for Ukraine reconstruction demand requiring 15,000-20,000 unit replacements.
- Medium:Versatile configurations accommodate mixed-crop operations across Brazil's Mato Grosso with modular header attachments.
- Small:Compact footprints navigate terraced rice paddies in Vietnam and Indonesia where transport corridor width limits machine dimensions.
Volume dominance: Large. Fastest climb: Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for combine harvesters concentrates in grain belts where precision agriculture adoption and fleet replacement cycles intersect with regulatory pressure on engine emissions and cab climate systems.
United States
Iowa and Illinois cooperatives managing 10,000-plus acre operations drive replacement demand toward RTK-guided autosteering platforms. The EPA enforces Tier-4 Final emission limits on diesel engines above 56 kW, forcing turbocharger redesigns that add cost and service complexity. Kansas and Nebraska operators retrofit 2018-2020 machines with LiDAR-based obstacle detection kits, creating a secondary hardware market alongside OEM integrated systems.
Brazil
Cerrado operators facing weight restrictions on transport corridors prioritize lighter high-strength steel chassis and GPS-integrated fleet management for logistics optimization. ANVISA and national agricultural machinery safety protocols govern electromagnetic compatibility for precision-agriculture-equipped models. Mato Grosso mixed-crop operations demand versatile medium-size configurations with modular header attachments for rapid crop-change capability.
Germany
Fleet operators under EU fleet decarbonization mandates pull demand toward hybrid dual-power architectures blending diesel and electric auxiliary systems. The EU F-Gas Regulation and REACH chemical restrictions govern refrigerants in cab climate systems and hydraulic fluid formulations, creating compliance barriers for non-European exporters. Bavaria and Lower Saxony foundries concentrate premium alloy casting capacity for threshing cylinders, exposing supply chains to energy price volatility.
India
Punjab and Haryana state agricultural departments aggregate 200-plus unit tenders, displacing individual farm purchases across the Indo-Gangetic Plain. The CEA and BIS certification requirements for agricultural machinery safety and electromagnetic compatibility add 8-12 month approval timelines for GPS and telemetry-equipped models. Northwestern grain belt cooperative procurement now accounts for 40 percent of annual combine placements.
Ukraine
Post-conflict agricultural recovery will require 15,000-20,000 unit replacements, creating a concentrated procurement window for manufacturers with established Black Sea distribution. National safety and environmental regulations align with EU approximation standards for machinery certification. Odessa and Dnipro industrial corridors position for reconstruction-era fleet modernization as grain export infrastructure rebuilds.
Combine Harvesters Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers scale foundry networks and precision-agriculture R&D to capture fleet replacement cycles. The vendor base clusters around three strategic archetypes: integrated powertrain specialists controlling alloy sourcing through captive foundries, modular frame architects accommodating regional crop profiles without full redesign, and precision-technology platform vendors leveraging sensor fusion and edge computing. M&A activity concentrates on precision-agriculture software assets, while geographic expansion targets Ukraine reconstruction demand and Indo-Gangetic Plain cooperative procurement channels.
Within the integrated powertrain tier, Deere & Company and CNH Industrial N.V. exemplify manufacturers leveraging foundry networks and precision-agriculture divisions to anchor North American and European supply respectively. AGCO Corporation occupies a position among modular frame architects competing on regional adaptability. These three represent the dominant competitive anchors shaping technology licensing and distribution alliance patterns across grain belt markets.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Kubota Corporation |
| Mahindra & Mahindra Limited |
| SDF S.p.A. |
| Iseki & Co., Ltd |
| Yanmar Holdings Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EPA Tier-4 Final certification creates a sharp bifurcation between emission-compliant premium machines and pre-2015 legacy units, with this compliance ladder simultaneously inflating factory pricing and concentrating supply chain leverage among foundry operators controlling high-strength alloy casting capacity. The divergence manifests in procurement patterns across the US Corn Belt, where cooperatives absorb Tier-4 premiums while Eastern European operators delay replacement, stretching service networks and reshaping parts demand.
Pricing Analysis
Volume concentration in standard self-propelled configurations compresses margins, while specialty rice and corn threshing geometries command premium positioning through tropical belt scarcity. Price differentiation rests on emission certification grade and RTK precision tier, with after-treatment systems adding substantial cost to mid-range units. Pricing pressure stems from Tier-4 compliance costs flowing downstream to fleet operators. Individual farmers in fragmented land-holding regions exhibit highest price sensitivity, whereas large-scale enterprises managing 10,000-plus acre operations prioritize technology integration over acquisition cost.
Supply Chain Analysis
Remanufacturing flows for 2018-2020 model year machines create secondary parts markets alongside OEM channels, with LiDAR retrofit kits and precision-agriculture hardware extending serviceable lifecycles. Foundry capacity clusters in Germany and Japan for premium alloy threshing cylinders, while high-strength steel chassis sourcing concentrates in North American and European mill networks. Raw material dependencies center on specialized steel alloys, hydraulic fluid formulations, and refrigerant compounds. Single-source vulnerability in precision casting exposes supply chains to energy price volatility. Distribution runs through dealer networks with captive service capabilities across grain belt regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The combine harvester market is becoming a vertical-integration race, with manufacturers pursuing backward control over alloy foundries and precision-agriculture software assets to defend margin pools against component cost inflation.
For Market Incumbents: Hedge Tier-4 after-treatment cost exposure through captive foundry expansion in Germany and Japan, while consolidating Raven-style precision-agriculture divisions to lock sensor-integrated platform differentiation against modular frame competitors. For New Entrants and Emerging Players: India's CEA certification protocols in the Indo-Gangetic Plain open a window for domestic assembly partnerships that bypass 8-12 month electromagnetic compatibility timelines, targeting state cooperative procurement channels with simplified telemetry architectures. For Investors and Strategic Acquirers: Re-rating potential sits with precision-technology platform vendors given fleet replacement cycles compressing toward sensor-integrated architectures. Long-term viability favors acquisition targets with edge-computing grain assessment and CAN-bus telemetry capabilities. Practitioners should monitor Ukraine reconstruction tender announcements and Indo-Gangetic Plain state procurement aggregations for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive alloy casting in Germany and Japan insulates against energy price volatility in threshing cylinder supply. |
| Precision-Agriculture Acquisition | Sensor fusion and RTK guidance assets consolidate platform differentiation for large-scale cooperative customers. |
| Hybrid Powertrain Development | Dual-power architectures address EU fleet decarbonization mandates in German and French operator bases. |
| Rice-Specific Configuration Launch | Modified rotor geometries unlock premium pricing in Vietnam and Indonesia cooperative channels. |
| Ukraine Distribution Partnership | Black Sea network positioning captures post-conflict reconstruction demand for 15,000-20,000 unit replacements. |
Research Approach
Document review covered EPA Tier-4 Final filings, EU F-Gas Regulation compliance databases, and Indian CEA certification records, complemented by interviews with fleet operations managers at Iowa and Illinois cooperatives, maintenance directors at Brazilian Cerrado enterprises, and procurement leads at Punjab and Haryana state agricultural departments. Secondary validation drew from machinery registration data, foundry capacity disclosures, and cooperative tender aggregations. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Cross-referencing historical replacement cycle patterns against expert panel input on precision-agriculture adoption curves shaped the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-user scale, and machine size across regional crop profiles. CAGRs derived from fitted growth curves incorporating fleet age distributions and regulatory compliance deadlines. Industry-specific inputs encompassed Tier-4 engine redesign cost pass-through rates and RTK autosteering penetration thresholds.
Caveats apply where EPA enforcement intensity, EU REACH chemical restriction scope, or India CEA certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions on cooperative procurement consolidation rates and Ukraine reconstruction pacing. Practitioners should monitor Black Sea grain export infrastructure rebuilds and Indo-Gangetic Plain state tender aggregations for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Meat Dicing Machine Market