
 Video Content Management Market | 2026-2036
Video Content Management Market Size, Share, and Industry Trends Forecast 2026-2036
Video Content Management Market Outlook
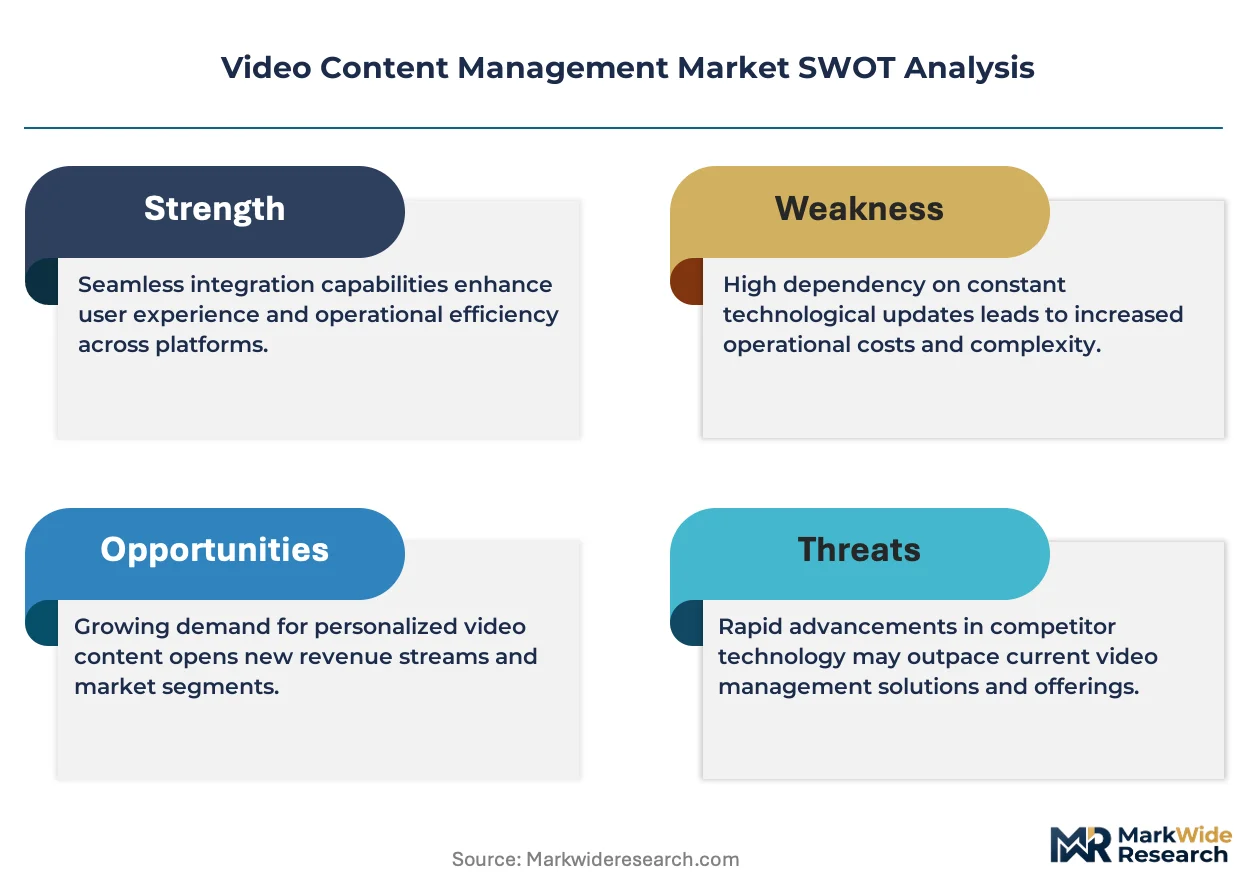
Enterprise-grade 4K streaming with real-time analytics is redrawing competitive boundaries in video content management. Brightcove Inc. leverages its global CDN footprint to serve broadcasters with low-latency delivery. Kaltura, Inc. anchors the education vertical through its open-source extensibility and campus-wide deployment architecture. Microsoft Corporation dominates enterprise video through native Teams integration and SharePoint-connected governance tools.
Video content management encompasses software platforms that ingest, transcode, store, distribute, and analyze video assets across organizational workflows, typically supporting H.265/HEVC compression, adaptive bitrate streaming, and automated speech-to-text indexing for searchability. Cloud-based solutions lead deployment preferences as IT departments trade capital expenditure for elastic storage scaling and API-driven integration with CRM and LMS ecosystems. Hybrid solutions capture growing interest from financial services and healthcare buyers seeking on-premises encryption key control alongside burst capacity to public cloud nodes.
FCC guidelines on closed captioning and accessibility shape product roadmaps for North American vendors, while GDPR and the EU AI Act constrain automated facial recognition and biometric indexing features across European deployments. Japan's METI promotes 8K broadcast standards that cascade into archival and management requirements for content libraries. Stakeholders must weigh sovereignty mandates against cloud economics when selecting deployment architecture for multi-national video estates.
Market Dynamics
Cloud-native transcoding pipelines are compressing time-to-publish from days to minutes, forcing legacy on-premise vendors to accelerate API-first refactoring or cede enterprise accounts to elastic infrastructure providers.
Growth Catalysts
- AI-powered metadata extraction:Automated speech-to-text and object recognition from AWS, Google Cloud, and Azure are slashing manual tagging costs for media archives. Broadcasters in Germany deploy these tools to meet public-service accessibility mandates.
- FCC closed-captioning enforcement:US educational institutions and streaming platforms face penalties for non-compliance, driving procurement of integrated captioning workflows within video management suites.
- Japan's 8K broadcast infrastructure:METI-funded trials for NHK and commercial broadcasters are generating petabyte-scale archival demands that require specialized compression and tiered storage management.
Market Restraints
- Cloud egress cost volatility:Unpredictable bandwidth charges from hyperscale providers erode the opex advantage of cloud migration for high-volume streaming workloads.
- Concentrated encoding ASIC supply:NVIDIA and Intel dominate hardware-accelerated transcoding, creating single-source risk for vendors building performance-dependent pipelines.
- GDPR biometric indexing limits:The EU AI Act restricts automated facial recognition in video archives, forcing European deployments to disable features standard in North American configurations.
Strategic Opportunities
- India's ed-tech procurement wave:Byju's, Unacademy, and government DIKSHA deployments are creating demand for low-bandwidth adaptive streaming optimized for 2G/3G networks.
- Healthcare surgical video capture:Operating room integration with HIPAA-compliant annotation and teaching library management remains underpenetrated relative to enterprise communications.
- Edge-compute and 5G convergence:Low-latency live production without central cloud round-trips enables new remote broadcast and esports tournament workflows.
Industry Challenges
- Specialized DevOps talent scarcity:Organizations struggle to hire engineers fluent in HLS/DASH packaging, CDN failover orchestration, and multi-cloud Kubernetes deployment.
- Interoperability with decades-old broadcast hardware:SDI-to-IP gateway complexity and proprietary codec licensing create friction in hybrid modernization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Content Management Market |
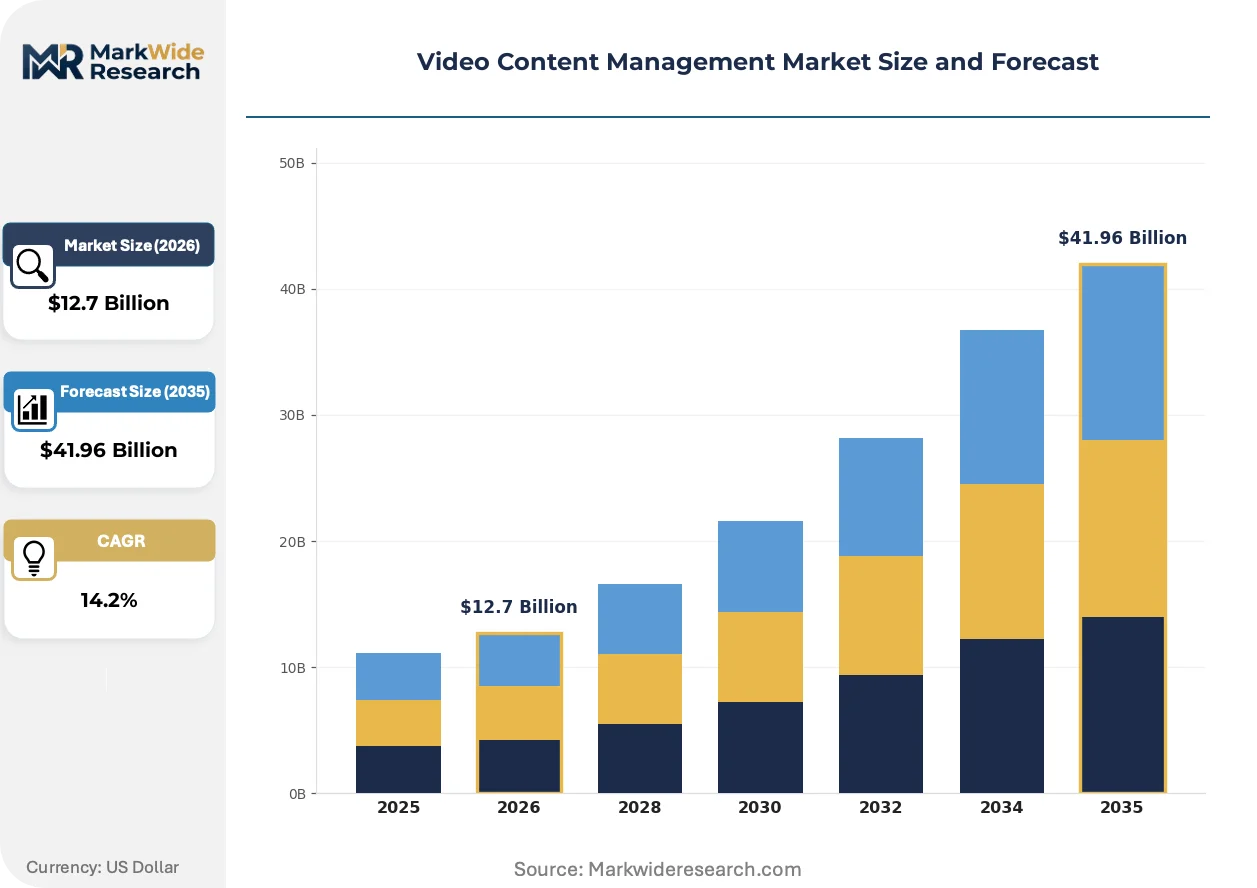
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises Solutions, Cloud-Based Solutions, Hybrid Solutions, Open-Source Platforms End User: Media Companies, Enterprises, Educational Institutions, Government Agencies Deployment: Public Cloud, Private Cloud, On-Premises, Hybrid Cloud Integration Level: API Integration, Native Integration, Custom Solutions, Third-Party Integration |
| Companies Covered | Brightcove Inc., Kaltura, Inc., IBM Corporation, Vimeo, Inc., Panopto, Inc., Microsoft Corporation, Wistia, Inc., JW Player LLC, Vidyard Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Content Management Market Strategic Shifts
Generative AI is rewriting content discovery and personalization workflows, while regulatory fragmentation across jurisdictions forces product teams to maintain parallel compliance tracks. These forces are compressing vendor R&D cycles and reshaping buyer evaluation criteria.
Edge-based inferencing for real-time content moderation is fragmenting the traditional cloud-centralized analytics architecture. Sports broadcasters and live event producers deploy GPU-equipped regional nodes to flag policy violations within sub-second latency windows. This distributed topology is fragmenting procurement patterns, with buyers now evaluating edge hardware vendors alongside software platform providers.
The EU AI Act's risk-classification framework for biometric identification systems is forcing European deployments to segregate feature sets by geography. Vendors must maintain dual codebases: full-capability stacks for North American clients and constrained versions for EU data estates. Healthcare and law enforcement verticals in France and Germany face the steepest compliance redesign timelines.
Subscription fatigue among enterprise buyers is compressing vendor sales cycles and elevating proof-of-concept requirements. Procurement committees now demand 90-day pilots with measurable engagement analytics before multi-year commitments. This behavior is most pronounced in US financial services, where compliance officers scrutinize data residency claims through independent penetration testing.
Video Content Management Market Segmentation
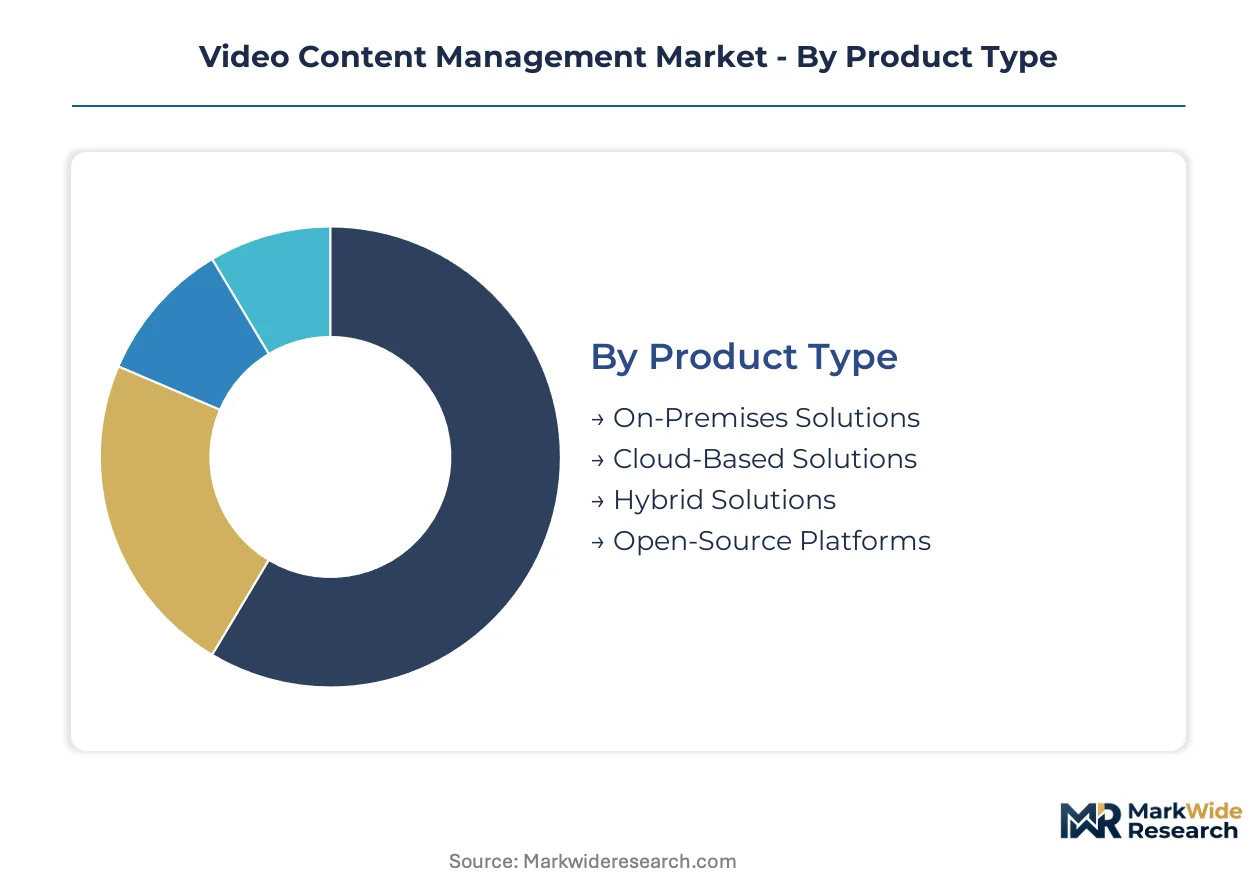
Segmentation in video content management reflects divergent buyer risk appetites for data sovereignty, cloud economics, and workflow integration depth. Procurement committees evaluate these dimensions simultaneously, creating complex cross-category trade-offs between compliance posture and operational agility.
Product Type:
Substitution pressure runs strongest against on-premise incumbents as elastic infrastructure commoditizes transcoding and storage functions.
- Cloud-Based Solutions:Multi-tenant architectures with API-driven orchestration enable burst scaling for live events without capital commitment. Media companies in Germany deploy these for public-service broadcasting mandates where peak concurrency demands exceed baseline infrastructure.
- Hybrid Solutions:Split architectures retain encryption key control on-premises while leveraging public cloud nodes for peak transcoding workloads. Financial services buyers in the United States favor this model for HIPAA and SOX compliance alongside elastic capacity.
- On-Premises Solutions:Single-tenant deployments with dedicated hardware for organizations with strict data residency requirements.
- Open-Source Platforms:Community-maintained codebases with extensible plugin architectures for education and non-profit budgets.
Cloud-Based Solutions anchors the volume base while Hybrid Solutions gains share at the steepest rate.
End User:
Cost tier stratification separates enterprise buyers with dedicated procurement teams from institutional segments with committee-driven evaluation cycles.
- Enterprises:Global deployments with unified communications integration, governance tooling, and analytics dashboards spanning tens of thousands of seats. Microsoft Teams-native workflows drive consolidation decisions in the United States.
- Educational Institutions:Campus-wide learning management system integration with accessibility compliance and lecture capture automation. K-12 districts and universities in Japan prioritize 8K archival readiness for future broadcast standards.
- Media Companies:Broadcasters and streaming platforms with real-time transcoding pipelines and multi-CDN failover requirements.
- Government Agencies:Classified and unclassified video estates with FedRAMP or equivalent certification mandates.
Enterprises dominate current procurement volume while Educational Institutions expand most quickly across emerging economies.
Deployment:
Customer type alignment shapes infrastructure choices, with regulated industries resisting full public cloud migration despite cost advantages.
- Public Cloud:Shared infrastructure with consumption-based billing and automatic software updates. Startups and mid-market media firms favor this for zero upfront capital requirements.
- Private Cloud:Dedicated single-tenant environments within hyperscale data centers, offering isolation without on-premises hardware ownership. Healthcare networks in Germany deploy these for GDPR-compliant surgical video archives.
- On-Premises:Buyer-operated data centers with full hardware control and customized security postures.
- Hybrid Cloud:Orchestrated workload portability between private and public nodes based on sensitivity and cost optimization.
Public Cloud carries the largest installed base while Hybrid Cloud climbs the fastest as sovereignty requirements harden.
Integration Level:
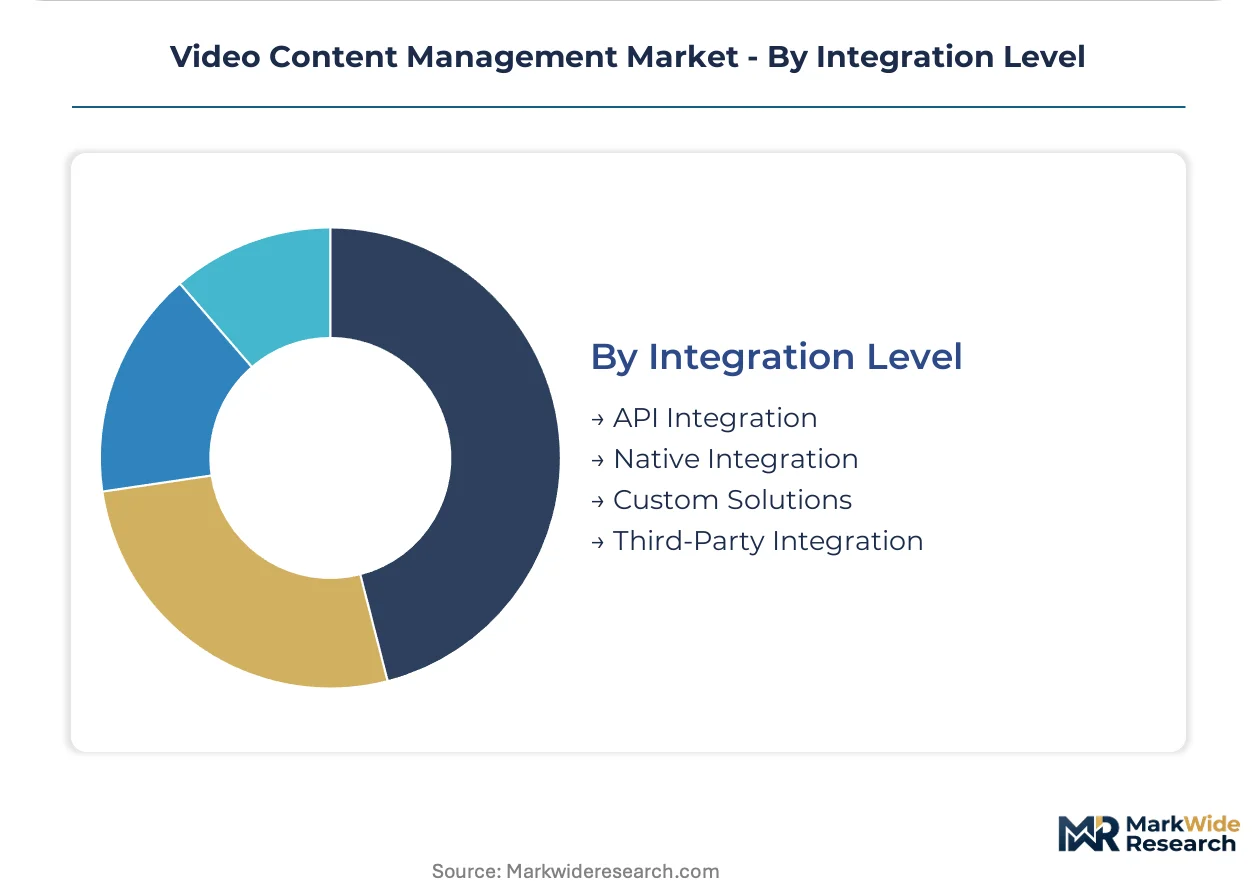
Supply concentration in API-first vendors is displacing custom development shops as standardized connectors proliferate across CRM, LMS, and collaboration ecosystems.
- API Integration:RESTful and GraphQL endpoints enabling programmatic workflow automation and data exchange with external systems. Developer-centric buyers in the United States prioritize OpenAPI specification completeness.
- Native Integration:Pre-built connectors for specific platforms like Salesforce, Canvas, or Slack without custom code requirements.
- Third-Party Integration:Middleware-dependent connections through integration-platform-as-a-service providers.
- Custom Solutions:Bespoke development for unique workflow requirements or legacy system interoperability.
API Integration represents the dominant procurement specification while Native Integration shortens sales cycles most effectively for mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export intensity in video content management platforms runs highest from US-based hyperscale providers, while import dependency concentrates in emerging economies modernizing legacy broadcast infrastructure. Trade flows in cloud transcoding services and edge-compute hardware shape regional procurement patterns.
United States
FCC closed-captioning enforcement drives compliance-focused procurement across educational streaming platforms and broadcasters. HIPAA and SOX frameworks constrain hybrid cloud architectures for healthcare and financial services buyers. Silicon Valley clusters anchor AI-powered metadata extraction development, with Seattle-based hyperscalers dominating enterprise integration pipelines.
Germany
Public-service broadcasting mandates from ARD and ZDF generate sustained demand for 8K-ready archival systems. GDPR and the EU AI Act restrict biometric indexing features, forcing deployment of constrained codebases. Berlin and Munich host concentrated vendor development centers serving Central European media modernization projects.
Japan
METI-funded 8K broadcast trials for NHK cascade into petabyte-scale content library management requirements. JIS standards compliance shapes compression and tiered storage specifications for commercial broadcasters. Tokyo-Osaka corridor concentrates domestic platform development alongside broadcast equipment manufacturing clusters.
India
Ed-tech procurement from Byju's, Unacademy, and government DIKSHA deployments drives demand for low-bandwidth adaptive streaming. TRAI regulations on data localization influence cloud architecture decisions for multinational platform providers. Bangalore and Hyderabad anchor domestic development centers optimizing codecs for 2G/3G network conditions.
United Kingdom
BBC charter renewal commitments to digital-first distribution reshape public broadcaster procurement priorities. Ofcom accessibility mandates align with FCC-equivalent captioning requirements for streaming services. London media technology clusters specialize in financial services video governance tooling and compliance-heavy enterprise deployments.
Video Content Management Market Competitive Environment
Concentration sits with hyperscale cloud providers integrating video management into unified communications stacks. The vendor base spans three tiers: broadcast-specialist platforms with global CDN footprints, education-anchored open-source extensible systems, and enterprise productivity-suite native offerings. Strategic moves center on API-first refactoring of legacy transcoding pipelines and edge-compute partnership structures for sub-second latency workflows.
Within the broadcast-specialist tier, Brightcove Inc. and Kaltura, Inc. exemplify divergent vertical anchoring strategies. Brightcove represents the global CDN-integrated delivery archetype serving low-latency requirements, while Kaltura occupies the education-vertical position through campus-wide deployment architectures. Microsoft Corporation anchors the enterprise-productivity integration vector, with native Teams connectivity and SharePoint-governed video estates consolidating procurement decisions in regulated industries.
| Leading Market Players |
|---|
| Brightcove Inc. |
| Kaltura, Inc. |
| IBM Corporation |
| Vimeo, Inc. |
| Panopto, Inc. |
| Microsoft Corporation |
| Wistia, Inc. |
| JW Player LLC |
| Vidyard Inc. |
| Others |
Value Chain & Pricing Dynamics
GPU-accelerated transcoding ASICs from NVIDIA and Intel displacing software-based encoding simultaneously concentrates supply geography in Taiwan and South Korea foundries while compressing per-stream pricing economics for cloud-native vendors competing against hyperscale in-house development.
Pricing Analysis
Enterprise procurement teams anchor SaaS-tiered subscription structures with consumption-scaled tiers. Pricing stratifies across premium enterprise-grade SLAs, standard multi-tenant deployments, and economy self-service tiers differentiated by API call volume and storage retention policies. Cost compression in the economy tier intensifies because hyperscale providers bundle video management into unified communications suites at marginal cost. Educational institutions exhibit highest price sensitivity due to budget committee oversight, while financial services buyers prioritize compliance-grade SLAs over unit economics.
Supply Chain Analysis
Inventory cycles for encoding hardware stretch 16-24 weeks following semiconductor foundry allocation decisions. Supply concentrates in Taiwan and South Korea for GPU and ASIC fabrication, with secondary packaging and testing in Malaysia and Vietnam. Raw material dependencies span silicon wafers, HBM memory modules, and specialized cooling substrates. Single-source vulnerability runs through NVIDIA's dominant position in AI-accelerated transcoding chips. Distribution runs through direct hyperscale procurement contracts and OEM channel partnerships serving mid-market software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise video infrastructure spending follows cyclical IT refresh patterns, with current expansion driven by post-pandemic hybrid work permanence forcing legacy system replacement.
For Market Incumbents: Consolidate API-first platform architectures to defend against hyperscale bundling. Acquire edge-compute hardware partnerships to preserve latency advantages in live broadcast workflows. Deepen SharePoint and Teams integration moats against best-of-breed disintermediation. For New Entrants and Emerging Players: Healthcare surgical video capture with HIPAA-compliant annotation layers represents an under-served service gap where incumbents lack vertical-specific workflow depth. Target mid-tier hospital networks in Germany and Japan with native DICOM integration and teaching library management as the go-to-market wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed education-software platforms holding campus deployment contracts but lacking cloud-native transcoding capabilities. Five-to-ten year viability hinges on AI metadata extraction differentiation. Watch for FCC accessibility enforcement acceleration as inflection signal for compliance-tooling acquisition demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Compute Partnership Structure | GPU-equipped regional nodes enable sub-second content moderation for live sports broadcasters. |
| API-First Platform Refactoring | RESTful orchestration layers displace legacy on-premise transcoding pipelines in enterprise accounts. |
| Vertical Compliance Certification | FedRAMP and HIPAA attestations unlock government and healthcare procurement committees. |
| AI Metadata Extraction Integration | Automated speech-to-text indexing from AWS and Azure reduces manual tagging costs for German public broadcasters. |
| Hybrid Cloud Architecture Deployment | On-premises encryption key control with burst cloud capacity addresses financial services sovereignty requirements. |
Study Parameters
Cross-validation between primary interviews with platform engineering directors and secondary validation through hyperscaler capex disclosures anchors the qualitative findings. Conversations with CTOs, IT procurement officers, LMS integration specialists, and broadcast technology consultants informed workflow prioritization. Secondary sources include SEC 10-K filings, FCC enforcement action records, METI 8K infrastructure grant announcements, and EU AI Act implementation guidance. Bottom-up deployment modeling triangulates against top-down enterprise software spending benchmarks.
Sensitivity analysis across cloud egress cost volatility scenarios and encoding hardware supply constraints shapes the projection framework. Segmentation dimensions span deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and infrastructure replacement cycles. Forecast inputs include AI-powered metadata extraction penetration rates and 8K broadcast readiness investment timelines.
Underlying assumptions cover sustained cloud migration momentum and stable hyperscale pricing discipline, with deviation risk concentrated in semiconductor supply disruptions and biometric indexing regulatory expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Video Player Market
Digital Media
Mobile Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Digital Content Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Video Wall Market
Digital Media
Indonesia Digital Media Market
Digital Media
Animation and VFX Market
Digital Media
Anime Market
Digital Media
Projection Mapping Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
VFX Market
Digital Media
Online Entertainment Market
Digital Media
Digital Music Services Market
Digital Media
Music Rights Management Market