
 Europe Inflight Entertainment and Connectivity Market | 2026-2036
Europe Inflight Entertainment and Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Inflight Entertainment and Connectivity Market Foresight
Satellite-to-cabin broadband integration is reshaping how European airlines deliver media and real-time services to passengers. Thales SA leverages its avionics heritage to anchor premium seatback installations across Air France-KLM and British Airways fleets. Viasat Inc. competes aggressively on Ka-band capacity, while Lufthansa Systems sustains software dominance through its BoardConnect streaming platform deployed on Eurowings and Austrian Airlines.
Europe Inflight Entertainment and Connectivity encompasses hardware, software, and network services that deliver audio-visual content and internet access to aircraft occupants during flight. Systems typically operate through L-band, Ku-band, or Ka-band satellite links with terminal weights between 5-25 kg and latency thresholds under 500 milliseconds for acceptable streaming quality. Connectivity Solutions command the largest revenue share as airlines prioritize broadband monetization over capital-intensive seatback retrofits, while Wireless IFE grows fastest by allowing carriers to bypass costly seat-embedded screens. Satellite-Based technology leads the technology dimension due to coverage reliability over transatlantic and intra-European routes where Air-To-Ground infrastructure remains patchy.
EASA airworthiness directives and the EU Cybersecurity Act shape hardware certification timelines and data governance standards for connected aircraft systems. The European Commission's Single European Sky ATM Research program indirectly pressures airlines to adopt lighter, more efficient connectivity equipment that reduces fuel burn. National regulators in Germany, France, and Spain enforce country-specific spectrum coordination rules that complicate cross-border fleet standardization. Stakeholders must monitor ETSI 5G-aviation spectrum allocation decisions and airline insourcing tendencies that threaten vendor margins.
Market Dynamics
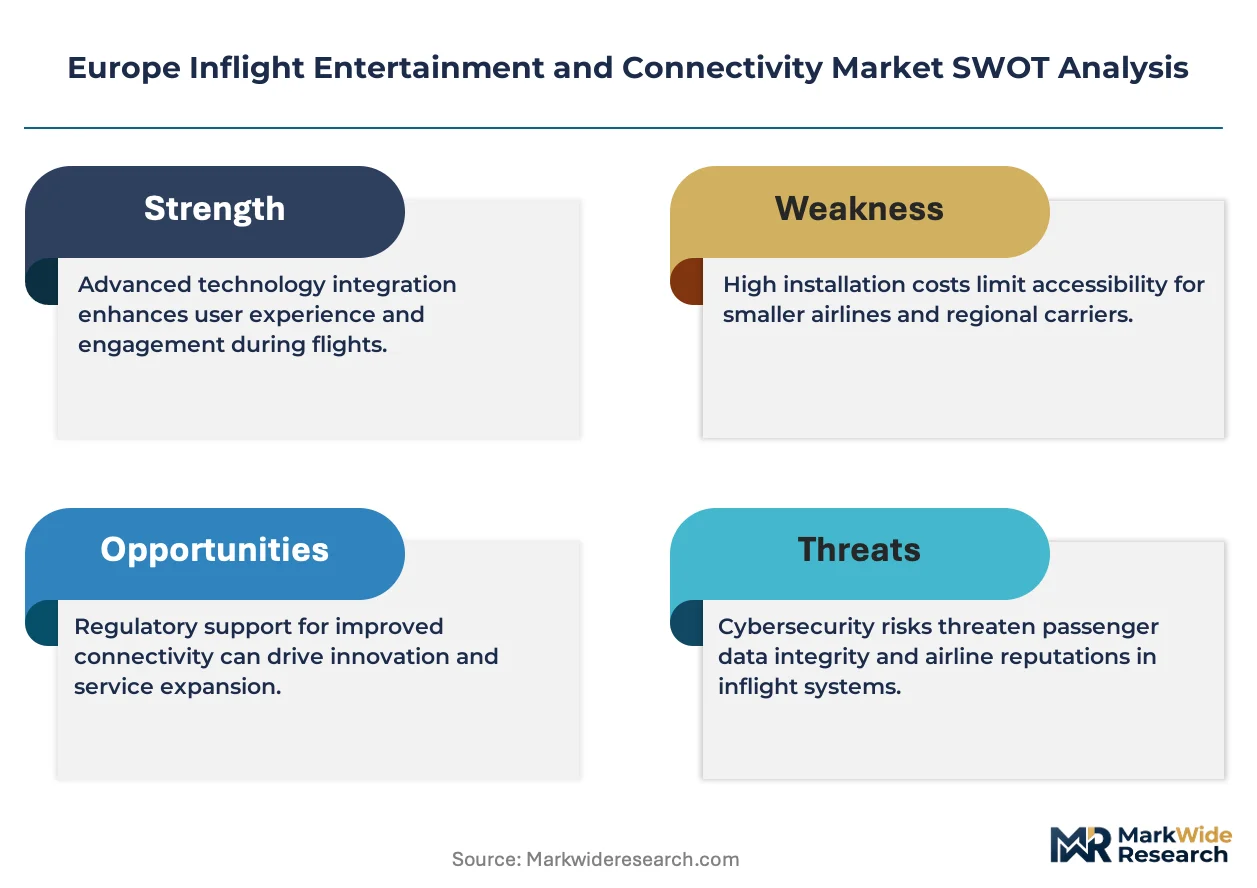
Satellite-to-cabin broadband integration is compressing hardware replacement cycles as European full-service carriers retrofit narrowbody fleets to match long-haul connectivity standards. EASA certification pressure for cybersecurity-hardened avionics is forcing simultaneous upgrades across multiple aircraft systems.
Growth Catalysts
- Fleet Renewal Programs:Germany, France, and the United Kingdom are executing the most active narrowbody and widebody replacement schedules, creating concentrated demand for integrated IFE and connectivity suites.
- EU Cybersecurity Act:Mandated data governance standards for connected aircraft systems are accelerating airline investments in certified, end-to-end encrypted cabin networks.
- Ka-band Satellite Capacity:Expanded orbital coverage over transatlantic corridors is enabling consistent broadband speeds that support streaming-quality passenger experiences.
Market Restraints
- Hardware Certification Timelines:EASA airworthiness directives impose multi-year validation periods for new connectivity terminals, delaying revenue realization for equipment vendors.
- Supply Concentration in Satellite Operators:European airlines depend on a limited orbital infrastructure base, creating pricing power asymmetry in bandwidth procurement negotiations.
- Seatback Screen Cost Structure:Capital-intensive embedded display retrofits face resistance from low-cost carriers pursuing bring-your-own-device strategies.
Strategic Opportunities
- Central and Eastern Europe:Underpenetrated flag carrier fleets in Poland, Hungary, and the Czech Republic present first-mover expansion potential for streaming-platform vendors.
- 5G-aviation Spectrum Allocation:ETSI decisions on terrestrial-airborne network integration could unlock low-latency connectivity for short-haul European routes.
- Software-Defined Cabin Architectures:Convergence of edge computing and lightweight antenna systems is virtualizing traditional hardware stacks, reducing per-aircraft installation mass.
Industry Challenges
- Cross-Border Spectrum Coordination:National regulators in Germany, France, and Spain enforce divergent frequency allocation rules that complicate fleet-wide equipment standardization.
- Integration with Legacy Avionics:Airlines operating mixed-generation fleets face technical friction when connecting modern broadband terminals to aging ARINC 429 data buses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Inflight Entertainment and Connectivity Market |
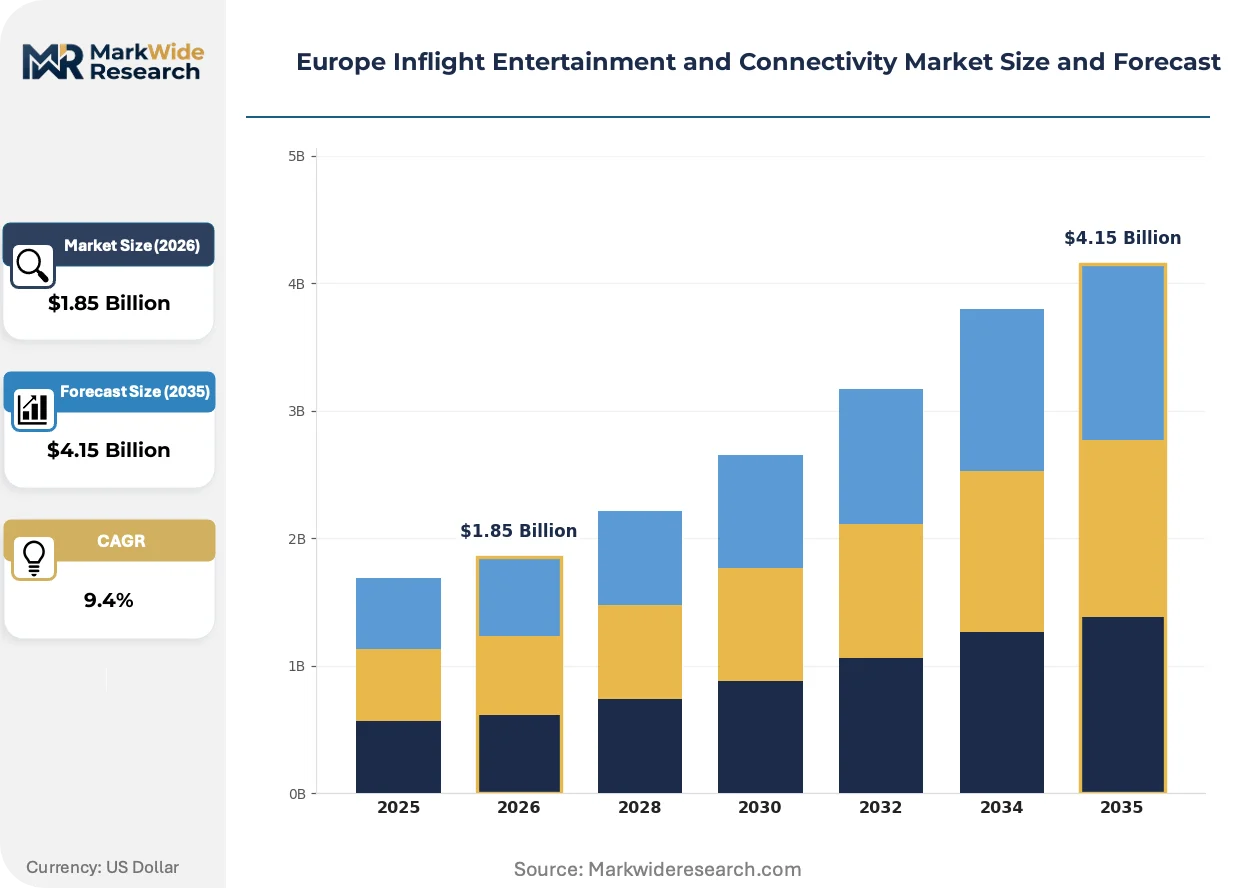
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Seatback Systems, Wireless IFE, Connectivity Solutions Technology: Satellite-Based, Air-To-Ground, Wi-Fi, Bluetooth End User: Commercial Airlines, Business Jets, Cargo Carriers, Government Aircraft Customer Segment: Leisure Travelers, Business Travelers, Travel Agencies, Aviation Partners |
| Companies Covered | Viasat Inc., Lufthansa Systems, Thales SA, Burrana, Immfly, Global Eagle Entertainment Inc., Inmarsat Global Limited, Gogo LLC, Panasonic Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Inflight Entertainment and Connectivity Market Shifts & Advancements
Three intersecting developments are restructuring how European airlines procure, deploy, and monetize cabin connectivity. Technology virtualization, regulatory cybersecurity mandates, and shifting procurement preferences are compressing traditional vendor relationships.
Wireless streaming platforms are virtualizing the seatback screen by shifting video rendering to passenger smartphones and tablets. Lufthansa Group and IAG are deploying server-centric architectures that eliminate embedded displays in short-haul configurations. This compression of hardware dependency is reducing per-seat installation costs while preserving content monetization through app-based portals.
GDPR-aligned data handling requirements under the EU Cybersecurity Act are mandating encryption standards for passenger data transit through satellite ground stations. Airlines must now demonstrate end-to-end data sovereignty across third-party network providers. This regulatory pressure is favoring vendors with European-hosted server infrastructure and EU-based technical support operations.
Airline technical procurement teams are consolidating vendor relationships around full-stack platform providers rather than assembling discrete hardware, software, and bandwidth contracts. British Airways and Air France-KLM have moved toward single-source connectivity agreements covering terminal, network, and content licensing. This concentration of buying authority is squeezing point-solution specialists and rewarding integrated service portfolios.
Europe Inflight Entertainment and Connectivity Market Segmentation
Segmentation in the Europe Inflight Entertainment and Connectivity Market reveals how procurement priorities diverge across hardware, network, and service layers. Airlines select configurations based on fleet age, route structure, and passenger yield profiles.
Product Type:
Cost tier determines how European carriers balance capital expenditure against passenger experience differentiation.
- Streaming Services:Cloud-hosted content platforms deliver licensed media through server-to-device transmission without embedded displays. Demand concentrates in Germany and France where Lufthansa Group and Air France-KLM pursue bring-your-own-device strategies on narrowbody fleets to reduce installation mass.
- Connectivity Solutions:Satellite and air-to-ground broadband terminals enable internet access, messaging, and streaming applications through antenna-to-cabin distribution. Revenue concentrates in transatlantic and intra-European routes where business travelers generate premium ancillary yields.
- Seatback Systems:Embedded screens with integrated control units and wired audio distribution.
- Wireless IFE:Server-centric architectures streaming to passenger devices via onboard Wi-Fi.
Connectivity Solutions commands the established base. The steepest expansion runs through Wireless IFE.
Technology:
Application requirements across route profiles dictate satellite versus terrestrial network selection.
- Satellite-Based:Ku-band and Ka-band links provide coverage over oceanic and remote terrain through geostationary and low-earth-orbit constellations. Deployment concentrates in long-haul fleets operating from London Heathrow and Frankfurt where consistent broadband quality supports paid Wi-Fi monetization.
- Air-To-Ground:Cellular tower connectivity delivers lower latency over landmasses through dedicated aviation spectrum.
- Wi-Fi:IEEE 802.11 standards for cabin distribution to passenger devices.
- Bluetooth:Short-range pairing for personal audio accessories and crew communication.
Satellite-Based technology anchors installed capacity. The fastest share gains are occurring in Air-To-Ground as European terrestrial networks densify.
End User:
Customer type shapes contract structure from multi-year fleet agreements to single-aircraft installations.
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger services with fleet-wide standardization requirements. Procurement concentrates in the United Kingdom, Germany, and France where IAG, Lufthansa Group, and Air France-KLM execute coordinated retrofit programs.
- Business Jets:Corporate and charter operators prioritizing lightweight, discrete installations.
- Cargo Carriers:Freighter operators deploying crew welfare connectivity on long-haul routes.
- Government Aircraft:State and military fleets with hardened security and sovereign network requirements.
Commercial Airlines represents the revenue foundation. Business Jets is climbing the fastest as fractional ownership expands.
Customer Segment:
Volume concentration among passenger yield tiers determines how airlines package and price connectivity offerings.
- Leisure Travelers:Price-sensitive passengers accessing ad-supported or basic-tier connectivity on holiday routes. Demand concentrates in Spanish and Italian leisure markets where Vueling and ITA Airways monetize through sponsored content models.
- Business Travelers:Premium passengers requiring guaranteed bandwidth for video conferencing and cloud applications.
- Travel Agencies:Intermediaries bundling connectivity into corporate travel contracts.
- Aviation Partners:Codeshare and alliance carriers integrating network roaming across fleets.
Leisure Travelers delivers the volume base. Business Travelers generates the steepest yield expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German connectivity hardware exports supply retrofit programs across British and French airline fleets. Transatlantic corridor traffic generates concentrated demand for satellite bandwidth procurement from London Heathrow and Frankfurt hubs.
Germany
Lufthansa Group's narrowbody fleet renewal drives integrated IFE suite procurement. The EU Cybersecurity Act mandates end-to-end encryption for passenger data transit through satellite ground stations. Munich and Hamburg host technical operations centers where Lufthansa Systems maintains its BoardConnect streaming platform development.
United Kingdom
British Airways and Virgin Atlantic execute coordinated widebody connectivity upgrades for transatlantic routes. EASA certification timelines for cybersecurity-hardened avionics compress equipment replacement cycles. London Heathrow anchors the region's satellite bandwidth demand concentration, with Gatwick supporting low-cost carrier streaming deployments.
France
Air France-KLM pursues premium seatback installations across long-haul fleets to differentiate passenger experience. The EU Green Deal pressures adoption of lighter connectivity equipment to reduce fuel burn. Toulouse hosts Thales SA avionics engineering operations supporting airline retrofit programs.
Spain
Vueling and ITA Airways monetize connectivity through ad-supported content models on leisure routes. National spectrum coordination rules complicate cross-border fleet standardization with French and German operations. Barcelona and Madrid concentrate low-cost carrier technical procurement decisions for bring-your-own-device strategies.
Poland
LOT Polish Airlines represents underpenetrated flag carrier demand for first-mover streaming platform expansion. ETSI 5G-aviation spectrum allocation decisions pending at EU level could unlock terrestrial connectivity for short-haul routes. Warsaw anchors Central European airline procurement negotiations with satellite operators.
Europe Inflight Entertainment and Connectivity Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement influence across European airline technical teams. The vendor base organizes around three strategic archetypes: full-stack platform providers bundling hardware, network, and content; satellite bandwidth specialists supplying orbital capacity; and software-centric streaming vendors virtualizing seatback infrastructure. Consolidation pressure favors integrated service portfolios over point-solution contracts. Dominant competitive moves include strategic partnerships between hardware manufacturers and satellite operators, plus geographic expansion into underpenetrated Central and Eastern European flag carriers.
Within the full-stack platform tier, Thales SA and Viasat Inc. occupy positions representing divergent technical approaches to cabin connectivity deployment. Lufthansa Systems GmbH anchors the software-centric streaming archetype through its server-to-device platform architecture. These three entities exemplify how European airline procurement teams are consolidating vendor relationships around comprehensive capability sets rather than assembling discrete hardware, network, and content licensing contracts.
| Leading Market Players |
|---|
| Viasat Inc. |
| Lufthansa Systems |
| Thales SA |
| Burrana |
| Immfly |
| Global Eagle Entertainment Inc. |
| Inmarsat Global Limited |
| Gogo LLC |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Frankfurt-to-London freight corridors carry Ka-band satellite terminals and lightweight antenna assemblies from German manufacturing hubs to British airline retrofit facilities, with logistics costs feeding directly into equipment pricing tiers and procurement contract structures across European full-service carriers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate satellite terminal procurement, with L-band and Ku-band hardware pricing tethered to semiconductor wafer and aluminum alloy commodity benchmarks. Price differentiation separates EASA-certified cybersecurity-hardened avionics from standard commercial-grade equipment, while volume scale discounts apply to fleet-wide retrofit programs. Pricing pressure stems from airline consolidation of vendor relationships around full-stack platform providers. Low-cost carriers exhibit highest price sensitivity, prioritizing bring-your-own-device streaming over capital-intensive seatback installations.
Supply Chain Analysis
Upstream feedstock for cabin connectivity hardware draws from semiconductor fabrication in Germany, France, and the Netherlands, alongside precision aluminum machining in Italy and Switzerland. Critical component dependencies include gallium nitride RF chips, phased-array antenna substrates, and avionics-grade cabling. Single-source vulnerability concentrates in geostationary satellite transponder leasing from limited orbital infrastructure operators. Distribution runs through authorized avionics distributors serving airline technical procurement teams, with direct OEM relationships gaining share for integrated platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Inflight Entertainment and Connectivity represents a high-growth disruption as EASA cybersecurity mandates and Ka-band satellite capacity expansion compress equipment replacement cycles across narrowbody and widebody fleets.
For Market Incumbents: Insulate installed base relationships by embedding software-defined cabin architectures that virtualize hardware stacks and reduce per-aircraft installation mass. Deepen backward integration into satellite bandwidth procurement to counter pricing power asymmetry with orbital infrastructure operators. Prioritize certification investment for EU Cybersecurity Act compliance as a competitive moat against uncertified challengers.
For New Entrants and Emerging Players: Central and Eastern European flag carrier fleets in Poland, Hungary, and the Czech Republic present first-mover streaming platform expansion opportunities with limited incumbent penetration. Target business jet fractional ownership segments climbing fastest on connectivity demand. Pursue go-to-market angles through lightweight server-centric architectures that bypass seatback screen capital expenditure resistance.
For Investors and Strategic Acquirers: Software-centric streaming vendors with European-hosted server infrastructure and GDPR-aligned data sovereignty capabilities offer compelling acquisition profiles. Long-term viability hinges on differentiation through regulatory compliance rather than hardware commodity positioning. Monitor ETSI 5G-aviation spectrum allocation decisions as an inflection indicator for terrestrial-airborne network integration opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Bandwidth Backward Integration | Captures pricing power from concentrated orbital infrastructure operators serving transatlantic routes. |
| Software-Defined Cabin Architecture Launch | Virtualizes seatback hardware through edge computing and lightweight antenna systems at Lufthansa Systems. |
| EASA Cybersecurity Certification Investment | Accelerates equipment replacement cycles through mandated end-to-end encryption standards under EU Cybersecurity Act. |
| Central European Geographic Expansion | Targets underpenetrated flag carrier fleets in Poland and Czech Republic for streaming platform deployment. |
| Airline Technical Procurement Partnership | Consolidates vendor relationships around full-stack platform providers at British Airways and Air France-KLM. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with airline technical procurement directors, avionics engineering leads, satellite operator bandwidth sales executives, and EASA certification specialists; alongside secondary validation through EASA airworthiness directives, EU Cybersecurity Act implementation guidance, airline fleet renewal announcements, and satellite operator coverage maps. Bottom-up equipment installation forecasts triangulated against top-down market sizing from connectivity revenue disclosures.
Forecast inputs considered hardware replacement cycles, fleet renewal schedules, and regulatory certification timelines across the projection horizon. Segmentation dimensions modeled include product type, technology band, end-user category, and customer yield tier. CAGRs derived from equipment installation run rates and connectivity revenue per passenger metrics, with EASA directive implementation schedules and Ka-band satellite launch timelines as industry-specific forecast inputs.
Practitioners should monitor ETSI spectrum allocation proceedings, airline insourcing tendencies, and satellite operator merger activity for early signals of forecast revision. Cross-checking against airline capital expenditure disclosures and fleet retrofit announcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Information Short Video Market
Digital Media
Sports Graphics Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Global Transport Media Market
Digital Media
Anime Streaming Tool Market
Digital Media
Da Vinci Systems Market
Digital Media
3D Animation Market
Digital Media
Digital Video Advertising Market
Digital Media
US Webtoons Market
Digital Media
Global Music Video Production Market
Digital Media
Pro AV Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
Webtoons Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
China Webtoons Market