
 Animation and VFX Market | 2026-2036
Animation and VFX Market Size, Share, and Industry Trends Forecast 2026-2036
Animation and VFX Market Analysis
Capital-intensity divergence between proprietary render farm operators and cloud-reliant studios is bifurcating competitive tiers. Industrial Light & Magic sustains in-house infrastructure for blockbuster franchise workloads. DNEG Group leverages cloud-distributed pipelines to scale capacity across concurrent productions. Pixar Animation Studios anchors its position through proprietary software ecosystems and decades of character-animation IP development.
Animation and VFX encompasses the creation of moving imagery through digital or hand-crafted techniques, combining computer-generated imagery, motion capture data, and compositing layers to produce photorealistic or stylized visuals for entertainment and commercial purposes. The application dimension shows film and television commanding established budget pools while video games absorb expanding real-time rendering investment. Technology segmentation reveals 3D modeling and motion capture as mature margin centers, whereas CGI pipelines for virtual production stages represent the fastest capability expansion. Service type dynamics place post-production and visual effects design as the highest-value capture points given client concentration among major studios.
The US FCC oversees broadcast content standards affecting VFX-heavy programming distribution, while the EU's GDPR shapes cross-border data flows for European production facilities using cloud-render services. Studios must monitor evolving AI copyright frameworks from the US Copyright Office and EU AI Act compliance requirements for generative tools in creative pipelines. Stakeholders face decisions about building captive render infrastructure versus multi-cloud dependency as energy pricing and data sovereignty rules tighten.
Market Dynamics
Real-time engine workflows are fragmenting traditional render pipeline economics, compressing post-production timelines from months to weeks while redistributing value capture toward pre-visualization and virtual production stages.
Growth Catalysts
- Streaming platform content volume mandates:Netflix, Disney+, and Amazon Prime Video commission original animated series and VFX-heavy features at unprecedented scale, sustaining baseline demand for studio capacity across Los Angeles, Vancouver, and London.
- EU AI Act compliance frameworks:Regulatory clarity on generative tool usage in creative pipelines reduces legal uncertainty for European facilities adopting AI-assisted rotoscoping and inpainting workflows.
- Virtual production volume expansion:LED volume stages at Pinewood Studios, Cinecittà, and Babelsberg integrate real-time rendering with physical cinematography, creating hybrid production demand.
Market Restraints
- Compute cost volatility:GPU cluster pricing fluctuates with semiconductor foundry capacity constraints, squeezing margins for cloud-reliant facilities during peak rendering periods.
- Talent pipeline concentration:Character animation and technical directing expertise clusters in Southern California and Greater Vancouver, creating regional wage premiums and mobility bottlenecks.
- Proprietary format lock-in:Major studios mandate delivery in vendor-specific scene description formats, fragmenting interoperability and raising switching costs for mid-tier service providers.
Strategic Opportunities
- India post-production scale-up:Mumbai, Hyderabad, and Bangalore facilities leverage timezone arbitrage and English-language proficiency to capture overnight rendering and compositing workflows from US and UK productions.
- Generative texture synthesis convergence:Diffusion models trained on material libraries accelerate environment art pipelines, enabling smaller teams to deliver broadcast-quality backgrounds.
- US Inflation Reduction Act clean energy credits:Render farm operators installing solar-plus-storage arrays in Nevada, Texas, and Arizona qualify for production tax credits that offset electricity-intensive computation costs.
Industry Challenges
- Real-time engine integration complexity:Legacy Maya and Houdini pipelines require substantial retooling to interoperate with Unreal Engine and Unity workflows, demanding mid-career reskilling for technical directors.
- Cross-border data residency compliance:European facilities rendering shots for US studios must architect cloud storage to satisfy GDPR data localization requirements while maintaining collaborative access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation and VFX Market |
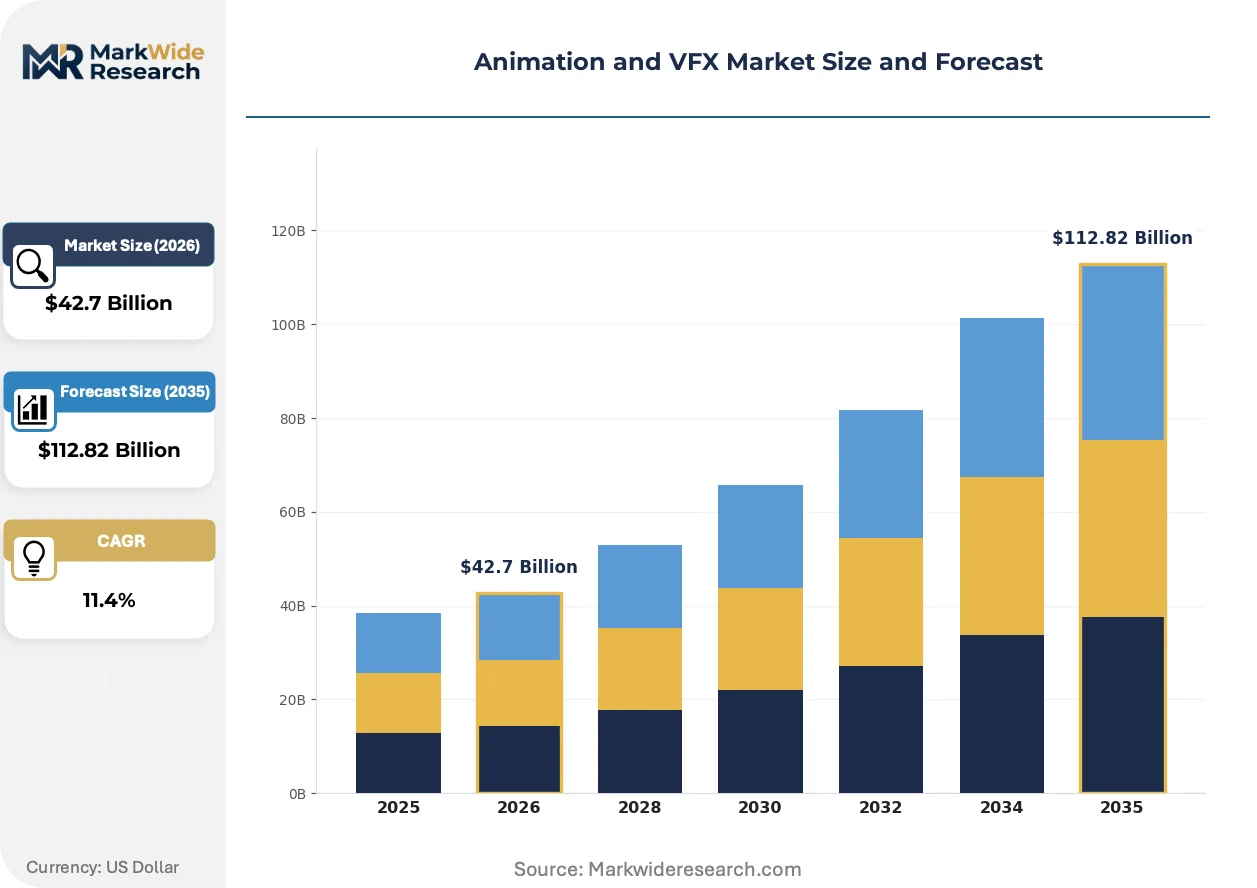
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Film, Television, Video Games, Advertising Technology: 3D Modeling, Motion Capture, CGI, Compositing End User: Studios, Independent Creators, Corporations, Educational Institutions Service Type: Post-production, Pre-visualization, Animation Production, Visual Effects Design |
| Companies Covered | Industrial Light & Magic, DNEG Group, Pixar Animation Studios, Sony Pictures Animation, Framestore, Walt Disney Animation Studios, Wētā FX, Illumination, DreamWorks Animation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation and VFX Market Emerging Trajectories
Neural rendering and synthetic media generation are redistributing creative labor across pre-production, production, and post phases, collapsing traditional sequential workflows into iterative real-time collaboration.
Gaussian splatting and neural radiance fields are decomposing conventional photogrammetry and LIDAR scan-to-mesh pipelines for environment reconstruction. Virtual art departments at Weta Digital and Framestore deploy these techniques to generate explorable 3D spaces from on-set photography within hours rather than weeks. The technology is decomposing the boundary between location shooting and stage-based production, enabling directors to revise set extensions during principal photography.
The EU AI Act's transparency requirements for generative content are mandating disclosure protocols and provenance tracking for AI-assisted VFX elements. Studios must now maintain audit trails distinguishing human-authored from algorithmically generated pixels in final deliverables. European co-productions face the strictest compliance burden, with French facilities implementing CNIL-aligned consent frameworks for training data sourcing.
Buyer concentration among streaming platforms has compressed greenlight-to-delivery timelines, forcing service providers to absorb schedule risk through fixed-bid contracts. Mid-tier animation houses in Seoul and Montreal respond by segmenting talent into dedicated show teams with embedded client liaisons, replacing the traditional pool-based resource allocation model. This restructuring is most advanced in children's animation, where Netflix and Paramount+ commission 52-episode series on 18-month cycles.
Animation and VFX Market Segmentation
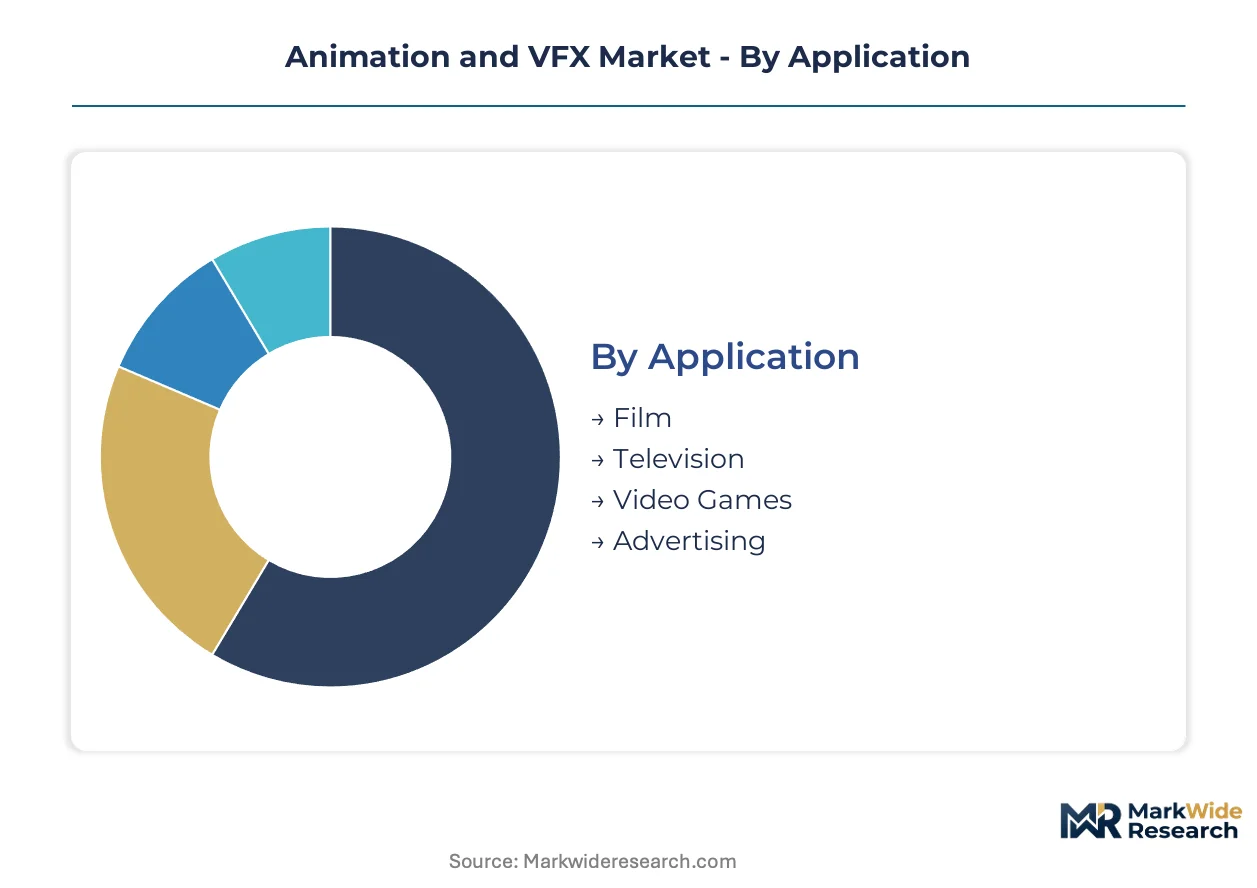
Segmentation in animation and VFX reveals how regulatory pressure, technology cost curves, and client procurement power reshape competitive positioning across distinct buyer categories. Studios configure service portfolios differently when serving streaming platforms versus independent creators, while technology choices determine margin sustainability under volatile compute pricing.
Application:
GDPR's cross-border data restrictions and the EU AI Act's transparency mandates fragment compliance architecture across production types, with European facilities facing stricter audit requirements for streaming content than theatrical releases.
- Film:Blockbuster franchises command proprietary render farm investment and multi-year pipeline development. Los Angeles and Vancouver facilities concentrate here, absorbing FCC content standards for US theatrical distribution alongside MPAA rating compliance costs.
- Television:Streaming volume mandates compress delivery timelines from 24 months to 12-18 months for premium series. Netflix, Disney+, and Amazon Prime Video procurement teams enforce fixed-bid contracting that transfers schedule risk to service providers.
- Video Games:Real-time engine integration dominates, with Unreal Engine and Unity workflows displacing traditional offline rendering for cinematic sequences. Demand clusters at publishers in Tokyo, Montreal, and Los Angeles.
- Advertising:Compressed turnaround requirements favor cloud-reliant studios with elastic capacity. Spot production cycles of 4-8 weeks reward facilities in Mumbai and Seoul exploiting timezone arbitrage.
Established volume favors Film; emerging adoption favors Video Games.
Technology:
Cost tier differentiation separates capital-intensive proprietary infrastructure from cloud-dependent elastic capacity, with GPU cluster pricing volatility squeezing margins for operators without captive compute.
- 3D Modeling:Mature margin center with established Maya, Blender, and Houdini expertise pools. Los Angeles and Greater Vancouver wage premiums reflect talent concentration for character and environment asset creation.
- Motion Capture:Performance capture stages at Pinewood Studios and Cinecittà integrate with LED volumes for hybrid production. Stage infrastructure investment creates regional lock-in for high-end feature work.
- CGI:Virtual production stages represent the steepest expansion trajectory, with LED volumes at Babelsberg and Cinecittà demanding real-time rendering integration with physical cinematography.
- Compositing:AI-assisted rotoscoping and inpainting workflows accelerate under EU AI Act compliance frameworks, with French facilities implementing CNIL-aligned consent protocols for training data sourcing.
Margin stability concentrates in 3D Modeling; capability expansion concentrates in CGI.
End User:
Customer type determines contract structure risk allocation, with Studios demanding fixed-bid accountability while Independent Creators accept revenue-share or milestone-based arrangements.
- Studios:Major studio procurement mandates vendor-specific scene description formats, fragmenting interoperability and raising switching costs for mid-tier service providers. Disney, Warner Bros., and Universal maintain approved vendor lists with embedded quality audits.
- Independent Creators:YouTube, TikTok, and direct-to-consumer platforms democratize access to cloud-based tools. Blender and Unreal Engine's no-cost entry points compress capital barriers for solo operators.
- Corporations:Internal creative teams at automotive and technology firms absorb real-time rendering for product visualization and training simulation. Procurement favors outcome-based statements of work over time-and-materials contracts.
- Educational Institutions:Gnomon, Vancouver Film School, and Gobelins anchor talent pipeline development. Curriculum alignment with studio hiring requirements determines graduate placement rates.
Revenue concentration favors Studios; growth velocity favors Independent Creators.
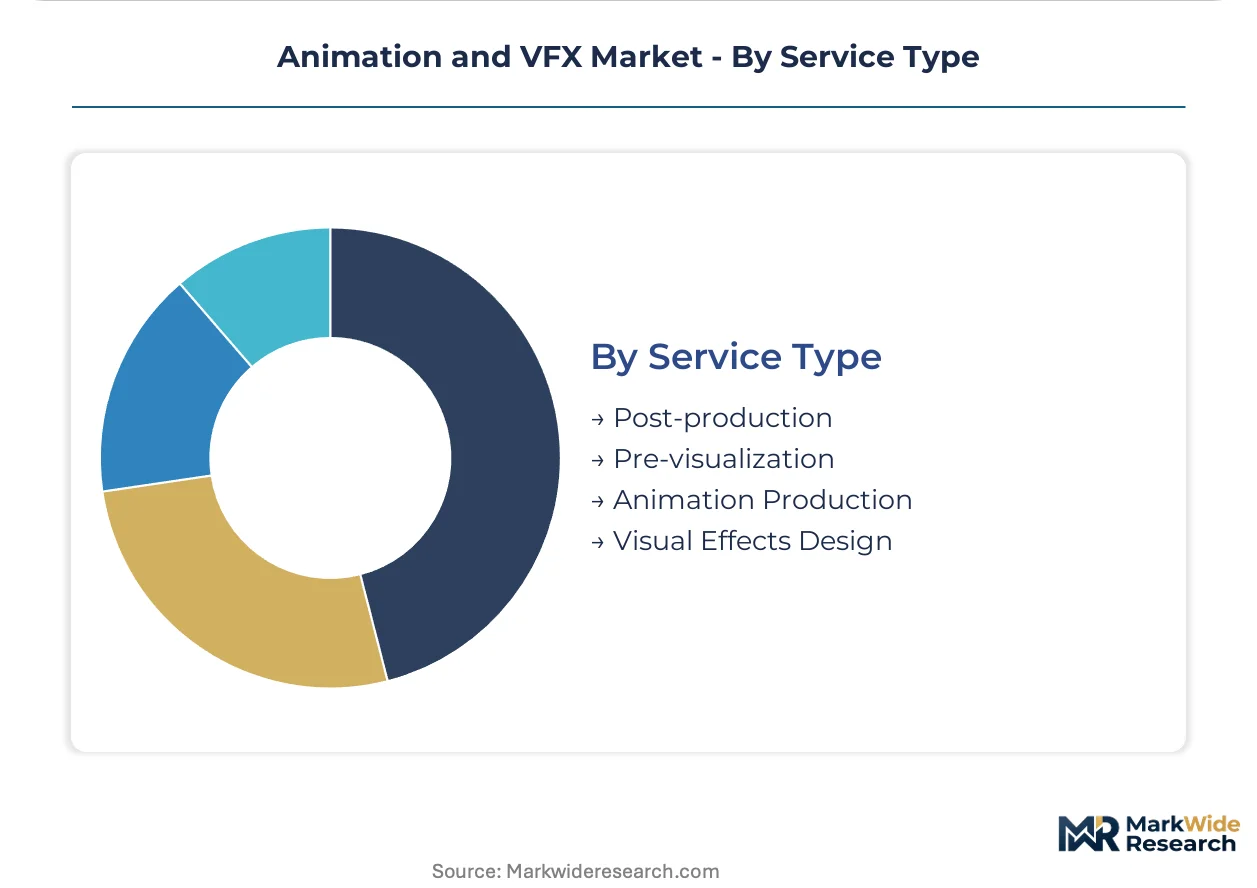
Service Type:
Supply concentration in post-production and visual effects design captures highest value given client concentration among major studios, while pre-visualization gains share as real-time engines compress planning cycles.
- Post-production:Color grading, editorial finishing, and deliverable mastering command premium rates for theatrical and streaming release compliance. Facilities in London and Los Angeles dominate premium tier.
- Pre-visualization:Real-time engine workflows redistribute value capture toward planning stages, with Unreal Engine enabling directors to revise blocking and camera movement before principal photography.
- Animation Production:Children's series commission cycles of 52 episodes on 18-month timelines. Seoul and Montreal houses segment talent into dedicated show teams with embedded client liaisons.
- Visual Effects Design:Highest-value capture point given proprietary pipeline investment and client concentration. Industrial Light & Magic and Weta Digital sustain in-house infrastructure for franchise workloads.
Value capture depth favors Visual Effects Design; workflow speed favors Pre-visualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between theatrical-heavy markets and streaming-dominated territories. The United States absorbs blockbuster franchise workloads requiring proprietary infrastructure, while India and South Korea capture timezone-arbitrage post-production flows from Western productions.
United States
Los Angeles and Vancouver clusters command franchise animation and VFX workloads for Disney, Warner Bros., and Netflix theatrical releases. The FCC enforces broadcast content standards affecting VFX-heavy programming distribution across streaming and linear channels. Georgia's tax credit program sustains Atlanta as the fastest-expanding US production hub outside California.
United Kingdom
London facilities absorb premium post-production and visual effects design for major studio theatrical releases. GDPR shapes cross-border data flows for European production facilities using cloud-render services. Pinewood Studios anchors LED volume stage investment integrating real-time rendering with physical cinematography.
India
Mumbai, Hyderabad, and Bangalore facilities leverage timezone arbitrage and English-language proficiency to capture overnight rendering workflows from US and UK productions. The country's national film certification regulator oversees content standards for theatrical and streaming distribution. Bangalore's technology corridor attracts real-time engine pipeline development for game cinematic outsourcing.
South Korea
Seoul animation houses segment talent into dedicated show teams serving Netflix and Paramount+ children's series commission cycles. The Korean Film Council's production incentives sustain competitive cost positioning against Southeast Asian alternatives. Busan facilities expand motion capture stage infrastructure for hybrid virtual production workflows.
Canada
Vancouver and Montreal clusters concentrate character animation and technical directing expertise for US studio theatrical releases. Canadian Heritage's production tax credits offset labor cost differentials against US facilities. Montreal's real-time engine integration specialists serve Ubisoft and Warner Bros. game cinematic pipelines.
Animation and VFX Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with proprietary infrastructure operators commanding premium franchise workloads while cloud-reliant studios scale across concurrent productions. The structure rewards captive render farm investment for blockbuster pipelines and penalizes pure-service operators during GPU pricing volatility. Two archetypes dominate: integrated studio-owned facilities and independent service providers. Competitive moves concentrate on M&A for talent acquisition and capacity expansion through LED volume stage construction.
Within the integrated studio tier, Industrial Light & Magic and Pixar Animation Studios exemplify proprietary software ecosystem strategies sustaining decades of character-animation IP development. DNEG Group occupies a position representing cloud-distributed pipeline scaling across concurrent theatrical and streaming productions. These three anchors illustrate the capital-intensity divergence bifurcating competitive tiers between in-house infrastructure and multi-cloud dependency.
| Leading Market Players |
|---|
| Industrial Light & Magic |
| DNEG Group |
| Pixar Animation Studios |
| Sony Pictures Animation |
| Framestore |
| Walt Disney Animation Studios |
| Wētā FX |
| Illumination |
| DreamWorks Animation |
| Others |
Supply Flow & Price Mechanics
Fixed-bid contracting for streaming content locks in both render farm capacity and price visibility for service providers, compressing margin buffers while transferring schedule risk from Netflix and Disney+ procurement teams to facilities in Los Angeles, Vancouver, and London. This structure rewards studios with captive GPU clusters and penalizes cloud-reliant operators during semiconductor foundry capacity crunches.
Pricing Analysis
Post-production service tiers drive lifetime value for VFX houses, with retainer-based color grading and editorial finishing commanding premium rates over project-based animation production. Three-tier pricing structure across premium theatrical, standard streaming, and economy advertising deliverables reflects client concentration and turnaround compression. Pricing pressure stems from GPU cluster cost volatility squeezing cloud-dependent facilities during peak rendering windows. Independent creators on YouTube and TikTok exhibit highest price sensitivity, while major studios absorb fixed-bid premiums for franchise pipeline security.
Supply Chain Analysis
GPU inventory lead times stretch 16-24 weeks during foundry allocation cycles, forcing studios to pre-commit to NVIDIA and AMD hardware generations ahead of production demand. Supply concentrates in Taiwan semiconductor fabrication, South Korea memory packaging, and USA chip design centers. Raw material dependencies span silicon wafers, high-bandwidth memory stacks, and specialized cooling infrastructure. Single-source vulnerability runs through TSMC's advanced node allocation for AI training chips. Distribution runs through direct OEM relationships with Dell and Supermicro for render farm assembly, bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as streaming volume mandates splinter demand across boutique specialists and regional scale players, with real-time engine workflows creating niches for pre-visualization boutiques and virtual production integrators.
For Market Incumbents: Secure proprietary render farm capacity in Nevada and Texas to capture US Inflation Reduction Act clean energy credits offsetting electricity-intensive computation. Defend against cloud-native challengers by embedding client liaisons within dedicated show teams for Netflix and Paramount+ children's series. Deepen backward integration into LED volume stage construction at Pinewood Studios and Cinecittà to lock in hybrid production demand. For New Entrants and Emerging Players: AI-assisted rotoscoping and inpainting services represent the most penetrable white-space, with French facilities facing CNIL-aligned consent bottlenecks that delay adoption. Target overnight rendering and compositing workflows from US and UK productions using timezone arbitrage from Mumbai, Hyderabad, and Bangalore. Deploy diffusion-model texture synthesis as a go-to-market wedge to enable smaller environment art teams delivering broadcast-quality backgrounds. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-distributed pipeline operators with multi-tenant architecture serving concurrent theatrical and streaming productions. Long-term viability over the next decade hinges on energy pricing trajectory and data sovereignty rule tightening across European facilities. Watch for inflection when EU AI Act transparency mandates trigger compliance-driven consolidation among mid-tier French and German VFX houses.| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Stage Construction | Pinewood Studios and Cinecittà integration locks in hybrid virtual production demand from major studios. |
| Cloud-Distributed Pipeline Scaling | DNEG Group's multi-tenant architecture captures concurrent theatrical and streaming workloads across timezones. |
| Proprietary Software Ecosystem Development | Pixar Animation Studios' decades of character-animation IP development sustains competitive moats. |
| AI-Assisted Workflow Integration | EU AI Act compliance frameworks reduce legal uncertainty for European facilities adopting generative rotoscoping. |
| Clean Energy Render Farm Deployment | Nevada and Arizona solar-plus-storage arrays qualify for US Inflation Reduction Act production tax credits. |
Methodological Framework
The analysis maps real-time engine workflows, virtual production stages, and AI-assisted pipelines, each validated through technical directors at Industrial Light & Magic, cloud operations leads at DNEG Group, and streaming procurement officers at Netflix. Primary interviews with VFX supervisors, render farm engineers, and talent pipeline directors at Gnomon and Vancouver Film School combined with secondary validation against SEC filings from major studio parents, FCC broadcast content standards, and EU AI Act implementation guidance. Bottom-up project pipeline tracking and top-down studio capex analysis triangulate market sizing.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for GPU cluster deployment and streaming platform content spend commitments across the projection horizon. Segmentation dimensions modeled include application type, technology maturity tier, end-user contract structure, and service type value capture depth. CAGRs derived from production volume elasticity to streaming subscriber growth and real-time engine adoption curves. Industry-specific inputs span render farm utilization rates and LED volume stage construction pipelines.
Underlying assumptions cover semiconductor foundry capacity allocation stability and streaming platform content renewal rates, with deviation risk concentrated in GPU pricing volatility and EU regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Photographic Services Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
China Webtoons Market
Digital Media
Digital Video Content Market
Digital Media
3D Animation Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Sports Graphics Market
Digital Media
Entertainment Market
Digital Media
Social TV Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Anime Derivatives Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Digital Content Creation Market