
 Online Entertainment Market | 2026-2036
Online Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Online Entertainment Market Intelligence
Creative talent scarcity in generative AI and immersive content production is bifurcating the labor pool between premium studios and lean algorithmic operators. Netflix leverages its original content pipeline to sustain subscriber retention across multiple continents. Walt Disney Company anchors its competitive edge through backward integration into beloved intellectual property franchises. Tencent Holdings dominates mobile gaming distribution across Asian markets with platform-level control.
Online entertainment encompasses digitally delivered media experiences transmitted through internet protocol networks, typically requiring bandwidth thresholds above 5 Mbps for high-definition streaming and sub-100 millisecond latency for interactive cloud gaming. Its primary commercial purpose centers on monetizing attention through subscription fees, advertising impressions, or transactional purchases. Streaming video occupies the largest revenue pool among content type segments, while online gaming captures the fastest engagement growth as live-service models extend player lifetime value. Smartphones lead device type distribution in emerging markets, though smart TVs command higher average revenue per user in North American and European households.
The EU AI Act imposes transparency requirements on algorithmic recommendation systems, compelling platforms to disclose content ranking logic. The FCC governs net neutrality principles affecting bandwidth prioritization for streaming services in the United States. India's TRAI periodically intervenes in data pricing to ensure affordable mobile access for entertainment consumption. Stakeholders must weigh regulatory compliance investments against the competitive cost of fragmented content licensing across divergent national frameworks.
Market Dynamics
Generative AI is fragmenting production workflows across streaming and gaming studios, compressing creative timelines while amplifying demand for specialized technical talent pools.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements are accelerating investment in explainable recommendation engines across European platforms.
- Mobile-first consumption in India:TRAI's data pricing interventions sustain affordable access, expanding addressable audiences for short-form video and cloud gaming.
- Live-service gaming architectures:Continuous content pipelines extend player retention economics and shift revenue recognition toward recurring models.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency in North American and European markets creates single-point vulnerability for streaming latency.
- Content licensing fragmentation:Territory-specific rights windows force redundant negotiation overhead and limit catalog portability.
- Substitute leisure formats:Immersive experiences and live events recapture discretionary entertainment hours post-pandemic.
Strategic Opportunities
- Brazil's underpenetrated premium tier:Local payment integration and Portuguese-language original production unlock subscription growth.
- Interactive-entertainment convergence:Real-time rendering engines merge gaming mechanics with serialized narrative formats.
- Saudi Arabia's cultural investment mandate:Giga-project entertainment zones create captive demand for localized content infrastructure.
Industry Challenges
- Generative AI skill scarcity:Prompt engineering and synthetic media governance expertise command premium compensation, constraining mid-tier studio hiring.
- Legacy rights management systems:Decades-old contract databases impede automated content identification for royalty distribution.
- Cross-border content moderation scale:Platform-scale human review pipelines face throughput ceilings as upload volumes expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Entertainment Market |
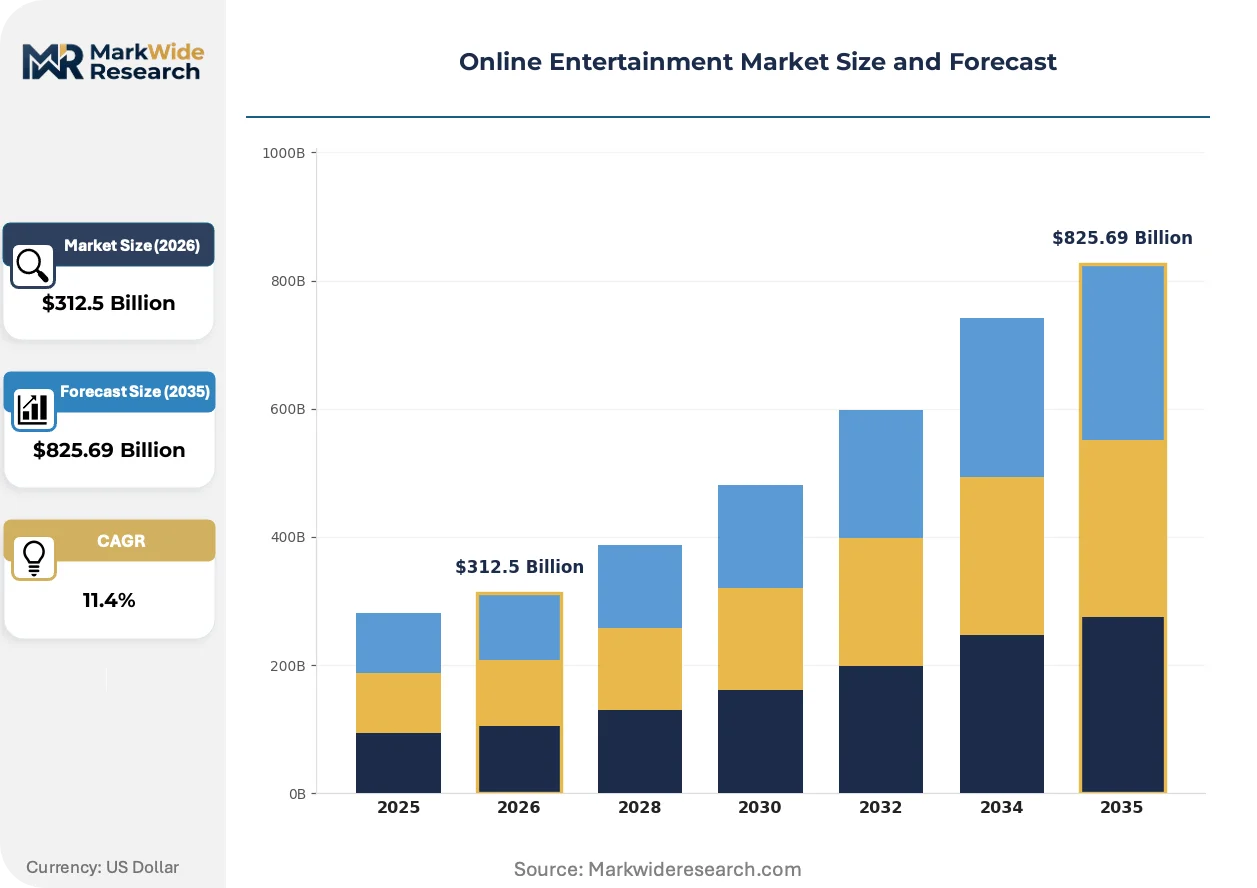
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $825.69 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Streaming Video, Streaming Music, Online Gaming, Podcasts Device Type: Smartphones, Tablets, Laptops, Smart TVs Subscription Model: Freemium, Ad-Supported, Subscription-Based, Pay-Per-View End User: Individual Consumers, Families, Schools, Corporations |
| Companies Covered | Netflix, Walt Disney Company, Sony Corporation, Spotify, Amazon.com, Google LLC, Tencent Holdings, Apple Inc., Comcast Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Entertainment Market Strategic Shifts & Innovations
Cloud-native production pipelines are collapsing traditional post-production hierarchies, enabling geographically distributed creative teams while compressing release cycles for serialized content.
Neural rendering is decomposing conventional asset creation workflows. Gaming studios and virtual production stages adopt real-time ray tracing and AI-assisted texture generation to replace manual modeling labor. This compression is decomposing the boundary between pre-rendered cinematic content and interactive engine output, forcing asset pipeline reinvestment across mid-sized studios.
The EU AI Act's transparency obligations for recommender systems are compelling platforms to document ranking logic and provide user override controls. Industrial consequence includes mandatory algorithmic auditing expenditures and revised product manager training protocols. Streaming services operating across Germany, France, and Italy are responding by segregating European recommendation architectures from global systems to limit disclosure scope.
Consumption patterns are rotating toward ambient and secondary-screen engagement, where audio-first and background-viewing modes displace appointment television. Smart speaker and automotive infotainment channels capture incremental listening hours previously allocated to video. This shift concentrates in United States and United Kingdom commuter demographics and expands addressable inventory for podcast and music platform advertising.
Online Entertainment Market Segmentation
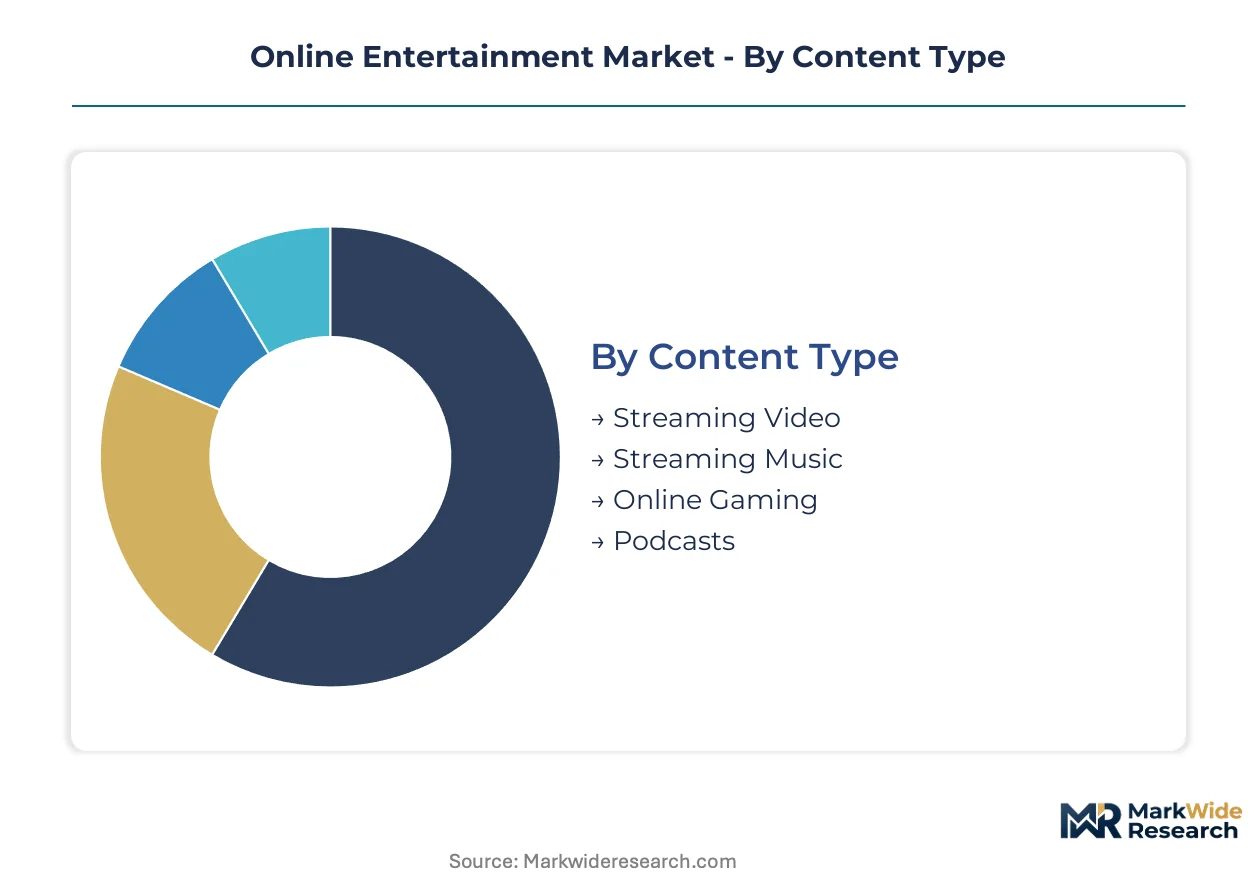
Online entertainment monetization pathways diverge sharply across content formats and access tiers. Device penetration patterns and subscription elasticity determine addressable revenue pools in each segment cluster.
Content Type:
Margin pools concentrate in formats with recurring engagement mechanics and proprietary distribution infrastructure.
- Streaming Video:High-definition and ultra-high-definition codecs dominate bandwidth consumption. Households in Germany and France drive premium tier subscriptions, constrained by the EU AI Act's algorithmic transparency mandates that inflate compliance costs.
- Online Gaming:Live-service architectures with continuous content pipelines extend player lifetime value. Mobile-first adoption in India accelerates through TRAI's data pricing interventions, though generative AI skill scarcity raises production costs for mid-tier studios.
- Streaming Music:Audio-first formats capture commuter and secondary-screen listening hours across United States and United Kingdom demographics.
- Podcasts:Serialized spoken-word content monetizes through dynamic ad insertion and exclusive licensing deals with platform aggregators.
Streaming video holds installed capacity. Online gaming is rotating up the share rankings.
Device Type:
Hardware specifications dictate content format accessibility and average revenue per user differentiation.
- Smartphones:Mobile chipsets and 5G modems enable cloud gaming and short-form video consumption. India's expanding mobile-first entertainment ecosystem concentrates demand here, with affordable data tariffs from TRAI sustaining addressable audience growth.
- Smart TVs:Large-format displays command premium subscription tiers in North American households. 4K and 8K resolution support drives hardware refresh cycles, though smart TV operating system fragmentation complicates app development economics.
- Tablets:Mid-size touchscreens serve children's content and portable gaming use cases with lower average revenue per user than smartphones.
- Laptops:Full keyboard interfaces support productivity-adjacent entertainment and browser-based gaming platforms with modest monetization depth.
Smartphones dominate unit shipments. Smart TVs are climbing the fastest in revenue contribution per device.
Subscription Model:
Payment structure flexibility determines conversion funnel efficiency and churn exposure across customer cohorts.
- Subscription-Based:Recurring monthly or annual fees generate predictable revenue recognition. Annual plans reduce churn in United States and United Kingdom markets where credit card infrastructure supports seamless auto-renewal.
- Freemium:Tiered access with premium feature unlocks converts non-paying users at 2-5% rates. Music and gaming platforms deploy this model most aggressively, with conversion efficiency varying by local payment method penetration.
- Ad-Supported:Impression-based monetization sustains free tiers with lower content licensing costs. Brand safety requirements and EU AI Act transparency obligations increase ad-tech infrastructure investment.
- Pay-Per-View:Transactional access for live events and theatrical releases captures discrete purchase intent. Sports rights and concert streaming deploy this model with high per-unit revenue but unpredictable demand clustering.
Subscription-based models hold installed capacity. Ad-supported tiers are gaining share fastest in emerging market expansions.
End User:
Customer type segmentation shapes content curation, parental control requirements, and procurement decision complexity.
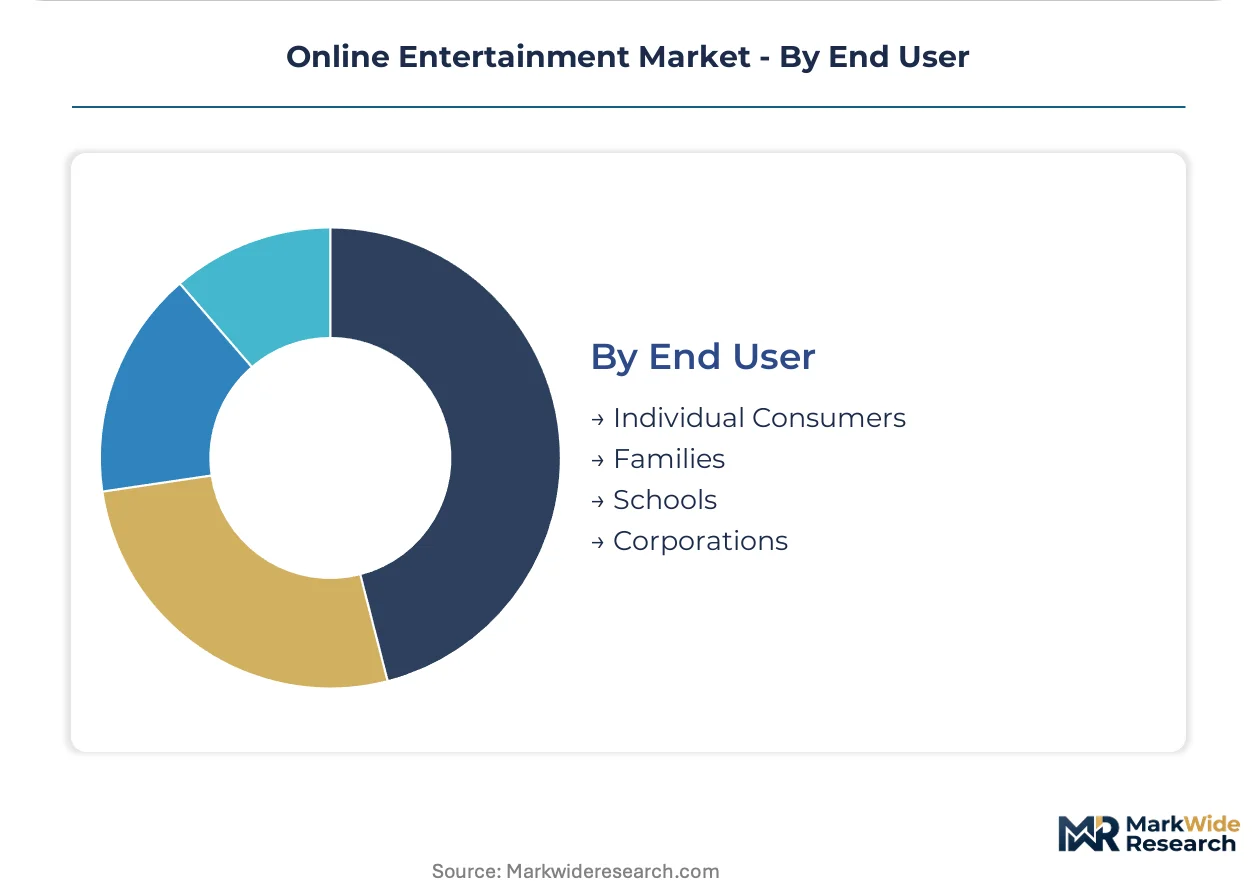
- Individual Consumers:Single-user accounts with personalized recommendation profiles. Solo viewing and gaming sessions dominate time-spent metrics, with privacy regulation compliance costs concentrated in European markets under GDPR and EU AI Act frameworks.
- Families:Multi-profile household plans with parental control features and content filtering. Shared payment credentials reduce individual subscriber acquisition costs while increasing support ticket volume for account management.
- Schools:Institutional licensing for educational video and interactive content with bulk pricing structures and curriculum alignment requirements.
- Corporations:Enterprise subscriptions for training, internal communications, and team-building gaming platforms with SSO integration and usage analytics dashboards.
Individual consumers hold installed capacity. Family plans are rotating up the share rankings as multi-profile features mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. India relies on mobile-first streaming through affordable data tariffs. Germany and France prioritize premium smart TV subscriptions with stringent algorithmic transparency mandates. The United States balances ad-supported tiers with high-value original content production.
United States
Households allocate substantial entertainment budgets to subscription stacking across multiple streaming platforms. The FCC governs net neutrality principles affecting bandwidth prioritization for streaming services. Los Angeles anchors original content production with major studio backlots driving serialized programming volume.
Germany
Consumers demonstrate strong willingness to pay for ad-free premium tiers and localized content libraries. The EU AI Act imposes transparency requirements on algorithmic recommendation systems operating across German territory. Berlin hosts a growing cluster of gaming studios adopting live-service architectures for European audiences.
India
Mobile-first consumption dominates with smartphones capturing the majority of video and gaming engagement hours. TRAI periodically intervenes in data pricing to ensure affordable mobile access for entertainment consumption. Mumbai and Bangalore concentrate regional headquarters for global streaming platforms targeting South Asian language markets.
Brazil
Portuguese-language original production unlocks subscription growth in an underpenetrated premium tier. Local payment integration requirements shape platform entry strategies and partnership structures. São Paulo serves as the primary production hub for Latin American original series and interactive content development.
Saudi Arabia
Giga-project entertainment zones create captive demand for localized content infrastructure and immersive experiences. The national cultural investment mandate channels sovereign capital into domestic production capabilities. Riyadh and the Eastern Province concentrate new studio construction and talent recruitment initiatives.
Online Entertainment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in online entertainment. Netflix, Disney, and Amazon command proprietary distribution infrastructure and original content pipelines. Mid-tier algorithmic operators compete on lean production models and niche audience targeting. Competitive moves concentrate on exclusive IP acquisition and geographic expansion through localized production.
Among integrated platform operators, Netflix and Walt Disney Company exemplify the vertically integrated archetype with captive content supply chains. Tencent Holdings occupies a distinct position anchoring mobile gaming distribution across Asian markets. These three entities represent contrasting strategic postures: the Los Gatos-based streaming pioneer, the Burbank-based entertainment conglomerate with backward integration into beloved franchises, and the Shenzhen-based technology holding company with platform-level control over interactive entertainment.
| Leading Market Players |
|---|
| Netflix |
| Walt Disney Company |
| Sony Corporation |
| Spotify |
| Amazon.com |
| Google LLC |
| Tencent Holdings |
| Apple Inc. |
| Comcast Corporation |
| Others |
Cost & Logistics Intelligence
Cloud rendering infrastructure substitution for on-premise studio hardware is redistributing production capacity toward hyperscaler-dominated geographies while compressing capital expenditure barriers for new entrants. This shift simultaneously fragments geographic supply concentration and intensifies price competition across mid-tier content production tiers.
Pricing Analysis
Long-term content licensing contracts anchor studio revenue recognition, though spot-market talent rates for generative AI specialists command premium multiples. Three-tier pricing structure across premium, standard, and economy levels separates Netflix-Disney original productions from algorithmic short-form operators and ad-supported user-generated platforms. Cost compression in mid-tier live-service gaming stems from talent scarcity for neural rendering pipelines. Individual consumers in India exhibit highest price sensitivity, while corporate training subscribers in the United States demonstrate lowest elasticity.
Supply Chain Analysis
The United States and Ireland concentrate cloud infrastructure for streaming delivery, while South Korea and Taiwan anchor semiconductor fabrication for mobile gaming chipsets. Content production draws from motion-capture stages in London and Vancouver, synthetic voice libraries from Estonia, and generative model training clusters in Singapore. Single-source vulnerability concentrates in AWS-GCP-Azure triopoly for latency-sensitive interactive entertainment. Distribution runs through app store gatekeepers and smart TV operating system licensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through platform-aggregator consolidation, as Netflix-Disney-Amazon triopoly tightens exclusive IP control and squeezes supplier margins across production ecosystems.
For Market Incumbents: Compound exclusive content pipelines through backward integration into beloved intellectual property franchises. Lock in generative AI talent pools through acquisition of specialist studios in Berlin and Bangalore. Defend against lean algorithmic operators by accelerating live-service architecture deployment for recurring revenue recognition.
For New Entrants and Emerging Players: Differentiate on Portuguese-language original production for Brazil's underpenetrated premium tier. Target Saudi Arabia's giga-project entertainment zones with localized immersive content infrastructure. Deploy local payment integration as primary go-to-market wedge against credit-card-dependent incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated production houses with captive generative AI capabilities and established regulatory compliance frameworks across EU AI Act jurisdictions. Long-term viability hinges on 5-10 year content library amortization cycles. Watch for inflection in TRAI data pricing interventions as signal for Indian mobile-first expansion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive IP Acquisition | Netflix and Disney lock franchise rights to sustain subscriber retention across multiple continents. |
| Localized Original Production | Portuguese-language series production in São Paulo unlocks Brazil's premium subscription growth potential. |
| Generative AI Talent Acquisition | Mid-tier studios acquire prompt engineering specialists to compress creative timelines for live-service content. |
| Regulatory Compliance Architecture | EU AI Act transparency mandates force algorithmic auditing investment across German and French operations. |
| Cloud Gaming Infrastructure Partnership | TRAI-sustained affordable data tariffs in India enable 5G-enabled mobile-first gaming distribution. |
Research Approach
Initial hypotheses were tested against primary input from streaming platform strategy officers, gaming studio technical directors, content licensing attorneys, and TRAI regulatory specialists and refined through secondary validation. SEC filings from Netflix and Disney, EU AI Act implementation guidance documents, TRAI tariff orders, and App Annie engagement metrics provided triangulation anchors. Bottom-up smartphone penetration curves and top-down entertainment expenditure aggregates were reconciled across the analysis window.
Variance decomposition across content type, device category, subscription model, and end-user segmentation dimensions shaped the analytical framework. CAGRs were derived from installed base projections and average revenue per user trajectories across the modeling period. Cloud infrastructure capex disclosures from hyperscalers and mobile data pricing elasticity assumptions from Indian market interventions served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained TRAI data affordability, EU AI Act enforcement intensity, or hyperscaler concentration stability would require recalibration. Forecasts reflect assumptions on content production cost curves and regulatory compliance investment trajectories. Recalibration cycles align with material shifts in sovereign cultural investment mandates and generative AI capability diffusion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
3D Anaglyph Glasses Market
Digital Media
US Automatic Content Recognition Market
Digital Media
North America Webtoons Market
Digital Media
Digital Music Content Market
Digital Media
Webcomics Market
Digital Media
Music Rights Management Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Animation and VFX Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Naruto Around Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Digital Media Market
Digital Media
Anime Streaming Tool Market
Digital Media
Animation Services Market