
 Music Rights Management Market | 2026-2036
Music Rights Management Market Size, Share, and Industry Trends Forecast 2026-2036
Music Rights Management Market Foresight
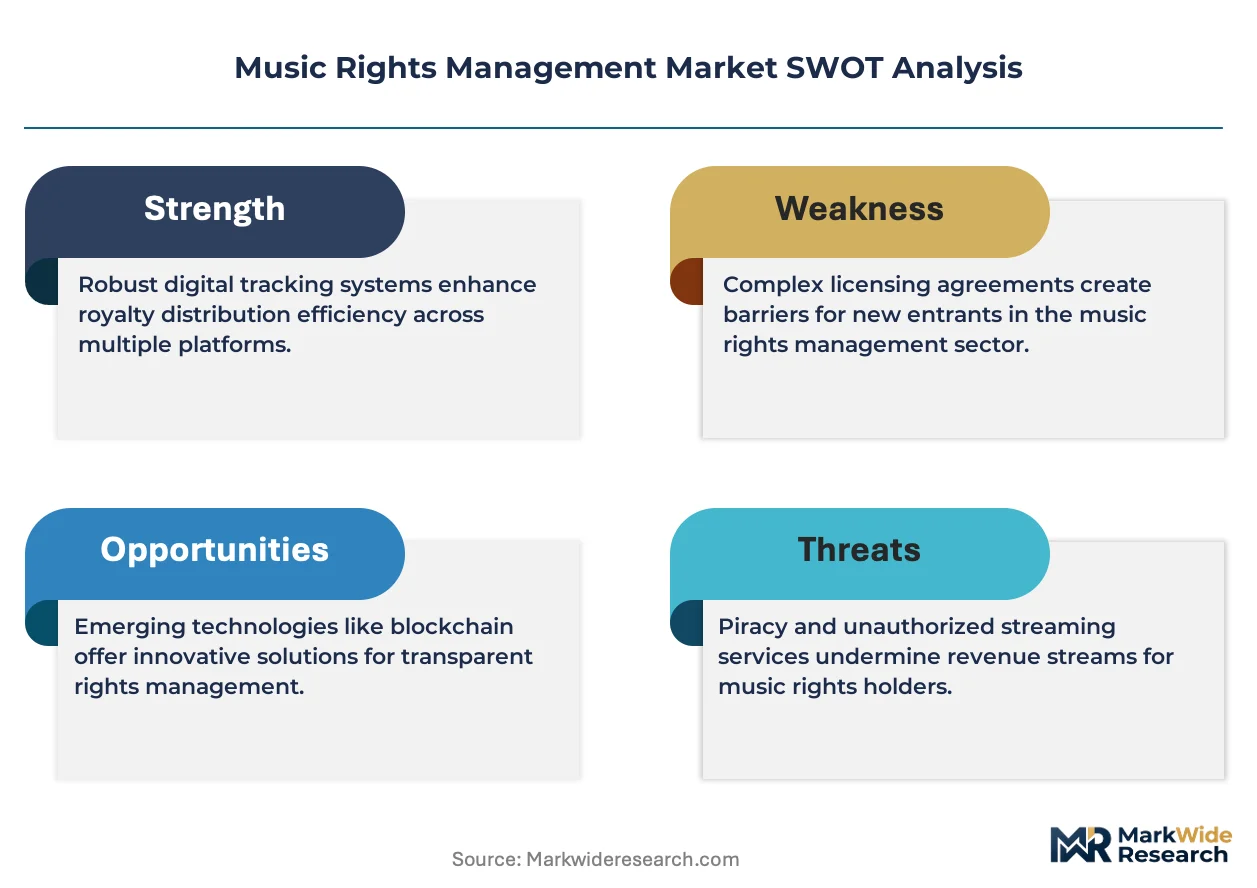
North America is rewriting competitive dynamics in music rights administration through publisher consolidation and PRO licensing reforms. Universal Music Publishing Group leverages its global catalog scale to dominate synchronization and performance licensing across film, television, and advertising. Sony Music Publishing anchors its position through deep vertical integration with recorded music operations and direct-to-creator platforms. Warner Chappell Music competes through aggressive A&R investment and regional office expansion in emerging production hubs.
Music rights management encompasses the legal, administrative, and technological systems that identify, track, license, and monetize musical compositions and sound recordings across broadcast, digital, physical, and live performance channels. The discipline relies on metadata standards such as ISWC, ISRC, and IPN to match works to rights holders and calculate royalty distributions. Performance rights administration represents the most mature revenue pool, while blockchain-based rights tracking is the fastest-growing technology segment as stakeholders seek immutable provenance chains. Digital distribution services command premium margins where platforms bundle analytics, licensing, and direct payment infrastructure for independent creators.
The US Copyright Office and EU collective rights management directives shape cross-border licensing frameworks and transparency mandates for royalty distributions. The US Department of Justice continues reviewing consent decrees governing ASCAP and BMI, with outcomes that would reshape rate-setting mechanics for digital and broadcast licensees. Stakeholders must monitor regulatory divergence between Anglo-American copyright traditions and continental European moral rights frameworks as platform licensing negotiations grow more complex across territories.
Market Dynamics
Streaming platform consolidation and the EU Digital Services Act are forcing rights administrators to rebuild royalty tracking infrastructure around real-time transparency mandates.
Growth Catalysts
- DSO Streaming Bundles:Digital service operators now package music with video and gaming subscriptions, multiplying licensing touchpoints and administrative fee pools.
- Blockchain Provenance Systems:Immutable ledger technology eliminates disputes over ownership chains, accelerating clearance for synchronization licenses in film and advertising.
- India's Copyright Office Modernization:The country's national copyright registry digitization reduces registration lag from months to days for composition filings.
Market Restraints
- Consent Decree Uncertainty:US Department of Justice review of ASCAP and BMI rate-setting mechanisms creates licensing cost unpredictability for digital platforms.
- Metadata Fragmentation:Inconsistent ISWC and ISRC application across territorial databases forces manual reconciliation, inflating operational overhead.
- PRO Territory Overlap:Competing collective management organizations in continental Europe claim identical repertoire segments, triggering double-licensing exposure for broadcasters.
Strategic Opportunities
- Sub-Saharan Africa Direct Licensing:Bypassing traditional PRO structures through mobile carrier partnerships captures unmonetized performance royalties in Nigeria and Kenya.
- AI-Generated Composition Tracking:New detection protocols for machine-created works open royalty streams previously uncaptured by human-centric identification systems.
- Live Event Micro-Licensing:Venue-specific blanket licenses for festivals and esports tournaments replace cumbersome individual song clearances.
Industry Challenges
- Cross-Border Royalty Matching:Reconciling performance data across incompatible national databases requires specialized data science talent scarce in rights administration.
- Legacy System Integration:Mainframe-based distribution engines at established PROs resist API connectivity with modern analytics platforms, delaying real-time reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Rights Management Market |
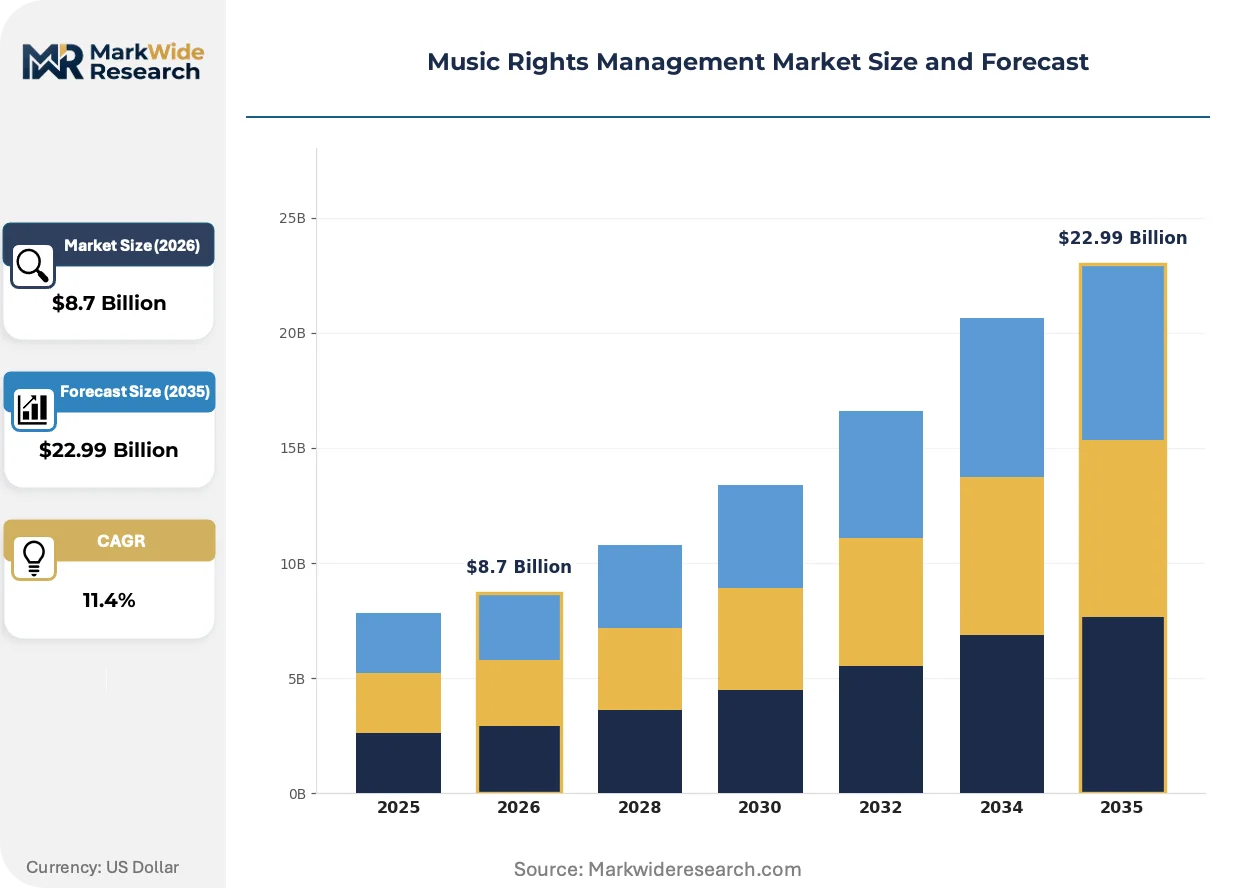
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | License Type: Performance Rights, Mechanical Rights, Synchronization Rights, Reproduction Rights Service Type: Digital Distribution, Licensing Administration, Rights Tracking, Royalty Collection End User: Record Labels, Music Publishers, Artists, Production Companies Technology: Blockchain, Cloud Storage, AI Analytics, Digital Rights Management |
| Companies Covered | Universal Music Publishing Group, Sony Music Publishing, Warner Chappell Music, BMG Rights Management, Kobalt Music, ASCAP, BMI, SESAC, SoundExchange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Rights Management Market Shifts & Advancements
Rights administration is pivoting from periodic reconciliation to continuous accounting, driven by platform demands for instant usage visibility and creator pressure for faster payment cycles.
Blockchain-based rights registries are collapsing the multi-week clearance timelines that previously delayed synchronization licensing for film and television productions. Major studios now demand immutable ownership proofs before greenlighting music placement, forcing publishers to migrate catalog data onto distributed ledgers. This compression is eliminating the escrow periods that once padded administrative cash flows.
The EU Digital Services Act transparency mandates are requiring platforms to disclose algorithmic recommendation weights and content moderation criteria affecting royalty-generating exposure. Streaming services must now report how editorial playlists allocate streams across repertoire, enabling rights holders to audit whether mechanical and performance distributions match actual consumption patterns. France's CNIL and Germany's data protection authorities are already enforcing granular disclosure requirements.
Creator-side procurement of administration services is fragmenting as independent artists bypass traditional publisher advances in favor of direct distribution with bundled rights management. DistroKid, UnitedMasters, and similar platforms now capture master and composition rights simultaneously, compressing the multi-party licensing chain into single-contract relationships. This unbundling is most visible in the United States, where SoundExchange and Harry Fox Agency compete for adjacent royalty streams previously siloed by rights type.
Music Rights Management Market Segmentation

Segmentation in music rights management reflects how revenue pools, administrative workflows, and technology adoption patterns diverge across rights types and stakeholder categories. Understanding these divisions clarifies where platform consolidation, regulatory pressure, and automation investment concentrate competitive advantage.
License Type:
Cost tier differentiation across license categories determines administrative complexity and margin structure for rights administrators.
- Performance Rights:Covers public performance of compositions in broadcast, live venues, and digital streaming. ASCAP and BMI in the United States, alongside SACEM in France, administer blanket licenses that pool repertoire for efficient clearance. This segment anchors established revenue flows but faces rate-setting uncertainty from ongoing Department of Justice consent decree reviews.
- Mechanical Rights:Governs reproduction and distribution of compositions in physical media and digital downloads. The Harry Fox Agency and Music Reports dominate US mechanical licensing, while MCPS in the United Kingdom handles similar functions. Streaming mechanicals now exceed physical reproduction volumes, shifting administrative focus toward digital service operator reporting systems.
- Synchronization Rights:Film, television, advertising, and gaming placements require negotiated licenses matching composition to visual media. Publishers retain direct control, bypassing collective management for premium-rate negotiations.
- Reproduction Rights:Covers duplication across formats including vinyl manufacturing and digital file creation. Smaller revenue pool concentrated in niche physical format resurgence and archival reissue markets.
Performance rights command the established base. The steepest expansion runs through synchronization rights as streaming video and gaming multiply placement opportunities.
Service Type:
Application focus determines whether providers capture value at the distribution endpoint or upstream in rights administration infrastructure.
- Digital Distribution:Platforms like DistroKid and UnitedMasters bundle upload, metadata management, and royalty aggregation for independent creators. These services compress the traditional label-publisher-administrator chain into direct relationships, capturing margin from disintermediation.
- Licensing Administration:Publishers and specialized administrators negotiate sync licenses, supervise blanket agreements, and enforce territorial exclusivities. Full treatment: Negotiates individual and blanket agreements across media channels. Sony Music Publishing and Universal Music Publishing Group maintain dedicated teams for film, television, and advertising placements, with rate cards varying by territory and usage scope.
- Rights Tracking:Metadata matching systems identify work usage across broadcast and digital platforms. BRIEF: Tunesat and SoundMouse provide automated detection for television and radio monitoring.
- Royalty Collection:Aggregates and distributes payments from multiple sources including PROs, digital platforms, and mechanical rights organizations. BRIEF: Black Box Royalty Solutions and Exactuals specialize in unclaimed royalty recovery and cross-border payment routing.
Digital distribution is gaining share fastest. Licensing administration retains the highest margin concentration.
End User:
Customer type segmentation reveals diverging procurement patterns between institutional rights holders and individual creators.
- Record Labels:Control master recording rights and negotiate adjacent composition licenses. Full treatment: Major labels including Warner Music Group and Sony Music Entertainment maintain in-house rights administration for core repertoire while outsourcing specialized functions. Label procurement emphasizes volume-based efficiency and direct platform relationships.
- Music Publishers:Administer composition rights across performance, mechanical, and synchronization categories. Full treatment: Publishers like Kobalt and Downtown Music Holdings compete through technology platforms that accelerate royalty matching and reduce distribution lag. Their procurement prioritizes real-time analytics and faster payment cycles to attract songwriter clients.
- Artists:Independent creators increasingly self-administer through direct distribution platforms. BRIEF: DIY tools from CD Baby and TuneCore enable rights retention without publisher intermediation.
- Production Companies:Film studios, advertising agencies, and game developers require efficient clearance for music placement. BRIEF: Netflix and Electronic Arts maintain dedicated music supervisors who interface directly with publishers and sync licensing platforms.
Music publishers command the established base. The steepest expansion runs through artists as creator tools democratize administration access.
Technology:
Maturity and supply concentration vary sharply across technology foundations, with newer architectures displacing legacy infrastructure.
- Blockchain:Distributed ledger systems create immutable ownership records and smart contract automation for royalty distribution. Full treatment: Platforms like Mediachain and Blokur enable publishers to register catalog provenance that studios require before synchronization licensing. Smart contracts automate split payments to multiple rights holders, reducing escrow delays.
- AI Analytics:Machine learning matches unidentified audio to rights databases and predicts royalty trends. Full treatment: Pex and Audible Magic deploy fingerprinting algorithms that identify works in user-generated content across YouTube and TikTok. These systems enable claiming of royalties previously lost to unidentified usage, expanding addressable revenue pools.
- Cloud Storage:Centralized repository systems for audio files, contracts, and metadata. BRIEF: Amazon Web Services and Google Cloud host publisher archives with tiered access controls.
- Digital Rights Management:Encryption and access control for content distribution. BRIEF: Widevine and PlayReady protect streaming audio from unauthorized extraction.
Cloud storage commands the established base. The steepest expansion runs through blockchain as major studios mandate immutable provenance for sync licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors transatlantic music rights administration through its dominance of streaming platform headquarters and performance rights organization infrastructure. Nashville's Music Row, Los Angeles production clusters, and New York publishing houses concentrate licensing negotiation capacity. The US Copyright Office shapes international royalty frameworks through its administrative precedents.
United States
Major publisher consolidation and PRO restructuring drive competitive realignment. The Department of Justice reviews ASCAP and BMI consent decrees, creating regulatory uncertainty for digital rate-setting. Nashville, Los Angeles, and New York host the densest concentration of synchronization licensing teams and catalog administration operations.
United Kingdom
Post-Brexit licensing fragmentation and MCPS-PRS Alliance operations reshape cross-border royalty flows. The Intellectual Property Office maintains copyright registry functions that influence EU-UK repertoire administration. London's Soho and Shoreditch clusters house boutique sync licensing agencies serving European advertising and film production.
Germany
GEMA's territorial licensing authority and streaming penetration rates sustain mechanical rights revenue pools. The Federal Cartel Office monitors collective management organization conduct under EU competition directives. Berlin's Kreuzberg and Mitte districts concentrate independent publisher operations and rights technology startups.
France
SACEM's administrative modernization and CNIL enforcement of Digital Services Act transparency mandates accelerate platform disclosure requirements. The country's moral rights tradition creates licensing complexity distinct from Anglo-American frameworks. Paris hosts major publisher regional headquarters and film music supervision clusters.
India
Copyright Office digitization and mobile streaming adoption multiply addressable royalty volumes. The Phonographic Performance Limited and Indian Performing Right Society compete for performance rights administration. Mumbai's Andheri and Bandra production hubs concentrate Bollywood music publishing and synchronization licensing activity.
Music Rights Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The market structures around three publisher conglomerates controlling global catalog scale, collective management organizations administering blanket licenses, and technology-enabled administrators competing on royalty velocity. Strategic archetypes include catalog aggregators maximizing synchronization placement, PROs defending territorial licensing authority, and creator-facing platforms disintermediating traditional publisher relationships. Competitive moves concentrate on publisher acquisitions for catalog depth and technology partnerships for metadata matching capabilities.
Within the catalog aggregator tier, Universal Music Publishing Group, Sony Music Publishing, and Warner Chappell Music exemplify scale-driven positioning through global repertoire control and vertical integration with recorded music operations. These entities occupy positions where synchronization licensing teams interface directly with film studios and advertising agencies, bypassing collective management for premium-rate negotiations. Their competitive posture reflects catalog breadth rather than administrative technology differentiation.
| Leading Market Players |
|---|
| Universal Music Publishing Group |
| Sony Music Publishing |
| Warner Chappell Music |
| BMG Rights Management |
| Kobalt Music |
| ASCAP |
| BMI |
| SESAC |
| SoundExchange |
| Others |
Supply & Pricing Matrix
The Los Angeles-to-Nashville freight corridor carries physical master tapes, legal documentation, and hardware infrastructure between recording hubs, with its cost dynamics amplifying supply concentration among three major publisher conglomerates while forcing tiered service differentiation downstream. Rights administrators absorb logistics overhead into platform fees, compressing margins for independent distributors while reinforcing premium positioning for catalog-scale operators.
Pricing Analysis
Volume-discount tiering structures dominate rights administration, with major publishers negotiating enterprise rates for blanket licenses while independent creators pay per-transaction fees through DIY platforms. Price differentiation hinges on catalog scale and real-time analytics access, with tiered pricing separating heritage catalog holders from emerging artist aggregators. Cost compression in the independent tier is intensifying because cloud infrastructure commoditizes basic distribution functions. Major labels exhibit the lowest price sensitivity; bedroom producers and regional indie labels face acute margin pressure.
Supply Chain Analysis
Supplier-financing angles including extended payment terms to PROs and supply-chain finance facilities for metadata vendors stabilize cash flow across the rights administration value chain. Geographic supply concentrates in the United States, the United Kingdom, and Germany, where PRO infrastructure and publisher headquarters cluster. Raw material dependencies include cloud compute capacity from AWS and Google Cloud, proprietary fingerprinting algorithms from Audible Magic and Pex, and blockchain node infrastructure from Ethereum-based registries. Single-source vulnerability runs through dominant cloud providers. Distribution runs through API-first platforms connecting directly to streaming services and broadcast monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rights administration functions as a service-attach opportunity where recurring royalty analytics and compliance layers expand faster than one-time catalog registration fees. The shift from periodic to continuous accounting creates durable revenue streams that outperform transactional clearance margins.
For Market Incumbents: Entrench catalog depth through exclusive administration deals with heritage songwriter estates, blocking competitor access to high-value synchronization placements. Acquire metadata-matching specialists to defend against AI-native entrants automating rights identification. Vertical integration into live event micro-licensing captures venue-specific revenue pools before PRO restructuring completes.
For New Entrants and Emerging Players: Build out white-label administration infrastructure for regional PROs in Sub-Saharan Africa and Southeast Asia, where legacy systems resist modernization. Sub-Saharan Africa offers the most penetrable geography given mobile streaming penetration and absent incumbent infrastructure. Partner with telecom carriers for direct carrier billing integration, bypassing traditional banking rails for royalty distribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from major label parent companies spinning off non-core administration technology stacks. Long-term viability centers on platforms owning the creator relationship end-to-end rather than intermediary licensing functions. Watch for Department of Justice consent decree resolution as the signal indicating rate-setting stability and valuation compression release.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Registry Migration | Mediachain and Blokur enable immutable provenance that Warner Bros. Discovery now mandates before sync licensing. |
| AI Detection Protocol Development | Pex fingerprinting algorithms claim royalties from TikTok user-generated content previously lost to unidentified usage. |
| Direct-to-Creator Platform Launch | DistroKid and UnitedMasters compress the label-publisher-administrator chain into single-contract relationships. |
| Regional PRO Technology Partnership | Indian Performing Right Society digitization reduces registration lag from months to days for composition filings. |
| Live Event Micro-Licensing Expansion | Esports tournament organizers replace cumbersome individual song clearances with venue-specific blanket licenses. |
Research Methodology
Desk research of PRO regulatory filings, streaming platform transparency reports, and copyright office digitization records preceded structured interviews with rights administration executives, music publisher licensing directors, independent artist platform operators, and blockchain registry technologists. Primary fieldwork validated secondary data from US Copyright Office administrative precedents, EU Digital Services Act implementation guidance, and national collective management organization annual reports. Bottom-up modeling of individual service revenue streams triangulated against top-down market sizing from platform disclosed user bases and average revenue per creator.
Assumptions held fixed include prevailing consent decree structures and current metadata standard adoption rates; variables stress-tested included PRO restructuring outcomes, blockchain registry penetration speed, and AI-generated composition volume growth. The analytical framework modeled license type, service type, end user category, and technology foundation across the projection horizon. CAGRs derived from segment-level growth trajectories weighted by revenue pool maturity and technology substitution curves. Forecast inputs incorporated streaming subscriber growth projections and synchronization licensing volume from film and gaming production databases.
Stress conditions across regulatory enforcement intensity, platform consolidation pace, and creator tool adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about PRO territorial authority stability and cross-border royalty matching efficiency. Macroeconomic contraction affecting discretionary entertainment spending, unilateral regulatory overhaul of rate-setting mechanisms, or breakthrough decentralized autonomous organization governance models would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Webtoons Market
Digital Media
Secondary Ticket Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Media Gateway Market
Digital Media
Anime Merchandising Market
Digital Media
Digital Content Creator Market
Digital Media
Africa Animation Market
Digital Media
Adult Entertainment Market
Digital Media
Middle East Gaming Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Video Production Market
Digital Media
Europe Professional Audio Video (Proav) Market