
 VFX Market | 2026-2036
VFX Market Size, Share, and Industry Trends Forecast 2026-2036
VFX Market Outlook
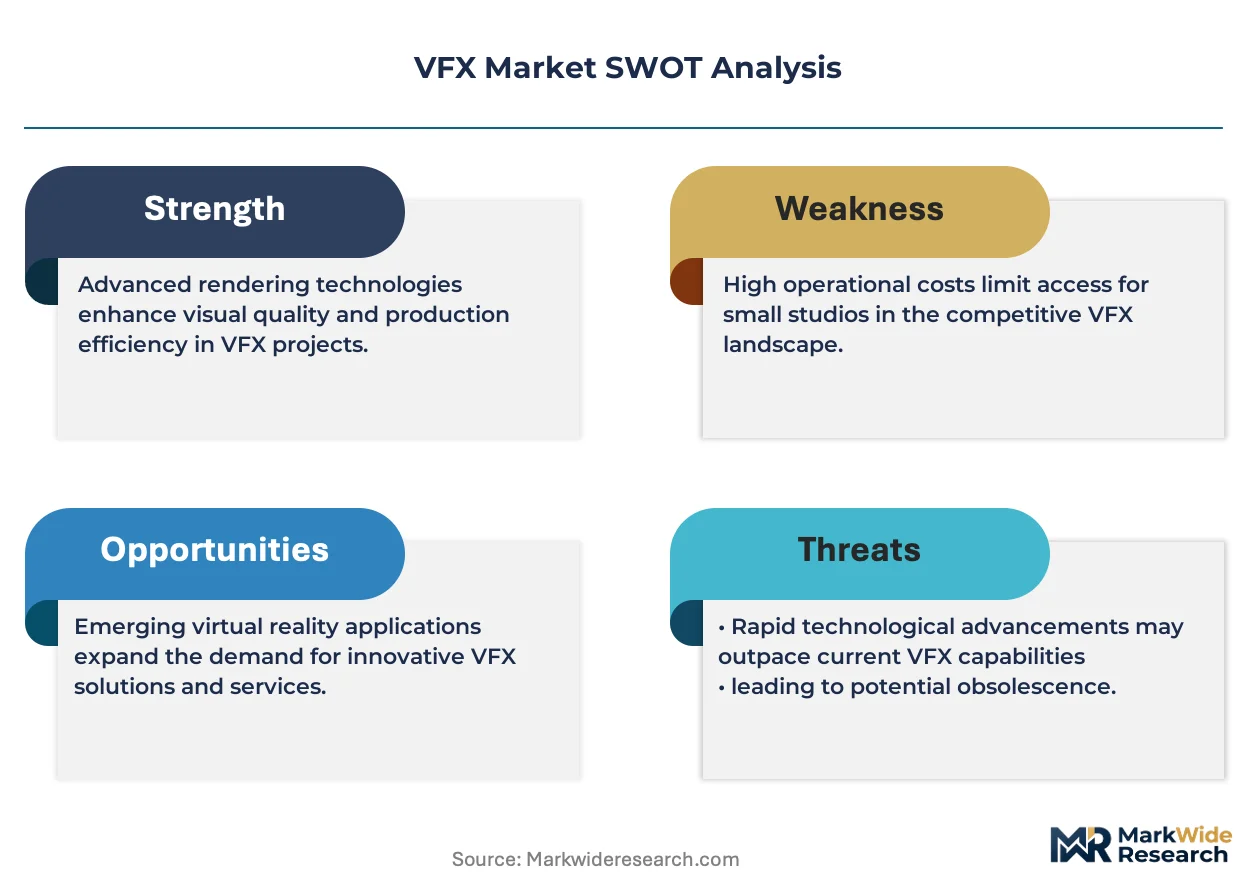
The EU AI Act is repositioning how VFX studios source and train generative image models across European co-productions. Wētā FX leverages proprietary facial capture systems to sustain competitive moats in creature animation for tentpole franchises. ILM anchors its dominance through deep integration with Lucasfilm production slates and proprietary StageCraft virtual production technology.
Visual effects (VFX) denotes the digital creation or manipulation of imagery outside live-action photography, encompassing compositing, 3D modeling, simulation, and motion tracking at resolutions up to 8K for theatrical exhibition. The primary purpose is to produce photorealistic or stylized imagery that physical production cannot capture safely or economically. Rendering services within the Service Type segment occupy the highest capital intensity due to cloud compute requirements and per-frame licensing costs. Virtual Reality under the Technology dimension represents the fastest-expanding margin pool as studios deploy real-time engines for previsualization and final-pixel virtual production.
The MPAA content rating system and France's CNC funding eligibility criteria shape demand by mandating theatrical-grade finishing for subsidy qualification. The UK's BFI certification tax relief and California Film Commission incentives further steer production geography toward jurisdictions with post-production infrastructure. Stakeholders must monitor how generative AI disclosure requirements evolve across national funding bodies and whether real-time engine pipelines displace traditional render farm architectures before the next technology refresh cycle.
Market Dynamics
Real-time engine pipelines are compressing production timelines for photorealistic digital environments while the EU AI Act forces disclosure protocols for generative training data across European co-productions.
Growth Catalysts
- Streaming content budgets:Netflix, Disney+, and Amazon Prime Video are commissioning original series requiring 8K finishing and volume-stage virtual production at scale.
- UK BFI certification tax relief:The 25% post-production credit attracts tentpole VFX work to London facilities, concentrating high-end compositing and creature animation contracts.
- LED volume stages:Industrial adoption of StageCraft and competing real-time systems reduces location shooting costs while enabling same-day final-pixel delivery.
Market Restraints
- Cloud render cost volatility:Per-frame licensing for Autodesk Arnold and Chaos V-Ray fluctuates with spot compute pricing, squeezing margin predictability at boutique houses.
- Supply concentration in California:Los Angeles and San Francisco Bay Area facilities control premium facial capture and machine learning R&D, creating bottleneck risk for non-integrated studios.
- Generative AI copyright friction:The EU AI Act's training data transparency mandates create legal uncertainty for diffusion-model deployment in European theatrical releases.
Strategic Opportunities
- India post-production expansion:Mumbai and Hyderabad facilities are capturing overflow rotoscoping and matchmove work from US studios seeking cost arbitrage on labor-intensive tasks.
- Previsualization services:Real-time engine pipelines for Unreal Engine and Unity are opening new revenue streams in early-stage creative development before greenlight decisions.
- France CNC funding eligibility:Theatrical-grade VFX finishing requirements for subsidy qualification steer co-production VFX spend toward Paris-based facilities.
Industry Challenges
- Pipeline TD talent scarcity:Shortages of technical directors proficient in USD (Universal Scene Description) and real-time engine integration delay facility technology refreshes.
- Legacy render farm stranded assets:Traditional CPU-based infrastructure faces accelerated obsolescence as GPU-accelerated real-time workflows displace overnight batch processing.
- Cross-jurisdiction IP licensing:Fragmented rights clearance for photogrammetry assets and motion capture libraries complicates multi-territory distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VFX Market |
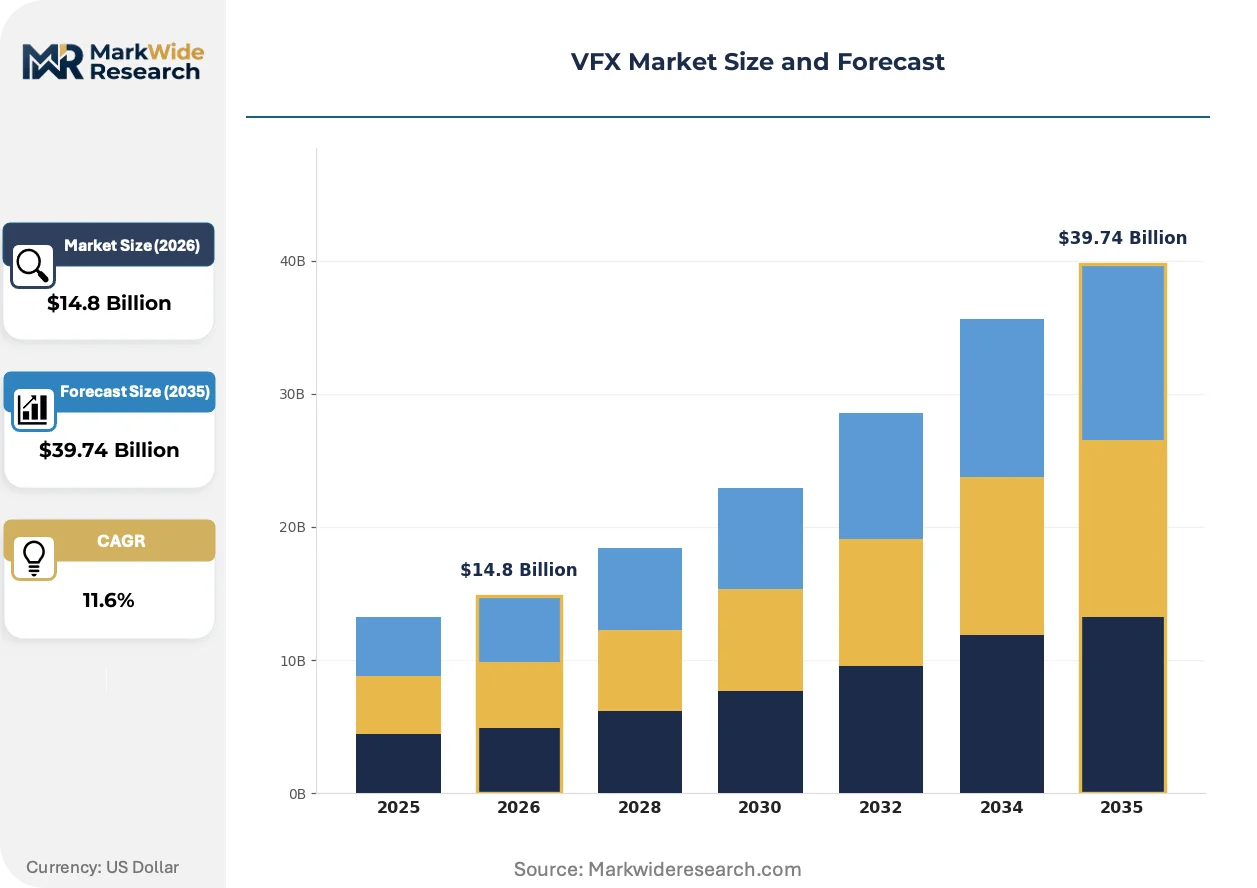
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Animation, Compositing, Motion Graphics, Rendering End User: Film Industry, Television, Video Games, Advertising Technology: 3D Rendering, Matte Painting, Simulation, Virtual Reality Application: Film Production, Game Development, TV Commercials, Live Events |
| Companies Covered | Wētā FX, PhantomFX, DNEG, Lux Aeterna, Milk VFX, ILM, Walt Disney Animation Studios, Tippett Studio, Framestore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VFX Market Strategic Shifts
Generative diffusion models and neural rendering are collapsing traditional boundaries between preproduction, production, and postproduction phases. Three developments are restructuring competitive positioning.
Neural radiance fields (NeRF) and Gaussian splatting are unifying volumetric capture with real-time playback, enabling cinematographers to scout and light fully realized digital locations during principal photography. Major studios are deploying these tools for franchise world-building where environmental consistency across sequels is mandatory. The technology is compressing location survey costs while expanding creative control over atmospheric conditions.
The EU AI Act's disclosure requirements for generative training data are forcing European co-productions to document provenance for every AI-assisted asset in delivery packages. VFX supervisors must now maintain chain-of-custody records for diffusion-model outputs used in creature design and environment generation. French and German facilities are responding by building proprietary training datasets from licensed photography to maintain subsidy eligibility.
Fixed-bid vendor contracts are giving way to time-and-materials arrangements with performance bonuses tied to delivery velocity. Streaming platforms are unbundling traditional postproduction packages, awarding separate contracts for previs, final pixel, and finishing to specialized houses. This fragmentation is most visible in Atlanta and London, where volume-stage operators now bid independently from compositing vendors.
VFX Market Segmentation
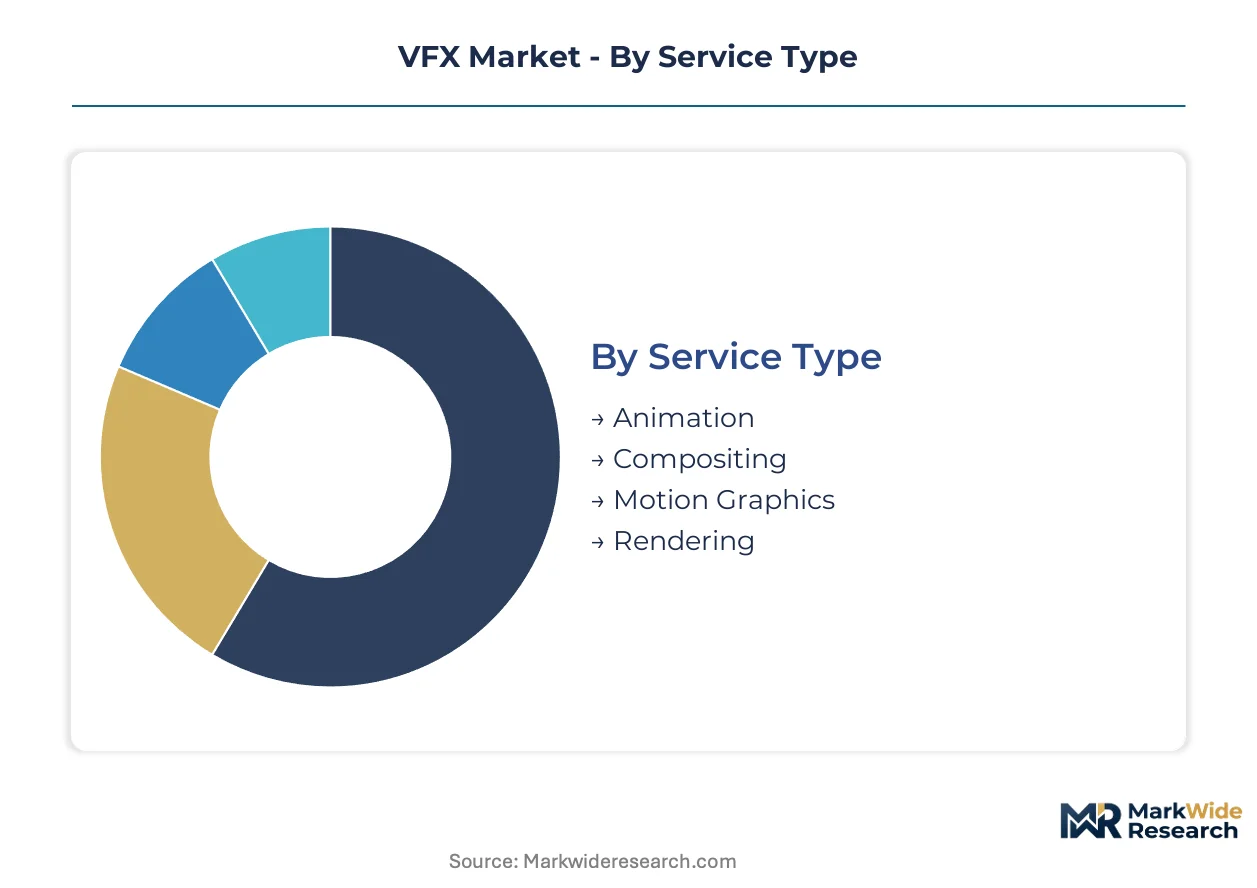
VFX market segmentation reveals how production pipelines fragment across specialized technical capabilities and distinct delivery contexts. Each dimension carries different margin profiles and capital requirements, shaping vendor positioning and facility investment decisions.
Service Type:
Standalone services operate on project-based contracts with discrete deliverables, while embedded services integrate into continuous production workflows requiring permanent pipeline infrastructure.
- Animation:Character and creature performance work demands proprietary rigging systems and facial capture databases. Film industry tentpole franchises in Los Angeles and London drive premium pricing for photorealistic digital actors. Labor intensity and talent scarcity constrain boutique facility expansion.
- Compositing:Layering of live-action plates with CG elements requires precision color matching and resolution handling up to 8K theatrical standards. UK BFI tax relief concentrates high-end compositing work in London facilities serving streaming platform original series.
- Motion Graphics:Title sequences and UI overlays for television and advertising deliver faster turnaround cycles with lower per-shot complexity.
- Rendering:Cloud compute clusters process final-frame output with per-minute licensing costs tied to spot pricing volatility. Capital intensity peaks here due to GPU farm requirements and software seat subscriptions.
Rendering leads volumes today; animation is gaining share fastest.
End User:
Customer types stratify by budget scale, delivery timeline compression, and technical specification tolerance.
- Film Industry:Theatrical releases demand 8K finishing, HDR color spaces, and Dolby Vision certification. Los Angeles studio lots and Atlanta volume stages anchor the largest concentration of premium VFX service contracts.
- Television:Streaming platform original series now match theatrical technical specifications. Netflix and Disney+ commissioning patterns favor vendors with StageCraft virtual production capabilities.
- Video Games:Real-time engine integration for cinematics and in-engine rendering pipelines blur traditional post-production boundaries.
- Advertising:Compressed timelines and brand-mandated revision cycles favor agile boutiques with motion graphics specialization.
Television expenditure is expanding most quickly; film industry retains the highest per-project value.
Technology:
Technology segments differentiate by computational architecture and integration depth with principal photography workflows.
- 3D Rendering:Ray-traced illumination and physically accurate materials require dedicated render farm infrastructure. Cloud-based autoscaling is displacing owned hardware at mid-size facilities.
- Matte Painting:Traditional digital environment extensions now incorporate neural radiance fields for volumetric depth. Franchise world-building applications in Los Angeles drive demand for environmental consistency across sequel productions.
- Simulation:Fluid, cloth, and destruction dynamics execute on GPU-accelerated solvers with shot-specific parameter tuning.
- Virtual Reality:Real-time engine pipelines for previsualization and final-pixel delivery represent the steepest expansion trajectory. LED volume stages in Atlanta and London deploy Unreal Engine for same-day cinematography decisions.
3D rendering dominates current facility revenue; virtual reality claims the fastest-climbing investment allocation.
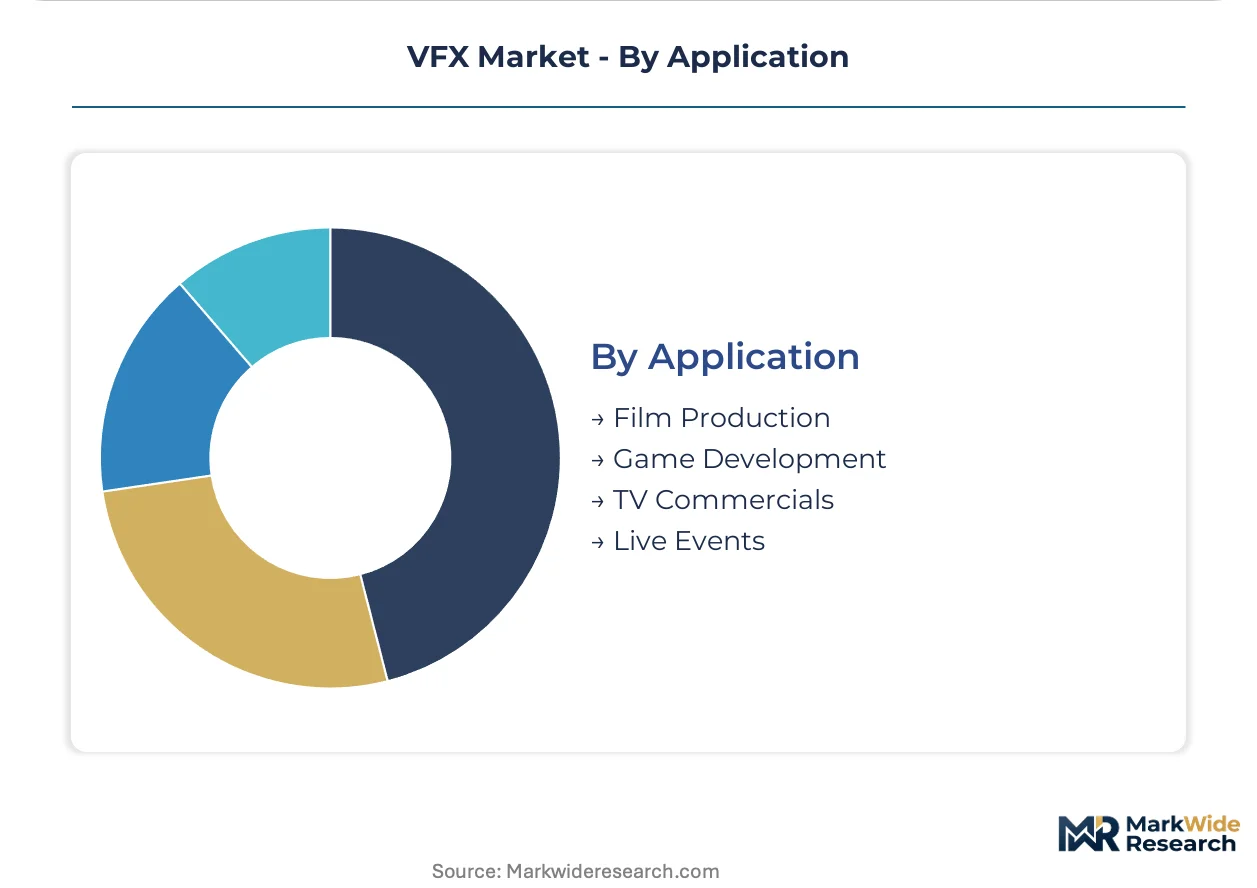
Application:
Application contexts determine pipeline configuration, from iterative game engine workflows to locked theatrical delivery specifications.
- Film Production:Theatrical exhibition mandates DCI-compliant color spaces and secure digital cinema package encryption. France CNC funding eligibility requires theatrical-grade finishing for subsidy qualification.
- Game Development:In-engine cinematics and marketing asset production leverage real-time rendering to compress iteration cycles.
- TV Commercials:Brand-agency relationships prioritize rapid turnaround and direct client attendance at review sessions.
- Live Events:Real-time graphics for broadcast sports and concert visualizations demand frame-synched multi-display output.
Film production commands the highest technical specification bar; game development shows the most rapid workflow transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and London host the densest concentrations of facial capture specialists and real-time engine technical directors. These talent clusters anchor premium service contracts for streaming platform original series and theatrical tentpole releases.
United States
Atlanta volume stages and Los Angeles studio lots command the largest share of LED virtual production contracts for Netflix and Disney+ original series. The California Film Commission tax credit steers post-production spend toward in-state facilities. Wētā FX maintains proprietary facial capture operations in Los Angeles serving franchise creature animation.
United Kingdom
London facilities capture overflow high-end compositing and creature work from US streaming commissions. The BFI certification tax relief delivers 25% post-production credits attracting tentpole VFX contracts. Soho-based houses anchor the European concentration of 8K finishing and HDR color grading infrastructure.
India
Mumbai and Hyderabad facilities absorb labor-intensive rotoscoping and matchmove overflow from US studios seeking cost arbitrage. The country's national film certification framework governs theatrical content standards. Bangalore technical directors increasingly integrate USD pipeline workflows for international co-productions.
France
Paris-based facilities secure theatrical-grade VFX finishing contracts mandated by CNC funding eligibility criteria. The EU AI Act's training data transparency requirements reshape generative model deployment across European co-productions. Île-de-France houses build proprietary licensed photography datasets to maintain subsidy qualification.
Canada
Vancouver and Toronto facilities leverage federal and provincial tax incentives to anchor mid-budget feature and streaming series work. The Canada Media Fund and provincial production services tax credits concentrate volume-stage and compositing contracts. Ontario-based houses increasingly deploy real-time engine pipelines for previsualization services.
VFX Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered vendor structure. Full-service houses maintaining permanent LED volume stages and render farm infrastructure bid against agile boutiques specializing in narrow technical disciplines. Three archetypes dominate: integrated studio-owned facilities with captive production slates, independent premium houses with proprietary technology, and cost-efficient offshore overflow specialists. Competitive dynamics center on strategic partnerships with streaming platforms and technology licensing arrangements for real-time engine integration.
Within the integrated studio tier, ILM and Walt Disney Animation Studios exemplify facilities with deep production slate integration and proprietary virtual production technology. Framestore and DNEG represent independent premium houses competing on creature animation and high-end compositing credentials. These named entities anchor competitive positioning without exhaustive market share claims.
| Leading Market Players |
|---|
| Wētā FX |
| PhantomFX |
| DNEG |
| Lux Aeterna |
| Milk VFX |
| ILM |
| Walt Disney Animation Studios |
| Tippett Studio |
| Framestore |
| Others |
Value Chain & Pricing Dynamics
Cloud compute spot pricing for GPU render nodes cascades through vendor tiers, with Los Angeles facilities passing volatility to streaming platform clients while Mumbai houses absorb fixed-cost rotoscoping contracts insulated from per-frame licensing swings.
Pricing Analysis
The bundled-vs-unbundled service split separates premium houses commanding time-and-materials rates with velocity bonuses from offshore rotoscoping vendors locked into fixed-bid overflow contracts. Price differentiation hinges on real-time engine integration depth and 8K theatrical certification tier. Pricing pressure stems from cloud render licensing volatility squeezing boutique margin predictability. Advertising agencies and mid-budget television productions exhibit highest price sensitivity, while streaming platforms with volume-stage mandates show lowest.
Supply Chain Analysis
Pipeline technical director scarcity in Los Angeles, London, and Vancouver constrains facility expansion timelines and technology refresh cycles. Raw material dependencies center on NVIDIA GPU hardware, Autodesk and Chaos software licensing, and proprietary motion capture database assets. Supply chain risk concentrates in single-source vulnerability for facial capture specialists and real-time engine technical directors. Distribution runs through direct studio relationships for premium work and tiered subcontractor networks for labor-intensive tasks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in virtual production volume-stage operations where LED infrastructure depreciation meets streaming platform demand for same-day final-pixel delivery, compressing traditional location shooting cost structures.
For Market Incumbents: To counter generative AI diffusion tools threatening creature design and environment generation workflows, ILM and Wētā FX should deepen proprietary training dataset investments and StageCraft technology licensing. Captive LED volume stage networks in Atlanta and London anchor client retention against agile boutiques. For New Entrants and Emerging Players: Launch via previsualization services for streaming platform greenlight decisions, exploiting real-time engine pipeline gaps before volume-stage capital requirements. White-space targets include Unreal Engine technical direction for mid-budget features and USD pipeline integration for India-US co-productions. For Investors and Strategic Acquirers: Consolidation pressure builds where boutique facilities face stranded CPU render farm assets and technical director talent scarcity simultaneously. Long-term viability favors asset-light previsualization specialists and proprietary facial capture technology holders. The signal to watch is real-time engine pipeline adoption rates displacing overnight batch processing contracts.| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Stage Expansion | Netflix and Disney+ mandates for virtual production capacity concentrate contracts in Atlanta and London facilities. |
| Proprietary Training Dataset Development | EU AI Act compliance for French CNC subsidy eligibility requires licensed photography provenance documentation. |
| Previsualization Service Launch | Unreal Engine workflows for streaming platform greenlight decisions open revenue before traditional post-production. |
| Pipeline Technical Director Acquisition | USD and real-time engine proficiency scarcity delays facility technology refreshes and contract delivery. |
| India Overflow Capacity Buildout | Mumbai and Hyderabad rotoscoping arbitrage captures labor-intensive work from US studios seeking cost compression. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with VFX supervisors, pipeline technical directors, streaming platform commissioning executives, and post-production facility CFOs with secondary validation against SEC filings from technology vendors, BFI and CNC subsidy disbursement records, and cloud compute pricing indices. Bottom-up facility revenue estimates triangulated against top-down streaming content budget allocations.
Segment-weighting distributed analytical emphasis across service type, end user, and technology dimensions, with particular attention to virtual production adoption curves and generative AI deployment rates across the analysis window. CAGRs derived from facility capacity expansion announcements, streaming platform original content commissioning patterns, and LED volume stage deployment timelines. Real-time engine pipeline displacement rates and EU AI Act compliance cost impacts informed scenario boundaries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under generative AI copyright litigation expansion or cloud compute spot pricing sustained volatility. Assumptions reflect current streaming platform budget trajectories and subsidy regime stability. Material deviation in regulatory enforcement intensity or real-time engine technical director supply warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Stock Video Market
Digital Media
Digital Media Production Software Market
Digital Media
Anime Derivatives Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Global Music Video Production Market
Digital Media
Media and Entertainment Market
Digital Media
Social TV Market
Digital Media
Digital Media Switchers Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
ACGN Subculture Market
Digital Media
Digital Music Services Market
Digital Media
Digital Content Locker Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
4K Content Market
Digital Media
India Webtoons Market
Digital Media
Global Online Movie Ticketing Services Market