
 Mobile Entertainment Market | 2026-2036
Mobile Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Entertainment Market Outlook
The transition from single-source content licensing to multi-source aggregation is shifting how platforms secure programming rights. Netflix, Inc. leverages its original production pipeline to reduce dependency on external studios. Spotify Technology S.A. anchors its growth in exclusive podcast deals and artist direct-licensing arrangements. Apple Inc. competes through tight hardware-software integration that locks users into its services ecosystem.
Mobile entertainment encompasses digitally delivered interactive and passive content consumed on portable connected devices, typically requiring continuous low-latency data transmission and adaptive bitrate streaming protocols to maintain quality across variable network conditions. Its primary commercial purpose is to monetize user attention through subscription fees, advertising impressions, or in-app transactions. Streaming services and games capture the dominant share of revenue, with music apps representing a mature but high-loyalty segment where subscriber retention exceeds new customer acquisition economics. The freemium subscription model generates the largest addressable user base, though subscription-based tiers extract the highest per-user lifetime value.
FCC guidelines on net neutrality and transparency shape how US carriers throttle or prioritize entertainment traffic, while GDPR and the EU AI Act in Europe impose strict boundaries on personalized content targeting and automated recommendation systems. In India, TRAI regulations on data pricing and content localization mandates influence platform market entry strategies. Stakeholders must monitor evolving algorithmic accountability rules and spectrum allocation policies that directly determine service quality thresholds and competitive differentiation.
Market Dynamics
The mobile entertainment sector is experiencing a fundamental restructuring as algorithmic content curation meets tightening data sovereignty requirements across major jurisdictions. Platforms now face simultaneous pressure to personalize experiences while restricting cross-border data flows and automated decision-making transparency.
Growth Catalysts
- 5G network densification:India's TRAI-mandated spectrum reforms and carrier infrastructure investments are slashing latency thresholds for real-time interactive content. Mobile-first subscribers in tier-2 cities now stream adaptive bitrate video without buffering interruptions.
- GDPR Article 22 compliance tooling:European platforms are converting regulatory overhead into competitive differentiation by marketing transparent recommendation logic. User control interfaces have become subscription conversion assets rather than cost centers.
- Localized content production:Vernacular-language original programming in Hindi, Tamil, and Telugu is capturing first-time subscribers outside India's metropolitan centers. Regional studio partnerships reduce customer acquisition costs compared to dubbed international catalogs.
Market Restraints
- Input cost volatility:Cloud compute and CDN bandwidth pricing fluctuations compress margins for ad-supported tiers. Providers lack pricing power to pass through infrastructure cost swings to zero-fee users.
- Supply concentration risk:Apple and Google app store duopoly control over in-app payment rails imposes 15-30% revenue shares. Platform dependency limits direct subscriber relationships and payment data ownership.
- Technical limitation:Device fragmentation across Android OEMs forces costly quality assurance matrices. Adaptive streaming protocols fail on entry-level chipsets prevalent in price-sensitive segments.
Strategic Opportunities
- Underpenetrated geography:Indonesia's 17,000-island archipelago presents whitespace for satellite-terrestrial hybrid delivery models. Localized Bahasa content libraries remain thin relative to addressable population scale.
- Technology convergence:Edge computing and on-device AI inference are enabling real-time content personalization without cloud round-trips. Latency-sensitive gaming and interactive formats benefit from distributed processing architectures.
- Regulatory tailwind:India's PLI scheme for electronics manufacturing is driving domestic smartphone production cost curves down. Affordable 5G handset penetration accelerates addressable market expansion.
Industry Challenges
- Skill scarcity in explainable AI:Engineering teams capable of building interpretable recommendation systems that satisfy EU AI Act documentation requirements command premium compensation. Talent competition with fintech and autonomous vehicle sectors intensifies recruitment friction.
- Legacy rights management integration:Studios' decades-old contract databases lack machine-readable licensing terms. Automated content availability checks across territorial windows require manual legal review, slowing catalog expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Entertainment Market |
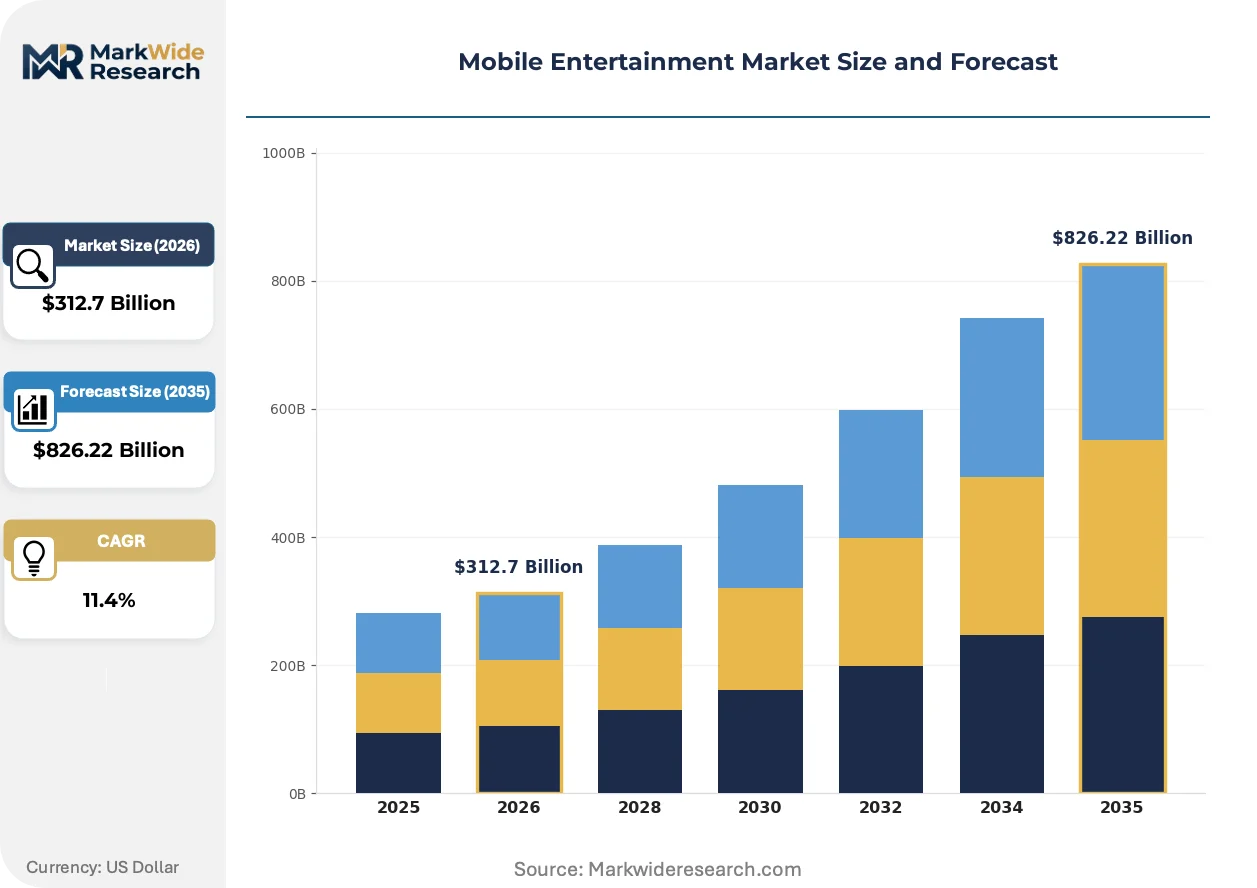
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Games, Streaming Services, Music Apps, Video Apps End User: Teens, Young Adults, Families, Seniors Subscription Model: Freemium, Subscription-based, Pay-per-view, Ad-supported Device Type: Smartphones, Tablets, Wearables, Laptops |
| Companies Covered | Netflix, Inc., Spotify Technology S.A., Apple Inc., Electronic Arts Inc., Meta Platforms, Inc., Google LLC, Amazon.com, Inc., Take-Two Interactive Software, Inc., Tencent Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Entertainment Market Strategic Shifts
Content delivery architectures are fragmenting as platforms race to reduce cloud dependency and respond to data localization mandates. Three concurrent developments are redefining technical infrastructure and commercial relationships across the value chain.
Edge caching and on-device machine learning is modularizing how streaming services distribute computational workloads. Tier-1 carriers in Germany and South Korea are deploying multi-access edge computing nodes within 50 kilometers of subscriber clusters. Gaming and live sports platforms are adopting these distributed architectures fastest, compressing round-trip latency below 20 milliseconds for interactive features.
The EU AI Act's risk classification framework for recommendation algorithms is forcing structural changes in content curation teams. Platforms serving European users must document training data provenance and maintain human oversight protocols for high-risk personalization systems. Music and video services with substantial EU subscriber bases are establishing dedicated algorithmic accountability functions, diverting engineering resources from feature development.
Young adult subscribers are abandoning long-form subscription commitments in favor of modular, event-based purchasing. Live virtual concert tickets, limited-series unlocks, and battle pass structures are displacing annual plans in acquisition funnels. This behavioral shift is most pronounced in Brazil and Mexico, where mobile wallet penetration enables frictionless microtransactions without credit card infrastructure.
Mobile Entertainment Market Segmentation
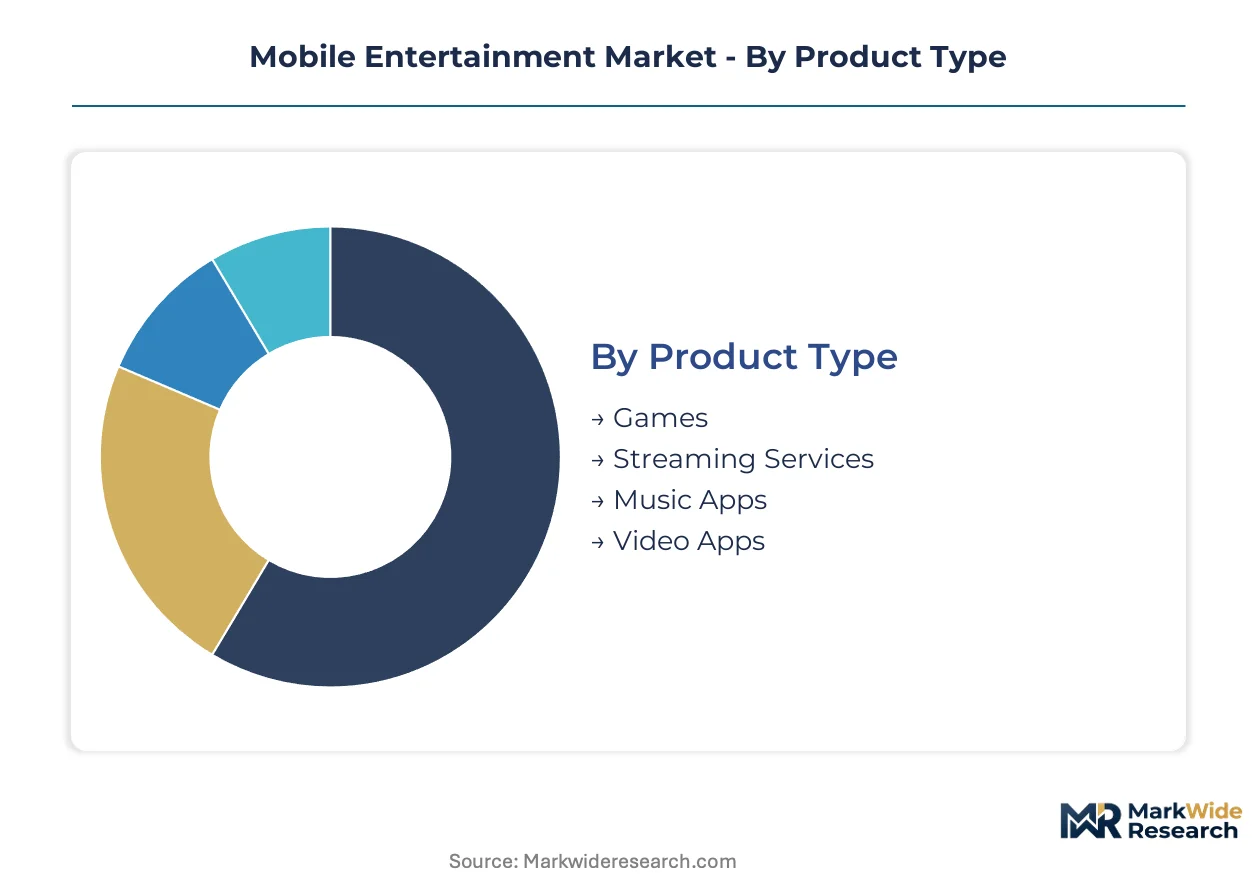
Mobile entertainment monetization depends on matching content format, user life stage, and payment willingness to device capabilities. Segmentation reveals where infrastructure investments and licensing spend concentrate.
Product Type:
Supply concentration in interactive content pipelines is reshaping platform investment priorities.
- Games:Real-time multiplayer engines and cloud-rendered graphics demand sub-50ms latency. Indian tier-2 cities and Southeast Asian mobile-first gamers drive revenue concentration as affordable 5G handsets penetrate price-sensitive segments. Battle pass and gacha monetization models extract higher per-user spend than subscription alternatives.
- Streaming Services:Adaptive bitrate protocols and DRM infrastructure define technical moats. Young adult subscribers in Brazil and Mexico favor event-based purchasing over annual commitments, compressing customer lifetime value metrics.
- Music Apps:Audio compression standards and offline caching differentiate user experience. High retention economics in mature markets offset saturated acquisition channels.
- Video Apps:Short-form vertical formats dominate engagement minutes. ByteDance and Meta algorithmic feeds displace traditional studio content in attention capture.
Games absorb the bulk of installed capacity; Streaming Services is expanding most quickly.
End User:
Generational cohorts exhibit divergent payment friction tolerance and content format preferences.
- Teens:Social discovery mechanics and peer-network effects drive platform selection. Microtransaction-native spending patterns in Roblox and Fortnite ecosystems normalize frictionless purchasing without credit infrastructure.
- Young Adults:Modular content consumption and subscription fatigue characterize behavioral profiles. Live virtual concerts and limited-series unlocks displace annual plans in acquisition funnels across Latin American markets.
- Families:Multi-profile account sharing and parental control features determine platform stickiness. Content breadth across age-appropriate categories justifies premium tier pricing.
- Seniors:Simplified interfaces and curated content libraries reduce onboarding friction. Voice navigation and larger touch targets accommodate accessibility requirements.
Young Adults command the largest addressable spend; Teens are gaining share fastest.
Subscription Model:
Margin compression in ad-supported tiers is forcing portfolio diversification across revenue architectures.
- Freemium:Zero-barrier entry converts to paid tiers at 2-5% rates. Cloud compute and CDN bandwidth pricing volatility squeezes margins for non-paying user bases.
- Subscription-based:Annual commitments and auto-renewal mechanics maximize lifetime value. EU AI Act transparency requirements add compliance overhead to personalized recommendation systems.
- Pay-per-view:Event-based purchasing captures occasional viewers without subscription friction. Live sports and virtual concert formats monetize scarcity and temporal exclusivity.
- Ad-supported:Programmatic inventory and first-party data targeting offset lower per-user yield. Apple's ATT framework and GDPR consent requirements degrade attribution precision.
Freemium captures the widest user base; Subscription-based extracts the highest per-account value.
Device Type:
Hardware-software integration strategies by Apple and Google fragment addressable market access.
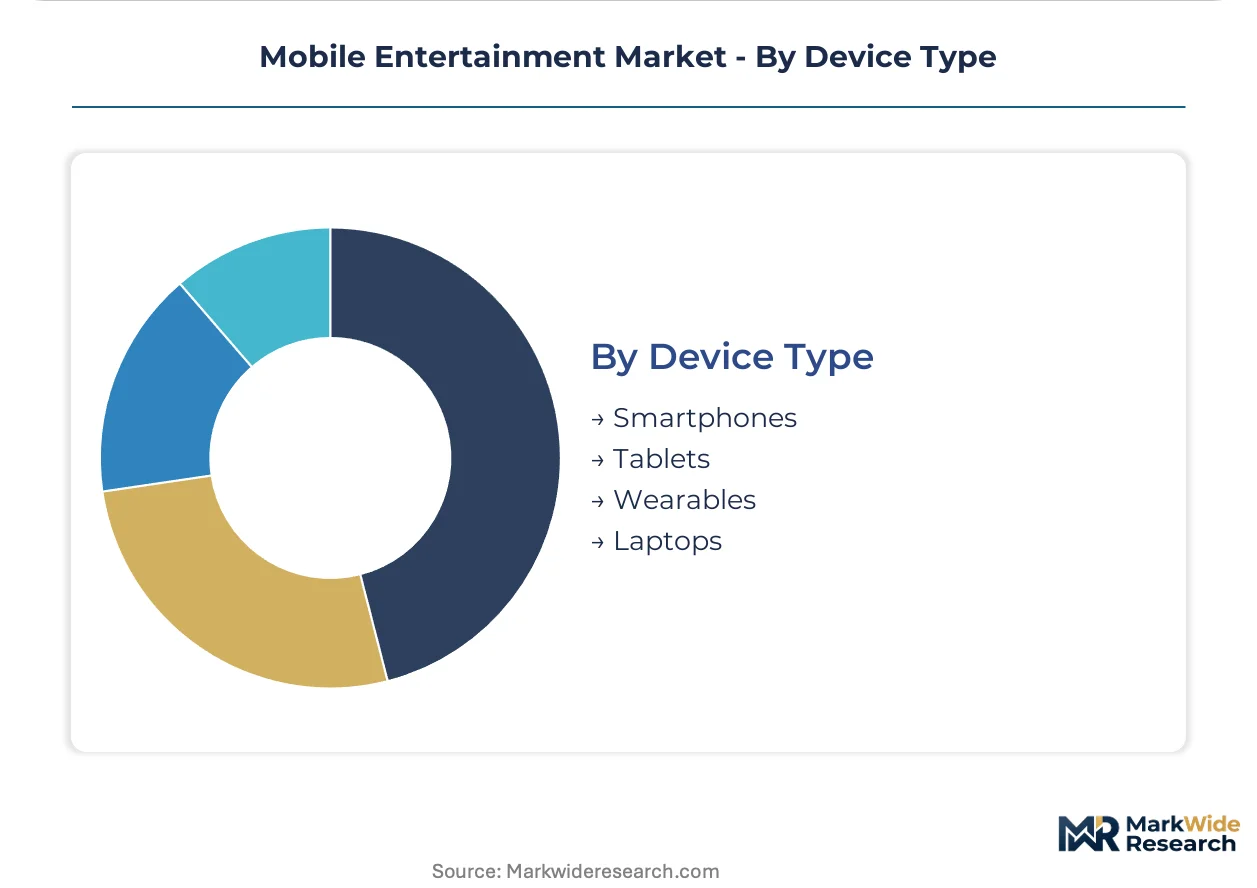
- Smartphones:Dominant consumption endpoint with 6-inch OLED panels and stereo audio. India's PLI scheme for electronics manufacturing accelerates affordable 5G handset penetration.
- Tablets:Larger screens enable multi-window productivity alongside entertainment. Apple iPadOS and Samsung DeX differentiate through stylus and keyboard accessory ecosystems.
- Wearables:Audio-first formats and fitness-integrated content consumption expand addressable moments. Spotify and Apple Music offline sync capabilities reduce phone dependency.
- Laptops:Cross-platform continuity features bridge mobile and desktop experiences. Intel Evo and Qualcomm Snapdragon X Elite platforms compete on battery endurance metrics.
Smartphones absorb the bulk of session minutes; Wearables are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center clusters in Northern Virginia and content production hubs in Mumbai anchor mobile entertainment infrastructure investment. Carrier densification and spectrum allocation policies determine service quality thresholds across subscriber markets.
United States
FCC net neutrality guidelines and spectrum auction outcomes shape carrier traffic prioritization policies. Content delivery networks concentrate in Ashburn, Virginia and Dallas-Fort Worth metroplexes. Edge computing deployments by Verizon and AT&T reduce latency for interactive gaming formats in these clusters.
India
TRAI-mandated spectrum reforms and affordable data pricing drive subscriber acquisition in tier-2 cities. The PLI scheme for electronics manufacturing accelerates domestic 5G handset production cost curves. Mumbai and Hyderabad host regional content studios producing Hindi and Telugu original programming.
Germany
GDPR Article 22 compliance requirements and EU AI Act risk classifications reshape recommendation algorithm architectures. Multi-access edge computing nodes by Deutsche Telekom compress streaming latency below 20 milliseconds. Berlin and Munich clusters concentrate explainable AI engineering talent for platform accountability functions.
Brazil
Mobile wallet penetration enables frictionless microtransaction purchasing without credit card infrastructure. ANATEL spectrum policies influence carrier infrastructure investment priorities. São Paulo and Rio de Janeiro metropolitan areas concentrate live virtual concert production and event-based content monetization.
South Korea
5G network densification by SK Telecom and KT Corporation delivers sub-50ms latency for real-time multiplayer engines. Korea Communications Commission content regulations shape platform localization requirements. Seoul Capital Area and Busan-Ulsan corridor anchor gaming studio clusters and cloud-rendered graphics pipelines.
Mobile Entertainment Market Competitive Environment
Exclusive content licensing dominates the current landscape as platforms compete for subscriber attention. The market structures around three tiers: vertically integrated technology conglomerates, specialized streaming pure-plays, and mobile-first gaming publishers. Strategic archetypes include hardware-software ecosystem builders, original production pipeline operators, and algorithmic feed optimizers. Portfolio diversification and geographic expansion constitute the dominant competitive moves as players seek to reduce dependency on single revenue architectures.
Within the vertically integrated tier, Apple Inc. and Google LLC exemplify ecosystem lock-in strategies through hardware-software-service integration. Netflix, Inc. and Spotify Technology S.A. occupy positions as pure-play streaming specialists competing through original content pipelines and exclusive licensing arrangements. Electronic Arts Inc. and Take-Two Interactive Software, Inc. represent mobile-first gaming publishers monetizing through battle pass and live service architectures. Tencent Holdings Ltd. anchors the Asia-based technology conglomerate archetype with diversified interactive entertainment holdings.
| Leading Market Players |
|---|
| Netflix, Inc. |
| Spotify Technology S.A. |
| Apple Inc. |
| Electronic Arts Inc. |
| Meta Platforms, Inc. |
| Google LLC |
| Amazon.com, Inc. |
| Take-Two Interactive Software, Inc. |
| Tencent Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
Edge computing infrastructure deployment is compressing content delivery costs while concentrating supplier power among Tier-1 carriers and hyperscale cloud providers. This technical transition simultaneously enables tiered service quality differentiation and locks platforms into long-term capacity commitments with limited alternative sourcing.
Pricing Analysis
Service-bundling architectures separate base streaming access from premium features like offline downloads, 4K resolution, and simultaneous device streams. Three-tier pricing structure across premium, standard, and economy levels captures divergent willingness-to-pay across Indian tier-2 cities and European metropolitan markets. Price differentiation hinges on content resolution tiers and after-sales support availability, with family plan multipliers reflecting account-sharing tolerance. Pricing pressure stems from cloud compute and CDN bandwidth cost volatility that platforms cannot pass through to ad-supported user bases. Young adult subscribers in Latin America exhibit highest price sensitivity, while enterprise licensing for commercial venue streaming shows lowest elasticity.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and TRAI-mandated data localization rules are reshaping content infrastructure sourcing toward domestic assembly and in-country server deployment. Geographic supply concentration centers on India for affordable 5G handset production, South Korea for OLED display panels, and Taiwan for advanced mobile chipsets. Raw material dependencies span rare earth elements for battery components, high-purity silicon for semiconductor fabrication, and cobalt for energy-dense power cells. Single-source vulnerability runs through concentrated foundry capacity for application processors. Distribution runs through carrier-direct channels, OEM pre-installation agreements, and app store duopoly gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Explainable AI engineering talent scarcity and on-device inference hardware bottlenecks are constraining personalization capability expansion, propping pricing power for platforms with captive technical capacity.
For Market Incumbents: Lock in exclusive content pipelines through multi-year regional studio partnerships in Hindi, Tamil, and Telugu markets. Prioritize backward integration into edge computing infrastructure to reduce carrier dependency for latency-sensitive formats. Defend against modular subscription fatigue by anchoring annual plans with exclusive live event access. For New Entrants and Emerging Players: Begin with satellite-terrestrial hybrid delivery models targeting Indonesia's 17,000-island archipelago where localized Bahasa content libraries remain underdeveloped. Focus initial penetration on battle pass and gacha monetization formats that extract higher per-user spend than subscription alternatives. Pursue carrier billing integration to bypass credit card infrastructure gaps in Southeast Asian markets. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by technology conglomerates seeking hardware-software-service integration. Long-term viability favors original production pipeline operators with territorial exclusivity in high-growth demographics. Monitor EU AI Act enforcement patterns as inflection indicator for compliance cost escalation and competitive moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Pipeline Expansion | Regional studio partnerships in India reduce licensing dependency and customer acquisition costs. |
| Edge Computing Infrastructure Deployment | Multi-access edge nodes by Deutsche Telekom and Verizon compress latency below 20 milliseconds. |
| Algorithmic Accountability Function Establishment | Dedicated EU AI Act compliance teams convert regulatory overhead into subscription conversion assets. |
| Vernacular Language Content Localization | Hindi, Tamil, and Telugu original programming captures first-time subscribers outside metropolitan centers. |
| Carrier Billing Integration Partnership | Mobile wallet penetration in Brazil and Mexico enables frictionless microtransaction monetization. |
Study Parameters
Independent corroboration across platform engineering executives, content licensing directors, carrier infrastructure planners, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from TRAI spectrum allocation records, SEC 10-K filings, EU AI Act implementation guidance, and App Annie usage analytics establishes measurement reliability. Bottom-up subscriber modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical 5G deployment trajectories and streaming adoption curves calibrated the projection framework. Segmentation dimensions span content format, generational cohort, subscription architecture, and device category across the modeling period. CAGRs derive from fitted growth curves applied to subscriber and revenue per user inputs. Cloud infrastructure capex disclosures and regional spectrum auction outcomes inform capacity expansion assumptions.
Underlying measurement precision varies by segment; games and streaming services carry tighter precision than emerging wearable formats. Forecasts embed assumptions regarding carrier infrastructure investment continuity and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Asia Pacific Photography Service Market
Digital Media
Asia-Pacific Animation Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Manga Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Stream Hosting Market
Digital Media
3D Animation Market
Digital Media
Photography Services Market
Digital Media
North America Photographic Services Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Global Animation Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Global Digital Painting Market
Digital Media
Media Coding Service Market
Digital Media
Europe Online Video Platform Market