
 Projection Mapping Market | 2026-2036
Projection Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Projection Mapping Market Intelligence
Real-time 3D rendering integration with spatial computing platforms is reshaping how projection mapping systems are architected for live environments. Panasonic Corporation leverages its broadcast heritage to sustain dominance in large-venue laser installations. Barco NV anchors its position through specialized image processing hardware for mission-critical events. Disguise Technologies Limited differentiates via software-defined workflows that control media servers across complex multi-surface setups.
Projection mapping deploys high-lumen video projectors, edge-blending processors, and spatial calibration software to register imagery onto irregular three-dimensional surfaces with sub-pixel accuracy. The technology serves commercial purposes spanning brand activation, cultural preservation, and immersive entertainment where flat-screen displays prove inadequate. DLP technology leads in brightness-critical applications while laser sources displace lamp-based systems due to reduced maintenance cycles and color stability. Live Events commands the largest application share though Art Installations represent the fastest-growing segment as museums pursue experiential differentiation.
FCC equipment authorization governs electromagnetic emissions from projection hardware sold in the United States, while CE marking mandates safety and interoperability standards across European deployments. The EU AI Act introduces compliance obligations for automated content adaptation systems that adjust projections in real time. Stakeholders must monitor how evolving energy efficiency regulations and right-to-repair legislation reshape hardware lifecycle economics and service revenue models.
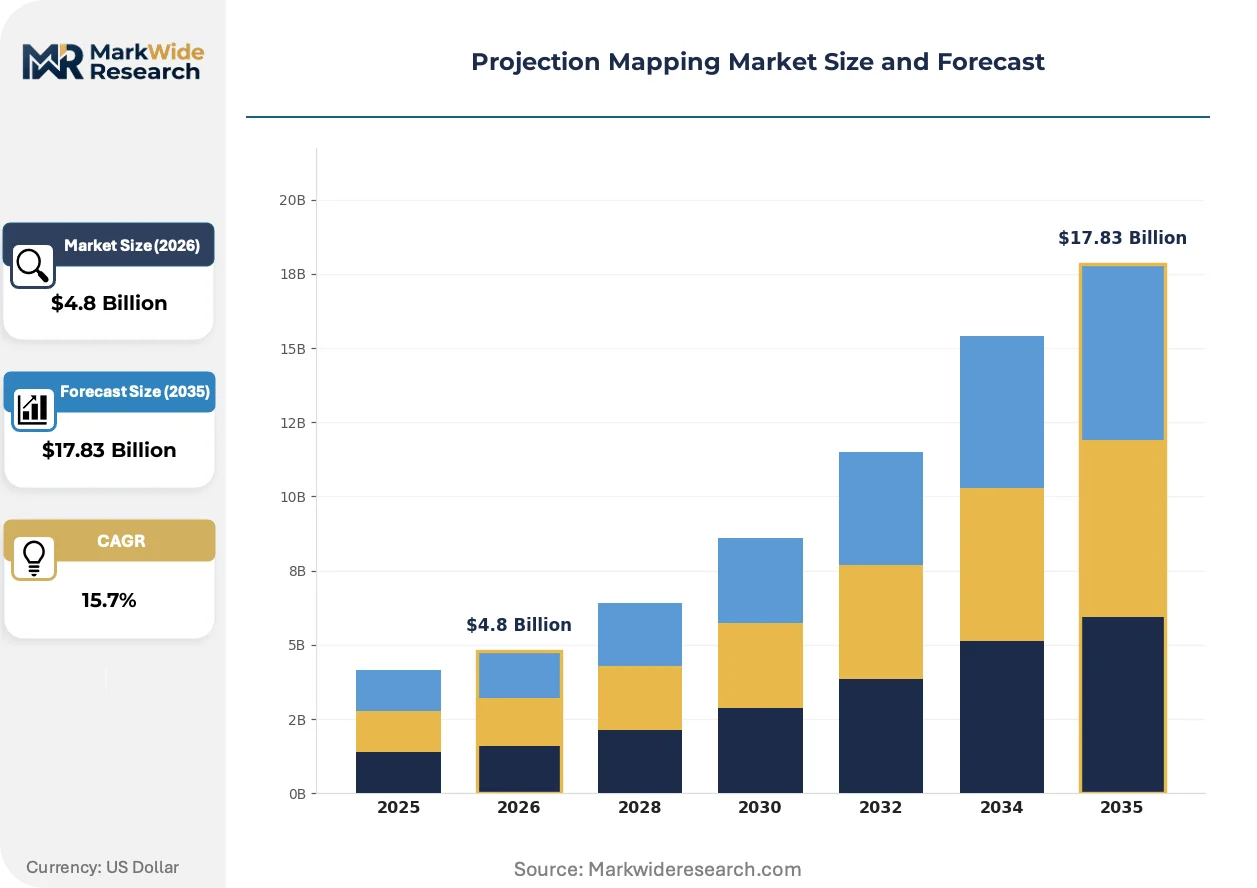
Market Dynamics
Live events and entertainment venues are accelerating adoption of immersive visual technologies, with real-time 3D rendering integration reshaping how projection mapping systems are architected for complex spatial environments.
Growth Catalysts
- EU AI Act:Automated content adaptation systems for digital displays across Europe face new compliance obligations, creating standardized procurement frameworks that favor certified hardware-software bundles.
- Laser phosphor sources:Museums and cultural institutions in Germany drive replacement cycles as reduced maintenance intervals and color stability justify premium positioning against lamp-based legacy fleets.
- Edge-blending processors:Mission-critical events demand sub-pixel registration accuracy across irregular surfaces, pulling investment into specialized image processing hardware.
Market Restraints
- High-lumen DLP engine concentration:Texas Instruments maintains captive supply of digital micromirror devices, creating single-source dependency for brightness-critical applications above 30,000 lumens.
- FCC equipment authorization friction:Electromagnetic emissions testing for laser-equipped projectors extends lead times by 8-14 weeks for United States deployments, compressing event production windows.
- LED video wall substitution:Direct-view fine-pitch displays capture daylight-viewable applications where ambient light rejection requirements exceed projector capability thresholds.
Strategic Opportunities
- India cultural infrastructure:Heritage site digitization initiatives under the Archaeological Survey of India create demand for weather-resistant outdoor projection systems at monument complexes.
- Spatial computing convergence:LiDAR-based environmental scanning integrated with real-time render engines enables dynamic surface mapping without pre-calibration, opening ephemeral installation formats.
- Right-to-repair legislation:European Union mandates for component accessibility and diagnostic software availability reshape service revenue models toward modular upgrade paths rather than full unit replacement.
Industry Challenges
- Spatial calibration expertise scarcity:Multi-surface projection alignment requires specialized technicians proficient in photogrammetry and mesh warping algorithms, with training pipelines lagging deployment velocity.
- Legacy media server integration:Existing venue infrastructure built on proprietary control protocols creates friction when adopting software-defined workflow platforms that demand IP-based networking.
- Energy efficiency certification timelines:evolving Ecodesign requirements for standby power and luminous efficacy impose retesting burdens on product portfolios with 18-24 month development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Projection Mapping Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $17.83 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Live Events, Advertising, Art Installations, Retail Displays Technology: DLP, LCD, Laser, LED End User: Entertainment Venues, Marketing Agencies, Museums, Educational Institutions Solution: Software, Hardware, Services, Content Creation |
| Companies Covered | Christie Digital Systems USA, Inc., BenQ Corporation, Panasonic Corporation, NEC Display Solutions, ViewSonic Corporation, Seiko Epson Corporation, Sony Corporation, Disguise Technologies Limited, Barco NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Projection Mapping Market Strategic Shifts & Innovations
Three forces are restructuring competitive positioning in projection mapping: solid-state illumination architectures, algorithmic content governance frameworks, and procurement models that unbundle hardware ownership from creative production services.
Solid-state laser-illuminated projectors are rendering obsolete lamp-based systems in permanent installation contexts. Museums and brand experience centers in North America and Europe now specify 20,000-hour maintenance-free operation as a baseline procurement criterion. This shift compresses total cost-of-ownership calculations and redirects capital toward content production rather than hardware lifecycle management.
The EU AI Act introduces compliance obligations for automated content adaptation systems that adjust projections in real time based on audience detection or environmental sensors. Hardware manufacturers must document algorithmic decision pathways and bias mitigation protocols to maintain CE marking eligibility. Live Events segment buyers in Germany, France, and Italy now require supplier attestations covering these AI governance dimensions alongside traditional safety certifications.
Service unbundling is fragmenting how venues acquire projection capability. Rather than capital purchase of projector fleets, cultural institutions and corporate event spaces increasingly contract for integrated creative-technical packages where hardware is provisioned as a managed service. This pattern concentrates most visibly in United Kingdom and Netherlands markets, where specialist production companies retain asset ownership and charge per-activation fees that align vendor incentives with uptime performance.
Projection Mapping Market Segmentation
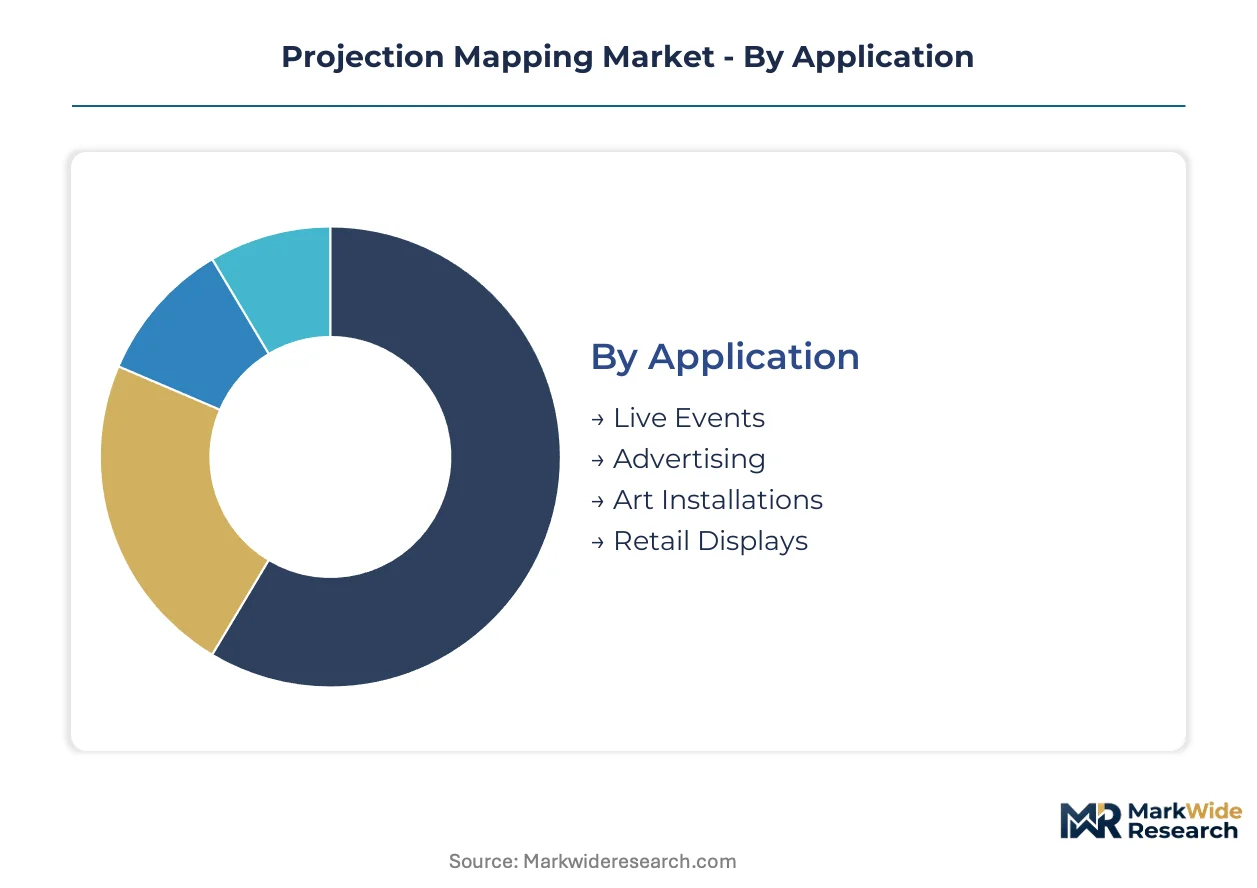
Segmentation in projection mapping reveals how technical specifications, procurement models, and venue requirements diverge across deployment contexts. Understanding these splits illuminates where capital concentrates versus where operational expenditure dominates.
Application:
Application segmentation distinguishes between revenue-driven commercial activations and institution-funded cultural programming, with divergent procurement cycles and technical specifications shaping vendor engagement strategies.
- Live Events:Temporary installations at concerts, product launches, and corporate gatherings demand rapid deployment protocols and redundant hardware configurations. Germany's trade show circuit and touring entertainment infrastructure in the United Kingdom sustain the highest deployment density, with procurement favoring rental-service models over capital purchase.
- Art Installations:Permanent or semi-permanent museum and gallery deployments emphasize color accuracy, silent operation, and conservation-grade illumination. French cultural institutions and Italian heritage sites are expanding commissioning budgets for experiential differentiation, though extended procurement timelines strain vendor cash conversion cycles.
- Advertising:Brand activations in transit hubs and retail environments prioritize daylight visibility and weather resistance.
- Retail Displays:Flagship store installations in luxury sectors integrate projection with architectural elements for seasonal campaign rotation.
Live Events commands the established base. The steepest expansion runs through Art Installations.
Technology:
Technology choices in projection mapping orbit around luminosity requirements, maintenance tolerance, and color gamut specifications that vary by venue permanence and ambient light conditions.
- DLP:Digital micromirror device arrays from Texas Instruments enable brightness outputs exceeding 30,000 lumens for large-venue applications. The technology dominates outdoor spectaculars and arena-scale events where ambient light rejection proves critical, though single-source chip supply creates procurement vulnerability.
- Laser:Solid-state phosphor and RGB laser architectures eliminate lamp replacement cycles and deliver chromatic stability across 20,000-hour operational lifespans. German museums and North American brand experience centers specify laser as baseline for permanent installations, redirecting lifecycle budgets toward content production.
- LCD:Liquid crystal panels serve cost-sensitive applications where maximum brightness thresholds fall below 10,000 lumens.
- LED:Direct-view emissive displays compete for daylight-viewable applications, particularly in retail and transit advertising contexts where projector throw distances prove impractical.
DLP anchors high-brightness applications. Laser is gaining share fastest across permanent installation contracts.
End User:
End user categories reflect divergent procurement sophistication, with entertainment venues operating on event-driven rental models while museums navigate public-sector procurement frameworks.
- Entertainment Venues:Stadiums, arenas, and performing arts centers deploy projection for pre-show spectaculars and interstitial programming. The United Kingdom's touring production infrastructure and German festival circuits sustain the densest hardware utilization rates, with technical directors prioritizing rapid rigging protocols over pixel density specifications.
- Museums:Cultural institutions balance conservation requirements against experiential mandates, specifying low-UV output and thermal management for artifact protection. Italian archaeological museums and French national galleries are commissioning immersive recontextualization projects for permanent collections.
- Marketing Agencies:Creative production houses orchestrate temporary brand activations with compressed deployment windows.
- Educational Institutions:Universities and research centers utilize projection for visualization laboratories and public science communication.
Entertainment Venues represent the volume anchor. Museums are climbing the fastest as experiential funding expands.
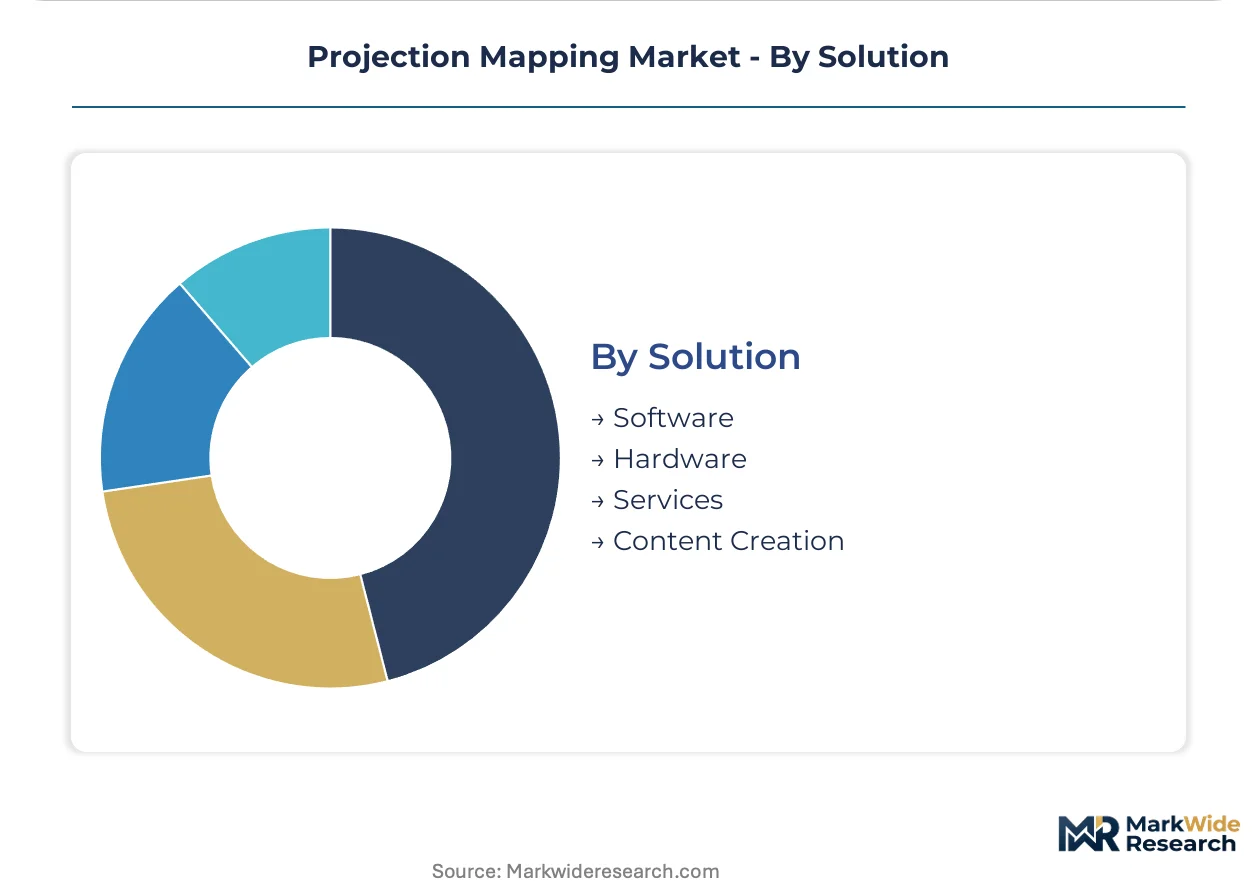
Solution:
Solution segmentation tracks the unbundling of projection capability from hardware ownership, with service models capturing margin expansion opportunities in software and creative production.
- Hardware:Projector engines, media servers, and edge-blending processors constitute the capital foundation of installations. Procurement concentrates in Germany and the United States for high-lumen laser systems, though right-to-repair legislation in the European Union is reshaping lifecycle economics toward modular upgrade paths.
- Software:Spatial calibration, real-time rendering, and show control platforms enable complex multi-surface alignment. The EU AI Act imposes compliance documentation requirements on automated content adaptation systems, favoring vendors with established algorithmic governance frameworks.
- Services:Technical production, on-site operation, and maintenance contracts align vendor incentives with uptime performance.
- Content Creation:Custom motion design and 3D asset production for specific architectural geometries or narrative objectives.
Hardware retains the revenue base. Software is expanding most quickly as procurement shifts toward subscription and managed-service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German projector manufacturers supply high-lumen laser systems to museums and trade show venues across France, Italy, and the United Kingdom. This trade corridor channels precision-engineered hardware into Western European cultural infrastructure while regulatory harmonization under the EU AI Act standardizes procurement frameworks.
Germany
Messe Frankfurt and Hannover Fairground drive rental-service demand for rapid-deployment projection rigs. The EU AI Act mandates algorithmic documentation for automated content adaptation systems, favoring certified hardware-software bundles. Bavaria's Munich cluster anchors permanent installation expertise for museum-grade laser phosphor systems.
United Kingdom
Touring entertainment infrastructure in London and Manchester sustains dense hardware utilization for pre-show spectaculars. GDPR compliance requirements shape content distribution protocols for audience-responsive displays. The Southeast England production corridor concentrates specialist technical crews proficient in multi-surface alignment.
France
Parisian national galleries and Lyon-based cultural institutions expand commissioning budgets for experiential recontextualization projects. CE marking mandates safety and interoperability standards for European deployments. The Île-de-France region hosts the densest concentration of conservation-grade illumination specifications for artifact protection.
Italy
Archaeological museums in Rome and Florence pursue immersive digitization for permanent collections. The country's national cultural heritage regulator oversees conservation standards for UV-sensitive projection environments. Northern Italy's Milan design district integrates projection with architectural elements for luxury retail activations.
United States
Las Vegas entertainment venues and Orlando theme parks deploy projection for interstitial programming and spectaculars. FCC equipment authorization governs electromagnetic emissions from laser-equipped hardware, extending lead times by 8-14 weeks. California's Bay Area and Los Angeles production clusters concentrate real-time rendering expertise for spatial computing convergence.
Projection Mapping Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiers. Broadcast heritage conglomerates and display technology manufacturers anchor the consolidated upper tier, while software-defined workflow specialists and regional projector assemblers occupy mid-market positions. Strategic archetypes include laser-engine licensors, spatial calibration platform developers, and integrated creative-technical service providers. Dominant competitive moves encompass strategic partnerships for content-technology bundling and geographic expansion into heritage digitization markets.
Within the broadcast heritage tier, Panasonic Corporation and Sony Corporation exemplify scale-driven positioning through captive supply chain control over solid-state illumination architectures. Barco NV, a Belgian limited liability company, anchors specialized image processing hardware for mission-critical events. Disguise Technologies Limited represents the software-defined workflow archetype, controlling media servers across complex multi-surface setups without manufacturing projector engines.
| Leading Market Players |
|---|
| Christie Digital Systems USA, Inc. |
| BenQ Corporation |
| Panasonic Corporation |
| NEC Display Solutions |
| ViewSonic Corporation |
| Seiko Epson Corporation |
| Sony Corporation |
| Disguise Technologies Limited |
| Barco NV |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Texas Instruments for digital micromirror devices above 30,000 lumens compresses pricing power for brightness-critical applications while simultaneously tethering supply chain resilience to semiconductor fabrication cycles in the United States. This captive supply dynamic widens spreads between DLP-engine premium tiers and laser-phosphor alternatives, redirecting procurement strategies toward solid-state architectures that bypass micromirror bottlenecks.
Pricing Analysis
Lamp-to-laser generational pricing gaps dominate procurement negotiations, with legacy mercury-vapor systems trading at steep discounts against 20,000-hour laser-phosphor baselines. Three-tier pricing structure across premium RGB-laser, standard laser-phosphor, and economy lamp-based levels reflects differentiation by color gamut certification and thermal management specifications. Cost compression in economy tiers intensifies as LED video walls capture daylight-viewable applications, forcing projector vendors to bundle content-creation services with hardware margins. Museums and cultural institutions exhibit lowest price sensitivity due to conservation-grade requirements, while rental-service providers for live events prioritize acquisition cost over operational lifespan.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk in laser diode and phosphor wheel sourcing, with Japanese and German component suppliers offering alternative routing. Manufacturing gravity centers on China for LCD panel integration, Japan for laser engine refinement, and Belgium for specialized image processing hardware. Raw material dependencies span rare-earth phosphors, precision optical glass, and aluminum heat-dissipation substrates. Single-source vulnerability in DLP chip supply from Texas Instruments constrains capacity expansion for large-venue applications. Distribution runs through German trade-show logistics hubs and United Kingdom touring production networks, with service unbundling shifting asset ownership toward specialist production companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic governance mandates constitute a regulatory inflection that separates certified hardware-software bundles from non-compliant alternatives, accelerating consolidation around vendors with documented bias-mitigation protocols. This compliance-driven disruption favors incumbents with established European certification infrastructure while raising capital barriers for speculative entrants.
For Market Incumbents: Pre-empt substitution threats from direct-view LED video walls by accelerating laser-phosphor cost curves through captive supply agreements with Japanese diode manufacturers. Defend position in German museum markets by front-loading EU AI Act compliance documentation ahead of competitor certification timelines, converting regulatory burden into procurement gatekeeping. Prioritize backward integration into media server software to capture recurring revenue streams as hardware ownership unbundles from creative services. For New Entrants and Emerging Players: Establish a beachhead in India's heritage digitization initiatives under the Archaeological Survey of India, where weather-resistant outdoor projection demand outpaces established vendor presence. Target white-space opportunities in spatial computing convergence for ephemeral installations, leveraging LiDAR-based environmental scanning to bypass pre-calibration expertise scarcity. Pursue go-to-market partnerships with regional creative production houses in the Netherlands and United Kingdom, where managed-service procurement models concentrate buyer relationships. For Investors and Strategic Acquirers: Software-defined workflow specialists with established algorithmic governance frameworks represent the most defensible acquisition archetype as EU AI Act compliance becomes a procurement prerequisite. Long-term viability hinges on vendors' capacity to unbundle hardware ownership from recurring creative-technical service revenue, aligning capital efficiency with shifting venue procurement preferences. Monitor right-to-repair legislation implementation timelines as the signal indicating when modular upgrade economics displace full-unit replacement revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Certification Program | CE marking alignment with EU AI Act documentation requirements secures German museum procurement pipelines. |
| Spatial Computing Partnership | LiDAR integration with real-time render engines opens ephemeral installation formats beyond permanent venue constraints. |
| Heritage Digitization Joint Venture | Archaeological Survey of India monument contracts channel weather-resistant hardware into underpenetrated cultural infrastructure. |
| Managed Service Platform Launch | Per-activation pricing aligns vendor incentives with uptime performance in United Kingdom rental markets. |
| Right-to-Repair Modular Upgrade Path | Component accessibility mandates redirect European service revenue toward recurring diagnostic software subscriptions. |
Research Approach
A spread of perspectives from live event technical directors, museum conservation officers, laser engine procurement leads, and spatial computing platform engineers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, EU AI Act implementation guidance, and trade show deployment records from Messe Frankfurt and Hannover Fairground. Customs data for high-lumen projector imports, SEC filings from display technology manufacturers, and cultural institution commissioning budgets from French national galleries supplemented stakeholder insights. Bottom-up triangulation across application segments and top-down reconciliation against regional infrastructure investment patterns anchored volume estimates.
Demand-supply balance dynamics across the projection mapping ecosystem shaped the analytical framework, with segmentation modeling spanning application context, illumination technology, end-user procurement sophistication, and solution unbundling patterns. CAGRs derived from installation velocity in German trade show circuits, Italian museum experiential budgets, and United Kingdom touring production utilization rates. Industry-specific forecast inputs incorporated laser phosphor replacement cycle acceleration against lamp-based legacy fleet depreciation, plus spatial computing convergence timelines for real-time environmental scanning adoption.
Sensitivities concentrate around Texas Instruments DLP supply allocation decisions, EU AI Act enforcement granularity for automated content adaptation systems, and LED video wall cost curves in daylight-viewable applications. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and technology substitution elasticities. Macroeconomic contraction in cultural funding, unilateral tariff escalation on laser diode imports, or breakthrough advances in direct-view emissive display efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
South Korea Webtoons Market
Digital Media
VFX Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Da Vinci Systems Market
Digital Media
Digital Media Switchers Market
Digital Media
Manga Market
Digital Media
India Webtoons Market
Digital Media
Online Movie Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Digital Content Locker Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Europe Animation Market
Digital Media
Online Gambling Market
Digital Media
Entertainment Transcription Market
Digital Media
Digital Effects Services Market
Digital Media
Europe Online Video Platform Market