
 Blockchain in Media and Entertainment Market | 2026-2036
Blockchain in Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Media and Entertainment Market Outlook
Market Context
North American cloud infrastructure providers is recalibrating enterprise blockchain capacity for media workloads. IBM Corporation leverages its permissioned ledger expertise to anchor supply-chain transparency for studio content provenance. Microsoft Corporation competes through Azure-based smart contract tooling that sustains developer adoption across streaming platforms.
Technical Definition and Segments
Blockchain in media and entertainment denotes distributed ledger architectures—typically employing SHA-256 hashing, Byzantine fault tolerance consensus, and immutable timestamping—to verify content ownership, automate royalty splits, and prevent unauthorized duplication across digital distribution channels. Smart contracts and decentralized storage dominate technology deployment, with the former capturing margin pools through automated rights execution while the latter displaces centralized CDN costs for long-tail content archives. Content distribution and rights management lead application adoption, though digital identity segments for creator verification are expanding fastest as platforms combat synthetic media fraud.
Regulatory Frame
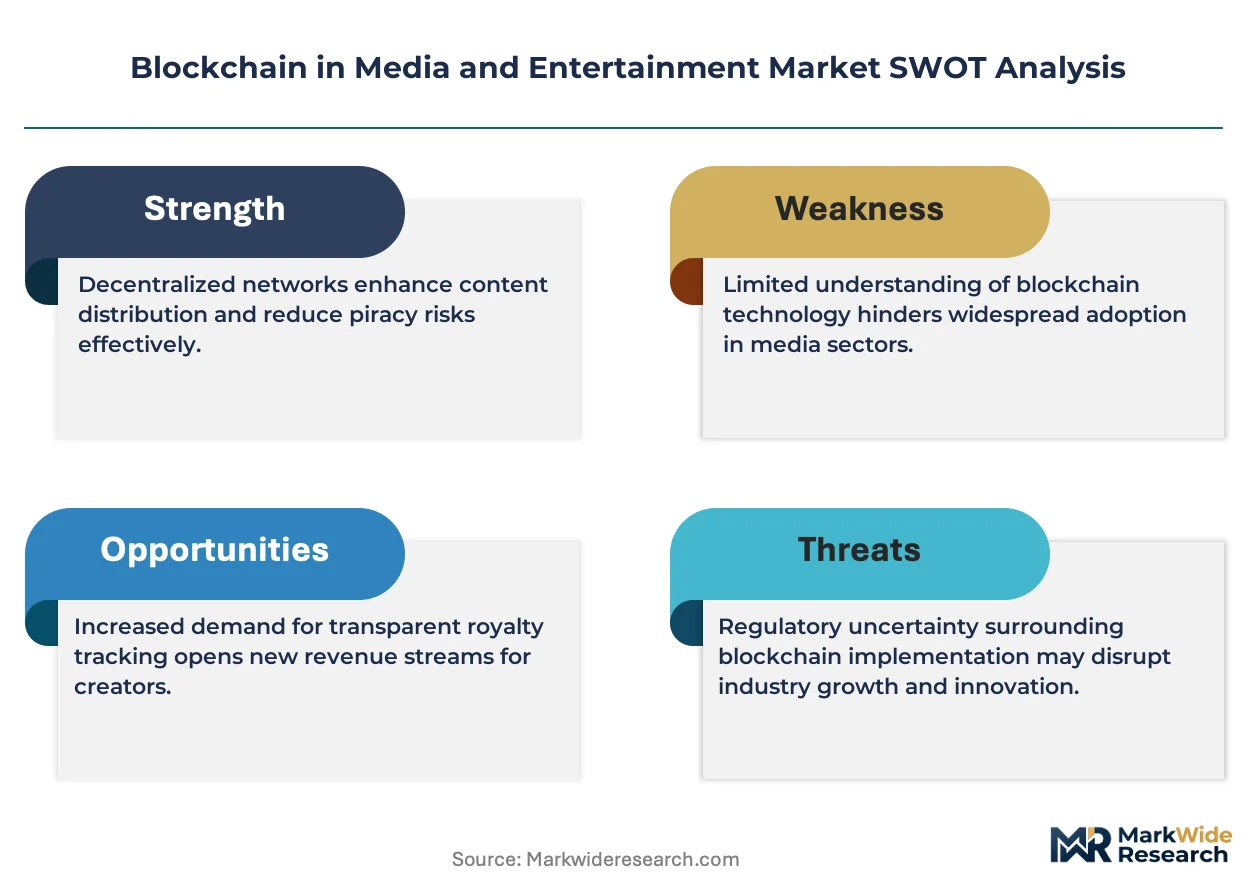
The U.S. SEC and CFTC exercise overlapping jurisdiction over tokenized media assets, creating compliance complexity that shapes platform architecture decisions for American operators. The EU's GDPR and emerging MiCA framework impose data portability and consumer protection standards that constrain pure decentralization in European deployments. Stakeholders must monitor evolving securities classification of fan tokens and royalty NFTs to avoid enforcement action that could freeze liquidity in secondary markets.
Market Dynamics
Smart contract automation is compressing royalty settlement cycles from quarterly to real-time, forcing studios to restructure accounting workflows and creator contracts around immutable ledger execution.
Growth Catalysts
- EU AI Act compliance requirements:Synthetic media detection mandates are driving demand for blockchain-based content provenance verification across European streaming platforms.
- Tokenized ticketing infrastructure:Sports and live entertainment venues are adopting NFT-based access credentials to eliminate fraud and capture secondary market revenue.
- Creator economy monetization:Decentralized autonomous organizations enable fan communities to fund film production through governance tokens, bypassing traditional studio gatekeeping.
Market Restraints
- Energy-intensive consensus mechanisms:Proof-of-work validation remains prohibitively expensive for high-volume content platforms, constraining deployment scale.
- Securities classification uncertainty:The U.S. SEC's evolving stance on fan tokens creates legal friction that freezes capital formation for experimental projects.
- Interoperability gaps:Proprietary ledger architectures prevent seamless asset transfer between competing entertainment ecosystems.
Strategic Opportunities
- India's digital content surge:Regional language streaming platforms present untapped demand for royalty transparency solutions among independent creators.
- Zero-knowledge identity verification:Convergence of privacy-preserving cryptography with age-gating requirements enables compliant adult content distribution without centralized data exposure.
- Germany's MiCA implementation:Clear regulatory frameworks for crypto-assets attract institutional capital into tokenized film financing structures.
Industry Challenges
- Smart contract auditing expertise:Scarce blockchain developer talent delays deployment timelines and inflates security review costs for media firms.
- Legacy rights database migration:Decades of fragmented ownership records resist clean on-chain tokenization without costly manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Media and Entertainment Market |
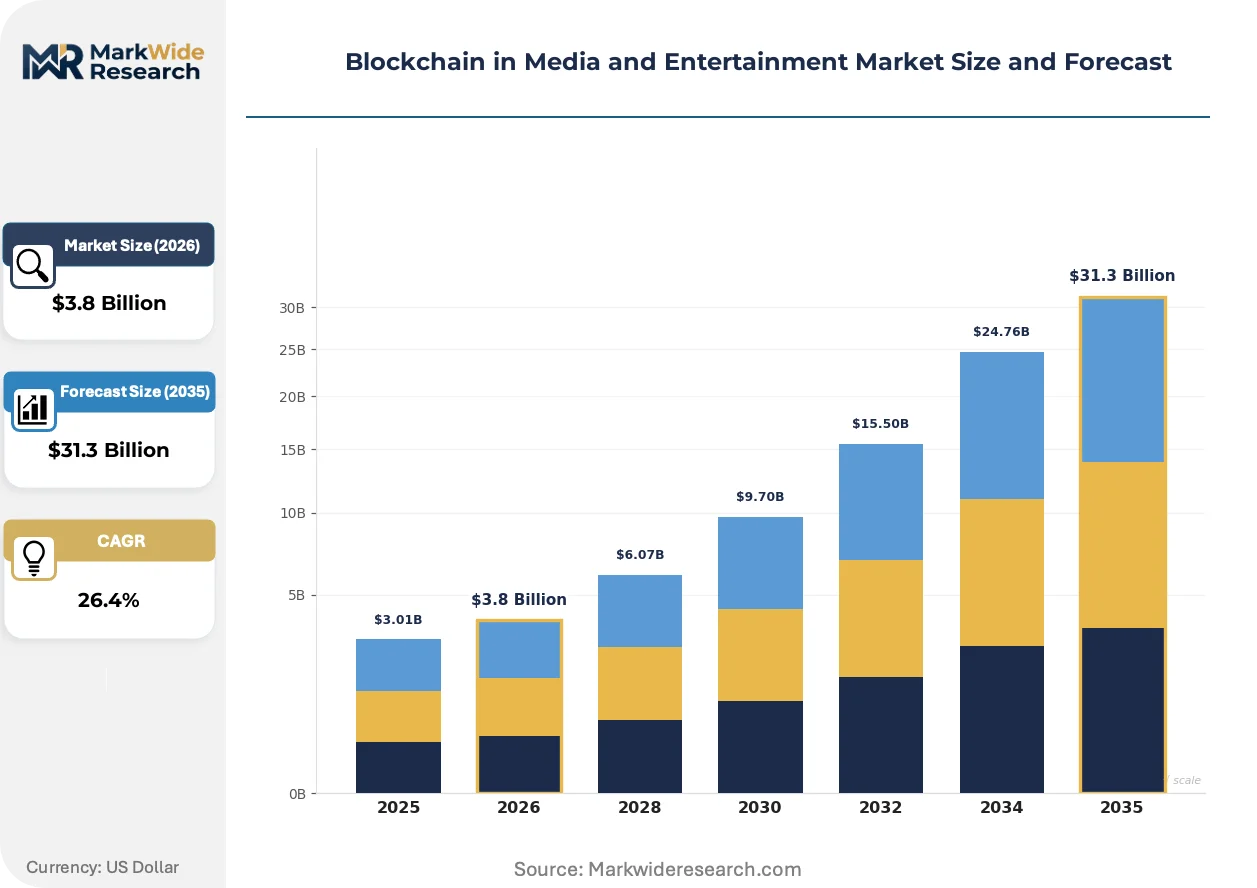
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $31.3 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Contracts, Cryptocurrency, Decentralized Storage, Permissioned Ledger Application: Content Distribution, Rights Management, Streaming Solutions, Digital Identity End User: Film Studios, Streaming Services, Publishers, Gaming Companies Deployment: On-Premise, Cloud-Based, Hybrid, Consortium |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon, Sony, Walt Disney, Warner Bros, Universal Music Group, Live Nation Entertainment, Dapper Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Media and Entertainment Market Strategic Shifts
Permissioned ledger architectures are displacing public blockchain deployments as studios prioritize transaction throughput and regulatory compliance over decentralization ideals.
Layer-2 scaling solutions are integrating zero-knowledge rollups to batch thousands of micro-royalty transactions into single settlement proofs. Music distributors and podcast networks are adopting these protocols to reduce gas fees below the threshold of economic viability for small-value payments. This compression is integrating automated split contracts into platforms that previously excluded independent creators due to cost barriers.
The EU's Markets in Crypto-Assets framework is mandating reserve backing and redemption guarantees for stablecoins used in platform economies. European ticketing operators must restructure token mechanics to ensure fiat convertibility, adding compliance overhead but attracting risk-averse institutional partners. German and French regulators are prioritizing enforcement against unlicensed fan token issuances, reshaping go-to-market strategies for engagement platforms.
Direct-to-creator subscription models are fragmenting aggregator dominance as audiences seek unfiltered relationships with individual artists. Blockchain-enabled patronage platforms displace traditional talent agencies in revenue collection and fan communication. This channel shift concentrates most visibly in South Korean idol fandoms and Brazilian independent film communities where platform-native tokens strengthen parasocial bonds.
Blockchain in Media and Entertainment Market Segmentation
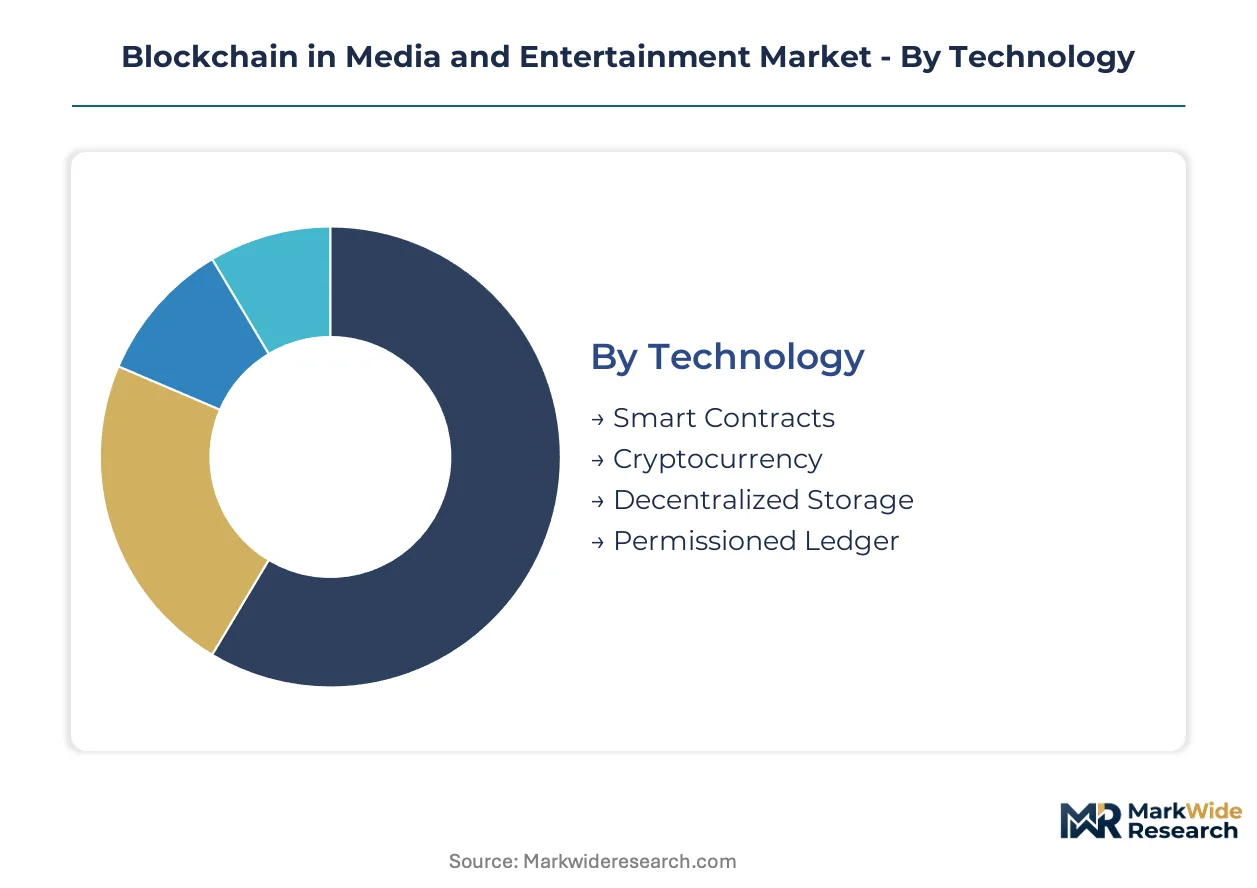
Segmentation in blockchain media deployments separates capital-heavy infrastructure investments from lightweight application layers. Studios allocate budget differentially across consensus mechanisms, storage architectures, and compliance frameworks depending on content volume and geographic regulatory exposure.
Technology:
Capital intensity peaks in consensus infrastructure and cryptographic hardware, with deployment scale determining whether studios build proprietary stacks or rent validator capacity.
- Smart Contracts:Self-executing code automates royalty splits and licensing terms without intermediary escrow. Film studios in Los Angeles and Mumbai deploy these for real-time creator payments, though auditing costs constrain adoption among independent producers.
- Decentralized Storage:Distributed file systems replace centralized CDN contracts for archival content, with IPFS and Arweave protocols gaining traction among documentary distributors managing petabyte-scale libraries. Energy costs for redundancy limit deployment to premium catalog tiers.
- Cryptocurrency:Native tokens power platform economies and fan engagement mechanics.
- Permissioned Ledger:Restricted node networks satisfy enterprise compliance requirements.
Most installed capacity flows through Smart Contracts. Expansion is steepest in Decentralized Storage.
Application:
Functional use cases diverge sharply by content type, with live event verticals demanding real-time settlement speed that archival libraries sacrifice for cost efficiency.
- Rights Management:Immutable ownership registries resolve chain-of-title disputes for co-production financing. European distributors leverage these systems to satisfy EU AI Act provenance mandates for synthetic media detection.
- Content Distribution:Peer-to-peer delivery networks bypass platform gatekeeping for direct creator-audience relationships. Brazilian independent filmmakers and South Korean music labels pioneer these channels to retain revenue share.
- Streaming Solutions:Token-gated access controls monetize premium tiers without subscription intermediaries.
- Digital Identity:Verifiable credentials combat deepfake impersonation of talent and executives.
Revenue concentration sits with Rights Management. Gaining share fastest is Digital Identity.
End User:
Customer scale and technical sophistication create tiered service requirements, from multinational studios demanding SOC-2 compliance to indie developers prioritizing API simplicity.
- Film Studios:Major production houses anchor demand for enterprise-grade permissioned networks. Warner Bros. Discovery and Sony Pictures Entertainment pilot blockchain provenance for franchise IP tracking across merchandising and gaming extensions.
- Streaming Services:Subscription platforms adopt smart contracts for transparent royalty pools. Spotify and Netflix experimentation with decentralized creator funds drives vendor selection criteria.
- Gaming Companies:Interactive entertainment firms integrate play-to-earn mechanics and asset interoperability.
- Publishers:News and book platforms deploy timestamp verification for content authenticity.
Budget authority concentrates with Film Studios. Climbing the fastest is Gaming Companies.
Deployment:
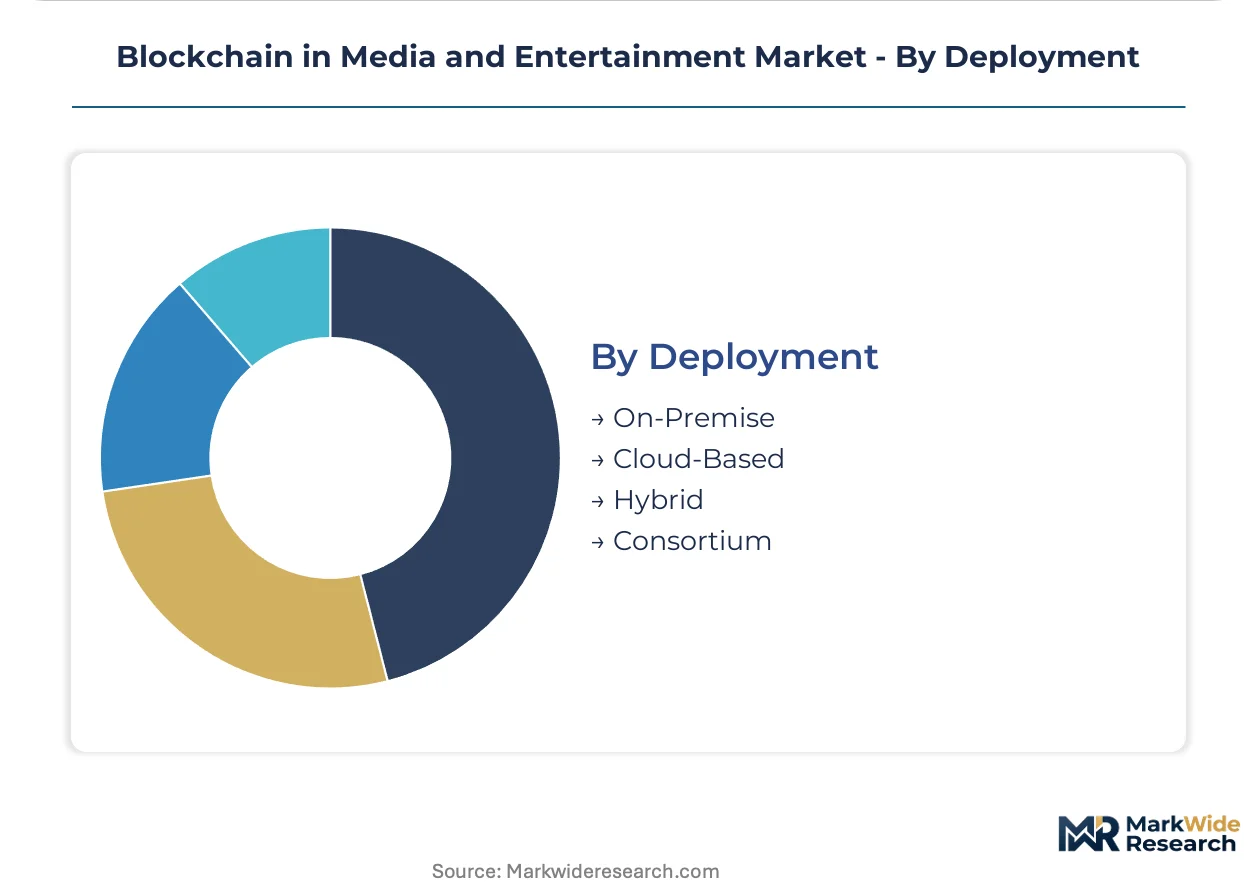
Architecture choices trade sovereignty against operational burden, with regulatory jurisdiction dictating whether data residency rules permit cloud validator participation.
- Cloud-Based:Managed node services from AWS and Azure reduce DevOps overhead for mid-tier distributors. German broadcasters prefer these configurations to satisfy GDPR data localization without自建 infrastructure investments.
- Consortium:Multi-party governed networks share infrastructure costs among non-competing studios. The Motion Picture Association coordinates member participation in shared royalty settlement rails.
- On-Premise:Self-hosted validators maximize control for classified content workflows.
- Hybrid:Split architectures isolate sensitive rights data on private nodes while exposing public verification layers.
Current deployment volume favors Cloud-Based. Steepest expansion trajectory belongs to Consortium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting blockchain media investment toward jurisdictions with clearer digital asset frameworks. Studios migrate operations where compliance costs stabilize capital formation for tokenized content ventures.
United States
SEC and CFTC jurisdictional overlap shapes platform architecture decisions for American operators. The Howey Test application to fan tokens creates legal friction that concentrates experimental projects in Wyoming and Florida regulatory sandboxes. Los Angeles production houses anchor enterprise-grade permissioned network pilots for franchise IP tracking.
Germany
MiCA implementation attracts institutional capital into tokenized film financing structures. BaFin licensing requirements for crypto custody services filter out undercapitalized platform operators. Berlin and Munich studio clusters coordinate shared royalty settlement rails through consortium ledger deployments.
United Kingdom
FCA stablecoin regulations reshape platform economics for ticketing operators serving Premier League venues. The Financial Services and Markets Act provisions on digital settlement assets impose reserve backing requirements. London fintech infrastructure supports secondary market liquidity for creator economy tokens.
South Korea
K-pop idol agencies drive demand for blockchain-enabled fan engagement and direct artist patronage. The Financial Services Commission's virtual asset service provider framework governs exchange listings for entertainment tokens. Seoul's Gangnam district hosts concentrated development of zero-knowledge identity verification for age-gated content.
India
Regional language streaming platforms generate untapped demand for royalty transparency among independent creators. RBI's cautious stance on private cryptocurrencies pushes studios toward permissioned ledger architectures. Mumbai and Hyderabad production centers pilot smart contract automation for real-time creator payments.
Blockchain in Media and Entertainment Market Competitive Environment
United States technology conglomerates anchor one tier; European and Asian specialists hold differentiated positions in rights management and fan engagement tooling. Market structure concentrates around vertically integrated cloud providers and pure-play blockchain developers. Three archetypes dominate: infrastructure-as-a-service platforms, content-native technology divisions, and decentralized application specialists. Competitive moves center on strategic partnerships between legacy studios and ledger developers, plus geographic expansion into regulatory-certain jurisdictions.
Within the infrastructure tier, IBM Corporation and Microsoft Corporation exemplify enterprise-grade permissioned ledger provision. Amazon occupies a position bridging cloud compute and managed blockchain services. Sony and Walt Disney represent content-native technology deployment, anchoring studio-led innovation in provenance verification and tokenized IP extension. Dapper Labs sits within the application-specialist archetype, exemplifying consumer-facing NFT infrastructure for sports and entertainment verticals.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon |
| Sony |
| Walt Disney |
| Warner Bros |
| Universal Music Group |
| Live Nation Entertainment |
| Dapper Labs |
| Others |
Value Chain & Pricing Dynamics
Captive validator infrastructure anchors supply positioning for enterprise blockchain deployments while insulating tier-one studios from gas fee volatility that erodes creator payment margins. Permissioned ledger operators in Los Angeles and Mumbai leverage in-house node networks to lock in throughput guarantees and command premium pricing for real-time royalty settlement services.
Pricing Analysis
Distributor margin compression in cloud-managed blockchain services is reshaping how studios procure ledger capacity. Subscription-tiered pricing stratifies across enterprise, mid-market, and developer tiers, with SOC-2 certification and GDPR compliance anchoring premium differentials. Pricing pressure stems from Layer-2 rollup competition that undercuts base-layer transaction costs. Indie creators exhibit highest price sensitivity, while major studios prioritize auditability over unit economics.
Supply Chain Analysis
Regional distribution centers for cryptographic hardware cluster in Taiwan, South Korea, and the United States, with specialized ASIC manufacturing feeding validator deployment pipelines. The supply chain draws from silicon wafer supplies, enterprise-grade storage arrays, and zero-knowledge proof acceleration chips. Single-source vulnerability in specialized cryptographic processors poses structural risk. Distribution runs through hyperscaler cloud marketplaces and direct OEM relationships with studio technology divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as studios prioritize immutable audit trails over cost minimization. Premium-grade provenance verification commands pricing power in co-production financing structures.
For Market Incumbents: To counter Layer-2 rollup providers undercutting base-layer margins, IBM and Microsoft should deepen backward integration into zero-knowledge hardware acceleration and lock in exclusive cloud validator capacity in Germany's MiCA-compliant zones. Certification investment in EU AI Act provenance tooling creates switching costs for European studio clients.
For New Entrants and Emerging Players: API-first distribution channels offer the lowest friction path into mid-tier streaming platforms that lack in-house blockchain expertise. India's regional language content creators represent the most penetrable segment, with white-space demand for transparent royalty splits that bypass aggregator gatekeeping. Target consortium ledger participation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized rights-management software vendors because fragmented ownership databases resist clean tokenization without manual reconciliation expertise. Five-to-ten year viability hinges on MiCA licensing moats that filter out undercapitalized competitors. Watch German BaFin enforcement patterns as the inflection signal for institutional capital flows into tokenized film financing.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Audit Certification | Establishes trust barriers that freeze out undercapitalized competitors in creator payments. |
| Zero-Knowledge Hardware Partnership | Accelerates Layer-2 throughput for micro-royalty settlement below viable cost thresholds. |
| MiCA Licensing Pre-Positioning | Captures institutional capital flows into regulated tokenized film financing structures. |
| Consortium Ledger Expansion | Shares infrastructure costs among non-competing studios through Motion Picture Association coordination. |
| Creator Economy Platform Integration | Displaces traditional talent agencies in revenue collection for South Korean and Brazilian markets. |
Study Parameters
Direct dialogue with blockchain engineering leads at major studios, smart contract auditors, cloud infrastructure procurement officers, and European regulatory compliance directors grounded the qualitative foundation. Secondary validation drew from SEC disclosure filings on tokenized asset pilots, EU AI Act implementation guidance, MiCA regulatory technical standards, and hyperscaler blockchain service announcements. Bottom-up deployment estimates triangulated against top-down market sizing from entertainment technology expenditure trends.
Bottom-up modeling of validator capacity expansion, smart contract deployment volumes, and creator platform user growth fed into segment-level projections across the analysis window. Segmentation dimensions included consensus mechanism type, application layer function, end-user scale tier, and geographic regulatory cluster. CAGRs derived from technology diffusion curves weighted against compliance timeline uncertainty. Forecast inputs incorporated Layer-2 adoption rates and stablecoin reserve backing requirements under MiCA.
The model assumes a particular technology adoption path; alternative pathways for zero-knowledge rollup integration would alter the outlook if cryptographic overhead fails to compress below micro-royalty economic viability. Forecasts reflect documented assumptions around regulatory enforcement intensity and studio accounting system migration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Adult Entertainment Market
Digital Media
Global Stock Video Market
Digital Media
US Automatic Content Recognition Market
Digital Media
Stream Hosting Market
Digital Media
Secondary Ticket Market
Digital Media
Digital Content Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Digital Video Advertising Market
Digital Media
Photography Services Market
Digital Media
United States Online Gambling Market
Digital Media
Global Transport Media Market
Digital Media
Video Player Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
South Korea Webtoons Market
Digital Media
In Flight Entertainment Market
Digital Media
APAC Media and Entertainment Market