
 Video Wall Market | 2026-2036
Video Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Video Wall Market Intelligence
CE marking under the EU Radio Equipment Directive is bifurcating the supplier base between qualified European vendors and non-compliant exporters. Samsung Electronics leverages its captive semiconductor supply to sustain margin control across high-resolution LED modules. Barco specializes in mission-critical control room installations, anchoring its position in defense and air traffic management verticals. Leyard Optoelectronics dominates domestic Chinese projects through vertical integration into LED chip packaging.
A video wall is a multi-monitor display system comprising tiled screens with bezel widths below two millimeters, driven by synchronized image processors to render continuous visual surfaces across areas exceeding ten square meters. These systems serve command centers, retail environments, and broadcast studios requiring real-time data visualization at scale. LCD panels still occupy the largest installed base due to cost efficiency in indoor corporate settings, though fine-pitch LED is displacing legacy projection in broadcast applications. Interactive display technology is capturing premium budgets in retail and museum deployments where touch-enabled surfaces extend dwell time.
The FCC regulates electromagnetic emissions from video wall controllers and signal distribution hardware sold into US commercial installations, while REACH compliance governs hazardous substance thresholds in European LED module substrates. China's GB standards for electronic display energy consumption, enforced by SAMR, shape procurement criteria for domestic smart city projects. Stakeholders must weigh regional certification cycles against product refresh timelines when allocating R&D across fine-pitch LED and emerging transparent OLED architectures.
Market Dynamics
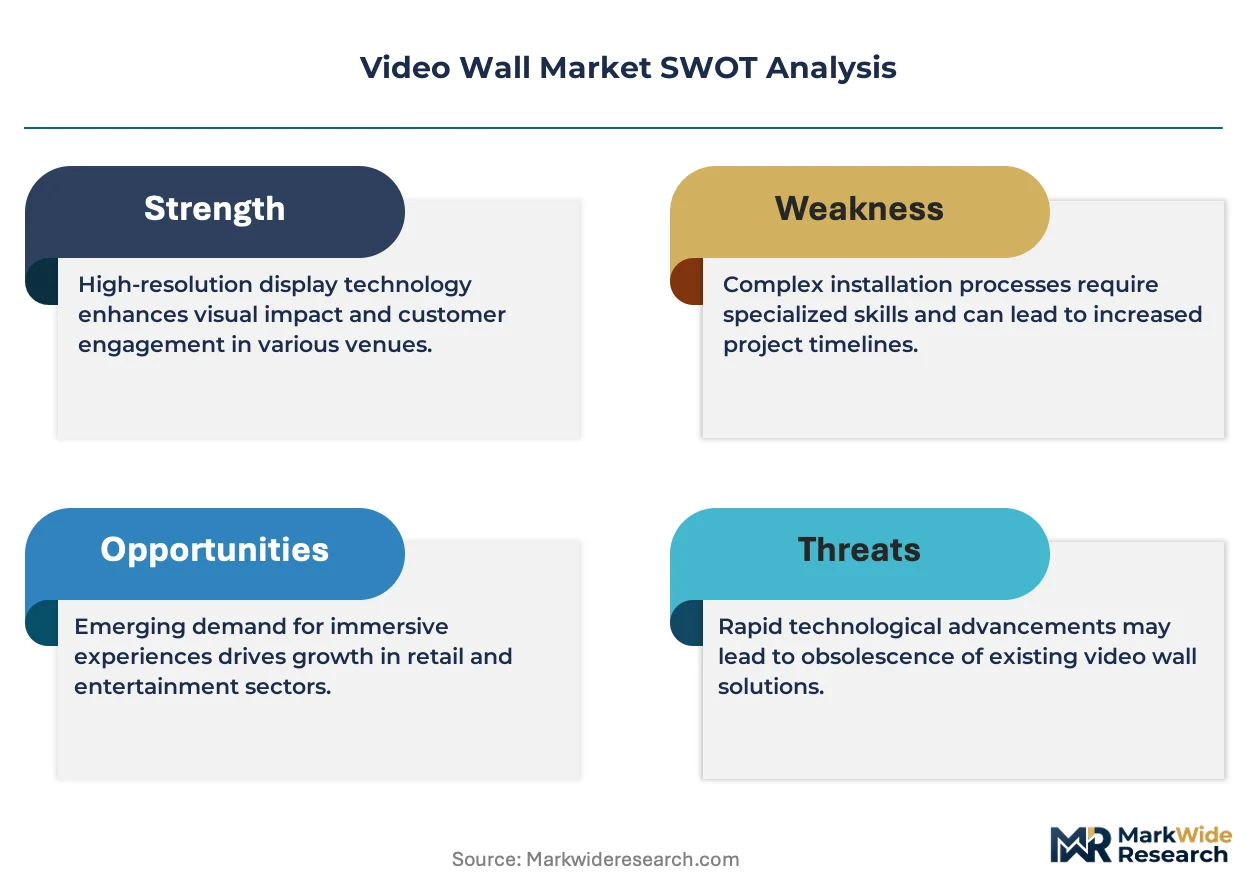
Fine-pitch LED technology is compressing pixel pitches below one millimeter, forcing incumbent LCD panel suppliers to defend corporate indoor installations against displacement in broadcast studios and command centers.
Growth Catalysts
- EU Energy Efficiency Directive:Tightening standby power thresholds for large-format digital displays are accelerating replacement cycles in European retail and transit environments.
- Control room digitization:Utilities and transportation authorities are expanding deployments of narrow-bezel LED arrays for real-time infrastructure monitoring.
- Shenzhen-Beijing cluster:Domestic panel fabs and systems integrators in China are capturing smart city procurement through localized supply chains.
Market Restraints
- Indium gallium arsenide phosphide supply:Red LED chip substrate costs fluctuate with mining concentration in Chinese rare earth processing facilities.
- CE marking bifurcation:The EU Radio Equipment Directive is splitting qualified European vendors from non-compliant exporters, limiting sourcing flexibility.
- Projection legacy:Existing DLP rear-projection cubes in aging control rooms create sunk-cost resistance to full LED retrofit.
Strategic Opportunities
- Transparent OLED architectures:Emerging transparent display layers enable augmented reality integration in museum and flagship retail facades.
- Interactive surface convergence:Touch-enabled video walls are extending visitor dwell time in experiential commerce installations.
- SAMR enforcement:China's GB standards for electronic display energy consumption are mandating efficiency upgrades in domestic smart city tenders.
Industry Challenges
- Image processor calibration:Synchronizing color uniformity across tiled LED modules requires specialized technicians scarce outside Shenzhen and Seoul.
- REACH substrate compliance:European hazardous substance thresholds in LED module materials extend certification cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Wall Market |
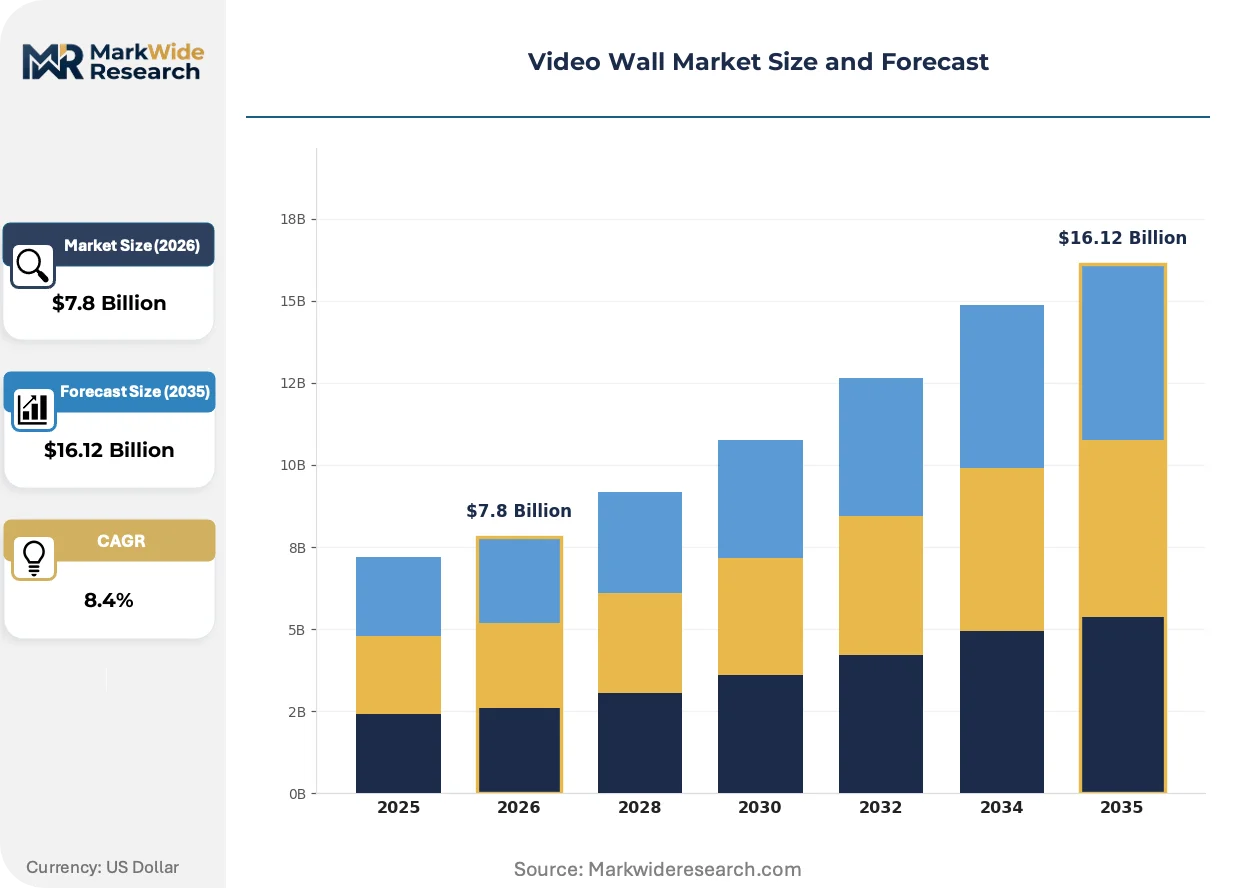
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Projection End User: Retail, Corporate, Broadcast, Control Rooms Technology: Digital Signage, Interactive Displays, 3D Displays, Video Conferencing Installation Type: Indoor, Outdoor, Wall-mounted, Free-standing |
| Companies Covered | Leyard Optoelectronics, Absen, Samsung Electronics, Delta Electronics, Toshiba Corporation, LG Electronics, Barco, Planar, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Wall Market Strategic Shifts & Innovations
Display architecture is pivoting from passive viewing surfaces toward active data interaction layers, with touch integration and transparency becoming baseline expectations in premium deployments.
Fine-pitch LED is miniaturizing pixel architectures to sub-millimeter pitches, enabling seamless visual continuity at viewing distances previously served by LCD. Broadcast studios in London and New York are adopting these arrays for virtual production backdrops. The technology is miniaturizing the physical footprint of control room installations while expanding effective resolution per square meter.
REACH compliance governs hazardous substance thresholds in European LED module substrates, forcing reformulation of solder masks and phosphor coatings. Manufacturers serving EU member states must maintain dual material specifications. Defense and air traffic management verticals face the longest validation timelines due to mission-critical reliability requirements.
Service unbundling is separating hardware procurement from multi-year maintenance contracts in corporate and institutional accounts. Systems integrators now compete on software-defined content management rather than installation margins. This pattern is most visible in German and Japanese enterprise deployments where total-cost-of-ownership scrutiny has intensified.
Video Wall Market Segmentation
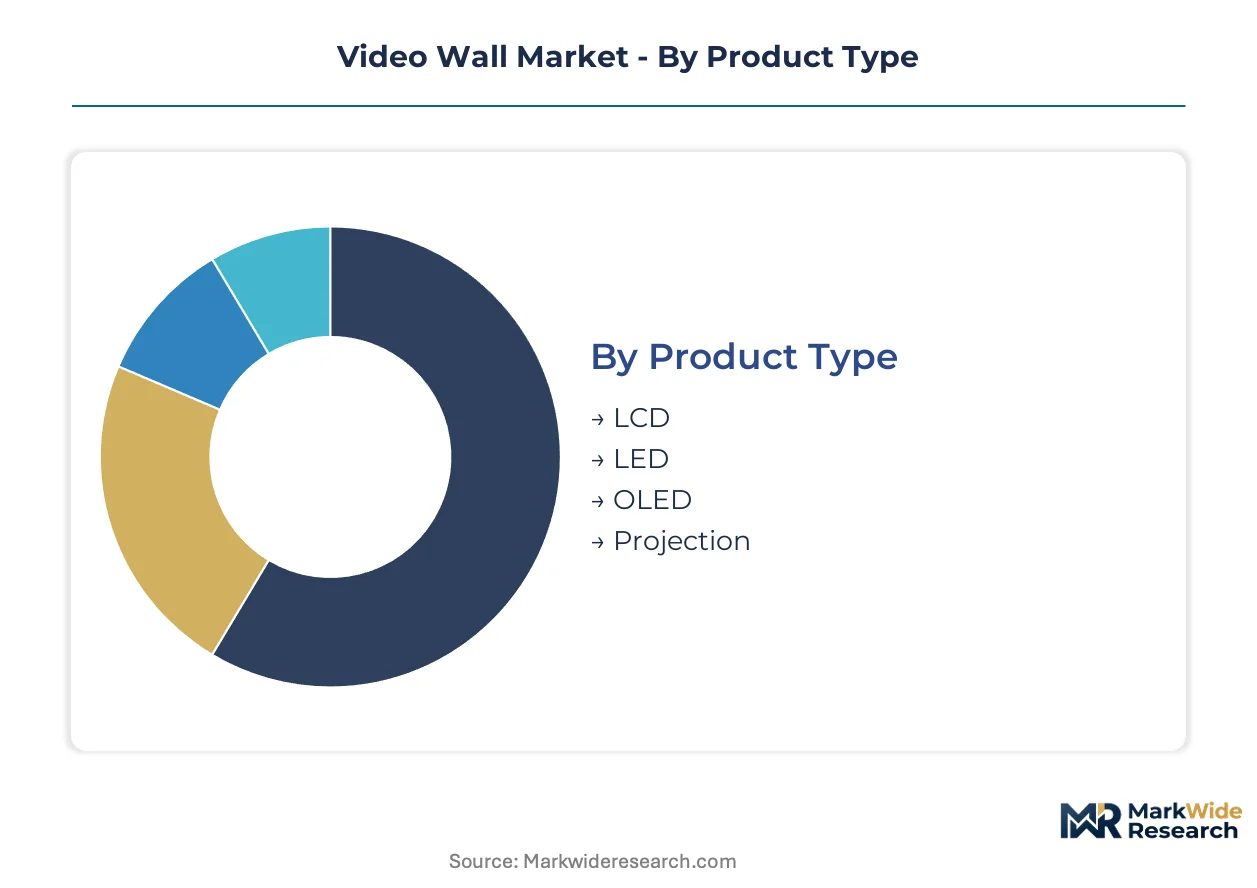
Video wall procurement patterns diverge sharply across display technologies and deployment contexts. Substitution pressures from fine-pitch LED reshape category economics differently in control rooms versus retail facades.
Product Type:
LED arrays exert mounting substitution pressure on legacy LCD installations as pixel pitches compress below one millimeter.
- LCD:Liquid-crystal panels with direct-lit or edge-lit backlighting dominate corporate indoor installations where cost efficiency outweighs bezel visibility. Procurement concentrates in German and Japanese enterprise deployments where total-cost-of-ownership scrutiny has intensified.
- LED:Direct-view LED tiles with sub-millimeter pixel pitches enable seamless visual continuity at viewing distances previously served by projection. Broadcast studios in London and New York adopt these arrays for virtual production backdrops, displacing legacy DLP cubes.
- OLED:Self-emissive organic layers deliver perfect black levels and wide viewing angles for premium museum installations.
- Projection:DLP and laser phosphor systems retain niche positions in budget-constrained education and temporary event staging.
LCD retains volume leadership across installed base; LED holds the steepest expansion curve as fine-pitch architectures penetrate broadcast and command center verticals.
End User:
Control room digitization drives specification intensity highest among infrastructure operators with 24/7 reliability requirements.
- Control Rooms:Mission-critical installations in utilities and air traffic management demand redundant signal paths and color-calibrated narrow-bezel arrays. Defense and transportation authorities anchor procurement in this segment with the longest validation timelines.
- Retail:Flagship stores and shopping malls deploy interactive surfaces to extend visitor dwell time. Touch-enabled layers capture premium budgets in experiential commerce installations where engagement metrics determine ROI.
- Broadcast:Studios require high refresh rates and chromatic consistency for virtual production environments.
- Corporate:Headquarters and conference facilities prioritize cost-efficient tiled displays for data visualization.
Control rooms command the highest specification tier; retail applications are expanding most quickly through interactive surface convergence.
Technology:
Interactive functionality commands price premiums that widen margin structures for systems integrators with software capabilities.
- Digital Signage:Networked content distribution systems with centralized management dominate transit and quick-service restaurant deployments. SAMR enforcement of GB standards shapes procurement criteria for domestic Chinese smart city tenders.
- Interactive Displays:Touch-enabled and gesture-responsive surfaces transform passive viewing into active engagement layers. Museums and flagship retail facades in Dubai and Singapore drive adoption where dwell time directly correlates with revenue.
- 3D Displays:Autostereoscopic and glasses-based systems serve medical imaging and specialized simulation applications.
- Video Conferencing:Integrated camera and microphone arrays support hybrid workplace collaboration in corporate campuses.
Digital signage maintains the broadest installed footprint; interactive displays gain share fastest as experiential commerce budgets expand.
Installation Type:
Outdoor specifications face the harshest environmental stress tests, filtering supplier participation toward vertically integrated manufacturers.
- Indoor:Climate-controlled environments permit narrower bezel tolerances and lower ingress protection ratings. Corporate campuses and broadcast studios in Seoul and Shenzhen concentrate demand for fine-pitch LED with specialized calibration requirements.
- Outdoor:Direct sunlight readability and thermal management drive brightness specifications above 5,000 nits. Stadium and transit authority deployments in Doha and Los Angeles require IP65-rated enclosures with redundant power supplies.
- Wall-mounted:Fixed installations dominate permanent control room and retail facade applications.
- Free-standing:Kiosk and temporary event configurations prioritize rapid deployment and reconfiguration flexibility.
Indoor installations retain volume leadership across procurement cycles; outdoor deployments follow the steepest expansion trajectory as smart city infrastructure investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Energy Efficiency Directive mandates are accelerating replacement cycles for large-format displays across member states. Control room digitization in utilities and transportation authorities drives narrow-bezel LED deployments. Domestic panel fabrication clusters in East Asia and localized systems integration capabilities reshape procurement geography.
United States
FCC electromagnetic emission standards govern video wall controllers and signal distribution hardware in commercial installations. Defense and air traffic management verticals anchor demand in Virginia and Florida command centers. Systems integrators in Dallas and Los Angeles compete on software-defined content management capabilities.
Germany
REACH hazardous substance thresholds extend LED module certification cycles by four to six months for European substrate compliance. Industrial headquarters in Munich and Frankfurt prioritize total-cost-of-ownership scrutiny in procurement decisions. Barco maintains mission-critical positioning in defense and transportation control rooms.
China
SAMR enforcement of GB standards for electronic display energy consumption shapes smart city tender criteria. Shenzhen and Beijing clusters concentrate domestic panel fabs and systems integrators capturing municipal infrastructure budgets. Leyard Optoelectronics anchors domestic project execution through backward integration into LED chip packaging.
Japan
METI efficiency guidelines and JIS standards regulate commercial display procurement in corporate and broadcast verticals. Tokyo and Osaka studios adopt fine-pitch LED for virtual production backdrops displacing legacy projection. Enterprise deployments emphasize multi-year maintenance contract unbundling from hardware procurement.
South Korea
Samsung Electronics leverages captive semiconductor supply chains to sustain margin control across high-resolution LED modules. Seoul metropolitan area concentrates broadcast studio and corporate campus demand for seamless visual surfaces. Specialized calibration technicians for tiled module synchronization remain concentrated in the capital region.
Video Wall Market Key Industry Players
Player mix skews toward diversified electronics conglomerates with captive display component supply. Market structure exhibits tiered concentration with premium specialists defending mission-critical verticals against scale-driven challengers. Strategic archetypes include vertically integrated semiconductor-display hybrids, narrow-vertical control room specialists, and China-centric fabrication-integrators. Competitive moves center on backward integration into LED chip production and geographic expansion through localized systems integration partnerships.
Within the diversified electronics tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through component supply chain control. Barco occupies a specialist position in defense and air traffic management verticals where validation timelines filter participation. Leyard Optoelectronics anchors the China-centric fabrication archetype through domestic project concentration. Delta Electronics and Absen sit within the mid-tier systems integration layer competing on regional deployment speed.
| Leading Market Players |
|---|
| Leyard Optoelectronics |
| Absen |
| Samsung Electronics |
| Delta Electronics |
| Toshiba Corporation |
| LG Electronics |
| Barco |
| Planar |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with rare-earth processors lock in indium phosphide substrate access while capping red LED chip cost volatility for display manufacturers. These arrangements bind Shenzhen-based systems integrators to fixed-volume commitments, creating price visibility that spot-market buyers in Seoul and Dallas cannot replicate.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate fine-pitch LED module procurement. Three-tier pricing structure across mission-critical, commercial-grade, and budget installations separates defense control rooms from corporate conference deployments. Cost compression in sub-millimeter pixel architectures is intensifying because Chinese domestic fabs are expanding wafer capacity. Corporate headquarters buyers exhibit highest price sensitivity; broadcast studios and defense installations demonstrate lowest elasticity due to reliability mandates.
Supply Chain Analysis
Inventory cycles for LED driver ICs now stretch sixteen to twenty weeks, constraining project delivery schedules for systems integrators outside East Asia. Manufacturing concentrates in China, South Korea, and Taiwan for display panels and image processors. Production draws from indium gallium arsenide phosphide substrates, rare-earth phosphors, and copper-clad laminates. Single-source vulnerability in Chinese rare-earth processing facilities poses structural risk. Distribution runs through authorized systems integrators with certified calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video wall procurement is shifting toward software-defined content platforms where hardware margins commoditize and ecosystem interoperability determines vendor stickiness. This platform-economics inflection rewards players controlling image processing firmware and cloud-based fleet management tools.
For Market Incumbents: Consolidate calibration technician networks in Seoul and Shenzhen to defend service attach rates against independent software vendors. Secure backward integration into LED driver semiconductor supply through foundry partnerships in Taiwan. Fine-pitch LED substitution threatens legacy LCD install bases; captive chip packaging capabilities anchor margin defense. For New Entrants and Emerging Players: Anchor in interactive surface deployments for museum and flagship retail verticals where touch-enabled layers command premium pricing and incumbent software portfolios remain thin. Target German enterprise campuses where total-cost-of-ownership scrutiny has unbundled hardware from maintenance contracts. Lead with software-defined content management as primary value proposition. For Investors and Strategic Acquirers: Narrow-vertical control room specialists with SAMR certification and defense validation timelines represent attractive acquisition targets. Long-term viability hinges on regulatory compliance moats widening faster than technology substitution cycles. Watch for CE marking enforcement tightening as inflection signal separating qualified European vendors from export-dependent challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Packaging | Leyard Optoelectronics demonstrates how captive substrate control secures domestic Chinese smart city tenders. |
| Software-Defined Content Platform Launch | Systems integrators in Dallas compete on cloud fleet management rather than installation margins. |
| CE Marking Certification Investment | REACH substrate compliance extends European market access for qualified vendors against non-compliant exporters. |
| Interactive Surface Capability Acquisition | Museum deployments in Dubai and Singapore reward touch-enabled layers with extended visitor dwell metrics. |
| Calibration Technician Network Expansion | Specialized color-uniformity technicians scarce outside Shenzhen and Seoul constrain competitor replication speed. |
Research Approach
Cross-validation between systems integrator interviews and customs shipment records anchors the qualitative findings in observable procurement patterns. Primary discussions with control room operators, broadcast engineers, retail experience designers, and SAMR certification consultants informed demand-side assumptions. Secondary sources include FCC equipment authorization databases, REACH substance restriction filings, and GB standard enforcement bulletins. Bottom-up project pipeline analysis triangulates against top-down display panel production estimates.
Sensitivity analysis across pixel pitch adoption curves, energy efficiency mandate timelines, and rare-earth price scenarios stress-tests projection robustness. The analytical framework segments by display technology, installation environment, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs derive from installed base replacement cycles and greenfield deployment trajectories. Virtual production backdrop adoption in London and New York studios, plus Shenzhen smart city tender volumes, serve as industry-specific demand proxies.
Material uncertainties — indium phosphide supply disruptions, CE marking enforcement acceleration, or transparent OLED technology maturation — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Video Advertising Market
Digital Media
Multichannel Network Market
Digital Media
Information Short Video Market
Digital Media
Anime Streaming Tool Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Digital Media Switchers Market
Digital Media
Anime Merchandising Market
Digital Media
Photographic Services Market
Digital Media
United States Online Gambling Market
Digital Media
Entertainment Transcription Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Online Movie Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
North America Photographic Services Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
China Webtoons Market