
 Europe Location-Based Entertainment Market | 2026-2036
Europe Location-Based Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Location-Based Entertainment Market Analytics
Recurring content licensing revenue is rewriting profitability models across the Europe Location-Based Entertainment landscape. Hologate leverages its proprietary VR arena systems to anchor premium positioning in German and British entertainment complexes. IMAX Corporation extends its large-format cinema heritage into immersive destination experiences, sustaining brand authority in high-traffic venues. Samsung Electronics Co., Ltd. competes through display and semiconductor integration, dominating visual infrastructure supply for interactive installations.
Europe Location-Based Entertainment denotes physically situated commercial attractions that deploy immersive technologies—3D projection mapping, motion-sensing interfaces, spatial audio arrays, and haptic feedback systems—to deliver narrative-driven experiences outside residential settings. These installations serve tourism, retail footfall generation, corporate team-building, and educational outreach functions. Virtual Reality and Augmented Reality product categories command the deepest R&D investment, while Escape Rooms occupy a mature margin tier sustained by repeat corporate bookings. Thematic Attractions integrate multiple technology layers including 3D Projection and Interactive Displays, concentrating capital deployment in indoor venues and theme parks where dwell-time economics justify higher per-square-meter buildout costs.
EU Green Deal building efficiency mandates and CE marking requirements for electrical installations shape venue construction timelines and equipment sourcing across member states. Germany's KBA and national fire safety regulators enforce structural standards for motion-platform installations, while France's CNIL imposes data handling protocols on visitor tracking systems used in interactive displays. Stakeholders must monitor evolving Ecodesign regulations and national gambling oversight frameworks that increasingly scrutinize skill-based redemption mechanics embedded in location-based attractions.
Market Dynamics
EU Green Deal building efficiency mandates are forcing venue operators across member states to reconfigure HVAC systems, lighting arrays, and motion-platform electrical infrastructure before securing operating permits. This regulatory compression is accelerating capital replacement cycles and reshaping supplier qualification criteria.
Growth Catalysts
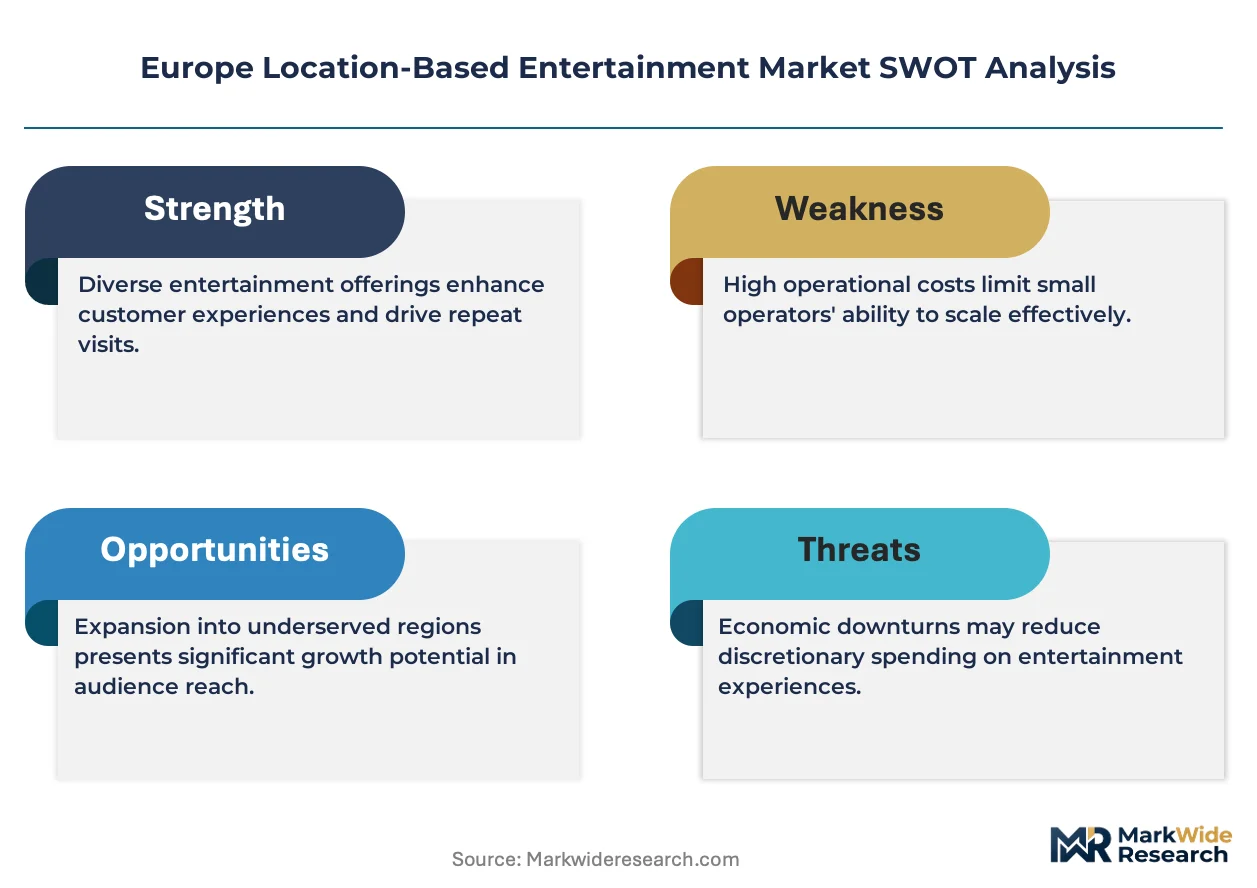
- EU Green Deal energy standards:Member states now require net-zero-ready building envelopes for new entertainment complexes, creating retrofit demand across Germany, France, and the United Kingdom.
- Corporate team-building procurement:Escape room venues in metropolitan clusters report sustained repeat bookings from enterprise clients seeking off-site experiential programming.
- Spatial audio arrays:Theatrical-grade immersive sound systems are becoming baseline specifications for premium venue tenders in London and Paris retail-leisure developments.
Market Restraints
- Motion-platform component concentration:Servo motor and hydraulic actuator supply concentrates among German and Japanese industrial automation suppliers, exposing venue builders to 14-18 week lead times.
- CE marking electrical compliance:Interactive display installations face extended certification timelines under evolving Ecodesign regulations, delaying revenue recognition for new venue openings.
- Residential VR substitution:Consumer-grade headset penetration in Nordic markets diverts discretionary entertainment spending from location-based attractions.
Strategic Opportunities
- Poland and Romania venue development:Secondary metropolitan retail clusters in these markets show underpenetrated immersive entertainment supply relative to household entertainment expenditure growth.
- 3D projection mapping convergence with haptic flooring:Technology layering creates differentiated premium-tier experiences commanding higher per-capita spend in tourist-dense districts.
- France CNIL-compliant visitor analytics:Privacy-respecting footfall and engagement tracking systems open corporate event and educational outreach revenue streams previously restricted by data handling protocols.
Industry Challenges
- Immersive content production talent scarcity:Venue operators struggle to recruit technical directors proficient in Unreal Engine and real-time rendering pipelines for interactive installations.
- Legacy fire safety infrastructure integration:Historic building conversions in Italian and Spanish city centers require expensive suppression system upgrades to accommodate high-occupancy immersive experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Location-Based Entertainment Market |
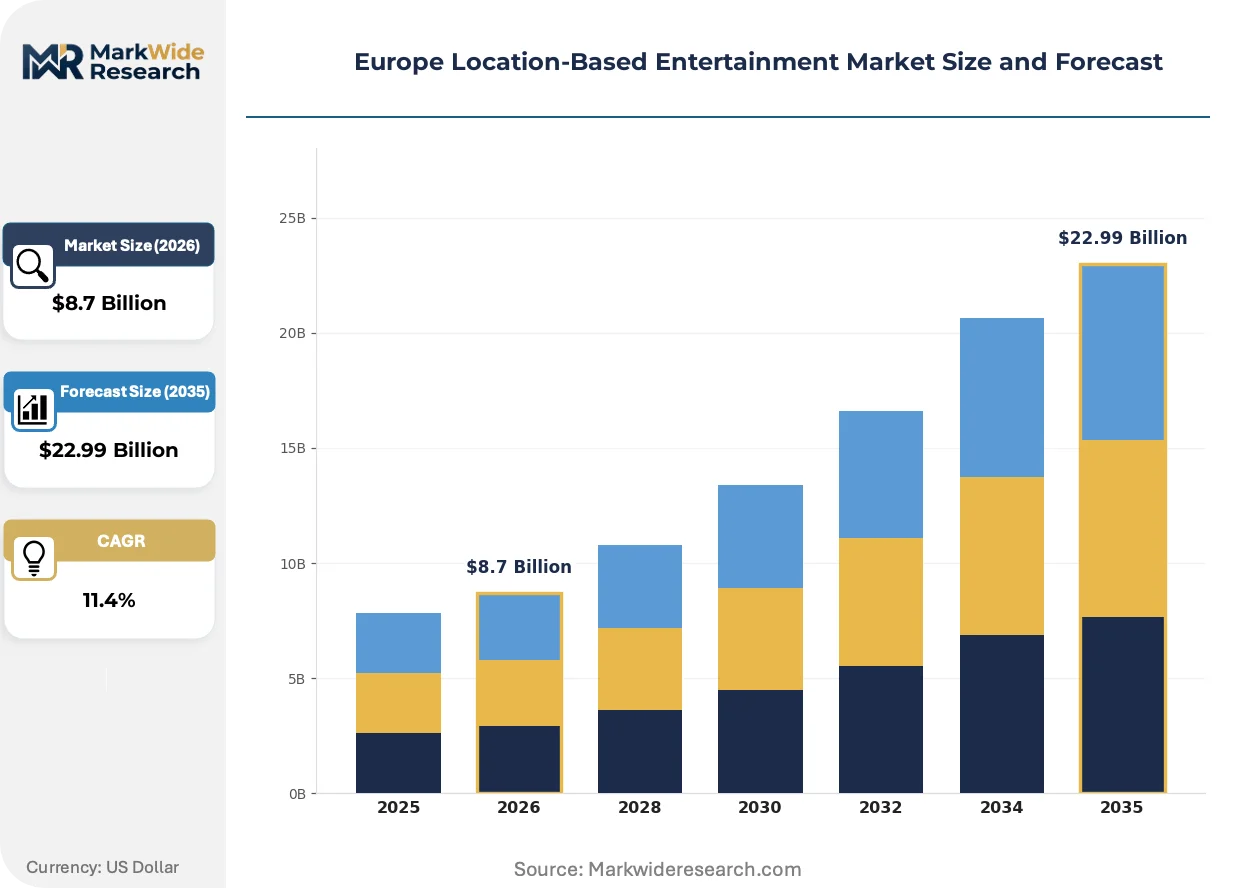
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Escape Rooms, Thematic Attractions Technology: 3D Projection, Motion Sensing, Mobile Apps, Interactive Displays End User: Families, Tourists, Corporate Groups, Schools Installation: Indoor Venues, Outdoor Parks, Theme Parks, Shopping Malls |
| Companies Covered | Teslasuit, Samsung Electronics Co., Ltd., HQSoftware, Hologate, Vicon Motion Systems Ltd., IMAX Corporation, SpringboardVR, Barco NV, Neurogaming Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Location-Based Entertainment Market Evolving Landscape
Real-time rendering pipelines and cloud-based content distribution are compressing production timelines for immersive experiences while enabling dynamic narrative personalization. These technical shifts are reconfiguring capital allocation between hardware infrastructure and software development capabilities.
Cloud-rendered VR streaming is virtualizing the compute-intensive rendering workload that previously required on-premise GPU clusters. Family entertainment centers in British retail parks are adopting this architecture to reduce per-venue hardware capital by 40-50%. The technology is virtualizing the traditional trade-off between visual fidelity and deployment scalability, allowing smaller operators to offer premium-tier experiences.
France's CNIL has tightened consent requirements for biometric data collection in visitor tracking systems used by interactive display installations. Venue operators must now implement explicit opt-in flows for facial recognition and gait analysis deployed for personalization. Thematic attractions in Paris and Lyon are responding by pivoting toward anonymized thermal mapping and smartphone-based interaction protocols that bypass biometric capture entirely.
Corporate procurement of location-based entertainment is fragmenting from centralized event management to departmental self-service booking. Individual business units in German and Dutch enterprises now directly contract escape room and VR arena providers, bypassing traditional hospitality procurement channels. This shift is most pronounced in technology and professional services verticals where team budgets exceed $15,000 annually for experiential programming.
Europe Location-Based Entertainment Market Segmentation
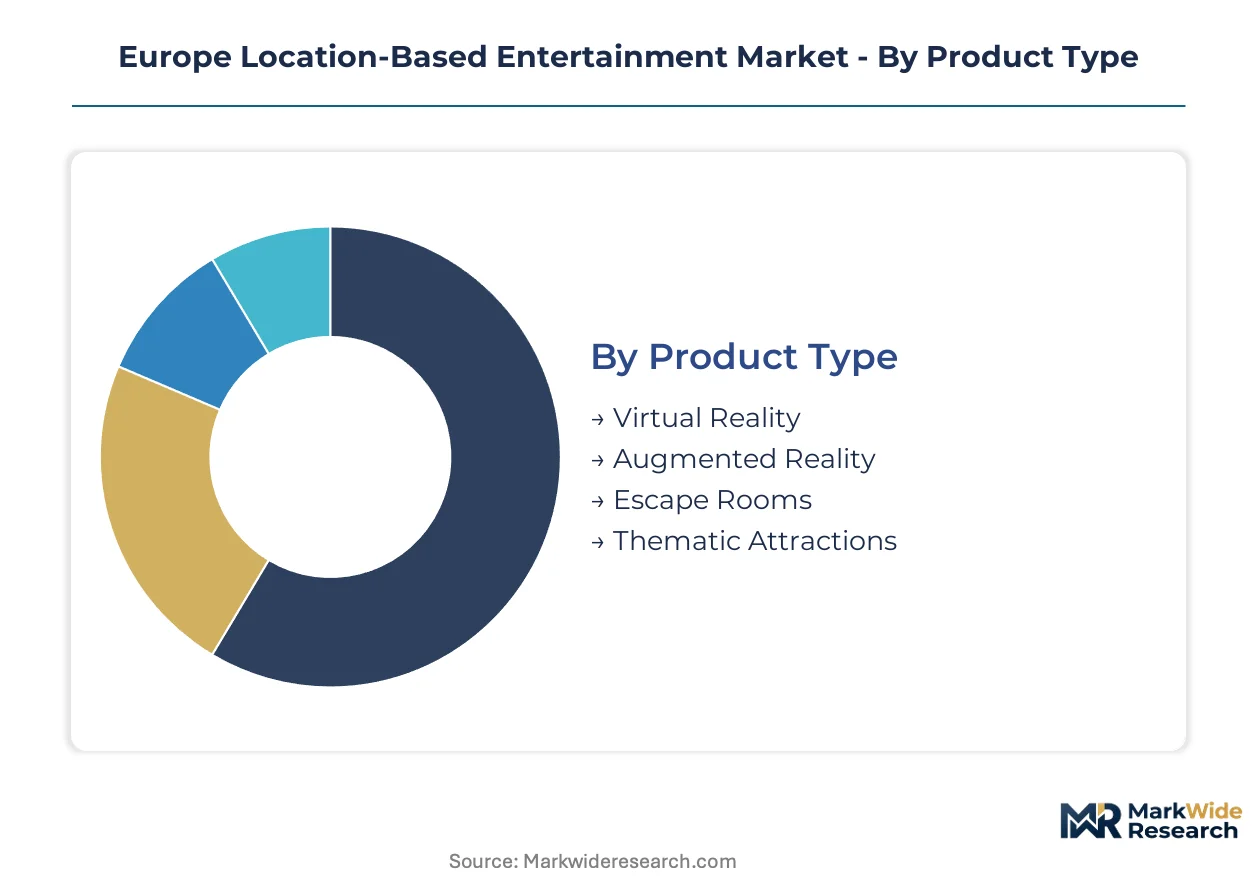
Segmentation in Europe Location-Based Entertainment reveals how technology investment, venue economics, and visitor demographics intersect to determine capital allocation and profitability. Operators configure their offerings around dwell-time optimization, repeat visitation mechanics, and regulatory compliance burdens that vary sharply across product categories.
Product Type:
Use-case spectrum spans solitary immersive escapism to large-group collaborative problem-solving, with each product category commanding distinct buildout economics and content refresh cadences.
- Virtual Reality:Headset-based and free-roam arena systems deploy real-time rendering engines and motion-tracking infrastructure. German and British entertainment complexes anchor premium-tier VR installations in metropolitan retail clusters, driven by corporate procurement of team-building programming.
- Augmented Reality:Smartphone-mediated and projection-based overlays blend physical environments with digital narrative layers. French museums and heritage sites in Lyon concentrate deployment, constrained by CNIL consent requirements for biometric visitor tracking.
- Escape Rooms:Physical puzzle environments with embedded electronics and theatrical set construction. Mature margin tier sustained by repeat corporate bookings in Dutch and German metropolitan markets.
- Thematic Attractions:Multi-technology installations combining projection, audio, and haptic systems in narrative-driven environments. Indoor venues and theme parks justify higher per-square-meter buildout costs through extended dwell-time economics.
Escape Rooms dominate installed base. Virtual Reality is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive infrastructure from software-layer investments that reduce per-venue hardware burdens.
- 3D Projection:Large-format mapping systems using high-lumen laser projectors and spatial calibration software. Thematic attractions in Paris and London tourist districts layer this with haptic flooring to command premium per-capita spend.
- Motion Sensing:Camera arrays, LiDAR, and infrared tracking enabling gesture and position-based interaction. VR arenas across British retail parks deploy this for multiplayer free-roam experiences, though servo motor supply concentration exposes builders to extended lead times.
- Mobile Apps:Smartphone-based interaction protocols that bypass dedicated hardware installation. French operators adopt these to satisfy CNIL-compliant anonymized engagement tracking without biometric capture.
- Interactive Displays:Touch surfaces, transparent OLED, and LED wall installations with embedded compute. CE marking electrical compliance under evolving Ecodesign regulations delays certification timelines for new venue openings.
3D Projection commands highest capital per installation. Mobile Apps are climbing the fastest as privacy-compliant alternatives proliferate.
End User:
Customer type determines booking patterns, from impulse family visitation to contracted corporate programming with annual budget commitments.
- Families:Weekend and holiday visitation seeking multi-generational accessible experiences. Indoor venues in German and French metropolitan retail clusters optimize for this segment through ticket bundling and membership programs.
- Tourists:One-time high-yield visitors concentrated in Paris, London, and Barcelona destination districts. Thematic attractions with localized IP licensing capture this discretionary spending.
- Corporate Groups:Enterprise clients procuring off-site team-building and experiential programming. German and Dutch technology verticals now delegate booking authority to individual business units with dedicated team budgets.
- Schools:Educational outreach programming with curriculum alignment requirements. Museums and science centers in British and Italian cities develop this revenue stream through structured field-trip packages.
Families anchor daily footfall volume. Corporate Groups represent the steepest expansion trajectory as procurement decentralizes.
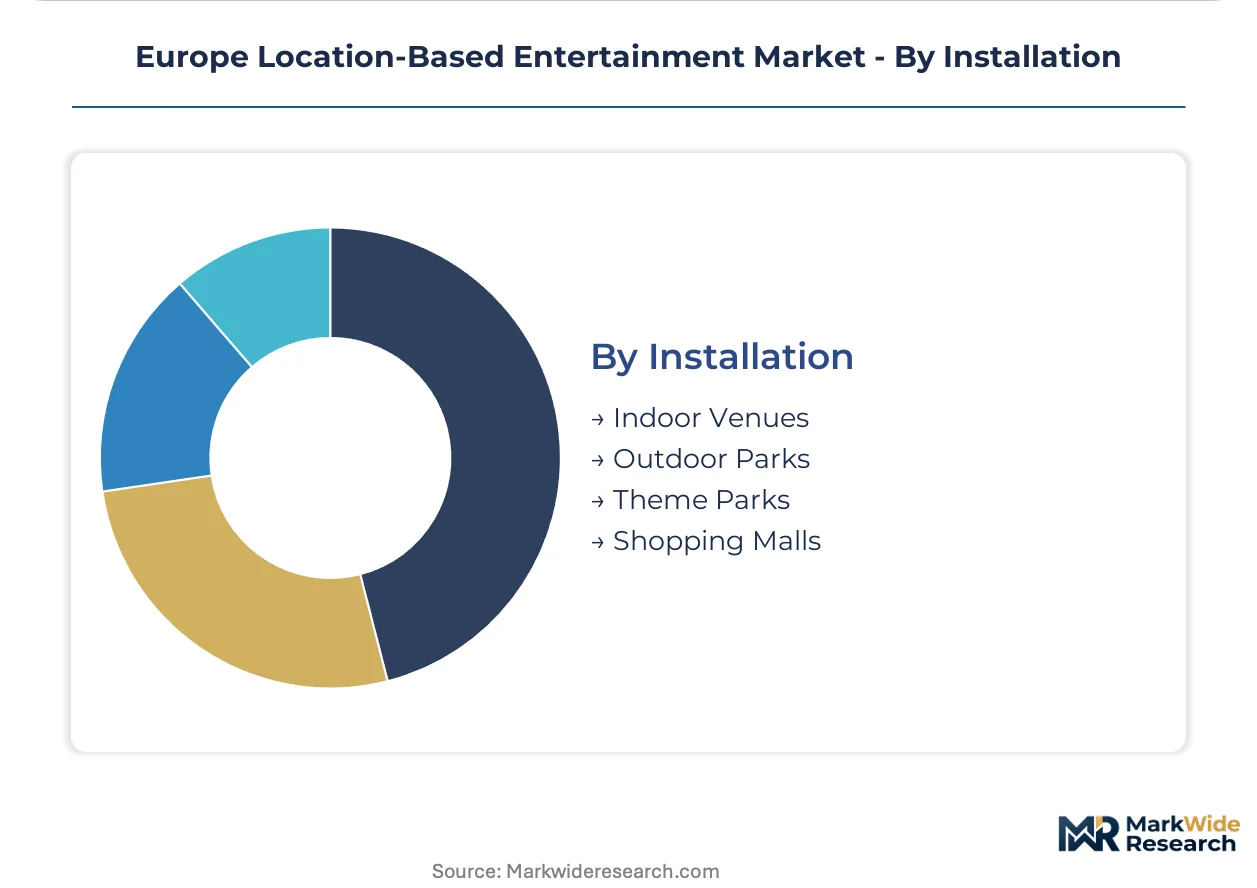
Installation:
Geography and venue type dictate regulatory exposure, from EU Green Deal building efficiency mandates for new construction to fire safety retrofit burdens in historic conversions.
- Indoor Venues:Controlled-environment installations in dedicated entertainment complexes and retail-leisure developments. Demand concentrates in major metropolitan clusters across Germany, France, and the United Kingdom where footfall economics justify premium buildout.
- Outdoor Parks:Seasonal and weather-dependent installations requiring ruggedized equipment enclosures. Mediterranean markets in Spain and Italy face compressed operating calendars that strain amortization schedules.
- Theme Parks:Large-scale integrated destinations with multi-day visitation patterns. Established European park operators in France and the Netherlands anchor immersive technology deployment in flagship attractions.
- Shopping Malls:Footfall-dependent inline and anchor tenant installations in retail-leisure hybrid developments. Polish and Romanian secondary metropolitan clusters show underpenetrated supply relative to household entertainment expenditure growth.
Indoor Venues dominate capital deployment. Shopping Malls are gaining share fastest as retail landlords seek experiential anchors to drive visitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Immersive entertainment venue construction concentrates in German and British metropolitan retail clusters, where footfall economics justify premium buildout costs. France and the Netherlands anchor large-scale theme park integration of immersive technologies. Secondary metropolitan markets in Poland and Romania show widening supply gaps relative to household entertainment expenditure growth.
Germany
Corporate team-building procurement and family entertainment center expansion drive venue development in Berlin, Munich, and Hamburg retail-leisure clusters. The KBA enforces structural standards for motion-platform installations, extending certification timelines for new attractions. North Rhine-Westphalia's Ruhr metropolitan area hosts dense concentrations of VR arena operators serving enterprise clients with dedicated experiential programming budgets.
United Kingdom
Cloud-rendered VR streaming adoption and tourist-dense destination districts in London propel immersive entertainment deployment. CE marking electrical compliance under evolving Ecodesign regulations delays interactive display certification for new venue openings. British retail parks in Greater Manchester and Birmingham anchor family entertainment center clusters adopting virtualized GPU architectures to reduce hardware capital burdens.
France
Museum-based AR overlays and thematic attractions in Paris capture high-yield tourist discretionary spending. The CNIL mandates explicit opt-in flows for biometric data collection in visitor tracking systems, forcing pivot toward anonymized thermal mapping. Lyon and Marseille heritage sites concentrate projection-based immersive installations that bypass facial recognition entirely through smartphone-mediated interaction protocols.
Netherlands
Enterprise escape room procurement and decentralized departmental booking authority reshape corporate experiential programming demand. The EU Green Deal drives net-zero-ready building envelope requirements for new entertainment complexes in Amsterdam and Rotterdam. Eindhoven's technology corridor anchors immersive content production talent pools serving venue operators across the Benelux region.
Poland
Secondary metropolitan retail cluster development and underpenetrated immersive entertainment supply relative to household expenditure growth create expansion opportunities. National building efficiency codes aligned with EU Green Deal mandates reshape venue construction standards in Warsaw and Kraków. Shopping mall landlords in Wrocław and Łódź actively recruit experiential anchors to drive footfall against e-commerce diversion.
Europe Location-Based Entertainment Market Competitive Landscape
Technology infrastructure suppliers and content-integrated venue operators split the market along hardware-versus-experience fault lines. The vendor base organizes around three strategic archetypes: display and semiconductor manufacturers supplying visual infrastructure, proprietary system developers anchoring premium-tier positioning, and content distribution platforms enabling smaller operator market entry. Competitive moves concentrate on technology licensing partnerships and cloud-based content delivery architectures that reduce per-venue capital requirements.
Within the infrastructure supply tier, Samsung Electronics Co., Ltd. and Barco NV represent dominant visual technology anchors. Hologate occupies a position among proprietary system developers leveraging VR arena platforms for premium entertainment complex positioning. IMAX Corporation exemplifies the large-format cinema heritage extension archetype, sustaining brand authority in high-traffic destination venues through immersive experience deployment.
| Leading Market Players |
|---|
| Teslasuit |
| Samsung Electronics Co., Ltd. |
| HQSoftware |
| Hologate |
| Vicon Motion Systems Ltd. |
| IMAX Corporation |
| SpringboardVR |
| Barco NV |
| Neurogaming Ltd |
| Others |
Value Network & Pricing Analysis
German and Japanese industrial automation suppliers concentrate servo motor and hydraulic actuator production, anchoring margin pools with venue builders who face extended procurement cycles and limited sourcing alternatives. This upstream concentration cascades into downstream pricing power for motion-platform integrators while compressing margins for smaller entertainment complex operators unable to secure volume commitments.
Pricing Analysis
After-sales content licensing revenue drives lifetime value across immersive entertainment installations, with recurring IP subscriptions and software maintenance contracts sustaining margin profiles beyond initial hardware deployment. Three-tier pricing structure across premium, standard, and economy levels separates flagship metropolitan venues from secondary retail park installations and mobile pop-up configurations. Cost compression in hardware tiers is intensifying because cloud-rendered VR streaming virtualizes GPU workloads and reduces per-venue capital requirements. Family entertainment centers in British retail parks exhibit highest price sensitivity, while corporate procurement teams in German technology verticals prioritize experiential outcomes over per-capita spend.
Supply Chain Analysis
Taiwanese and South Korean display panel manufacturers hold dominant capacity for high-lumen laser projectors and transparent OLED installations feeding European venue construction. Component sourcing draws from Chinese LED driver assemblies, German precision motion hardware, and Dutch spatial audio array fabrication. Single-source vulnerability concentrates in semiconductor supply for real-time rendering engines, exposing operators to allocation constraints during demand surges. Distribution runs through specialized AV integrators and direct OEM relationships with large-scale theme park operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as EU Green Deal building efficiency mandates and national safety certifications create multi-year barriers for unqualified entrants. Incumbents who secure KBA structural approvals and CNIL-compliant visitor analytics systems embed switching costs that compound over venue operational lifecycles.
For Market Incumbents: Insulate market position by deepening backward integration into proprietary content production pipelines using Unreal Engine talent pools concentrated in Eindhoven and Amsterdam. Pursue CE marking pre-certification for interactive display architectures to compress revenue recognition timelines for new venue openings. Vertical integration into cloud-rendered VR streaming infrastructure counters residential VR substitution threats while reducing hardware capital exposure for franchise expansion.
For New Entrants and Emerging Players: Polish secondary metropolitan retail clusters in Wrocław and Łódź present underpenetrated immersive entertainment supply relative to household expenditure growth and active landlord recruitment of experiential anchors. Romanian shopping mall developments in Cluj-Napoca and Timișoara mirror this white-space opportunity with comparable footfall economics and limited incumbent saturation. Corporate team-building procurement decentralization in German and Dutch enterprises offers direct departmental contracting channels that bypass traditional hospitality gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed VR arena operators who scaled through hardware-heavy deployment models now facing cloud virtualization disruption. Five-to-ten year viability hinges on content refresh cadence and recurring licensing revenue attachment rates rather than one-time installation margins. Acquisition targets should demonstrate CNIL-compliant visitor analytics capabilities and established relationships with metropolitan retail landlords. The signal to watch is corporate procurement budget fragmentation accelerating escape room and VR arena direct contracting by individual business units.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Rendered VR Streaming Deployment | Virtualizes GPU workloads to reduce per-venue hardware capital by 40-50% for British retail park operators. |
| CNIL-Compliant Visitor Analytics Development | Enables privacy-respecting engagement tracking that opens corporate event revenue streams in French museums. |
| Proprietary Content Production Pipeline | Secures Unreal Engine talent pools in Eindhoven to compress immersive experience development timelines. |
| Net-Zero-Ready Building Envelope Certification | Satisfies EU Green Deal mandates for new entertainment complexes in Amsterdam and Rotterdam developments. |
| Corporate Procurement Direct Channel | Bypasses traditional hospitality gatekeepers to capture decentralized team-building budgets in German technology verticals. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with venue operators, immersive technology integrators, corporate event procurement managers, and retail landlord development teams; and secondary validation through EU Ecodesign regulatory filings, national building permit databases, and entertainment complex investment disclosures. Bottom-up triangulation aggregated individual venue economics and content licensing contracts, while top-down analysis cross-referenced metropolitan retail footfall indices and household entertainment expenditure surveys.
Forecast inputs span product type segmentation across VR arena systems, AR museum overlays, escape room installations, and thematic attractions; technology layers including 3D projection, motion sensing, and mobile app protocols; end-user categories from family visitation to corporate programming; and installation types across indoor venues, outdoor parks, theme parks, and shopping malls. CAGRs were derived from regression analysis against macroeconomic indicators and regulatory implementation timelines. Industry-specific inputs incorporate KBA structural certification backlogs and CNIL consent requirement enforcement patterns.
Practitioners should monitor CE marking electrical compliance timeline extensions and servo motor supply allocation constraints for early signals of venue opening delays and capital deployment friction. Forecasts reflect assumptions regarding EU Green Deal building efficiency mandate adherence rates and corporate procurement decentralization velocity. Quarterly review of national permit issuance data and immersive content production talent pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Online Entertainment Market
Digital Media
Middle East Gaming Market
Digital Media
Adult Entertainment Market
Digital Media
Digital Music Services Market
Digital Media
LED Stadium Screens Market
Digital Media
North America Photographic Services Market
Digital Media
VFX Market
Digital Media
Mexico Webtoons Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Indonesia Digital Media Market
Digital Media
Digital Content Creation Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Europe Online Video Platform Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Da Vinci Systems Market