
 Indonesia Digital Media Market | 2026-2036
Indonesia Digital Media Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Digital Media Market Insights
Indonesian over-the-top streaming capacity is hardening as fiber-to-the-home rollout accelerates in Java and Sumatra. PT Vidio Dot Com leverages its local sports rights portfolio to anchor live viewership during Liga 1 football seasons. Netflix Pte. Ltd. competes through original Indonesian-language productions filmed in Jakarta and Bali. PT Telkom Indonesia controls last-mile broadband access, extending its infrastructure advantage into bundled streaming partnerships.
Indonesia digital media encompasses content creation, distribution, and monetization across internet-connected devices, relying on adaptive bitrate streaming protocols and programmatic ad insertion to deliver personalized experiences to audiences. The primary commercial purpose is capturing consumer attention and converting engagement into advertising revenue or direct subscription payments. Video streaming leads content type monetization due to higher CPM rates and brand safety preferences from FMCG advertisers. Mobile apps dominate platform access, though smart TV penetration is accelerating in middle-income households across Greater Jakarta. Ad-supported models sustain the largest user base, while subscription-based tiers capture disproportionate margin from urban professionals seeking ad-free experiences.
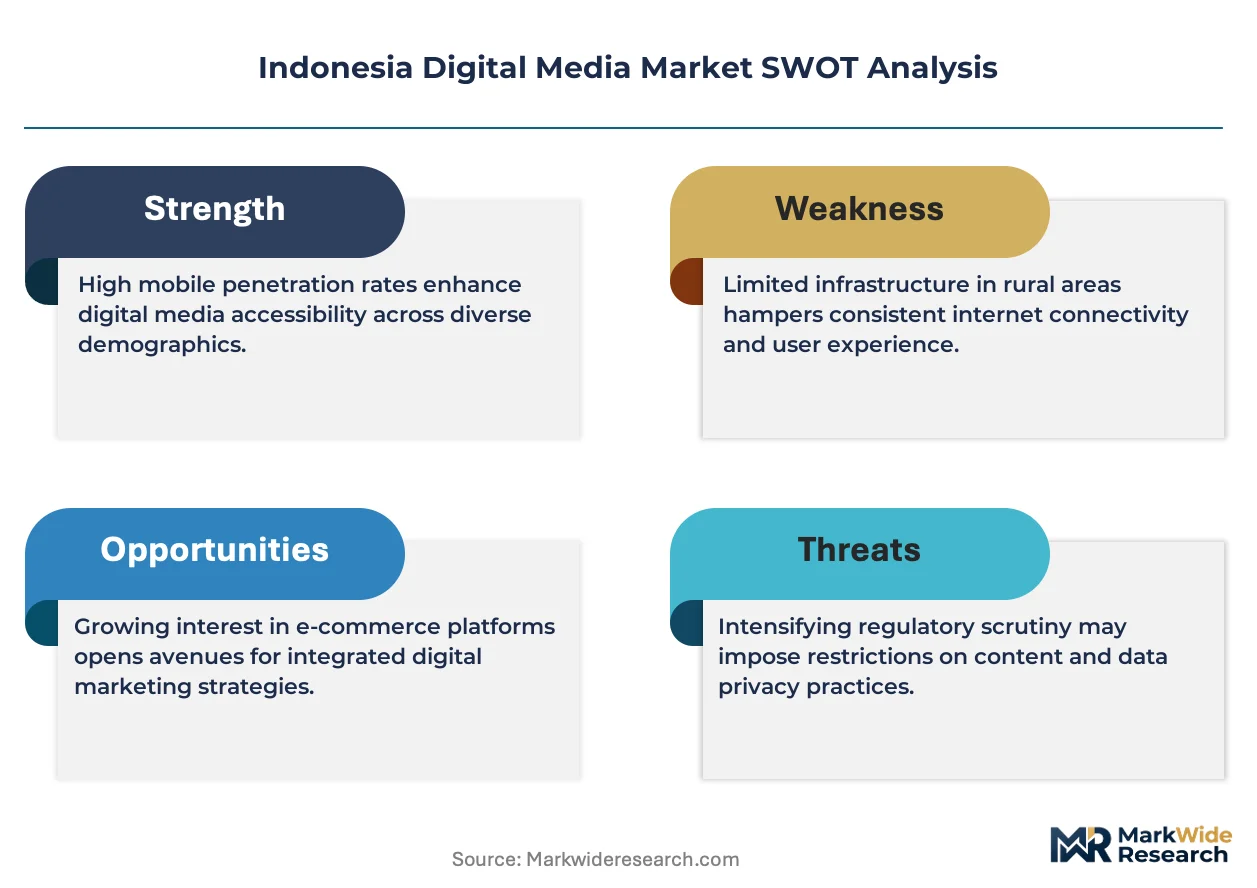
Indonesia's Ministry of Communication and Informatics enforces content licensing requirements under the Broadcasting Law, while the Financial Services Authority monitors fintech advertising disclosures in digital channels. These frameworks elevate compliance costs for foreign platforms and create preferential conditions for domestically registered operators. Stakeholders must monitor evolving data localization mandates and cross-border content taxation proposals that could reshape platform economics and partnership structures.
Market Dynamics
Indonesia's Electronic Information and Transactions Law is compressing platform economics by forcing foreign operators into domestic licensing structures and content moderation compliance, while fiber infrastructure deployment in Java and Sumatra is redistributing streaming capacity toward provincial urban centers.
Growth Catalysts
- Broadcasting Law licensing mandates:Domestic registration requirements under Indonesia's Ministry of Communication and Informatics create preferential operational conditions for locally registered platforms versus foreign competitors.
- Mobile-first consumer behavior:Smartphone penetration in Jakarta and Surabaya drives video advertising conversion rates for FMCG brands seeking attention capture on handheld devices.
- Fiber-to-the-home rollout:PT Telkom Indonesia's infrastructure expansion into Java and Sumatra enables adaptive bitrate streaming quality that supports premium subscription tiers.
Market Restraints
- Data localization compliance costs:Proposed cross-border content taxation and server location mandates elevate operational overhead for platforms with distributed cloud architectures.
- Last-mile broadband concentration:PT Telkom Indonesia's control over fixed-line access creates dependency risk for streaming services seeking bundled distribution partnerships.
- Content moderation staffing intensity:Electronic Information and Transactions Law enforcement requires human reviewer scale that compresses margin structures for user-generated content platforms.
Strategic Opportunities
- Eastern Indonesia connectivity gaps:Kalimantan and Sulawesi present underpenetrated addressable markets where satellite and fixed wireless infrastructure investments could unlock first-mover streaming adoption.
- Programmatic ad insertion convergence:Integration of real-time bidding systems with live sports broadcasts enables dynamic creative optimization during Liga 1 football seasons.
- Fintech advertising disclosure frameworks:Financial Services Authority monitoring creates compliant partnership pathways between streaming platforms and digital payment providers.
Industry Challenges
- Local-language content production talent scarcity:Scriptwriting and production management expertise for Indonesian-language original series lags behind platform commissioning demand.
- Legacy broadcast licensing complexity:Simultaneous digital and terrestrial rights negotiations for sports content fragment exclusivity windows and inflate acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Digital Media Market |
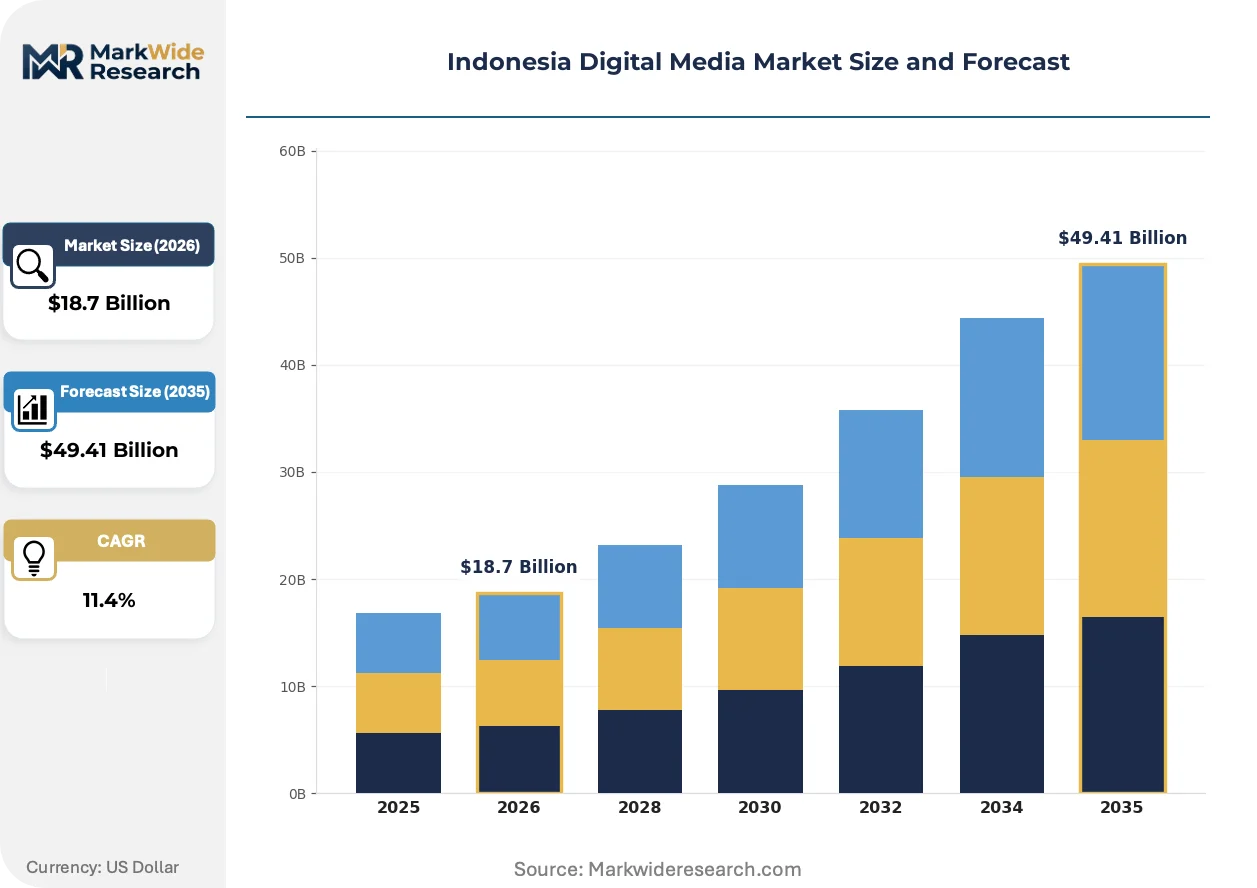
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video Streaming, Social Media, Digital News, Online Gaming Platform: Mobile Apps, Websites, Smart TVs, Tablets Subscription Model: Freemium, Subscription-Based, Ad-Supported, Pay-Per-View Advertising Format: Display Ads, Video Ads, Sponsored Content, Native Advertising |
| Companies Covered | PT Vidio Dot Com, PT Media Nusantara Citra Tbk, Kompas Gramedia, Trans Media, MNC Media, Emtek Group, Netflix Pte. Ltd., Spotify AB, PT Telkom Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Digital Media Market Trends and Innovations
Streaming technology architecture is pivoting toward edge-caching and live-event infrastructure as sports rights become the primary battleground for subscriber retention, while regulatory pressure on content moderation is automating compliance workflows.
Serverless edge computing is consolidating video delivery architecture by pushing transcoding and caching closer to provincial ISPs. Mid-tier streaming operators in Surabaya and Bandung are adopting these distributed nodes to reduce transit costs. This infrastructure shift is consolidating competitive position for platforms without direct CDN ownership.
Indonesia's Ministry of Communication and Informatics is tightening content classification requirements under the Broadcasting Law. Foreign platforms must now deploy domestic content review teams with Indonesian-language fluency. Live sports broadcasters face the steepest compliance burden due to real-time moderation demands during Liga 1 matches.
Subscription bundling is displacing standalone direct-to-consumer signups as the dominant acquisition channel. Telco-OTT partnerships through PT Telkom Indonesia's IndiHome service are capturing urban household consolidation. This channel shift is most pronounced in Greater Jakarta, where fixed broadband penetration supports multi-service household contracts.
Indonesia Digital Media Market Segmentation
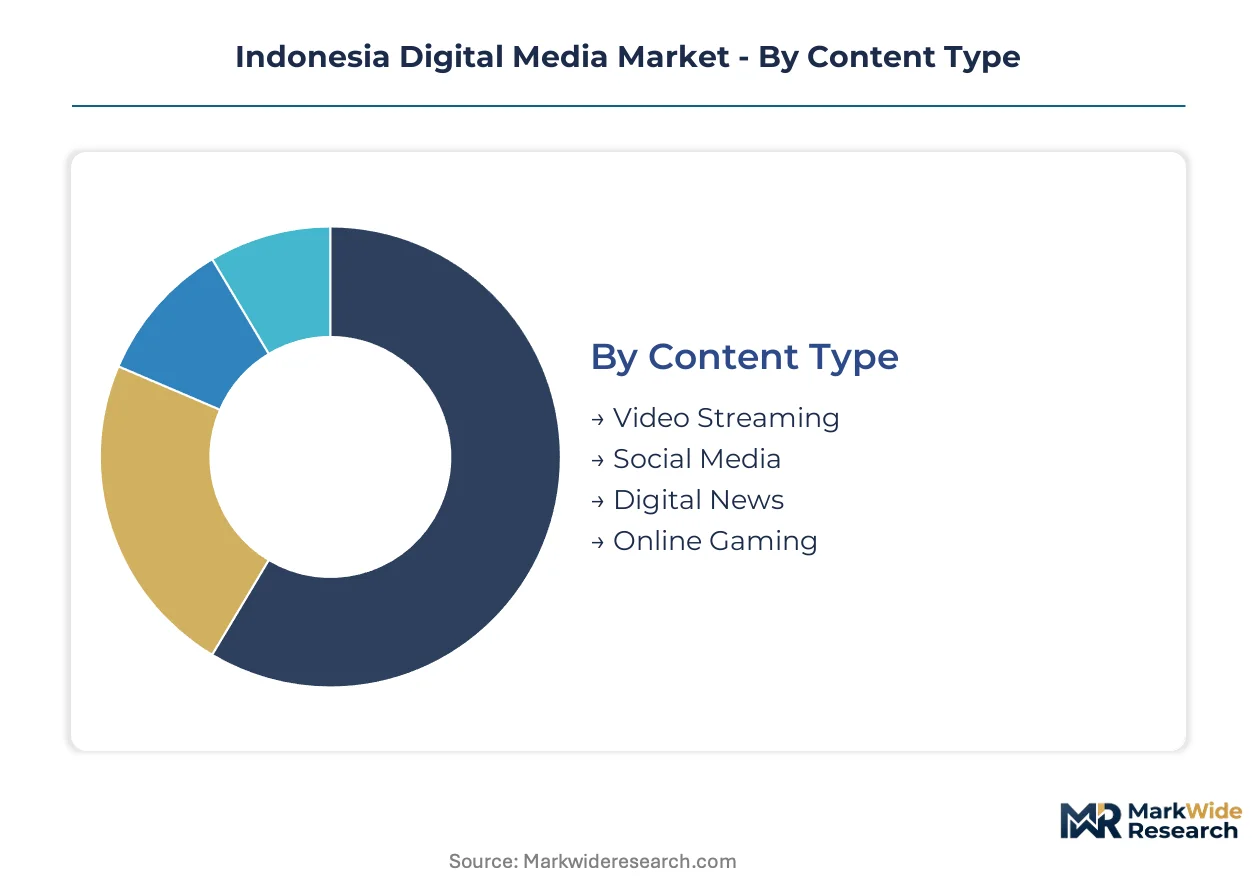
Segmentation in Indonesia digital media reveals how infrastructure maturity and regulatory pressure fragment monetization pathways. Platform economics diverge sharply between mobile-first ad-supported models and fiber-enabled subscription tiers. Understanding these divides exposes where capital concentrates and where compliance costs erode returns.
Content Type:
Upgrade cycles in content consumption follow device replacement and connectivity improvements rather than format innovation alone.
- Video Streaming:Adaptive bitrate protocols deliver HD and 4K content to Java and Sumatra households with fiber-to-the-home access. Demand clusters in Greater Jakarta where PT Telkom Indonesia's IndiHome bundles reduce subscriber acquisition friction. Liga 1 football rights anchor live viewing windows that advertisers pay premium CPMs to access.
- Social Media:Short-form video and user-generated content platforms dominate daily active engagement through smartphone interfaces. The Electronic Information and Transactions Law forces domestic content moderation teams, elevating operational overhead for foreign operators while creating regulatory shelter for locally registered competitors.
- Digital News:Text and multimedia journalism distributed through mobile-optimized websites and dedicated apps.
- Online Gaming:Multiplayer and casual gaming titles monetizing through in-app purchases and advertising integrations.
Video Streaming sits at the top of the volume ranking, with Social Media climbing the fastest.
Platform:
Cost tier structures separate premium experiences on large screens from mass-market access on handheld devices.
- Mobile Apps:Native iOS and Android applications optimized for Indonesia's smartphone-dominant user base. FMCG advertisers concentrate spend here to capture attention during commute and evening leisure hours in Jakarta and Surabaya.
- Websites:Responsive web portals serving users without app storage capacity or preference for browser-based access.
- Smart TVs:Application ecosystems on connected television sets enabling lean-back viewing in middle-income households. Fiber infrastructure expansion in Java unlocks addressable inventory for premium subscription tiers and high-CPM video advertising.
- Tablets:Larger-screen mobile devices serving education and entertainment use cases with intermediate portability.
Mobile Apps command the largest installed base, while Smart TVs gain share fastest where broadband density permits.
Subscription Model:
Customer type determines willingness to pay for ad-free experiences versus tolerance for interruption in exchange for free access.
- Freemium:Tiered access models offering basic content libraries with upgrade prompts to premium tiers. Urban professionals in Jakarta convert at higher rates where disposable income supports subscription commitments.
- Subscription-Based:Recurring monthly or annual payments for full content access without advertising interruption. Telco bundling through PT Telkom Indonesia partnerships reduces churn and acquisition costs in Greater Jakarta.
- Ad-Supported:Free access funded entirely by programmatic and direct-sold advertising inventory. The mass-market foundation sustaining reach for FMCG brands seeking nationwide audience coverage.
- Pay-Per-View:Transactional access to individual live events or premium content titles. Liga 1 football matches and theatrical releases drive spikes in one-time purchase behavior.
Ad-Supported models reach the widest audience, with Subscription-Based tiers expanding most quickly among urban households.
Advertising Format:
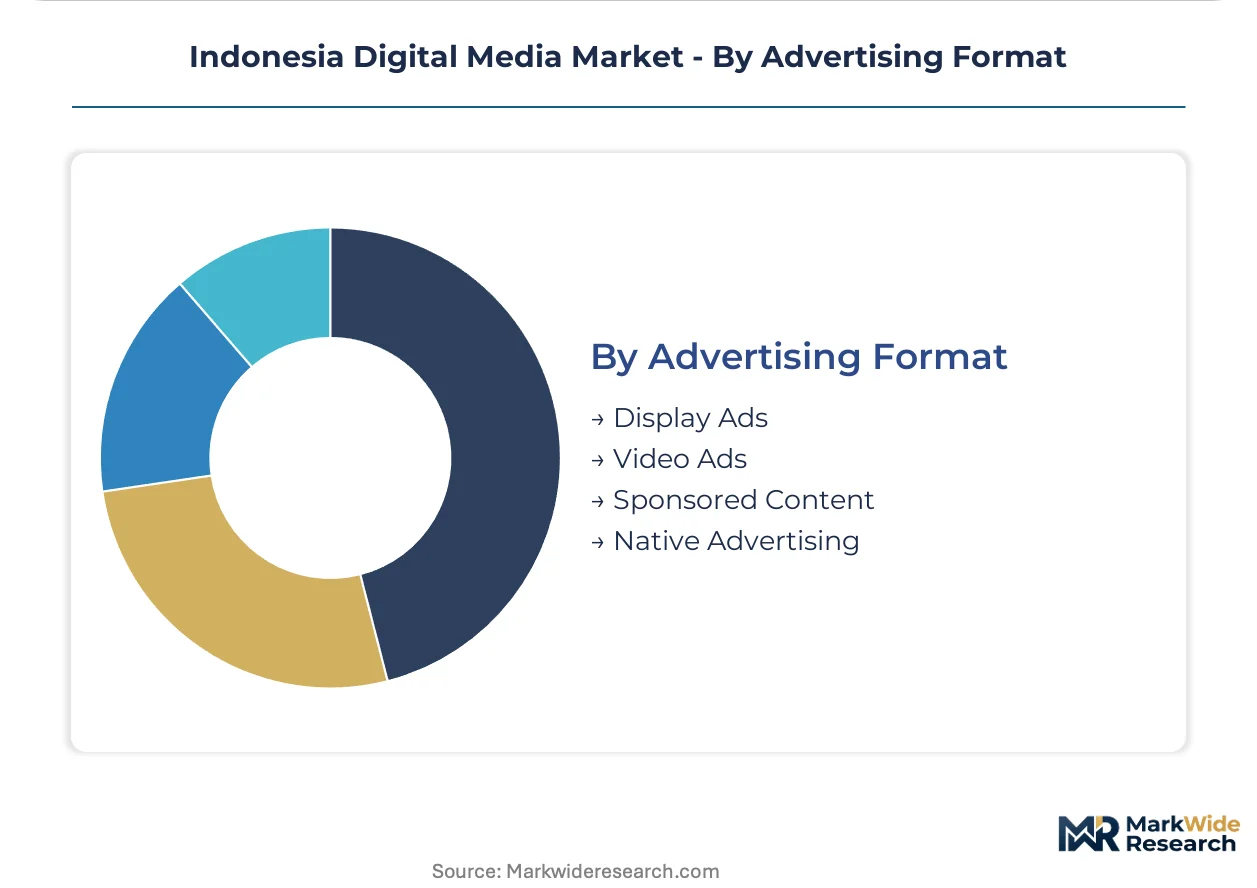
Supply concentration in programmatic infrastructure favors formats with real-time bidding compatibility and brand safety verification.
- Display Ads:Banner and rich media placements on websites and mobile applications. Inventory oversupply in social media feeds compresses effective CPMs outside premium publisher contexts.
- Video Ads:Pre-roll, mid-roll, and outstream video placements commanding premium rates from brand advertisers. The Broadcasting Law's content classification requirements elevate brand safety assurance costs for publishers.
- Sponsored Content:Native editorial and creator partnerships blending promotional messaging with platform-native formats. Financial Services Authority disclosure mandates apply to fintech and investment product integrations.
- Native Advertising:In-feed and recommendation-driven placements matching surrounding content aesthetics. Algorithmic optimization drives performance improvements in engagement metrics.
Video Ads generate the highest revenue per impression, with Sponsored Content expanding fastest as creator economy infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is fragmenting platform economics across Southeast Asia as Indonesia's Electronic Information and Transactions Law forces domestic licensing structures that elevate compliance costs for foreign operators relative to neighboring jurisdictions with lighter content moderation mandates.
Java
Greater Jakarta and Surabaya concentrate Indonesia's digital media demand through fiber-enabled households and smartphone-dense commuter corridors. The Ministry of Communication and Informatics enforces Broadcasting Law licensing requirements most stringently in these metropolitan zones. Bandung's creative economy cluster supplies production talent for original Indonesian-language series commissioned by streaming platforms.
Sumatra
Medan and Palembang represent underpenetrated expansion targets where PT Telkom Indonesia's fiber rollout is accelerating fixed broadband penetration. Provincial regulators apply Electronic Information and Transactions Law provisions with variable enforcement intensity relative to Java. Batam's free trade zone status creates content hosting arbitrage opportunities for platforms seeking reduced cross-border data taxation exposure.
Kalimantan
Satellite and fixed wireless infrastructure gaps constrain streaming quality outside Balikpapan and Samarinda urban cores. The national government's Palapa Ring fiber backbone extension promises last-mile connectivity improvements by 2026. Pontianak's border proximity to Malaysia creates cross-border content licensing complexity for platforms operating under Indonesian jurisdiction.
Sulawesi
Makassar anchors Eastern Indonesia's digital media consumption through mobile-first engagement patterns on 4G networks. Local content moderation staffing for Indonesian-language fluency remains scarce relative to Java-based reviewer pools. Manado's tourism economy supports niche demand for premium international content among hospitality sector professionals.
Bali and Nusa Tenggara
Denpasar's creative production infrastructure attracts international streaming platforms filming original Indonesian content. Tourism-dependent advertising demand fluctuates seasonally, compressing CPM rates during low-occupancy months. The island's geographic isolation elevates CDN transit costs for platforms without edge-caching partnerships with local ISPs.
Indonesia Digital Media Market Competitive Landscape
Jakarta-based media conglomerates anchor one tier through integrated broadcast-digital assets and domestic sports rights portfolios; international streaming specialists hold differentiated positions through original Indonesian-language production investments and global content libraries. Market structure tilts toward consolidation as telco-OTT bundling through PT Telkom Indonesia partnerships reduces standalone platform viability. Three archetypes dominate: vertically integrated domestic media groups, international subscription platforms with localized content slates, and telecom operators leveraging last-mile infrastructure control. Competitive intensity centers on exclusive sports rights acquisition and telco distribution partnership exclusivity.
Within the domestic integrated media tier, PT Vidio Dot Com and PT Media Nusantara Citra Tbk exemplify archetypes combining broadcast heritage with digital platform extension. Netflix Pte. Ltd. occupies a position representing international subscription platforms investing in Jakarta and Bali production facilities. PT Telkom Indonesia anchors the infrastructure-leveraged operator archetype through IndiHome bundling and last-mile broadband control. These three entities collectively illustrate how regulatory compliance costs, content production localization, and distribution infrastructure access define competitive positioning boundaries.
| Leading Market Players |
|---|
| PT Vidio Dot Com |
| PT Media Nusantara Citra Tbk |
| Kompas Gramedia |
| Trans Media |
| MNC Media |
| Emtek Group |
| Netflix Pte. Ltd. |
| Spotify AB |
| PT Telkom Indonesia |
| Others |
Pricing and Supply Chain Analysis
Indonesia's Electronic Information and Transactions Law enforcement gates both qualified supply and premium-tier pricing access by mandating domestic content moderation infrastructure that foreign platforms must fund before competing on ad-supported or subscription tiers.
Pricing Analysis
Telco bundling discounts through PT Telkom Indonesia's IndiHome partnerships anchor pricing differentiation between urban fiber-enabled households and mobile-only users. Three-tier pricing structure across premium, standard, and economy levels separates ad-free subscription tiers from freemium upgrades and fully ad-supported access. Cost compression in ad-supported tiers is intensifying because FMCG advertisers concentrate spend on verified brand-safe inventory. Price-sensitive rural mobile users tolerate interruption-heavy experiences, while Jakarta professionals pay premiums for bundled multi-service contracts.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure and CDN capacity are emerging as streaming platforms seek alternatives to PT Telkom Indonesia's last-mile dominance. Content production draws from Jakarta's creative clusters, Bali's international filming facilities, and Singapore's post-production houses. Supply chain risk centers on single-source vulnerability in fixed broadband access where IndiHome controls household connectivity. Distribution runs through telco-OTT partnerships, direct app store downloads, and smart TV manufacturer pre-installs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's digital media market operates as a regulatory compounder where Electronic Information and Transactions Law compliance investments by foreign platforms create acquisition demand for domestically licensed operators with established moderation infrastructure.
For Market Incumbents: Deploy exclusive sports rights acquisition as the primary retention lever against international subscription platforms. Secure Liga 1 broadcasting exclusivity through multi-season contracts that lock out competitor live-event strategies. Deepen telco bundling partnerships with PT Telkom Indonesia to reduce subscriber acquisition costs in Greater Jakarta. Invest in domestic content review team scale to maintain compliance margin advantage under Ministry of Communication and Informatics enforcement timelines. For New Entrants and Emerging Players: Launch via satellite and fixed wireless infrastructure partnerships targeting Kalimantan and Sulawesi connectivity gaps. Eastern Indonesia's underpenetrated streaming adoption offers first-mover positioning before Palapa Ring fiber extensions mature. Prioritize ad-supported models with lightweight data requirements suited to 4G network constraints. Partner with provincial ISPs for edge-caching nodes that reduce transit costs relative to national CDN contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier streaming operators with domestic licensing credentials but sub-scale sports rights portfolios. Long-term viability hinges on regulatory shelter duration and content production localization capabilities. Target acquisition archetypes combine Broadcasting Law compliance infrastructure with undermonetized regional user bases. Watch Ministry of Communication and Informatics data localization mandate timing as the critical inflection signal for platform economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Moderation Infrastructure | Ministry of Communication and Informatics licensing requirements force operational presence that foreign platforms must acquire or build. |
| Liga 1 Sports Rights Exclusive Licensing | Live football viewership anchors advertiser premium CPMs and subscriber retention during seasonal competition windows. |
| Telco-OTT Bundle Partnership Expansion | PT Telkom Indonesia's IndiHome integration reduces churn and acquisition friction in fiber-enabled Jakarta households. |
| Edge-Caching Node Provincial Deployment | Distributed infrastructure in Surabaya and Bandung cuts transit costs for mid-tier operators lacking direct CDN ownership. |
| Original Indonesian-Language Production Investment | Netflix Pte. Ltd. and domestic platforms compete for Jakarta and Bali filming capacity to meet local content quotas. |
Research Methodology
Multiple input streams — executive interviews with streaming platform operators, regulatory compliance officers at Ministry of Communication and Informatics, and PT Telkom Indonesia partnership managers — were reconciled against secondary validation from Broadcasting Law filings, Electronic Information and Transactions Law enforcement records, and fiber infrastructure deployment disclosures. Bottom-up subscriber and advertising revenue estimates were triangulated with top-down market sizing from telco bundling contract analysis and FMCG media spend allocations.
Data-stream reconciliation across the projection horizon applied segmentation modeling by content type, platform access mode, subscription tier, and regional infrastructure maturity. CAGRs were derived from installed base growth curves, ARPU progression assumptions, and ad load optimization trajectories. Forecast inputs incorporated Palapa Ring fiber extension timelines, smartphone replacement cycles in Jakarta and Surabaya, and sports rights contract renewal schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated data localization mandates or sudden Broadcasting Law licensing suspensions. Forecasts reflect assumptions about regulatory enforcement intensity, infrastructure rollout pacing, and advertiser budget reallocation between digital and legacy channels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Online Gambling Market
Digital Media
Drone Wedding Photography Market
Digital Media
Global ACGN Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Middle East Gaming Market
Digital Media
Digital Effects Services Market
Digital Media
3D Animation Market
Digital Media
Video Wall Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Video Production Market
Digital Media
Europe Online Gambling Market
Digital Media
Sound Effects Services Market
Digital Media
Stream Hosting Market
Digital Media
Digital Content Creation Market
Digital Media
In Flight Entertainment Market
Digital Media
Anime Derivatives Market