
 Digital Content Market | 2026-2036
Digital Content Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Content Market Insights
India is reconfiguring its digital infrastructure with expanded data center capacity and localized cloud regions to support surging content creation workloads. Google leverages its search and YouTube ecosystems to anchor advertising-supported distribution at massive scale. Adobe specializes in professional-grade creative software that dominates enterprise workflows for image and video production. NVIDIA sustains its position through GPU architectures that power generative AI rendering and real-time content synthesis pipelines.
Digital content encompasses encoded media assets—video, audio, text, and image files—produced, processed, and distributed through software-defined pipelines operating at resolutions up to 8K with adaptive bitrate streaming protocols. Its primary commercial purpose is to enable information transfer, entertainment delivery, and brand communication across networked endpoints. Video content within the content type segment commands the largest current revenue pool due to bandwidth expansion and streaming platform proliferation, while generative AI-assisted text and image creation represents the fastest-expanding margin opportunity. The monetization model dimension shows subscription structures capturing predictable recurring value, whereas advertising models compete for volume scale in social media and mobile app channels.
The EU Digital Services Act and GDPR impose content moderation transparency and data processing constraints on platforms serving European users, directly shaping product architecture and compliance expenditure. In the United States, the FCC and emerging state-level privacy statutes create a layered regulatory environment that fragments platform operational standards. India's BIS guidelines and the country's proposed digital content regulation framework signal tighter oversight of streaming catalogues and intermediary liability. Stakeholders must monitor how divergent jurisdictional requirements for algorithmic accountability and creator compensation reshape platform economics and technology investment priorities.
Market Dynamics
Generative AI diffusion is collapsing production timelines for video, image, and text assets while fragmenting creator economics across professional and amateur tiers.
Growth Catalysts
- EU Digital Services Act:Content moderation transparency mandates are forcing platform upgrades that expand enterprise software demand for compliance tooling.
- India's data center expansion:Localized cloud regions in Mumbai, Hyderabad, and Chennai are reducing latency for regional-language streaming pipelines.
- GPU architecture advances:Real-time rendering clusters are enabling 8K adaptive bitrate streaming at consumer price points.
Market Restraints
- Energy cost volatility:AI training and inference workloads face input cost pressure from electricity pricing swings affecting data center operations.
- Foundry concentration:Advanced semiconductor manufacturing concentrates in Taiwan and South Korea, creating supply vulnerability for rendering hardware.
- GDPR data localization:Cross-border content distribution incurs regulatory friction that fragments platform architecture.
Strategic Opportunities
- Brazil's underpenetrated mobile creator economy:Portuguese-language short-form content platforms show whitespace for localized creative tool adoption.
- AI-human workflow convergence:Text-to-video and image-to-3D pipelines are opening new service layers between raw generation and final production.
- India's PLI scheme for electronics:Manufacturing incentives are attracting assembly investment for tablets and smartphones that anchor content consumption.
Industry Challenges
- Prompt engineering talent scarcity:Enterprises face skill gaps in optimizing generative model outputs for brand-consistent creative production.
- Legacy rights management systems:IP tracking infrastructure struggles to accommodate AI-generated derivative works and automated licensing.
- Multi-jurisdiction compliance timelines:Platforms must sequence deployments across divergent national content regulation frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Content Market |
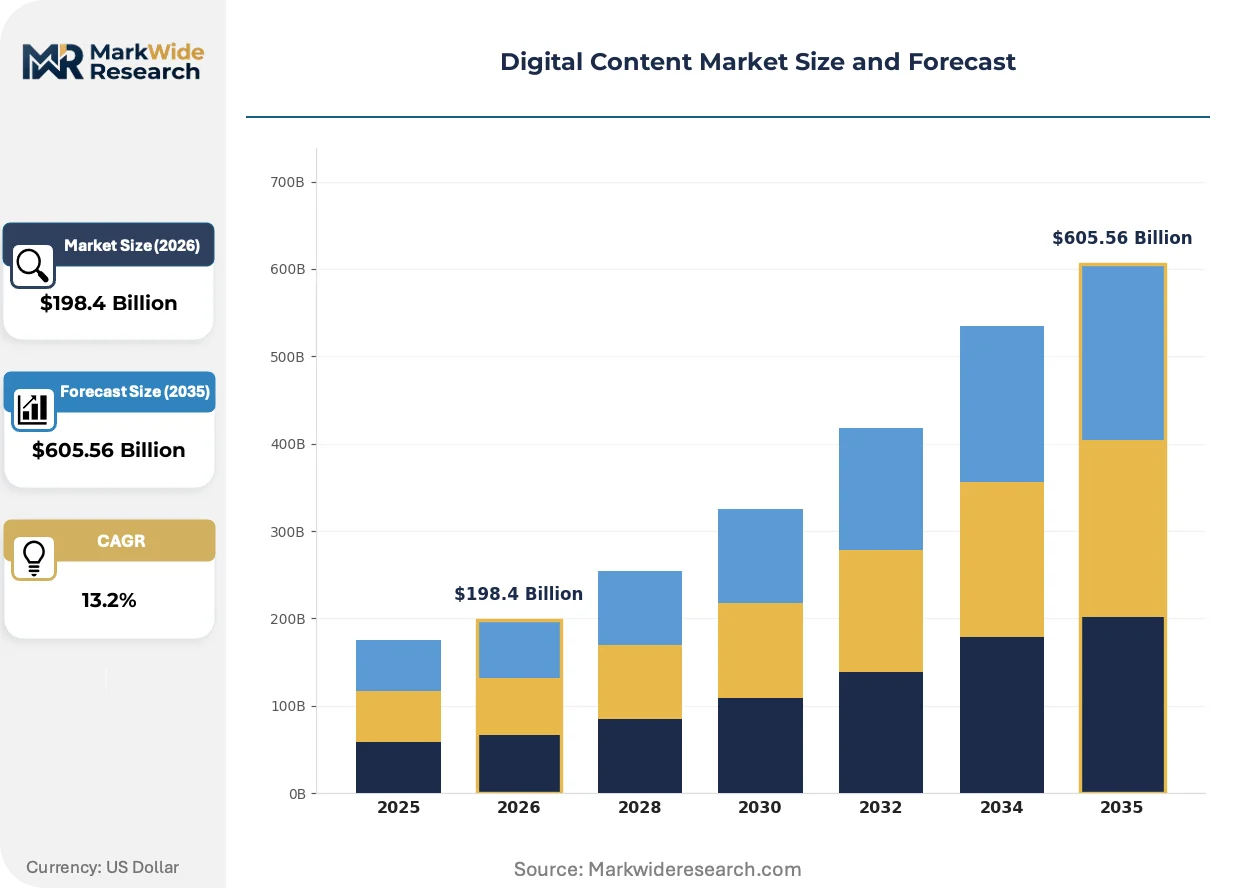
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $605.56 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video, Audio, Text, Image Distribution Channel: Social Media, Websites, Streaming Platforms, Mobile Apps Monetization Model: Subscription, Advertising, Pay-Per-View, Freemium End User: Individuals, Businesses, Educational Institutions, Non-Profits |
| Companies Covered | Adobe, Google, Microsoft, Apple, Autodesk, Canva, Aptara, NVIDIA, Vimeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Content Market Trends and Innovations
Production pipelines are compressing from months to hours as generative models displace manual asset creation, while regulatory fragmentation forces architectural modularity.
Neural radiance fields (NeRFs) are collapsing the distinction between captured and synthetic video by reconstructing 3D scenes from sparse 2D inputs. Film studios and game developers in California adopt these pipelines for virtual production stages. The technology is collapsing location shooting requirements and reducing post-production vendor dependencies.
GDPR's algorithmic accountability provisions are mandating explainability layers for content recommendation systems across platforms serving European users. This forces engineering investment into interpretable ranking models that can document decision pathways. Video streaming services face the steepest compliance burden due to personalized feed complexity.
Subscription fatigue among North American consumers is fragmenting entertainment budgets across more niche services with shorter commitment periods. Platforms respond with hybrid ad-supported tiers that trade data collection for reduced fees. This pattern is most visible in the United States where average household streaming subscriptions peaked and began contracting.
Digital Content Market Segmentation
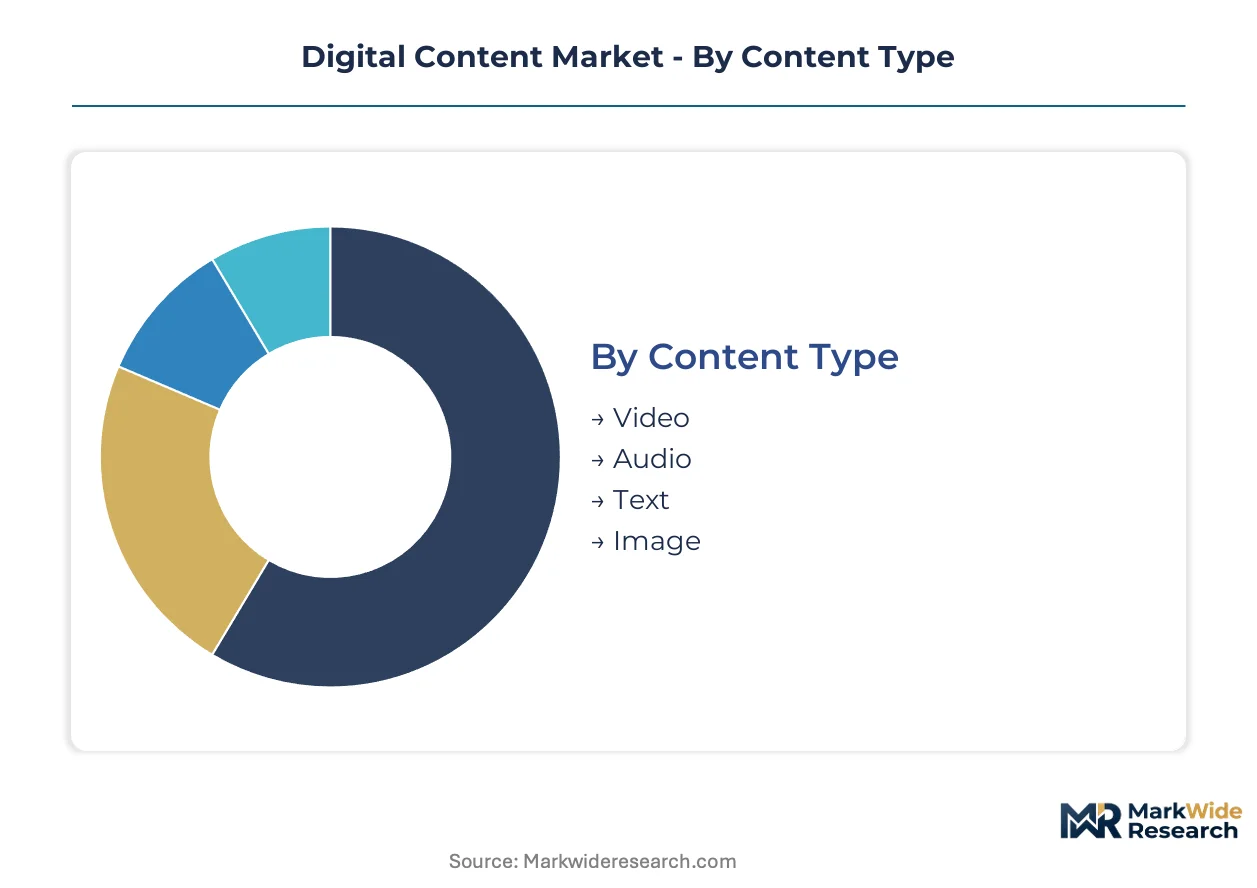
Content type cycles determine inventory velocity and infrastructure investment intensity. Distribution channel selection shapes margin profiles and compliance exposure. Monetization models and end-user categories further stratify platform economics and technology requirements.
Content Type:
Video assets rotate through production pipelines most slowly due to rendering complexity, while text and image formats iterate in hours. Audio occupies a middle tier with moderate production overhead and persistent format innovation.
- Video:Encoded media files ranging from short-form vertical clips to cinematic 8K productions with adaptive bitrate delivery protocols. Streaming platforms in India and the United States concentrate demand as regional-language catalogues expand and bandwidth infrastructure deepens. GPU cluster availability constrains real-time rendering scalability.
- Text:Generative AI-assisted written content spanning articles, scripts, and interactive narratives with automated localization pipelines. Enterprise learning platforms in North America and marketing automation systems drive procurement velocity. Prompt engineering talent scarcity limits brand-consistent output quality.
- Audio:Podcast episodes, music streams, and voice-synthesized content distributed through dedicated platforms and embedded players. Subscription audio services in Brazil and Indonesia show concentrated uptake. Licensing fragmentation across performance rights organizations creates royalty complexity.
- Image:Static visual assets including photography, illustrations, and AI-generated artwork deployed across advertising and editorial workflows. E-commerce product imagery and social media advertising in Southeast Asia anchor volume. Metadata standardization gaps impede automated rights verification.
Video anchors the volume base while text gains share at the steepest rate.
Distribution Channel:
Social media and mobile apps command the lowest customer acquisition costs but impose the steepest content moderation burdens. Streaming platforms and owned websites retain pricing autonomy at higher infrastructure investment thresholds.
- Social Media:Algorithmically curated feeds on platforms with billions of daily active users and embedded native advertising auctions. Short-form video consumption in Brazil and Southeast Asia concentrates engagement hours. EU Digital Services Act transparency mandates force architectural upgrades for European user bases.
- Streaming Platforms:Subscription-gated libraries with personalized recommendation engines and original content production arms. North American enterprise learning modules and India's regional-language entertainment catalogues drive content commissioning. Bandwidth costs and content licensing renewals compress operating margins.
- Websites:Publisher-controlled destinations with direct audience relationships and flexible monetization stack integration. B2B software documentation and educational courseware in Germany and Japan sustain traffic stability. Search engine algorithm changes create organic discovery volatility.
- Mobile Apps:Native distribution through Apple App Store and Google Play with in-app purchase rails and push notification re-engagement. Casual gaming content and creator tools in Indonesia and Nigeria show installation momentum. Platform fee structures and store policy enforcement limit revenue retention.
Social media commands absolute volume while mobile apps climb the fastest.
Monetization Model:
Subscription structures lock in predictable recurring revenue at higher upfront conversion friction. Advertising and freemium models scale user bases rapidly while trading data dependency for price accessibility.
- Subscription:Recurring fee structures with tiered access levels and annual commitment discounts. Premium streaming services and professional creative tool suites in the United States and United Kingdom retain customer lifetime value. Churn management and content refresh costs consume operational focus.
- Advertising:Impression and engagement-based revenue with programmatic auction mechanics and audience targeting capabilities. Social media feeds and connected television inventory in India and Brazil attract brand budgets. Privacy regulation fragmentation across GDPR, state-level US statutes, and India's proposed frameworks complicates targeting precision.
- Pay-Per-View:Transactional access for live events and premium releases with time-limited viewing windows. Sports broadcasting and theatrical window releases in Saudi Arabia and Mexico sustain per-unit pricing power. Piracy and windowing strategy leaks erode capture rates.
- Freemium:Zero-cost entry tiers with feature-gated upgrades and usage-triggered conversion prompts. Mobile creative tools and educational content libraries in South Korea and Turkey expand addressable markets. Conversion rate optimization and feature prioritization strain product management bandwidth.
Advertising underpins the broadest volume base while freemium expands most quickly.
End User:
Individuals and businesses generate the highest transaction frequency with diverging customization requirements. Educational institutions and non-profits operate on extended procurement cycles with specialized accessibility mandates.
- Individuals:Consumer-grade content consumption and amateur creation with personal budget constraints and platform switching flexibility. Entertainment streaming and social media participation in Indonesia and Nigeria scale user counts. Subscription fatigue in North American households fragments spending across niche services.
- Businesses:Enterprise content production, internal training deployment, and external marketing communication with procurement security requirements. Corporate learning management systems and brand asset libraries in Germany and Japan demand integration capabilities. Compliance documentation and vendor security assessments extend sales cycles.
- Educational Institutions:Curriculum-aligned content licensing and student-facing platform deployments with accessibility and data protection obligations. K-12 digital textbook platforms and university streaming services in Australia and Canada require pedagogical alignment. Budget approval hierarchies and academic calendar constraints season demand.
- Non-Profits:Mission-driven content creation and donor communication with restricted funding sources and volunteer-dependent production. Advocacy video and fundraising campaign materials in Kenya and Bangladesh operate under cost discipline. Grant reporting requirements and board governance reviews slow technology adoption.
Individuals anchor the volume base while businesses gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rendering hardware fabrication concentrates in Taiwan and South Korea, creating supply vulnerability that shapes regional deployment strategies. Cloud infrastructure investment patterns diverge sharply between mature markets building compliance layers and emerging economies prioritizing latency reduction.
United States
Enterprise learning platforms and streaming services drive demand for interactive video modules and AI-assisted content pipelines. The FCC maintains layered oversight alongside emerging state-level privacy statutes that fragment operational standards. California's film studios and game developers adopt neural radiance field pipelines for virtual production stages, collapsing location shooting requirements.
India
Regional-language streaming catalogues and mobile-first creative tools anchor concentrated demand from individual creators and entertainment platforms. The BIS guidelines and proposed digital content regulation framework signal tighter oversight of streaming catalogues and intermediary liability. Mumbai, Hyderabad, and Chennai host expanding data center capacity and localized cloud regions reducing latency for content delivery.
Germany
B2B software documentation and educational courseware sustain stable traffic for publisher-controlled websites with flexible monetization integration. The GDPR algorithmic accountability provisions mandate explainability layers for content recommendation systems serving European users. Berlin-Brandenburg clusters engineering investment into interpretable ranking models that document decision pathways.
Brazil
Portuguese-language short-form content platforms and mobile creator tools show whitespace for localized creative tool adoption. ANVISA and national data protection frameworks shape platform compliance architecture for regional operations. São Paulo anchors advertising-supported social media engagement hours with algorithmically curated feeds capturing brand budgets.
Japan
Corporate learning management systems and brand asset libraries demand integration capabilities with extended procurement security requirements. METI standards and JIS frameworks influence technology adoption timelines for enterprise content production. Tokyo-Kanto clusters host precision-engineered workflow automation for image and video production pipelines.
Digital Content Market Competitive Landscape
Cloud-scale platforms and creative software specialists split the market between advertising-supported distribution and professional-grade production tooling. The vendor base organizes around three strategic archetypes: infrastructure providers supplying rendering hardware, platform operators monetizing user attention, and workflow software vendors capturing enterprise procurement. Consolidation pressure intensifies as generative AI capabilities force portfolio diversification and strategic partnerships bridging generation and distribution layers.
Within the creative software tier, Adobe and Autodesk exemplify professional-grade workflow dominance, while NVIDIA occupies a position anchoring infrastructure supply for real-time rendering and AI synthesis pipelines. These three entities represent distinct competitive vectors: subscription-based creative suites, specialized production tools, and hardware-dependent cloud services.
| Leading Market Players |
|---|
| Adobe |
| Microsoft |
| Apple |
| Autodesk |
| Canva |
| Aptara |
| NVIDIA |
| Vimeo |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber routes connecting Los Angeles to Singapore and Tokyo carry the bulk of raw video footage and rendered assets, with bandwidth pricing volatility directly compressing margins for streaming platforms while amplifying cost advantages for cloud providers with owned infrastructure. This logistics corridor's cost structure reinforces pricing power concentration among hyperscalers and fragments competitive positioning for regional distributors.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure for platforms serving European users, forcing compliance investment that stratifies offerings across premium ad-free, standard ad-supported, and economy limited-access tiers. Price differentiation hinges on content resolution tiers and GDPR certification levels for data handling. Cost compression in the economy tier is intensifying because energy input volatility raises data center operating expenses. Individual consumers in emerging markets exhibit the highest price sensitivity, while enterprise procurement teams in Germany and Japan demonstrate the lowest.
Supply Chain Analysis
TSMC and Samsung Foundry hold the dominant share of advanced GPU and AI accelerator fabrication capacity, with concentrated assembly at Foxconn and Pegatron facilities. Taiwan and South Korea anchor semiconductor supply, while China and Vietnam host downstream device assembly for tablets and smartphones. The supply chain draws from rare earth elements for magnet components, high-bandwidth memory stacks, and specialized optical substrates. Single-source vulnerability in EUV lithography equipment creates systemic risk. Distribution runs through hyperscaler cloud regions and OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as generative AI tooling refreshes enterprise content production budgets and triggers replacement cycles for legacy creative suites.
For Market Incumbents: Insulate subscription revenue by embedding generative AI features that increase switching costs for Adobe and Autodesk users. Acquire compliance automation vendors to address EU Digital Services Act documentation requirements. Build captive rendering capacity in India to reduce hyperscaler dependency and defend margin position against cloud-native challengers. For New Entrants and Emerging Players: Brazil's underpenetrated mobile creator economy offers whitespace for Portuguese-language creative tools with lightweight storage footprints. Target Indonesia's short-form video producers with AI-assisted editing apps that operate on mid-tier smartphones. Pursue freemium distribution through TikTok and Instagram native integrations to bypass app store fee structures. For Investors and Strategic Acquirers: Specialized NeRF and virtual production workflow vendors with studio relationships in California represent attractive acquisition targets as film production pipelines consolidate. Monitor GPU cluster availability pricing as an inflection indicator for infrastructure provider margin expansion. Long-term viability favors vendors controlling both generation software and distribution rails.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Platform Launch | EU Digital Services Act mandates force architectural upgrades for transparency tooling across European user bases. |
| Regional Cloud Region Expansion | Localized infrastructure in Mumbai and São Paulo reduces latency for regional-language streaming pipelines. |
| AI-Human Workflow Service Layer | Text-to-video and image-to-3D intermediation opens new revenue pools between raw generation and final production. |
| NeRF Virtual Production Partnership | California film studios adopting neural radiance fields reduce location shooting costs and vendor dependencies. |
| Enterprise Learning Integration Suite | North American corporate LMS procurement demands seamless embedding of interactive video modules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory filings. The research program incorporated structured interviews with CTOs at streaming platforms, content operations directors at enterprise learning vendors, platform engineers at social media companies, and procurement leads at film production studios. Bottom-up segment sizing triangulates against top-down market boundary analysis from trade flow and bandwidth consumption metrics.
Forecast inputs include generative AI adoption curves, data center buildout timelines, and regulatory implementation schedules across the analysis window. The modeling framework segments by content type, distribution channel, monetization model, and end-user category, with additional dimensioning for regional cloud region maturity. CAGRs derive from fitted growth curves applied to observed 2024-2025 infrastructure investment patterns and content commissioning volumes.
Practitioners should monitor GPU foundry utilization rates, EU content moderation enforcement actions, and India data center permitting velocity for early signals of forecast revision. Quarterly review of streaming subscriber churn rates and enterprise creative software renewal pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
United States Sports Betting Market
Digital Media
Da Vinci Systems Market
Digital Media
Digital Content Creation Market
Digital Media
Global Music Video Production Market
Digital Media
Sports Graphics Market
Digital Media
Digital Effects Services Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Video Wall Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Animation and VFX Market
Digital Media
Digital Video Content Market
Digital Media
Wedding Photography Market
Digital Media
Global Animation Market
Digital Media
Multichannel Network Market