
 Digital Music Services Market | 2026-2036
Digital Music Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Music Services Market Insights
AI-powered audio compression and adaptive bitrate streaming is reconfiguring how digital music services deliver high-fidelity experiences over variable network conditions. Spotify Technology S.A. leverages its proprietary recommendation engine to sustain listener engagement across diverse geographic markets. Apple Music anchors its competitive stance through lossless and spatial audio differentiation. Tencent Music Entertainment Group dominates social entertainment integrations that blend streaming with live interactive features.
Digital music services encompass cloud-based audio content platforms that encode, distribute, and monetize recorded music through streaming protocols, digital rights management systems, and personalized discovery algorithms. These platforms operate on bitrates ranging from 96 kbps for efficient mobile delivery to 24-bit/192 kHz hi-resolution tiers, serving the commercial purpose of replacing physical media ownership with on-demand access to expansive licensed catalogs. Streaming subscriptions command the largest revenue pool within the service type dimension, while ad-supported tiers capture emerging market volume where payment infrastructure remains fragmented. The freemium payment model functions as the dominant user acquisition funnel, converting free listeners through graduated feature unlocking rather than immediate paywall enforcement.
FCC net neutrality rulings in the United States shape how carriers prioritize music streaming traffic, while GDPR and the EU AI Act impose algorithmic transparency and data processing constraints on European platform operations. Brazil's ANCINE content quotas and local artist promotion mandates influence catalog composition and licensing negotiations for services operating in that market. Stakeholders must monitor evolving royalty rate determinations by copyright tribunals and performance rights organizations across multiple jurisdictions, as these administrative decisions directly alter platform cost structures and artist payout frameworks without legislative action.
Market Dynamics
AI-powered recommendation engines are restructuring how digital music platforms acquire and retain subscribers, forcing incumbents to rebuild their discovery architectures around machine learning inference rather than human curation.
Growth Catalysts
- Automotive Infotainment Integration:OEMs in Germany, Japan, and the United States are embedding native streaming applications into dashboard systems, converting drive-time radio listeners into paid subscribers through seamless Bluetooth and 5G connectivity.
- Brazil's ANCINE Localization Mandates:Content quotas requiring domestic artist promotion are accelerating platform investment in Portuguese-language catalog expansion and regional licensing negotiations.
- Adaptive Bitrate Streaming:This compression technology enables high-fidelity audio delivery over variable network conditions, expanding addressable markets beyond urban fiber corridors into tier-two cities with inconsistent infrastructure.
Market Restraints
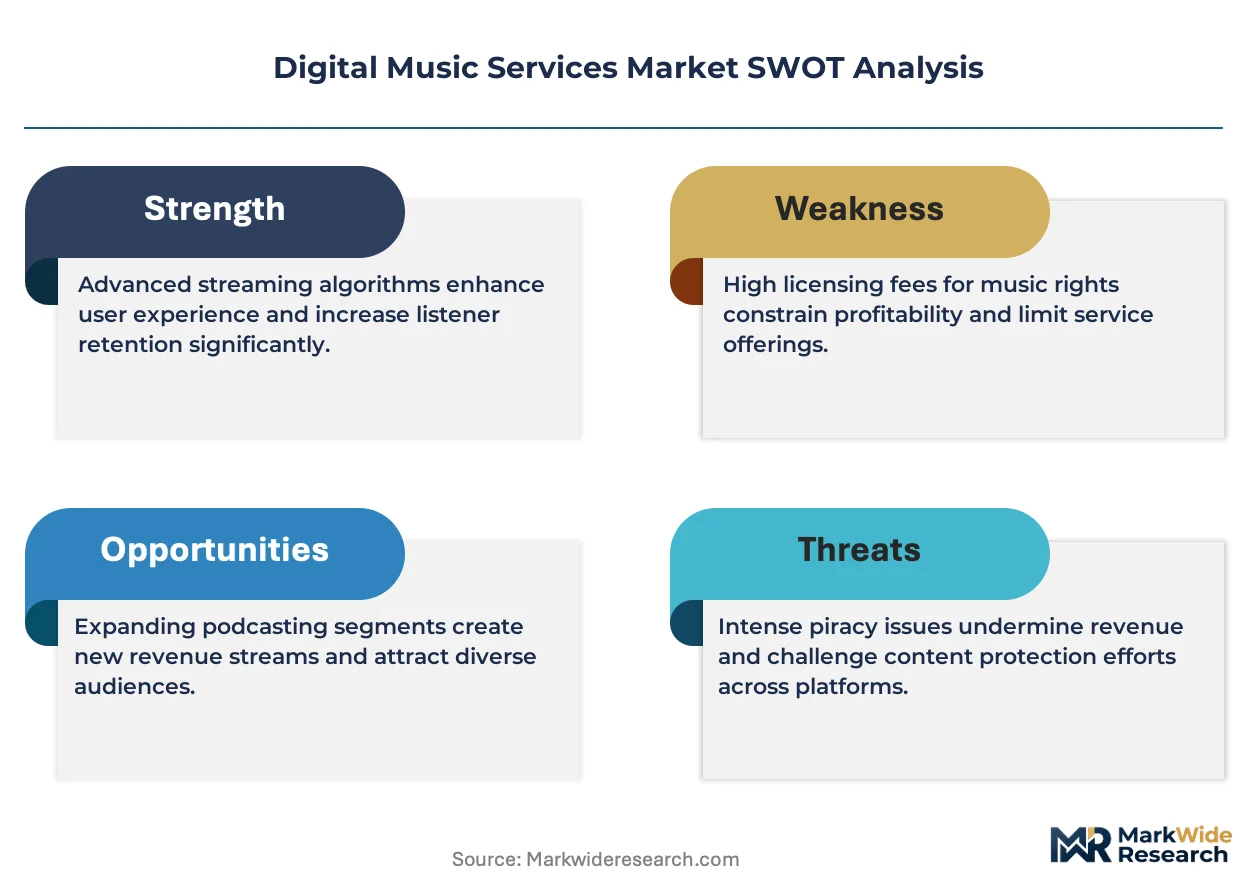
- Copyright Tribunal Royalty Volatility:Administrative rate determinations by performance rights organizations in the United States and European Union directly alter platform cost structures without legislative predictability.
- Payment Infrastructure Fragmentation:Emerging market subscriber conversion remains constrained by underdeveloped credit card penetration and mobile wallet interoperability across Sub-Saharan Africa and Southeast Asia.
- Lossless Audio Storage Costs:24-bit/192 kHz tier delivery requires 3-5x server capacity versus standard compressed streams, compressing gross margins for services competing on audiophile differentiation.
Strategic Opportunities
- Social Entertainment Convergence:Live interactive features blending streaming with virtual gifting and artist-fan chat rooms represent unmonetized white space beyond passive consumption models.
- EU AI Act Algorithmic Transparency:Compliance investments in explainable recommendation systems create competitive moats against smaller platforms lacking technical resources for audit-ready architectures.
- India's Mobile-First Listener Base:Jio and Airtel's sub-$2 data plans have compressed smartphone penetration timelines, opening subscription growth corridors in tier-three cities previously unreachable via desktop-centric acquisition funnels.
Industry Challenges
- ML Engineer Talent Scarcity:Recommendation system optimization requires scarce expertise in large-scale collaborative filtering and natural language processing for lyrics analysis, driving compensation inflation in Silicon Valley and Shenzhen hiring markets.
- Legacy DRM Integration Complexity:Platforms maintaining backward compatibility with early-2010s download-to-own libraries face technical debt in unified playback architectures across streaming and purchased content silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Music Services Market |
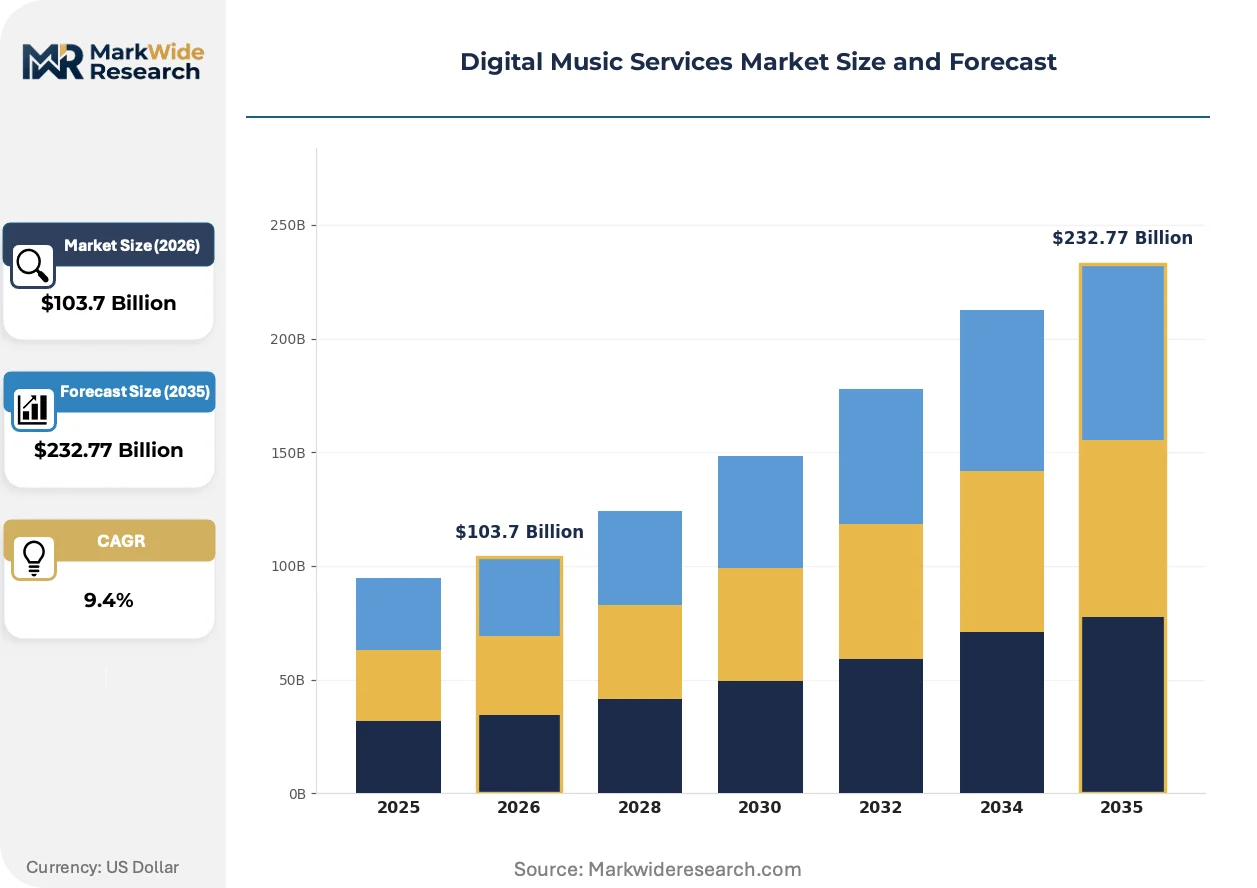
| Market Size in 2026 | $103.7 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Streaming, Download, Podcasting, Live Concerts Payment Model: Subscription, Pay-Per-Download, Ad-Supported, Freemium User Type: Individual, Family, Student, Professional Content Type: Albums, Singles, Playlists, Radio Stations |
| Companies Covered | Spotify Technology S.A., Apple Music, Amazon Music, YouTube Music, Tencent Music Entertainment Group, NetEase Cloud Music, Deezer, Tidal, iHeartMedia Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Music Services Market Trends and Innovations
Generative audio synthesis and spatial audio rendering are collapsing production timelines while raising new questions about copyright ownership and listener authentication across synthetic and recorded content boundaries.
Spatial audio encoding technology is hybridizing stereo production pipelines with object-based mixing workflows. Automotive OEMs and headphone manufacturers are adopting Dolby Atmos and Sony 360 Reality Audio formats at accelerated cadences. This convergence is compressing the premium tier definition from bitrate specifications toward immersive rendering capabilities.
The EU AI Act's content moderation provisions are imposing algorithmic transparency obligations on European platform operations. Services must document training data provenance and recommendation logic for regulatory audit. French and German regulators are already demanding impact assessments for generative audio features before public deployment.
Listener procurement of music access is fragmenting across bundled telecommunications offers rather than direct platform relationships. JioSaavn in India and Tencent Music's carrier partnerships in China illustrate this displacement of standalone subscriptions. Brazil's Vivo and Claro are replicating this model, embedding streaming into mobile data plans as a retention tool rather than revenue center.
Digital Music Services Market Segmentation
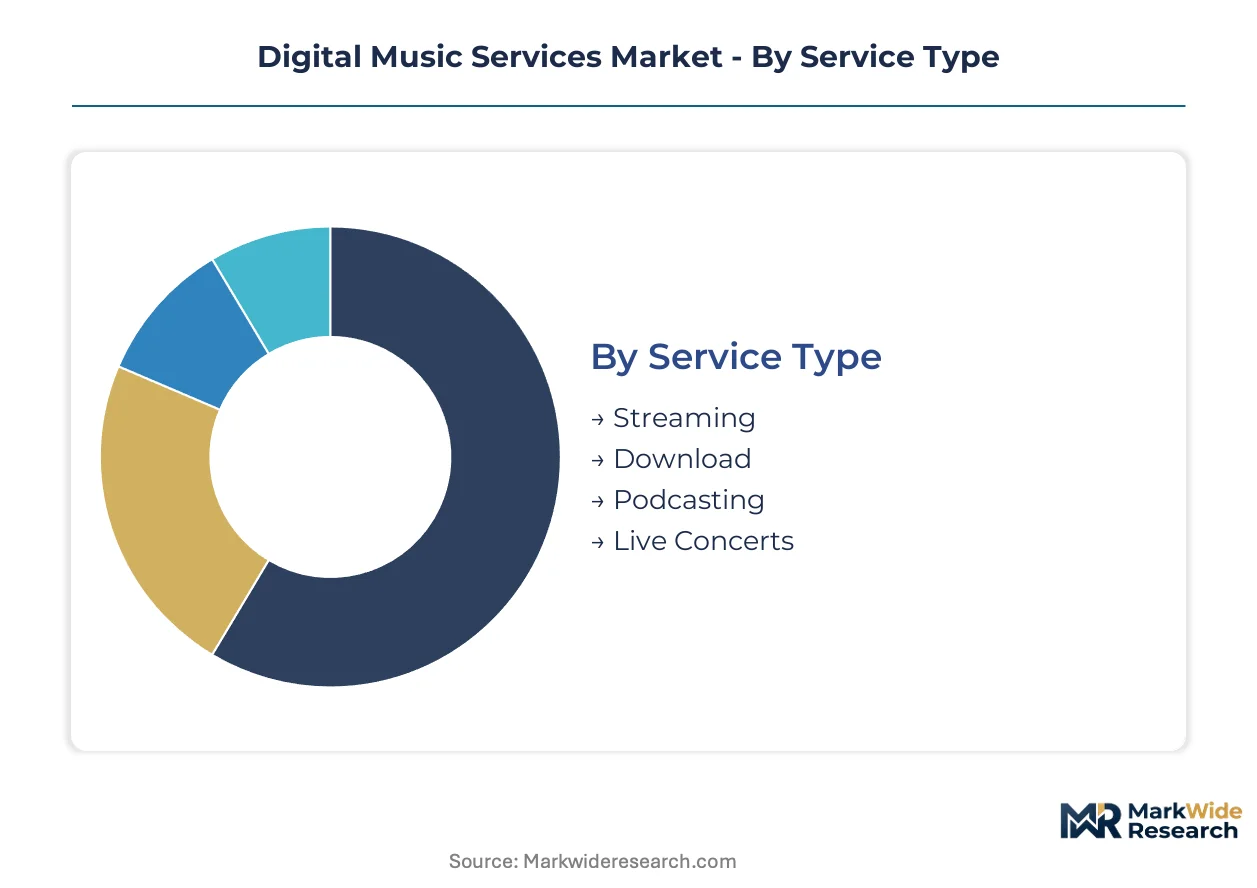
Segmentation in digital music services determines platform monetization architecture and infrastructure investment priorities. Service type and payment model configurations directly shape server capacity planning, licensing cost structures, and customer lifetime value calculations across geographic markets.
Service Type:
After-sales-service intensity varies dramatically across service types, with live concerts demanding real-time technical support while downloads require minimal ongoing intervention.
- Streaming:Cloud-based audio delivery via adaptive bitrate protocols serves 96 kbps mobile tiers through 24-bit/192 kHz hi-resolution streams. Demand concentrates in Brazil and India where mobile-first listener bases and sub-$2 data plans from Jio and Airtel compress smartphone penetration timelines. FCC net neutrality rulings shape carrier traffic prioritization for this segment in the United States.
- Live Concerts:Real-time virtual performance streaming with interactive chat and virtual gifting features. Social entertainment convergence drives investment from Tencent Music Entertainment Group in China, blending passive consumption with artist-fan engagement tools. EU AI Act algorithmic transparency requirements impose audit-ready architecture costs on European deployments.
- Download:DRM-protected file ownership with offline playback rights. Legacy integration complexity burdens platforms maintaining early-2010s purchase libraries alongside streaming architectures.
- Podcasting:Spoken-word content distribution through RSS feeds and proprietary hosting platforms. Advertiser demand for host-read sponsorships reshapes content acquisition strategies.
By volume, Streaming leads. By growth pace, Live Concerts is ahead.
Payment Model:
Cost tier differentiation separates enterprise-grade subscription stacks from lightweight ad-supported implementations.
- Subscription:Recurring monthly or annual fees unlocking full catalog access and offline playback. Family plan multipliers and student discounts expand addressable demographics. Payment infrastructure fragmentation in Sub-Saharan Africa and Southeast Asia constrains conversion rates despite smartphone penetration gains.
- Freemium:Tiered feature unlocking that graduates free listeners through graduated capability expansion rather than immediate paywall enforcement. Spotify Technology S.A. pioneered this funnel architecture. Brazil's Vivo and Claro carrier partnerships embed freemium tiers as mobile data plan retention tools.
- Ad-Supported:Zero-cost access funded by programmatic audio advertising and host-read sponsorships. ANCINE content quotas in Brazil mandate domestic artist promotion within ad-funded catalog rotations.
- Pay-Per-Download:Transactional ownership of individual tracks or albums. Declining share as streaming displacement accelerates across developed markets.
Subscription captures the revenue concentration. Freemium expands the user base fastest.
User Type:
Customer type determines pricing elasticity and churn risk profiles across demographic cohorts.
- Individual:Single-account access with personalized recommendation engines. Apple Music anchors competitive positioning through lossless and spatial audio differentiation for this cohort.
- Family:Multi-account bundles with parental controls and shared playlist features. Higher average revenue per account offsets individual plan discounts.
- Student:Verified educational discounts with conversion pathways to full-price individual plans upon graduation. Price sensitivity demands lean operational cost structures.
- Professional:Commercial licensing tiers for venues, retailers, and content creators. BMI and ASCAP performance rights organization rates directly alter platform cost structures for this segment.
Individual accounts dominate active usage. Student plans climb the fastest as education verification partnerships expand.
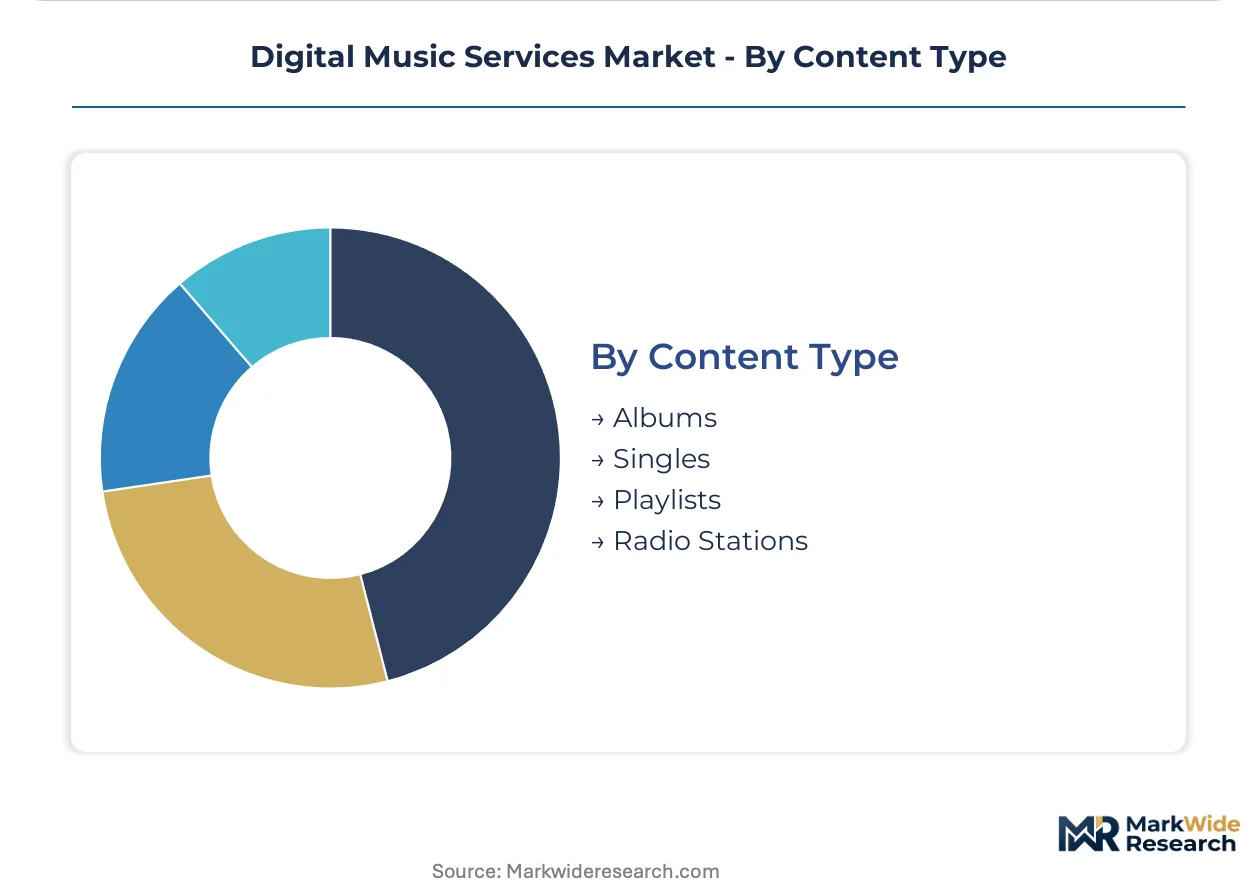
Content Type:
Supply concentration shapes licensing negotiation leverage and catalog investment priorities.
- Singles:Individual track releases optimized for playlist placement and algorithmic discovery. Streaming platform recommendation engines prioritize single-track engagement metrics.
- Playlists:Curated and algorithmic track collections driving session duration and discovery. Editorial curation competes with ML-generated personalized streams.
- Albums:Artist-curated full-length releases with narrative and thematic coherence. Audiophile-tier lossless encoding investments concentrate here.
- Radio Stations:Linear programmed streams mimicking broadcast formats with limited skip functionality. Automotive infotainment integration in Germany, Japan, and the United States converts drive-time listeners through native dashboard applications.
Playlists command engagement hours. Singles gain share fastest as release cadences accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile-first listener bases concentrate in Brazil and India, where sub-dollar data plans compress smartphone penetration timelines. Carrier-bundled subscriptions displace direct platform relationships across these markets. Regulatory mandates in Europe and content quotas in Brazil reshape catalog investment priorities.
United States
FCC net neutrality rulings determine how carriers prioritize streaming traffic across 5G networks. BMI and ASCAP rate proceedings alter platform cost structures through administrative royalty determinations. Detroit's automotive cluster drives native streaming app integration into OEM dashboard systems.
Germany
EU AI Act algorithmic transparency requirements impose audit-ready architecture costs on European platform operations. KBA automotive standards influence infotainment system certification for streaming applications. Berlin's tech cluster hosts compliance engineering teams building explainable recommendation systems.
Brazil
ANCINE content quotas mandate domestic artist promotion within platform catalogs. Vivo and Claro carrier partnerships embed streaming tiers as mobile data plan retention tools. São Paulo's creative industries concentrate Portuguese-language catalog expansion investment.
India
Jio and Airtel sub-dollar data plans compress smartphone penetration timelines in tier-three cities. TRAI net neutrality frameworks shape carrier traffic prioritization for audio streaming. Mumbai's media cluster anchors regional licensing negotiation hubs for South Asian catalog rights.
China
MIIT data localization requirements constrain cross-border content delivery infrastructure. SAMR antitrust scrutiny shapes exclusive licensing negotiations between platforms and major labels. Shenzhen's hardware ecosystem supplies automotive infotainment components for streaming-integrated dashboard systems.
Digital Music Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure. Consolidation pressures concentrate around recommendation engine capabilities and exclusive catalog access. Three archetypes dominate: vertically integrated technology platforms, carrier-bundled regional specialists, and audiophile-tier differentiation players. Competitive moves center on strategic partnerships with automotive OEMs and portfolio diversification into live interactive features.
Within the technology platform tier, Spotify Technology S.A. and Apple Music exemplify divergent approaches to listener retention—algorithmic personalization versus lossless audio differentiation. Tencent Music Entertainment Group anchors the social entertainment convergence archetype, blending streaming with virtual gifting and artist-fan engagement tools. These three entities occupy positions that illustrate how scale, audio fidelity specialization, and interactive feature integration define competitive positioning in this market.
| Leading Market Players |
|---|
| Spotify Technology S.A. |
| Apple Music |
| Amazon Music |
| YouTube Music |
| Tencent Music Entertainment Group |
| NetEase Cloud Music |
| Deezer |
| Tidal |
| iHeartMedia Inc. |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber routes from Los Angeles to Tokyo and Singapore transmit master audio files to regional encoding centers, with bandwidth costs compressing margins for hi-resolution tiers while concentrating pricing power among platforms with captive server infrastructure in Frankfurt, São Paulo, and Mumbai.
Pricing Analysis
Cost-plus licensing contracts with major labels index to subscriber growth metrics and territory-specific ARPU benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates lossless spatial audio subscribers from compressed mobile tiers and ad-supported free listeners. Price differentiation hinges on audio fidelity certification and bundled family account scale. Pricing pressure stems from carrier-bundled subscriptions in Brazil and India that commoditize direct platform relationships. Student and emerging market segments exhibit highest price sensitivity, while audiophile tiers in Germany and Japan show inelastic demand.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for automotive infotainment hardware components. Server infrastructure concentrates in the United States, Ireland, and Singapore, with content delivery networks drawing from localized edge nodes to minimize latency. Raw material dependencies include lithium-ion battery cells for portable devices, rare earth elements for headphone drivers, and silicon for automotive system-on-chip processors. Single-source vulnerability persists in Dolby Atmos encoding hardware. Distribution runs through carrier partnerships in emerging markets and direct-to-consumer app stores in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across listener acquisition channels creates specialization opportunities as carrier bundling, automotive integration, and social entertainment features each demand distinct platform architectures.
For Market Incumbents: Pre-empt regulatory compliance costs by building audit-ready recommendation transparency systems before EU AI Act enforcement expands. Consolidate automotive OEM relationships through exclusive dashboard integration contracts that lock out competing platforms. Address talent scarcity in ML engineering by acquiring specialized natural language processing teams for lyrics analysis capabilities. For New Entrants and Emerging Players: Establish a beachhead in live interactive features blending virtual gifting with artist-fan chat rooms, a segment Tencent Music has validated but Western platforms underinvest. Target tier-three Indian cities where Jio and Airtel data plans have compressed smartphone penetration timelines without saturating subscription demand. Deploy carrier-embedded freemium tiers as the primary go-to-market mechanism rather than direct consumer acquisition. For Investors and Strategic Acquirers: Regional specialists with ANCINE compliance infrastructure and Portuguese-language catalog depth represent attractive acquisition targets as Brazil's content quotas harden. Long-term viability favors platforms with diversified revenue beyond subscription—advertising, live events, and social entertainment integrations. Monitor copyright tribunal rate determinations in the United States and European Union as inflection indicators for platform cost structure compression.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive OEM Partnership | Native dashboard integration converts drive-time radio listeners through seamless 5G connectivity. |
| Spatial Audio Certification | Dolby Atmos and Sony 360 Reality Audio licensing differentiates premium tiers from compressed mobile streams. |
| Carrier Bundling Expansion | Vivo and Claro partnerships in Brazil embed streaming as mobile data plan retention tools. |
| EU AI Act Compliance Investment | Explainable recommendation architectures create technical moats against audit-resource-constrained competitors. |
| Live Interactive Feature Development | Virtual gifting and artist-fan chat rooms unlock social entertainment revenue beyond passive consumption. |
Research Methodology
The analysis maps streaming subscriptions, live virtual concerts, podcast distribution, and download-to-own segments, each validated through platform licensing directors, automotive infotainment procurement leads, carrier partnership executives, and performance rights organization administrators. Primary interviews with these stakeholders triangulate against secondary sources including FCC net neutrality filings, ANCINE regulatory decrees, EU AI Act implementation guidance, and copyright tribunal rate determinations. Bottom-up subscriber and revenue modeling reconciles with top-down market sizing across geographic clusters.
Assumptions held fixed include prevailing royalty rate structures and carrier bundling penetration ceilings, while variables tested include AI Act enforcement timelines and automotive integration adoption curves. Segmentation dimensions encompass service type, payment model, user archetype, and content format, with regional regulatory frameworks as an industry-specific overlay. CAGRs derive from logistic diffusion modeling of smartphone penetration and data plan affordability curves. Forecast inputs include server capacity cost trajectories and ML engineer compensation inflation indices.
Stress conditions across copyright tribunal rate volatility, carrier partnership renewal negotiations, and automotive OEM exclusivity windows were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that regulatory acceleration or platform consolidation could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Sound Effects Services Market
Digital Media
United States Online Gambling Market
Digital Media
Global Animation Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
India Webtoons Market
Digital Media
Adult Animation Market
Digital Media
China Webtoons Market
Digital Media
Entertainment Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Video Content Management Market
Digital Media
Online Gambling Market
Digital Media
4K Content Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
US Webtoons Market
Digital Media
LED Stadium Screens Market
Digital Media
Digital Video Advertising Market