
 Europe Sperm Separation Devices Market | 2026-2036
Europe Sperm Separation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sperm Separation Devices Market Foresight
German laboratory equipment manufacturers is realigning production priorities toward assisted reproductive technology consumables. Nidacon International AB leverages its Nordic manufacturing base to sustain density gradient media supply across Scandinavian fertility networks. Hamilton Thorne, Ltd. anchors its European position through specialized sperm analysis systems integrated with separation workflows. The Cooper Companies Inc. competes by extending distribution reach into Southern European clinic chains.
Sperm separation devices isolate motile, morphologically normal spermatozoa from seminal plasma through centrifugation, density gradient centrifugation, or microfluidic sorting, typically achieving 90-95% motile sperm recovery rates for clinical insemination procedures. Gradient centrifuges and density gradient media together command the largest revenue share, while microfluidics-based sperm sorters represent the fastest-expanding technology segment due to reduced oxidative stress on gametes. Fertility clinics absorb the majority of end-user demand, though research laboratories are gaining procurement share as translational reproductive biology funding expands across the continent.
EMA oversight of device-derived biological material and the EU Medical Device Regulation's Class IIa classification requirements shape product registration timelines and clinical evidence standards for manufacturers. CE marking under MDR and compliance with ISO 13485 quality management systems determine market access trajectories for non-European suppliers such as Kitazato Corporation and Bonraybio Co., Ltd. Stakeholders must monitor evolving EMA guidance on gamete handling devices and anticipate stricter post-market surveillance obligations as member state competent authorities harmonize enforcement.
Market Dynamics
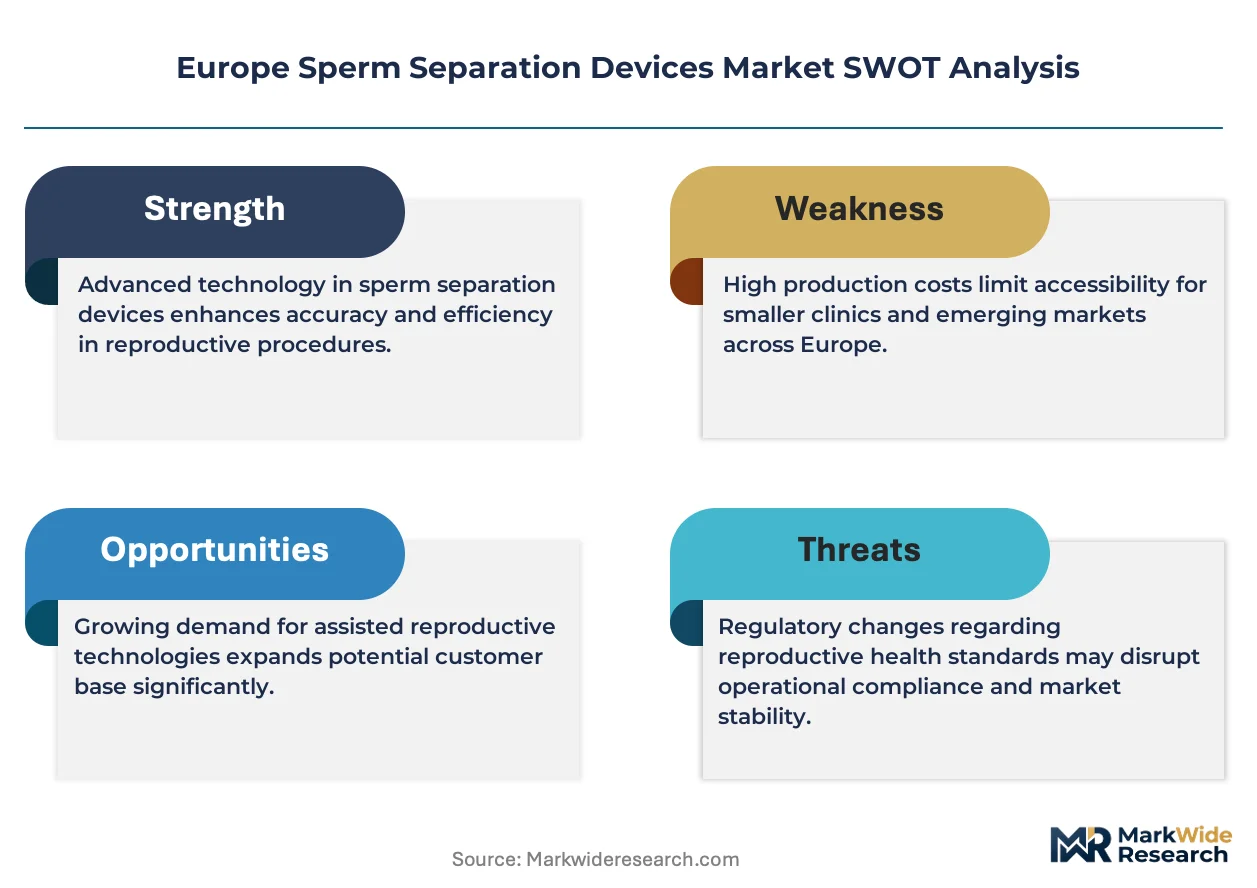
EU Medical Device Regulation reclassification is compressing product registration timelines and forcing manufacturers to rebuild clinical evidence portfolios for existing gradient centrifuge systems. The transition from MDD to MDR certification is creating a bottleneck that favors well-capitalized laboratory equipment suppliers over smaller media specialists.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's 2024-2026 transition window is accelerating replacement cycles for legacy separation equipment as clinics preemptively upgrade to certified systems.
- Germany's Fertility Clinic Consolidation:Laboratory network mergers across Bavaria and North Rhine-Westphalia are standardizing procurement toward high-throughput density gradient platforms.
- Microfluidic Gamete Handling:Chip-based sperm sorting is displacing conventional centrifugation in premium IVF segments due to demonstrably lower oxidative stress markers in recovered spermatozoa.
Market Restraints
- Colloidal Silica Supply Concentration:Density gradient media production concentrates among three Nordic chemical suppliers, exposing downstream device manufacturers to raw material allocation risk.
- EMA Biological Material Oversight:Evolving guidance on device-derived gamete handling is extending regulatory review periods by 8-14 months for novel separation technologies.
- Centrifuge Electromechanical Limits:Conventional gradient centrifugation imposes fixed oxidative stress floors that microfluidic alternatives are now exploiting in head-to-head clinical comparisons.
Strategic Opportunities
- Southern Europe Clinic Chains:Spain and Italy's fragmented fertility sector presents acquisition targets for device distributors seeking to replicate German laboratory network models.
- Research Laboratory Procurement:Translational reproductive biology funding through Horizon Europe is opening parallel demand channels beyond clinical IVF applications.
- ISO 13485 Certification Arbitrage:Non-European manufacturers with existing quality management credentials can accelerate MDR market entry ahead of competitors rebuilding compliance infrastructure.
Industry Challenges
- Embryologist Training Compression:Microfluidic workflow adoption requires reskilling laboratory staff accustomed to manual gradient preparation protocols, lengthening implementation timelines.
- Post-Market Surveillance Scaling:MDR mandates for systematic clinical follow-up data are forcing manufacturers to build member state-specific adverse event reporting infrastructure.
- Legacy Device Servicing Obligations:Extended support requirements for pre-MDR equipment are diverting engineering resources from next-generation platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sperm Separation Devices Market |
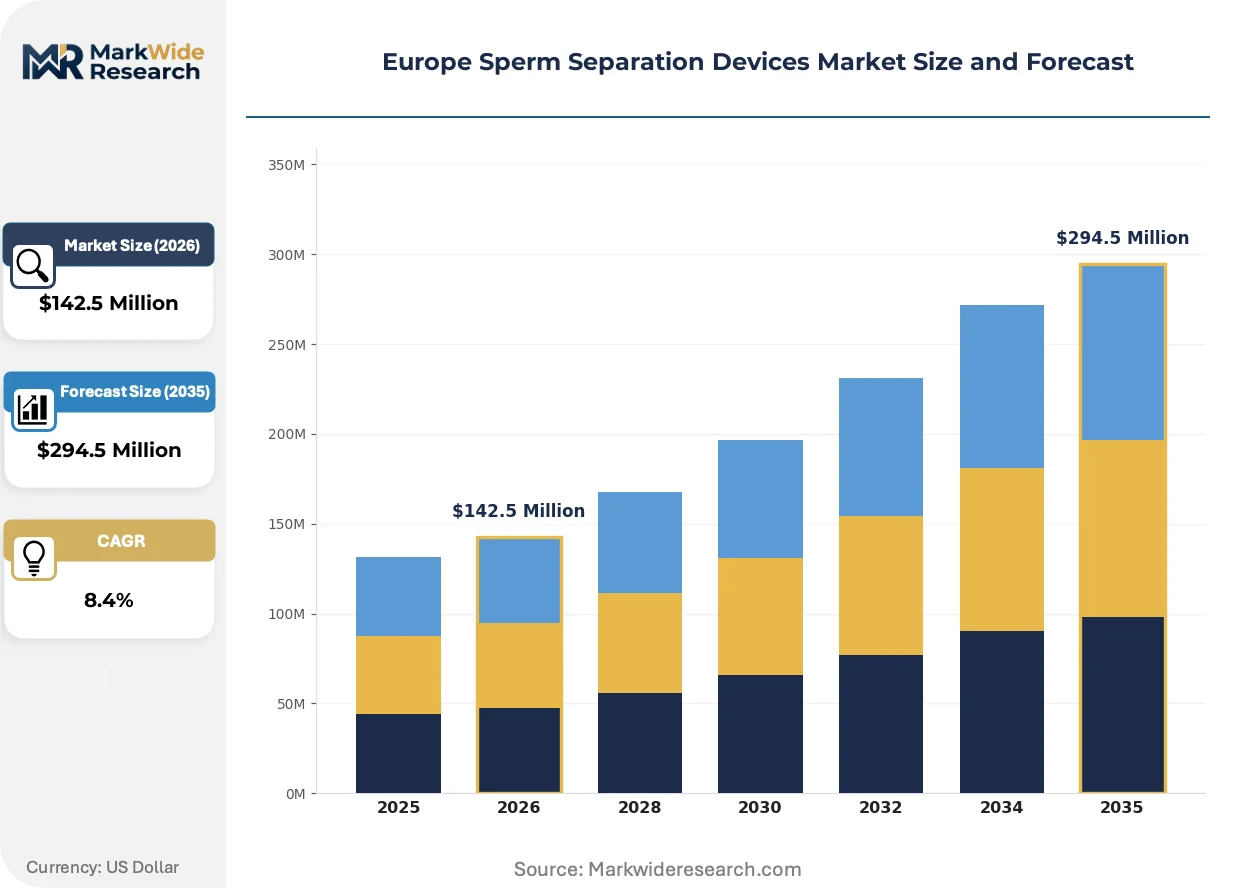
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gradient Centrifuges, Density Gradient Media, Wash Buffers, Sperm Sorters End User: Fertility Clinics, Hospitals, Research Laboratories, Sperm Banks Technology: Centrifugation, Filtration, Magnetic Separation, Microfluidics Application: IVF, ICSI, Sperm Preservation, Genetic Testing |
| Companies Covered | gynotec, Nidacon International AB, DxNow, Promega Corporation, Menicon Co., Ltd., The Cooper Companies Inc., Hamilton Thorne, Ltd., Kitazato Corporation, Bonraybio Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sperm Separation Devices Market Shifts & Advancements
Automation and regulatory stringency are converging to reshape competitive positioning across European fertility laboratory supply chains. Device manufacturers are racing to embed compliance documentation into product architecture rather than treating certification as a post-development hurdle.
Microfluidic sperm sorting is automating gamete isolation workflows that previously required manual pipetting and multi-step centrifugation sequences. Fertility clinics in Denmark and Sweden are adopting these platforms at twice the rate of Southern European counterparts. The technology is automating labor-intensive preparation steps while simultaneously generating audit trails that satisfy MDR clinical evidence requirements.
CE marking under the EU Medical Device Regulation is redefining quality management system scope for all assisted reproductive technology equipment suppliers. Manufacturers must now demonstrate clinical performance across extended follow-up periods rather than relying on bench validation alone. Gradient centrifuge and density gradient media categories face the steepest evidence burden increases, with notified bodies demanding pregnancy outcome data previously reserved for implantable devices.
Clinic procurement committees are consolidating vendor relationships to reduce qualification overhead under stricter supplier audit requirements. Single-source contracts for integrated separation-analysis systems are displacing multi-vendor best-of-breed configurations in Germany's largest laboratory networks. This concentration is most visible in Berlin and Hamburg, where three clinic groups now account for a disproportionate share of annual device procurement volume.
Europe Sperm Separation Devices Market Segmentation
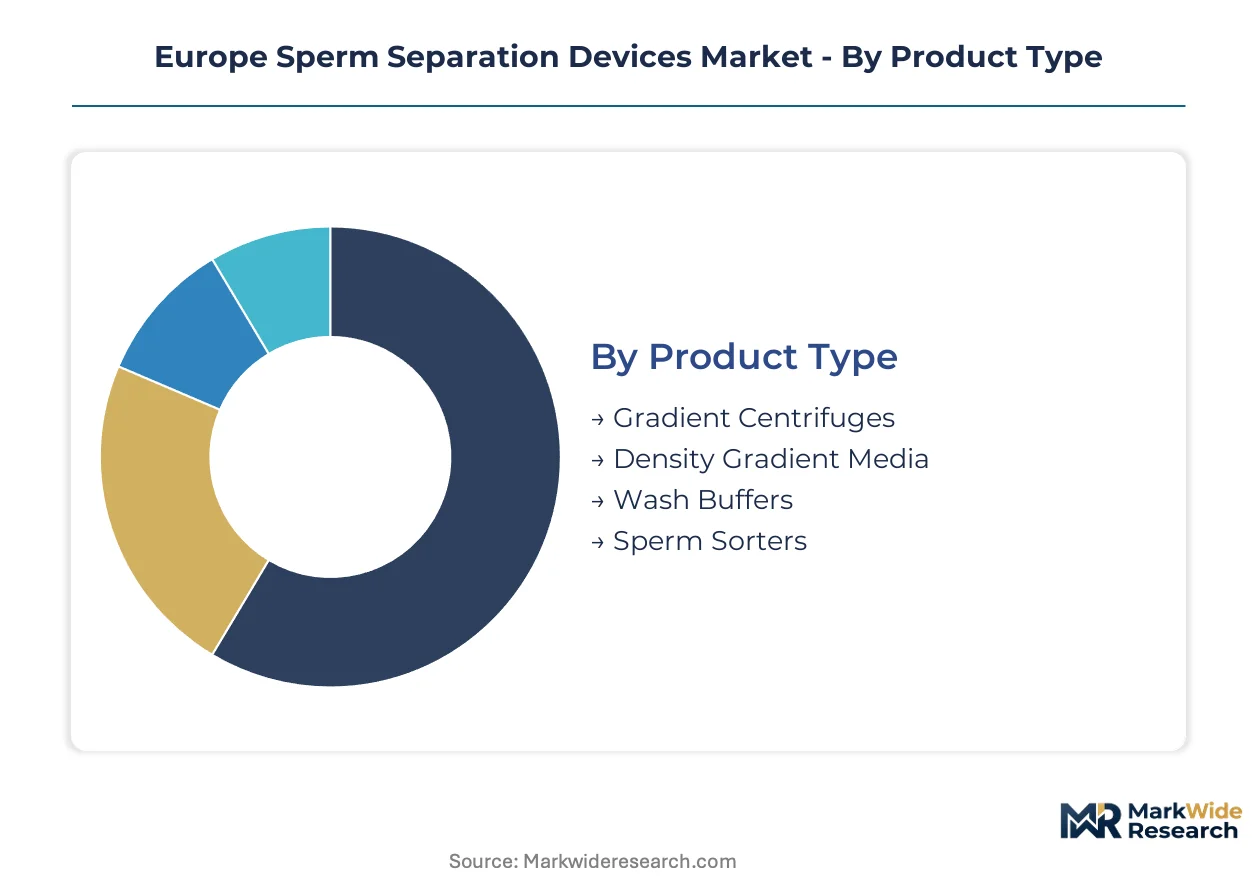
Sperm separation device procurement across Europe fragments along technical specifications, clinical workflow requirements, and regulatory compliance tiers. Manufacturers configure product portfolios to match distinct end-user capabilities and application intensities rather than pursuing universal platform strategies.
Product Type:
Equipment specifications range from capital-intensive centrifuge systems to single-use consumable media, with procurement economics driving divergent vendor relationships across laboratory networks.
- Gradient Centrifuges:Programmable temperature-controlled units process multiple semen samples simultaneously through standardized G-force protocols. German fertility clinic networks in Berlin and Hamburg are consolidating procurement toward high-throughput platforms that integrate with laboratory information management systems.
- Density Gradient Media:Colloidal silica suspensions in varying concentration formulations enable layered separation based on sperm motility and morphology characteristics. Nordic chemical suppliers dominate manufacturing, exposing downstream device makers to raw material allocation constraints during demand surges.
- Wash Buffers:Isotonic solutions remove seminal plasma components and density gradient residues prior to clinical use.
- Sperm Sorters:Automated platforms combining optical detection with mechanical isolation for high-purity sperm selection.
Mature deployment sits with gradient centrifuges and density gradient media combinations. Newer deployment is concentrated in sperm sorters as Spanish and Italian clinics modernize laboratory infrastructure.
End User:
Procurement authority and technical sophistication vary substantially across clinical versus research settings, shaping product positioning and service bundling strategies.
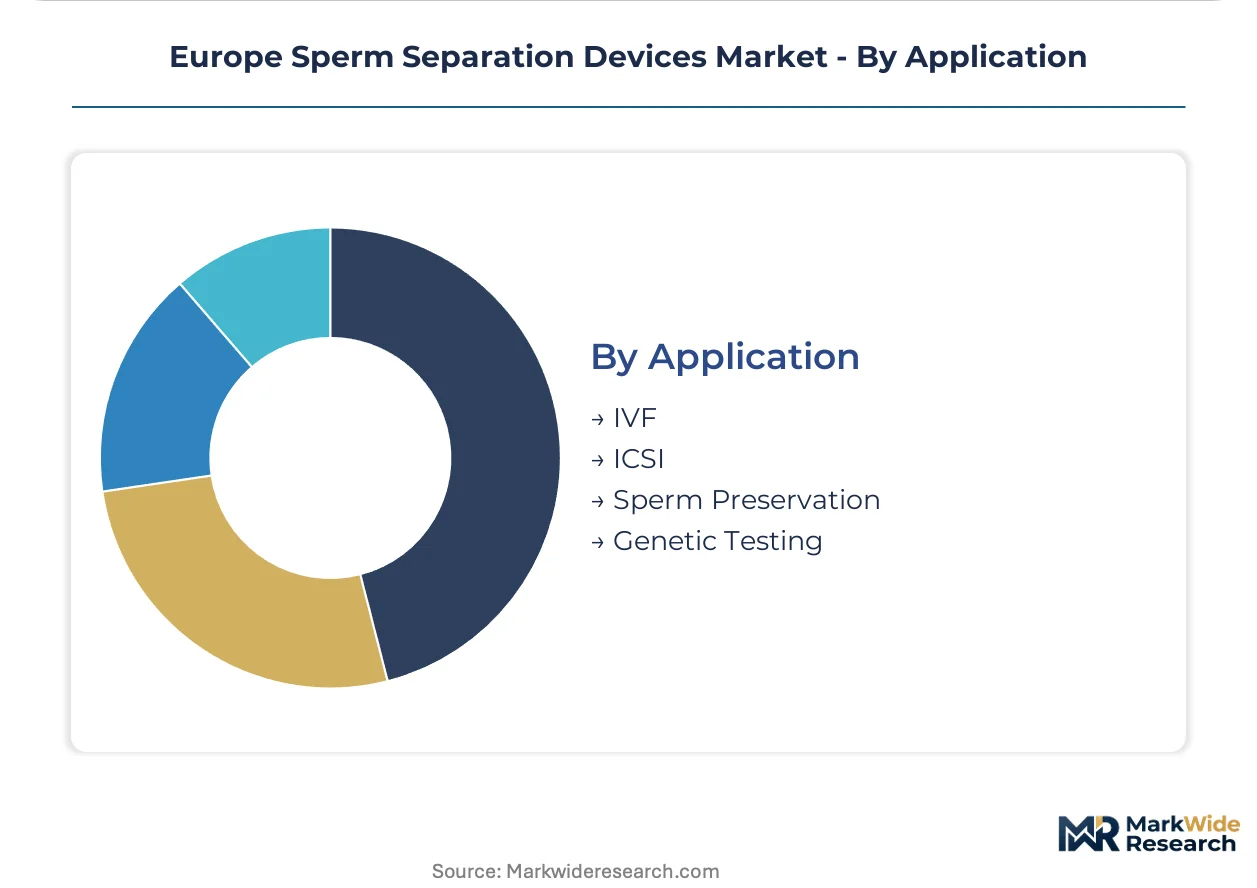
- Fertility Clinics:Specialized reproductive medicine centers perform the majority of clinical sperm preparation procedures for IVF and ICSI cycles. Bavarian and North Rhine-Westphalia laboratory mergers are standardizing equipment specifications across multi-site networks.
- Research Laboratories:Academic and translational biology facilities utilize separation devices for gamete biology studies and protocol development. Horizon Europe funding expansion is accelerating procurement beyond traditional clinical channels.
- Hospitals:General medical centers with reproductive endocrinology departments maintain smaller-scale separation capabilities.
- Sperm Banks:Cryopreservation facilities require high-throughput processing for donor sample qualification and storage preparation.
Volume concentration rests with fertility clinics. Steepest expansion trajectory belongs to research laboratories as reproductive biology funding diversifies across the continent.
Technology:
Underlying separation mechanisms impose distinct oxidative stress profiles, recovery rates, and automation potential that determine clinical adoption patterns.
- Centrifugation:Differential and density gradient centrifugation remain the dominant mechanical separation approach across European fertility laboratories. Fixed oxidative stress floors from high-G processing are driving substitution interest in premium clinic segments.
- Microfluidics:Chip-based laminar flow sorting exploits sperm motility for passive isolation without centrifugal force application. Danish and Swedish fertility networks are adopting these platforms at twice the rate of Southern European counterparts due to earlier regulatory familiarity.
- Filtration:Membrane-based size exclusion methods provide rapid processing for specific clinical scenarios.
- Magnetic Separation:Immunomagnetic bead systems target surface marker selection for specialized applications.
Established clinical workflows depend on centrifugation. Emerging adoption clusters around microfluidics where oxidative stress reduction justifies platform conversion costs.
Application:
Procedure-specific requirements for sperm quantity, purity, and functional integrity determine device configuration and consumable selection.
- IVF:Standard in-vitro fertilization requires motile sperm preparation for co-incubation with retrieved oocytes. German clinic networks prioritize high-throughput gradient systems that minimize technician handling time during peak stimulation cycles.
- ICSI:Intracytoplasmic sperm injection demands morphologically normal sperm selection for individual oocyte injection. Microfluidic platforms are gaining traction in ICSI-dominant practices where sperm quality thresholds are most stringent.
- Sperm Preservation:Cryopreservation preparation requires removal of seminal plasma components that compromise post-thaw viability.
- Genetic Testing:Preimplantation genetic testing workflows impose purity requirements that influence separation protocol selection.
Procedure volume concentrates in IVF and ICSI applications. Fastest share gains are occurring in genetic testing as preimplantation screening expands across European regulatory jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colloidal silica feedstock from Nordic chemical suppliers anchors European density gradient media production, with downstream device manufacturing clustering around Germany's fertility laboratory networks and Scandinavian distribution hubs.
Germany
Fertility clinic consolidation across Bavaria and North Rhine-Westphalia is standardizing procurement toward high-throughput gradient centrifuge platforms. The EU Medical Device Regulation's Class IIa classification compresses registration timelines for new equipment installations. Berlin and Hamburg host three dominant laboratory networks that now account for disproportionate annual device procurement volume.
United Kingdom
London fertility centers are expanding IVF capacity following updated National Institute for Health and Care Excellence guidelines on assisted conception access. The Medicines and Healthcare products Regulatory Agency aligns with MDR transitional provisions for legacy equipment recertification. Cambridge and Oxford research corridors are attracting Horizon Europe translational reproductive biology funding that accelerates research laboratory procurement.
France
Parisian clinic chains are modernizing sperm preparation workflows ahead of ANSM enforcement harmonization with EU-wide post-market surveillance mandates. The country's national pharmaceutical regulator is extending clinical evidence requirements for novel separation technologies. Lyon and Marseille fertility networks are piloting microfluidic platforms in ICSI-dominant practices.
Sweden
Stockholm and Gothenburg fertility laboratories are adopting microfluidic sperm sorting at twice the Southern European rate due to earlier regulatory familiarity with chip-based medical devices. The Swedish Medical Products Agency has streamlined CE marking pathways for low-oxidative-stress gamete handling systems. Uppsala's academic medical centers are integrating separation devices with preimplantation genetic testing workflows.
Spain
Barcelona and Madrid fertility clinics are expanding laboratory infrastructure to capture cross-border reproductive tourism demand from Northern European patients. The Spanish Agency for Medicines and Health Products maintains MDR compliance deadlines that accelerate replacement cycles for legacy centrifugation equipment. Andalusian clinic chains present acquisition targets for distributors seeking to replicate German network consolidation models.
Europe Sperm Separation Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities, with laboratory equipment conglomerates facing specialized Nordic media suppliers and emerging microfluidic technology developers. Market structure tilts toward consolidation as MDR certification costs favor well-capitalized incumbents over smaller consumables specialists. Three archetypes dominate: integrated laboratory platform vendors, density gradient media pure-plays, and microfluidic workflow innovators. Competitive moves center on M&A-driven laboratory network penetration and ISO 13485 certification arbitrage for accelerated market entry.
Among Nordic manufacturing specialists, Nidacon International AB exemplifies the regional media supplier archetype with Scandinavian distribution density. Hamilton Thorne, Ltd. represents the integrated platform vendor tier, while The Cooper Companies Inc. anchors the multinational laboratory equipment conglomerate segment. Kitazato Corporation and Bonraybio Co., Ltd. occupy positions as non-European manufacturers leveraging existing quality management credentials to navigate MDR transition bottlenecks.
| Leading Market Players |
|---|
| gynotec |
| Nidacon International AB |
| DxNow |
| Promega Corporation |
| Menicon Co., Ltd. |
| The Cooper Companies Inc. |
| Hamilton Thorne, Ltd. |
| Kitazato Corporation |
| Bonraybio Co., Ltd. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up laboratory equipment specialists have consolidated procurement leverage across German fertility networks, compressing vendor margins while enforcing stricter service-bundling requirements for density gradient media and gradient centrifuge platforms. This ownership concentration simultaneously tightens pricing discipline among Nordic chemical suppliers and accelerates volume-based rebate structures for high-throughput clinic chains.
Pricing Analysis
Warranty extensions and preventive maintenance contracts are unbundled from base equipment quotes, shifting total cost of ownership calculations toward multi-year service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects MDR certification tier, automation grade, and geographic delivery complexity. Cost compression in standard-tier gradient centrifuges is intensifying because clinic procurement committees are consolidating vendor relationships to reduce qualification overhead. Research laboratories exhibit the highest price sensitivity due to grant-funded budget constraints, while German laboratory networks with private-equity backing show the lowest sensitivity given standardized enterprise pricing.
Supply Chain Analysis
Direct-to-clinic channels handle high-volume fertility network demand, while specialized distributors serve fragmented Southern European markets. Manufacturing concentration rests in Germany for gradient centrifuge assembly, Sweden and Norway for colloidal silica density gradient media, and Denmark for microfluidic chip fabrication. Raw material dependencies include high-purity colloidal silica, medical-grade polymers for microfluidic substrates, and precision electromechanical components for centrifuge motors. Single-source vulnerability in Nordic chemical feedstock exposes downstream device makers to allocation risk during demand surges. Distribution runs through regional laboratory equipment specialists with ISO 13485 certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as MDR compliance costs force smaller media specialists into distressed sales or partnership structures, favoring well-capitalized platform vendors with existing notified body relationships.
For Market Incumbents: Acquire microfluidic technology portfolios to preempt substitution threats from chip-based sperm sorters displacing conventional centrifugation in premium IVF segments. Deepen backward integration into colloidal silica supply through offtake agreements with Nordic chemical suppliers, insulating production from raw material allocation shocks. Priority investment in MDR clinical evidence generation accelerates recertification timelines for legacy gradient systems. For New Entrants and Emerging Players: The premium-economy price gap in Southern European fertility clinics creates entry opportunity for mid-tier automation platforms with streamlined CE marking pathways. Spain and Italy's fragmented laboratory infrastructure offers the most penetrable geography, with Andalusian clinic chains presenting acquisition targets for distributors replicating German network consolidation. A go-to-market angle emphasizing reduced oxidative stress markers in recovered spermatozoa differentiates against entrenched centrifugation workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified consumables specialists in Scandinavia facing working capital constraints during MDR transition bottlenecks. Long-term viability over the next decade hinges on exposure to microfluidic workflow adoption curves and research laboratory procurement expansion through Horizon Europe funding. The signal to watch is EMA guidance evolution on gamete handling devices, which will determine regulatory review period compression for novel separation technologies.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Investment | CE marking under EU Medical Device Regulation demands pregnancy outcome data previously reserved for implantable devices. |
| Microfluidic Platform Development | Chip-based sperm sorting automates labor-intensive preparation while generating audit trails satisfying MDR requirements. |
| Horizon Europe Research Partnership | Translational reproductive biology funding opens parallel demand channels beyond clinical IVF applications. |
| Nordic Media Supplier Acquisition | Colloidal silica production concentration exposes downstream manufacturers to raw material allocation risk. |
| Southern European Distribution Expansion | Spain and Italy's fragmented fertility sector presents consolidation targets for German network replication. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with laboratory directors, embryologists, biomedical engineers, and procurement managers at fertility clinic networks. EMA guidance documents, EU Medical Device Regulation implementation notices, notified body certification databases, and Horizon Europe funding disclosures provided regulatory and funding trajectory validation. Bottom-up equipment procurement estimates from clinic network expansion announcements were triangulated against top-down market sizing from Nordic chemical supplier production disclosures.
Granularity-level modeling dissected the market by product type, end user, technology, application, and country-level regulatory cluster across the analysis window. CAGRs were derived from segment-specific growth trajectories weighted by procurement volume concentration in German laboratory networks and emerging adoption patterns in microfluidic platforms. Forecast inputs incorporated MDR transition timeline assumptions, clinic consolidation velocity in Bavaria and North Rhine-Westphalia, and translational research funding allocation through Horizon Europe.
Inputs from fertility clinic procurement databases and Nordic chemical supplier production records were available through the study window; gaps in real-time adverse event reporting from member state competent authorities introduce uncertainty bands around post-market surveillance compliance cost estimates. Periodic stress-testing of base assumptions against EMA guidance evolution and notified body capacity constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intubation Tubes Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
China Respiratory Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market