
 Physical Therapy Supplies Market | 2026-2036
Physical Therapy Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Therapy Supplies Market Analytics
Portable electrotherapy and connected rehabilitation platforms is fragmenting traditional supply chains as cloud-integrated devices displace standalone units. Dynatronics Corporation anchors its position through in-house manufacturing of clinical-grade stimulation systems. Performance Health competes across multiple channel tiers with broad distribution reach. Storz Medical AG specializes in shockwave technology for orthopedic rehabilitation applications.
Physical therapy supplies encompass equipment and consumables used to restore musculoskeletal function, including electrical stimulation devices operating at 1-120 Hz frequencies, latex-free resistance bands rated by tensile strength, and cryotherapy systems maintaining temperatures between 10-15 degrees Celsius for therapeutic application. These products serve clinical and home-based rehabilitation programs following surgery, injury, or chronic condition management. Exercise bands and resistance tubes capture substantial volume in home user segments where convenience drives repeat purchase behavior. Rehabilitation centers and sports clinics generate higher per-site revenue through capital equipment procurement including combination therapy devices and hydrotherapy systems. Direct sales channels retain margin advantages for complex electrotherapy configurations requiring clinical training.
The US FDA classifies electrical stimulation devices under 21 CFR 890.5850, requiring premarket notification for powered muscle stimulators used in prescription settings. The EU MDR mandates clinical evidence and notified body certification for active therapeutic devices distributed across member states, with CE marking transitions creating compliance bottlenecks for smaller manufacturers. Japan's PMDA enforces QMS ordinances that foreign suppliers must satisfy through in-country representatives. Stakeholders must monitor evolving reimbursement codes in Germany, the United States, and Japan, as coverage decisions directly determine addressable volume for capital-intensive modalities.
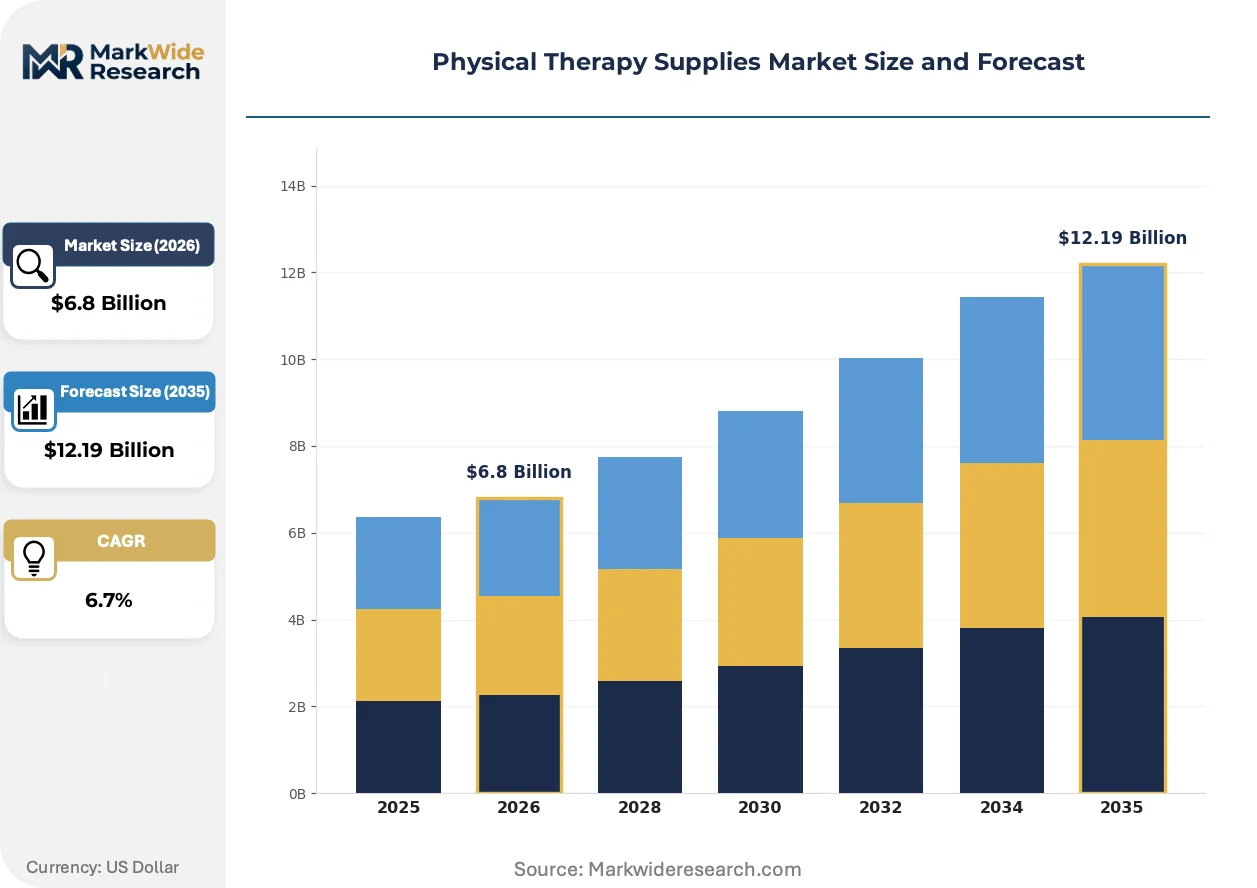
Market Dynamics
Portable rehabilitation equipment is fragmenting traditional supply chains as cloud-integrated electrotherapy systems displace standalone units in clinical and home settings. This shift compresses replacement cycles while expanding addressable volume beyond institutional buyers.
Growth Catalysts
- Statutory health insurance coverage:Germany's statutory health insurance funds prescribed physical therapy devices, creating guaranteed reimbursement pathways that stabilize procurement volumes for electrical stimulation and shockwave systems.
- FDA 510(k) pathway efficiency:The FDA's premarket notification framework for powered muscle stimulators under 21 CFR 890.5850 accelerates commercialization timelines for prescription-grade electrotherapy innovations.
- Sports clinic expansion:Orthopedic and sports medicine clinics in Australia, Brazil, and South Korea are scaling capital equipment procurement for combination therapy platforms serving post-surgical rehabilitation protocols.
Market Restraints
- EU MDR compliance bottlenecks:CE marking transitions under the EU Medical Device Regulation create clinical evidence requirements and notified body certification delays that constrain smaller manufacturers' market access.
- Copper and semiconductor input volatility:Electrotherapy device production depends on copper wiring and microcontroller components subject to supply concentration in East Asian foundries.
- Substitution by virtual physical therapy:Telehealth platforms delivering guided exercise protocols without hardware displace low-complexity resistance band and basic mobility aid purchases in home segments.
Strategic Opportunities
- Japan's aging demographic tailwind:METI's Silver Innovation initiatives and PMDA's streamlined QMS ordinances for home-use devices open reimbursement-aligned pathways for connected rehabilitation platforms.
- Shockwave-ESWT convergence:Extracorporeal shockwave therapy systems are hybridizing with radial pressure wave technologies to create multi-modal orthopedic treatment platforms serving tendon and bone healing applications.
- Direct-to-patient subscription channels:Cloud-integrated home electrotherapy devices bypass durable medical equipment distributors through manufacturer-managed recurring revenue models.
Industry Challenges
- Biomedical engineer scarcity:Clinical-grade stimulation system development requires specialized firmware and signal processing expertise concentrated in medical device hubs.
- Legacy EMR integration complexity:Connected rehabilitation platforms face interoperability friction with hospital electronic medical record systems that delay enterprise sales cycles.
- ISO 13485 certification timelines:Quality management system audits for active therapeutic devices extend product launch schedules by 12-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Therapy Supplies Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exercise Bands, Resistance Tubes, Foam Rollers, Massage Balls End User: Rehabilitation Centers, Sports Clinics, Hospitals, Home Users Application: Injury Recovery, Pain Management, Mobility Enhancement, Strength Training Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | BTL, EMS Physio Ltd., Dynatronics Corporation, RICHMAR, Performance Health, Storz Medical AG, Zimmer MedizinSysteme GmbH, ITO Co., Ltd., Enraf-Nonius B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Therapy Supplies Market Evolving Landscape
Electrotherapy and rehabilitation technology is converging around sensor-enabled feedback systems that transform passive treatment into quantified therapeutic protocols. This convergence redefines product value propositions across institutional and consumer segments.
Transcutaneous electrical nerve stimulation (TENS) and neuromuscular electrical stimulation (NMES) platforms are hybridizing with accelerometer and pressure sensor arrays to deliver real-time biomechanical feedback during rehabilitation exercises. Sports medicine clinics in Germany and the United States are adopting these integrated systems at replacement cycle compression rates of 30-40% faster than standalone predecessors. The technology is hybridizing treatment documentation and outcomes verification into single-device workflows that satisfy payer audit requirements.
The EU Medical Device Regulation's clinical evidence mandates for active therapeutic devices are forcing manufacturers to establish post-market surveillance systems and periodic safety update reports. This regulatory burden disproportionately affects Class IIa and IIb electrotherapy manufacturers distributing across member states, with notified body capacity constraints extending certification timelines. German and French orthopedic device suppliers are responding by consolidating technical documentation and clinical evaluation reports across product families.
Home-based rehabilitation buyers are consolidating purchases through specialty durable medical equipment retailers and manufacturer-direct digital channels that displace traditional pharmacy and general medical supply distribution. This channel migration compresses price transparency and comparison shopping for resistance bands, cryotherapy systems, and portable stimulators. The shift is most visible in United States and Australian markets where high-deductible health plans increase consumer price sensitivity.
Physical Therapy Supplies Market Segmentation
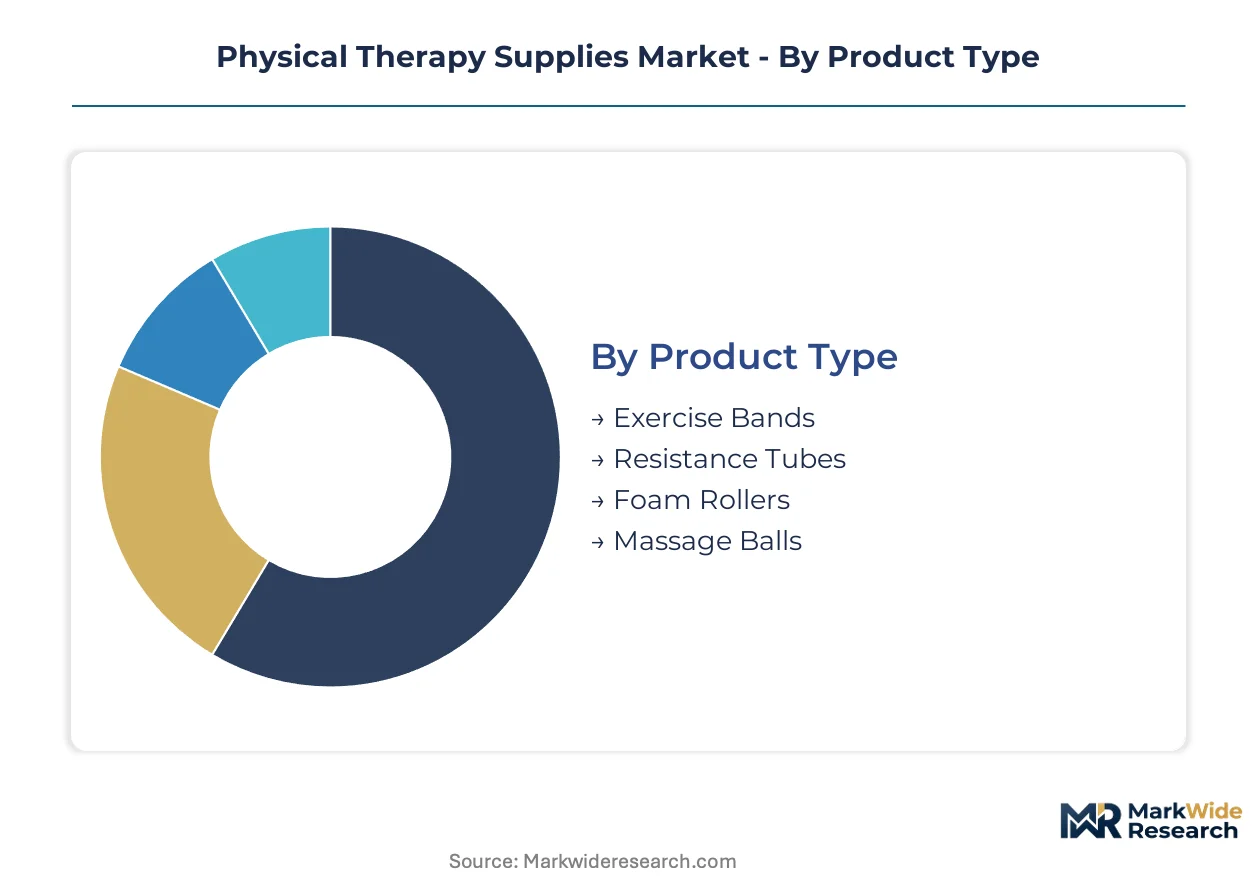
Physical therapy supplies fragment across multiple demand dimensions where product complexity, reimbursement pathways, and user sophistication diverge sharply. Understanding these splits reveals why capital equipment and consumable categories follow entirely different margin and replacement cycle logics.
Product Type:
After-sales intensity separates consumable disposables from capital platforms requiring calibration support and firmware maintenance contracts.
- Exercise Bands:Latex-free elastomer strips rated by tensile strength from 3-15 pounds serve progressive resistance protocols in home and clinical settings. German statutory health insurance reimbursement for prescribed resistance training drives institutional procurement volumes in Europe's largest rehabilitation market.
- Resistance Tubes:Hollow elastomer cylinders with handles or ankle attachments enable multi-planar movement patterns unavailable with flat bands. Sports clinics in Australia and South Korea are scaling tube-based protocols for post-surgical shoulder and hip rehabilitation where controlled tension progression accelerates return-to-play timelines.
- Foam Rollers:EVA and EPP foam cylinders of varying density provide myofascial release for muscle recovery protocols.
- Massage Balls:Silicone and rubber sphere configurations target trigger point therapy with portable, low-cost intervention.
Exercise Bands hold the largest share; momentum sits with Resistance Tubes as sports medicine protocols expand.
End User:
Capital deployment capacity and procurement authorization complexity stratify sharply across institutional and individual buyers.
- Rehabilitation Centers:Dedicated facilities operating under physician supervision procure combination therapy platforms including hydrotherapy systems and multi-channel electrotherapy devices. Japan's PMDA QMS ordinances for home-use device exports create compliance pathways that Japanese rehabilitation chains exploit for technology refresh cycles.
- Sports Clinics:Orthopedic and sports medicine practices prioritize portable modalities with rapid setup times and minimal space requirements. Brazilian and Australian clinic networks are expanding shockwave and ESWT platform procurement as post-surgical rehabilitation protocols standardize across private practice settings.
- Hospitals:Acute care facilities integrate physical therapy supplies into bundled payment models where length-of-stay reduction drives equipment selection.
- Home Users:Individual purchasers operating without clinical supervision favor low-complexity, visually intuitive products available through direct digital channels.
Rehabilitation Centers dominate capital expenditure; Home Users are expanding most quickly as high-deductible plans shift cost burden to individuals.
Application:
Clinical evidence requirements and reimbursement code availability determine which applications support premium pricing versus commodity competition.
- Injury Recovery:Post-surgical and post-trauma rehabilitation protocols require graduated loading and tissue healing monitoring. FDA 510(k) pathway efficiency for powered muscle stimulators accelerates commercialization of prescription-grade devices serving this segment in the United States.
- Pain Management:TENS and cryotherapy applications targeting chronic pain conditions face substitution pressure from pharmacological alternatives and virtual physical therapy platforms. Germany's statutory coverage for prescribed electrotherapy devices stabilizes procurement volumes despite competitive pressure.
- Mobility Enhancement:Gait training and range-of-motion protocols serve neurological and geriatric patient populations with specialized equipment needs.
- Strength Training:Progressive resistance protocols span athletic performance and functional restoration with overlapping product requirements.
Injury Recovery commands premium pricing; Pain Management faces steepest margin compression from virtual alternatives.
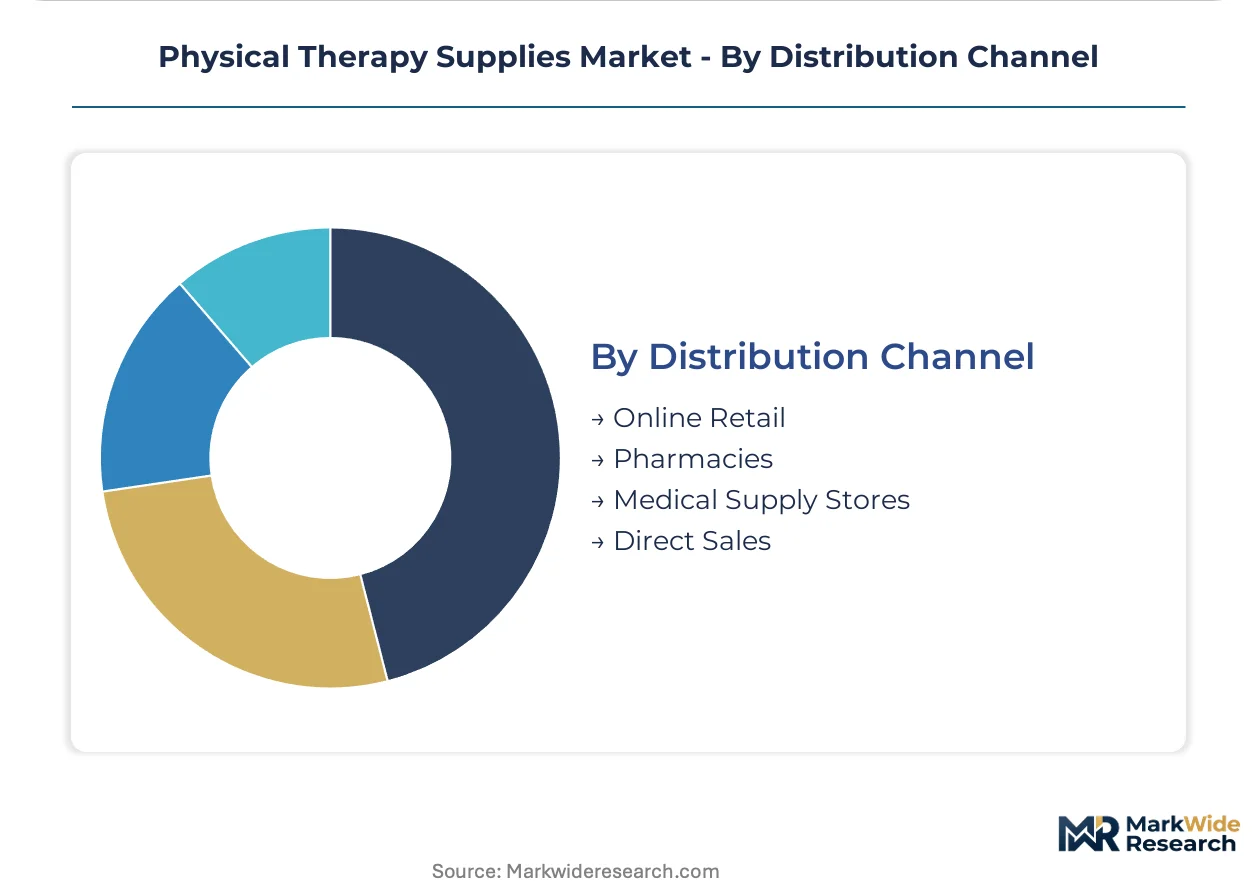
Distribution Channel:
Channel selection determines margin retention, customer data access, and clinical training obligation allocation between manufacturer and intermediary.
- Online Retail:Digital marketplaces and manufacturer-direct platforms displace traditional distribution for standardized consumables. United States and Australian consumers consolidate purchases through specialty durable medical equipment retailers where price transparency compresses comparison shopping for resistance bands and portable stimulators.
- Direct Sales:Manufacturer-controlled channels retain margin advantages for complex electrotherapy configurations requiring clinical training and installation support. Cloud-integrated home electrotherapy devices are migrating toward subscription models that bypass durable medical equipment distributors entirely.
- Pharmacies:Retail pharmacy chains capture convenience-driven purchases of low-complexity mobility aids and basic cryotherapy products.
- Medical Supply Stores:Independent and chain specialty retailers serve institutional procurement with credit terms and volume pricing unavailable through consumer channels.
Direct Sales retains highest margin; Online Retail is gaining share fastest as home-use device connectivity enables manufacturer-managed recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electrotherapy systems to sports clinics across Australia and Brazil, establishing a trade corridor that channels European engineering expertise into high-growth rehabilitation markets.
United States
FDA 510(k) premarket notifications for powered muscle stimulators under 21 CFR 890.5850 accelerate commercialization timelines for prescription-grade devices. Private orthopedic networks in Texas and Florida are consolidating procurement through group purchasing organizations. The Greater Boston cluster anchors connected rehabilitation platform development with proximity to biomedical engineering talent pools.
Germany
Statutory health insurance funds prescribed physical therapy devices, creating guaranteed reimbursement pathways for electrical stimulation and shockwave systems. The EU MDR's clinical evidence mandates force manufacturers to consolidate technical documentation across product families. Bavaria's medical technology corridor concentrates shockwave-ESWT hybrid system production serving tendon and bone healing applications.
Japan
METI's Silver Innovation initiatives align with PMDA's streamlined QMS ordinances for home-use devices, opening reimbursement-aligned pathways for connected rehabilitation platforms. The aging demographic generates demand for sensor-enabled feedback systems in geriatric rehabilitation. Kanto's Tokyo-Osaka industrial belt hosts firmware development for clinical-grade stimulation systems.
Australia
Sports medicine clinics are scaling capital equipment procurement for combination therapy platforms serving post-surgical rehabilitation protocols. The TGA's medical device regulatory framework parallels FDA pathways, reducing compliance friction for US and European suppliers. Sydney and Melbourne anchor private clinic network expansion with rapid technology refresh cycles.
Brazil
ANVISA's medical device registration requirements create compliance checkpoints for imported electrotherapy equipment. Private orthopedic and sports medicine practices are standardizing post-surgical rehabilitation protocols across clinic networks. São Paulo's healthcare infrastructure concentrates demand for portable modalities with rapid setup times.
Physical Therapy Supplies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures where distribution reach and clinical training capabilities determine margin retention. The vendor base separates into three archetypes: diversified health equipment conglomerates with broad distribution networks, electrotherapy specialists with in-house manufacturing of stimulation systems, and shockwave technology pure-plays focused on orthopedic applications. M&A activity targets connected rehabilitation platform capabilities, while strategic partnerships address legacy EMR integration complexity.
Among diversified equipment suppliers, Performance Health exemplifies channel-controlling scale across multiple distribution tiers. Dynatronics Corporation anchors the clinical-grade manufacturing archetype through captive production of stimulation systems. Storz Medical AG occupies the shockwave specialization vector with radial pressure wave expertise. These three represent distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| BTL |
| EMS Physio Ltd. |
| Dynatronics Corporation |
| RICHMAR |
| Performance Health |
| Storz Medical AG |
| Zimmer MedizinSysteme GmbH |
| ITO Co., Ltd. |
| Enraf-Nonius B.V. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese microcontroller foundries is compressing component costs for electrotherapy manufacturers while simultaneously eroding supplier pricing power across portable rehabilitation device tiers. This utilization dynamic creates divergent margin pressures where cloud-integrated platforms capture premium positioning while standalone units face commodity pricing.
Pricing Analysis
Current-generation cloud-integrated electrotherapy systems command substantial premiums over prior-generation standalone units, while next-generation AI-enhanced feedback platforms are entering at super-premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared prescription devices from OTC wellness products and unbranded consumables. Cost compression in resistance bands and basic cryotherapy systems is intensifying because telehealth substitution eliminates hardware requirements for guided exercise protocols. Home users operating under high-deductible health plans exhibit highest price sensitivity, while German rehabilitation centers with statutory reimbursement coverage show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for copper wiring and semiconductor components that feed electrotherapy device assembly. Manufacturing concentrates in China, South Korea, and Germany, with East Asian foundries supplying microcontroller units and Bavarian engineering clusters producing clinical-grade stimulation system housings. Raw material dependencies center on copper conductors, medical-grade elastomers for resistance bands, and lithium-ion cells for portable units. Single-source vulnerability in advanced microcontroller fabrication creates bottlenecks for connected rehabilitation platform launches. Distribution runs through durable medical equipment wholesalers for institutional procurement and manufacturer-direct digital channels for home-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical therapy supplies sit in early-cycle expansion as cloud-integrated rehabilitation platforms penetrate home segments previously served only by institutional providers. Japan's aging demographic tailwind and Germany's statutory reimbursement coverage create dual demand anchors for connected device adoption.
For Market Incumbents: Pre-empt virtual physical therapy substitution by embedding sensor-enabled feedback systems that telehealth platforms cannot replicate without hardware partnerships. Defend margin position through backward integration into firmware development for clinical-grade stimulation systems, reducing dependence on scarce biomedical engineering talent. Accelerate ISO 13485 certification investments to compress product launch timelines against emerging competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in Brazil and Australia's sports clinic networks where post-surgical rehabilitation protocol standardization drives capital equipment procurement. Target shockwave-ESWT hybrid systems for orthopedic applications where clinical evidence requirements create barriers to commoditization. Deploy direct-to-patient subscription channels that bypass entrenched durable medical equipment distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwind play because aging populations across Japan, Germany, and the United States guarantee sustained demand for musculoskeletal rehabilitation. Acquisition candidates with connected platform capabilities and established EMR integration pathways offer highest strategic value. Monitor FDA 510(k) clearance velocity and EU MDR notified body capacity as inflection indicators for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence mandates force consolidation of technical documentation across electrotherapy product families. |
| Hospital System Partnership | Bundled payment models in US acute care facilities prioritize length-of-stay reduction through combination therapy platform procurement. |
| Software Companion Development | Cloud-integrated rehabilitation platforms require EMR interoperability to satisfy enterprise sales cycle requirements. |
| Reimbursement Strategy | Germany's statutory health insurance coverage for prescribed devices stabilizes procurement volumes against virtual therapy substitution. |
| FDA Submission | Premarket notification efficiency under 21 CFR 890.5850 accelerates commercialization timelines for powered muscle stimulators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with rehabilitation center directors, sports clinic procurement managers, biomedical engineers at device manufacturers, GPO contracts administrators, and home-use device consumers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, German statutory health insurance reimbursement code registries, and Japan PMDA QMS ordinance guidance documents. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, application, and distribution channel dimensions.
Calibration against historical replacement cycle data and regulatory approval timelines anchored volume and value outputs across the projection horizon. Segmentation modeling incorporated product complexity tiers, reimbursement pathway availability, institutional versus home-use buyer archetypes, and regional regulatory cluster variations. CAGRs were derived from weighted average growth contributions across segment-level demand trajectories, with specific inputs including electrotherapy device penetration rates in sports medicine clinics and resistance band repeat purchase frequency in consumer channels.
Sensitivities concentrate around EU MDR notified body capacity constraints, copper and semiconductor input cost volatility, and virtual physical therapy platform substitution rates. Forecasts reflect documented assumptions regarding reimbursement stability and technology refresh cycle compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Shoe Cover Market