
 Asia-Pacific Repair and Rehabilitation Market | 2026-2036
Asia-Pacific Repair and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Repair and Rehabilitation Market Outlook
High-performance epoxy-grade specifications is rotating through the Asia-Pacific repair and rehabilitation supply base as asset owners prioritize load-bearing restoration over cosmetic patching. SIKA AG leverages its Swiss-originated formulation expertise to dominate specification-grade adhesive supply chains across Southeast Asian infrastructure tenders. MBCC Group anchors its regional position through backward integration into cementitious repair mortar production in India and Thailand. Pidilite Industries Ltd specializes in cost-optimized acrylic bonding agents that compete aggressively in India's residential renovation segment.
Asia-Pacific repair and rehabilitation encompasses the structural restoration, surface protection, and functional renewal of deteriorated concrete, steel, and composite substrates using cementitious grouts, polymer-modified mortars, and elastomeric membranes to extend service life and restore design load capacity. Epoxy injection resins and carbon fiber laminates achieve tensile strengthening ratios exceeding steel plate bonding while minimizing dead load additions. Cementitious repair mortars lead product type volumes due to their compatibility with existing concrete substrates and lower material cost structures across public infrastructure budgets. Advanced materials technology commands premium positioning in Japan's seismic retrofitting sector where carbon fiber reinforced polymer sheets displace traditional steel jacketing for column confinement. Eco-friendly solutions represent the fastest-growing technology trajectory as Australia's Green Star certification and Singapore's Building and Construction Authority sustainability mandates drive low-VOC formulation requirements.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces mandatory bridge inspection cycles that directly expand demand for structural monitoring and repair material procurement. India's BIS certification requirements for repair products create market access barriers that favor established domestic manufacturers with testing laboratory relationships. Australia's National Construction Code and state-level building audit programs in New South Wales and Victoria accelerate commercial upgrade spending on fireproofing and facade remediation. Stakeholders must monitor how evolving carbon accounting rules across Australian state jurisdictions reshape material specification criteria for publicly funded rehabilitation contracts.
Market Dynamics
Japan's seismic retrofitting mandates and Australia's bridge inspection cycles are compressing specification timelines for carbon fiber reinforced polymer systems across Asia-Pacific infrastructure procurement.
Growth Catalysts
- Japan's MLIT bridge inspection mandates:Mandatory assessment cycles for highway and railway structures generate recurring demand for structural monitoring systems and epoxy injection materials.
- Carbon fiber laminate adoption:Public infrastructure authorities in Australia specify CFRP sheets for column confinement, displacing traditional steel jacketing in seismic upgrade programs.
- Urban renewal corridors:Australia's state-level building audit programs in New South Wales and Victoria accelerate commercial facade remediation and fireproofing material procurement.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margins for injection resin formulators serving public infrastructure tenders.
- BIS certification barriers:India's Bureau of Indian Standards testing requirements favor established domestic manufacturers with laboratory relationships, limiting new entrant access.
- Steel plate bonding substitution:Cost-conscious municipal clients in Southeast Asia retain conventional strengthening methods despite CFRP performance advantages.
Strategic Opportunities
- Green Star certification tailwinds:Australia's sustainability mandates for low-VOC formulations create specification advantages for eco-friendly mortar and membrane suppliers.
- Thailand's industrial corridor expansion:Manufacturing facility construction generates demand for concrete repair and protective coating systems in underpenetrated provincial markets.
- Digital inspection convergence:Integration of drone-based structural assessment with automated material specification platforms streamlines procurement for asset managers.
Industry Challenges
- Certified applicator scarcity:CFRP installation requires specialized technician training that outpaces workforce development programs in Indonesia and Vietnam.
- Legacy substrate compatibility:Cementitious repair mortars must accommodate variable aggregate conditions in aging Indian public buildings without standardized pre-treatment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Repair and Rehabilitation Market |
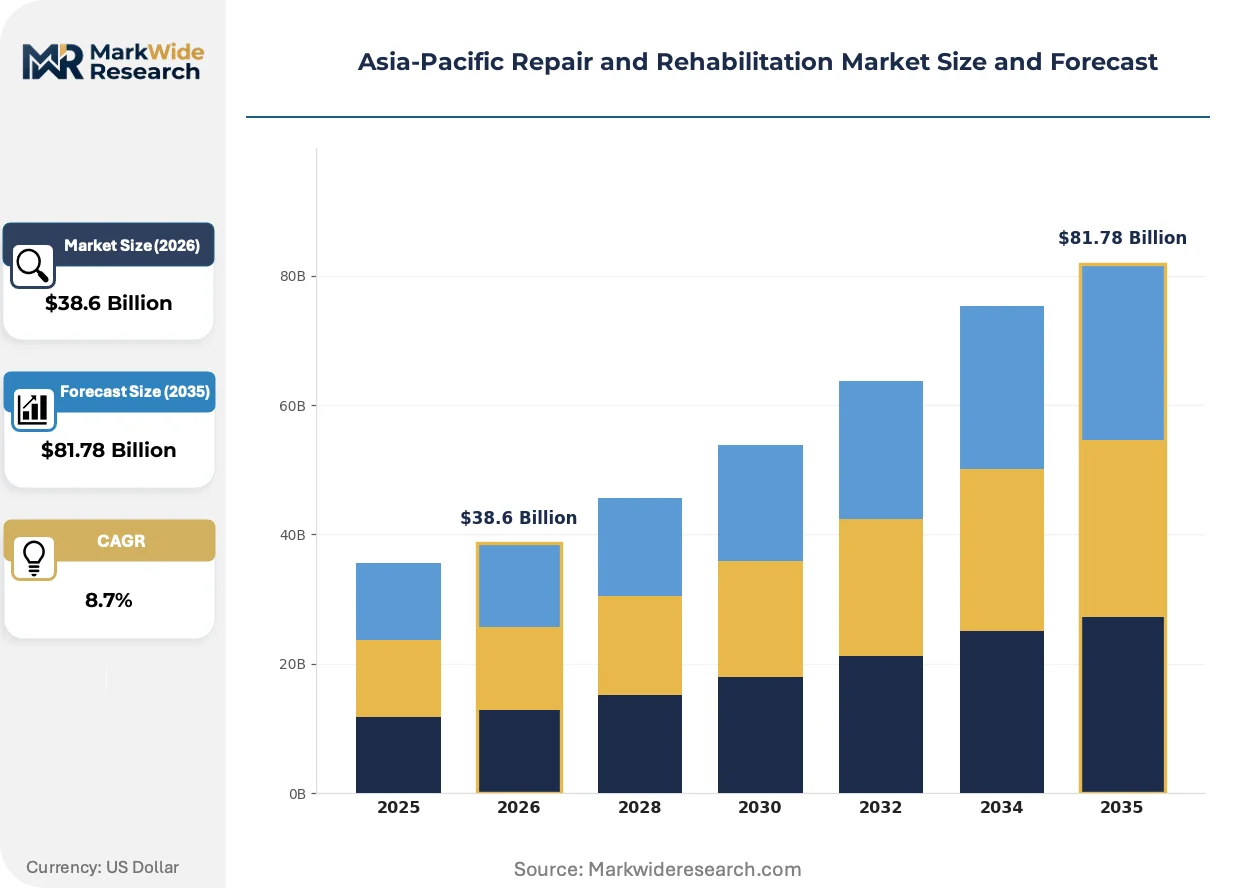
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cements, Adhesives, Coatings, Sealants Technology: Traditional Methods, Advanced Materials, Eco-Friendly Solutions, Nanotechnology End User: Construction, Automotive, Aerospace, Marine Application: Infrastructure Maintenance, Residential Renovation, Industrial Repair, Commercial Upgrades |
| Companies Covered | Arkema, MBCC Group, SIKA AG, Pidilite Industries Ltd, RPM International Inc, Saint-Gobain, FairMate, STP Limited, Fosroc Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Repair and Rehabilitation Market Strategic Shifts
Material specification priorities across Asia-Pacific infrastructure are pivoting from cosmetic remediation toward load-bearing restoration, reshaping formulation requirements and procurement evaluation criteria.
Carbon fiber reinforced polymer sheet systems are decomposing the market for traditional steel jacketing in seismic retrofit applications. Japan's Ministry of Land, Infrastructure, Transport and Tourism specifies CFRP confinement for bridge columns and building frames, compressing lead times for steel fabrication and reducing dead load additions. Municipal asset managers in Tokyo and Osaka now prioritize polymer systems in standard tender documents.
Singapore's Building and Construction Authority sustainability mandates are tightening volatile organic compound limits for repair mortars and protective coatings. Construction material suppliers must reformulate cementitious products to meet low-emission certification requirements for publicly funded projects. Green building consultants now screen repair material submissions against embodied carbon thresholds before specification approval.
Asset owners in Australia's commercial property sector are unbundling structural assessment from repair execution, creating discrete procurement categories for engineering diagnostics and material supply. Facility managers contract specialized inspection firms for drone-enabled concrete condition mapping before soliciting separate bids for carbon fiber or epoxy remediation. This bifurcation is most visible in Sydney and Melbourne's aging office stock, where ownership structures separate capital planning from operational maintenance budgets.
Asia-Pacific Repair and Rehabilitation Market Segmentation
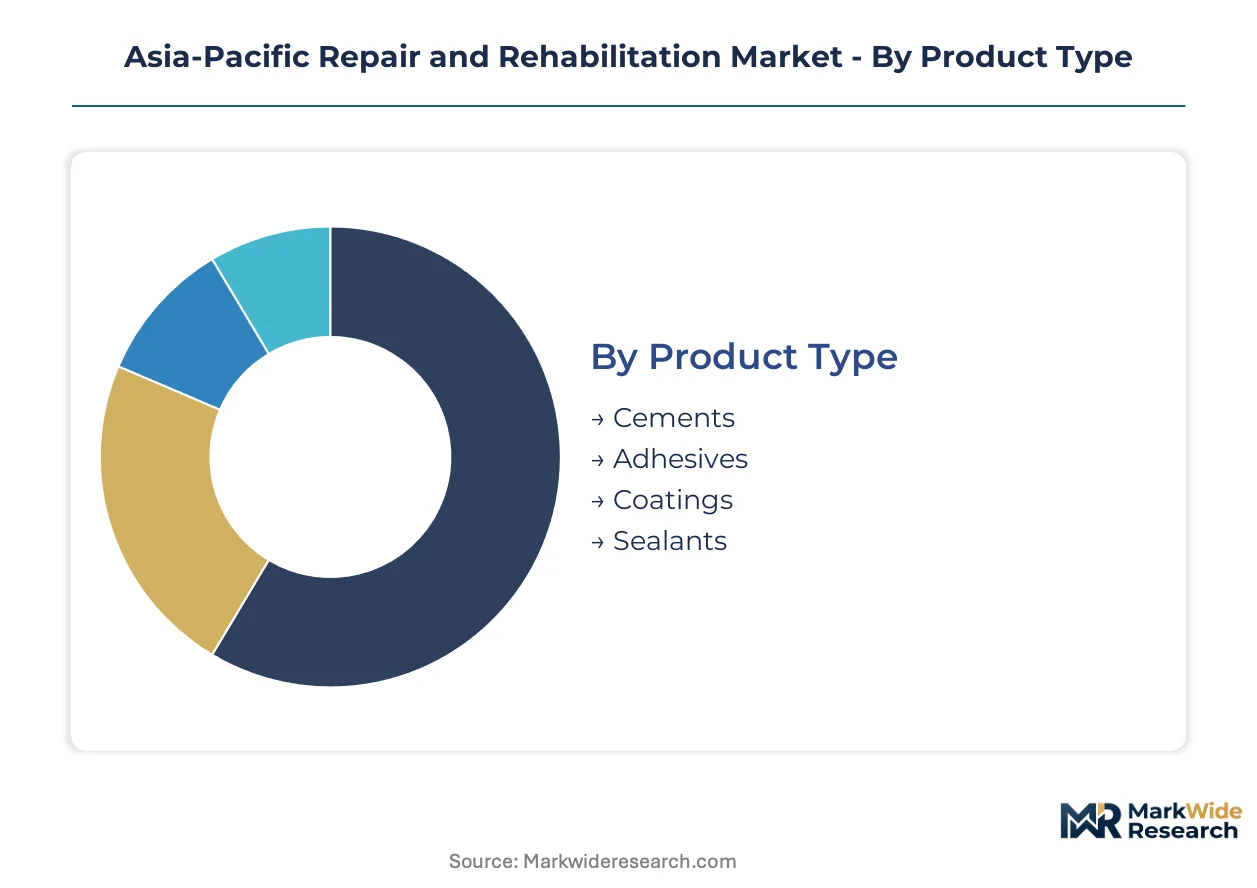
Segmentation reveals how repair material specifications diverge across procurement channels in the Asia-Pacific repair and rehabilitation market. Product type and technology choices cascade through infrastructure tenders, residential renovation retail, and industrial maintenance contracts with distinct margin and volume profiles.
Product Type:
Cementitious materials flow through bulk procurement channels serving public infrastructure authorities, while polymer systems concentrate in specialized contractor networks for seismic retrofitting applications.
- Cements:Cementitious repair mortars combine Portland cement with polymer modifiers to achieve substrate compatibility in aging concrete restoration. India's Bureau of Indian Standards certification requirements concentrate demand among domestic manufacturers with established testing laboratory relationships, creating procurement barriers for imported alternatives.
- Adhesives:Epoxy injection resins and structural bonding agents achieve tensile load transfer for crack injection and laminate bonding. Australia's bridge maintenance programs specify high-performance formulations, displacing lower-grade alternatives in state-level tender documents for New South Wales and Victoria infrastructure corridors.
- Coatings:Protective membranes and elastomeric finishes shield substrates from moisture ingress and chemical exposure. Singapore's Building and Construction Authority mandates low-VOC formulations for publicly funded projects.
- Sealants:Joint sealing compounds accommodate structural movement while preventing water penetration. Marine and industrial end-users in Thailand's eastern seaboard drive specification for polyurethane and polysulfide grades.
Cements dominate installed base across public infrastructure budgets. Adhesives are where expansion concentrates as carbon fiber laminate adoption accelerates.
Technology:
Technology selection stratifies by project scale and performance requirements, with cost tiers separating municipal maintenance from premium seismic retrofitting contracts.
- Traditional Methods:Concrete patching, steel plate bonding, and cementitious grouting retain preference in cost-constrained Southeast Asian municipal contracts. Indonesia and Vietnam maintain specification for conventional techniques despite performance limitations in seismic zones.
- Advanced Materials:Carbon fiber reinforced polymer sheets and high-modulus laminates achieve column confinement with minimal dead load addition. Japan's Ministry of Land, Infrastructure, Transport and Tourism specifies CFRP systems for highway and railway structure upgrades, compressing procurement timelines for steel fabrication alternatives.
- Eco-Friendly Solutions:Low-VOC mortars and bio-based coatings gain specification share under Australia's Green Star certification and Singaporean sustainability mandates. Embodied carbon thresholds now screen repair material submissions.
- Nanotechnology:Nano-modified cementitious additives and self-healing concrete formulations penetrate high-value infrastructure monitoring contracts. Pilot deployments concentrate in Tokyo and Osaka metropolitan asset management programs.
Traditional methods anchor volume across Southeast Asian public budgets. Eco-friendly solutions are climbing the fastest as certification requirements tighten.
End User:
End-user concentration shapes geographic demand clusters, with construction absorbing bulk volumes while specialized industrial segments command premium pricing.
- Construction:Building and infrastructure rehabilitation consumes the majority of cementitious and polymer repair materials. Japan's seismic retrofitting sector and Australia's urban renewal corridors generate concentrated demand for structural-grade systems.
- Automotive:Manufacturing facility concrete repair and protective coating applications serve assembly plant maintenance cycles. Thailand's industrial corridor expansion drives provincial market development.
- Aerospace:Airport runway and hangar facility rehabilitation requires high-performance repair systems with rapid return-to-service characteristics. Specifications concentrate in major hub cities.
- Marine:Port infrastructure and coastal structure protection demands corrosion-resistant repair mortars and splash-zone coatings. Singapore and Australian port authorities drive material innovation.
Construction absorbs the dominant volume share. Marine applications are where technology premiums concentrate.
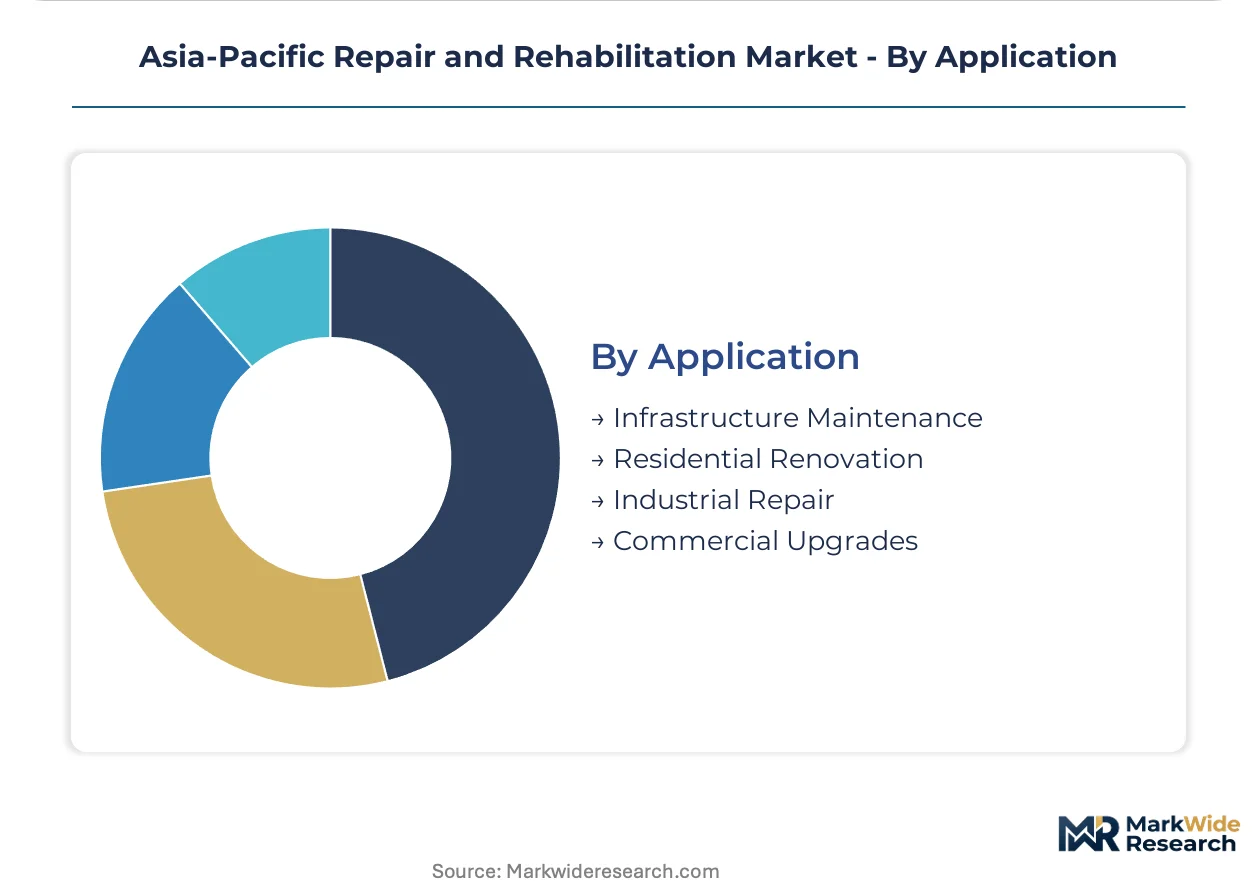
Application:
Application type determines procurement channel structure, with infrastructure maintenance flowing through public tender processes and residential renovation serving fragmented retail distribution.
- Infrastructure Maintenance:Bridge, tunnel, and highway rehabilitation programs operate through government procurement frameworks with extended specification cycles. Japan's MLIT inspection mandates generate recurring demand for structural monitoring and repair material procurement.
- Residential Renovation:Aging building stock remediation in India's urban centers and Australia's established suburbs drives cost-optimized acrylic bonding agent and decorative repair mortar consumption. Pidilite Industries competes aggressively in this price-sensitive segment.
- Industrial Repair:Manufacturing facility floor restoration, chemical containment area rehabilitation, and equipment foundation repair serve continuous operations requirements. Thailand and Vietnam industrial zones expand addressable market.
- Commercial Upgrades:Office building facade remediation and fireproofing material procurement accelerate under Australian state-level audit programs. Sydney and Melbourne ownership structures separate capital planning from operational maintenance budgets.
Infrastructure maintenance dominates specification-grade volumes. Commercial upgrades are where procurement bifurcation between assessment and execution is advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports carbon fiber reinforced polymer systems to Australia's bridge maintenance programs, creating a specialized trade corridor for seismic-grade repair materials across the Asia-Pacific region.
Japan
Seismic retrofitting mandates from the Ministry of Land, Infrastructure, Transport and Tourism drive recurring demand for structural monitoring and epoxy injection materials. MLIT enforces mandatory bridge inspection cycles that directly expand procurement volumes for carbon fiber laminate systems. Tokyo and Osaka metropolitan asset management programs concentrate specification-grade adhesive consumption for highway and railway structure upgrades.
Australia
Urban renewal corridors in New South Wales and Victoria accelerate commercial facade remediation and fireproofing material procurement. The National Construction Code and state-level building audit programs reshape specification criteria for publicly funded rehabilitation contracts. Sydney and Melbourne's aging office stock exhibits procurement bifurcation between drone-enabled structural assessment and separate repair execution bids.
India
Aging public buildings in urban centers generate demand for cost-optimized cementitious repair mortars and acrylic bonding agents. The Bureau of Indian Standards mandates stricter structural audit protocols and certification requirements that favor established domestic manufacturers with testing laboratory relationships. Maharashtra and Gujarat industrial zones concentrate BIS-certified mortar production capacity.
Singapore
The Building and Construction Authority sustainability mandates tighten volatile organic compound limits for repair mortars and protective coatings. Low-emission certification requirements for publicly funded projects screen material submissions against embodied carbon thresholds. Marina Bay and Jurong industrial clusters drive specification for eco-friendly membrane systems in port infrastructure applications.
Thailand
Manufacturing facility construction in provincial markets generates demand for concrete repair and protective coating systems. The eastern seaboard industrial corridor expansion drives specification for polyurethane and polysulfide sealants in marine and chemical containment applications. Rayong and Chonburi provinces concentrate industrial maintenance contract awards for floor restoration and equipment foundation repair.
Asia-Pacific Repair and Rehabilitation Market Competitive Environment
Listed leaders compete with private specialists across formulation expertise and certification relationships, producing a tiered structure where Swiss-originated multinationals anchor premium specification channels while domestic manufacturers capture cost-sensitive segments. The vendor base stratifies into three strategic archetypes: multinational chemical conglomerates with backward integration into polymer production, regional specialists with BIS laboratory relationships, and diversified construction material suppliers with retail distribution networks. Competitive moves concentrate on M&A for testing facility access and strategic partnerships for drone-enabled inspection platform integration.
Within the multinational tier, SIKA AG and MBCC Group exemplify formulation-led positioning, with the former leveraging Swiss-originated adhesive expertise and the latter anchoring regional presence through cementitious mortar production in India and Thailand. Pidilite Industries Ltd occupies a position among domestic specialists competing aggressively in India's residential renovation segment through cost-optimized acrylic bonding agent portfolios.
| Leading Market Players |
|---|
| Arkema |
| MBCC Group |
| SIKA AG |
| Pidilite Industries Ltd |
| RPM International Inc |
| Saint-Gobain |
| FairMate |
| STP Limited |
| Fosroc Inc |
| Others |
Value Chain & Pricing Dynamics
Sixty-day epoxy resin lead times from Japanese petrochemical hubs concentrate pricing power among CFRP laminate suppliers serving Australia's bridge maintenance tenders. This inventory compression forces asset owners into long-term offtake contracts or spot market premiums, while domestic mortar producers in India and Thailand capture margin through backward integration into cementitious raw materials.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Asia-Pacific infrastructure procurement. Three-tier pricing structure across seismic-grade, structural-grade, and maintenance-grade levels separates Japan's MLIT-certified CFRP systems from Australia's standard bridge repair specifications and India's cost-optimized cementitious alternatives. Pricing pressure stems from petrochemical feedstock volatility in epoxy resin formulations, squeezing margins for injection material suppliers serving public tenders. Municipal authorities in Southeast Asia exhibit highest price sensitivity, while Japan's metropolitan asset managers prioritize performance certification over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate Japan's seismic-grade adhesive procurement, while just-in-time inventory management prevails among Australia's commercial facade remediation contractors. Manufacturing concentration rests on Japan for carbon fiber precursor chemicals, India for BIS-certified cementitious mortars, and Thailand for polyurethane sealant production. Raw material dependencies center on bisphenol-A epoxies, polyacrylonitrile carbon fiber feedstocks, and Portland cement clinker. Single-source vulnerability runs through Japanese carbon fiber tow suppliers for regional CFRP laminate fabricators. Distribution runs through specialized contractor networks for polymer systems and bulk procurement channels for cementitious materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as steel plate bonding retains preference among cost-constrained Southeast Asian municipal clients despite CFRP performance advantages.
For Market Incumbents: Consolidate specification-grade adhesive positioning through captive laboratory relationships with India's BIS and Australia's state-level infrastructure authorities. Deepen backward integration into epoxy resin formulation to offset petrochemical price volatility compressing margins on injection materials. Prioritize certification investment for Green Star-compliant low-VOC mortar portfolios as Singapore and Australia tighten sustainability mandates.
For New Entrants and Emerging Players: Lead with drone-enabled structural assessment platforms that unbundle diagnostics from repair execution, targeting Australia's commercial property sector where ownership structures separate capital planning from operational maintenance. Penetrate Thailand's provincial industrial corridors for concrete repair and protective coating systems, where manufacturing facility construction outpaces established supplier coverage. Deploy direct contractor channel partnerships rather than competing for public tender specifications dominated by incumbent certification relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because BIS laboratory relationships and MLIT certification pathways create durable moats around specification-grade material suppliers. Target acquisition archetypes include domestic mortar manufacturers with established testing facility access in India and regional specialists with drone inspection platform integration capabilities. Watch for inflection when carbon accounting rules across Australian state jurisdictions reshape material specification criteria for publicly funded contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Mitigates petrochemical price volatility squeezing margins on MLIT-specified injection materials. |
| BIS Laboratory Certification Investment | Creates procurement barriers favoring established domestic manufacturers in India's public infrastructure tenders. |
| Drone-Enabled Inspection Platform Partnership | Captures Australia's bifurcated procurement separating structural assessment from carbon fiber repair execution. |
| Green Star Low-VOC Formulation Transition | Aligns mortar and coating portfolios with Singapore BCA sustainability mandates tightening emission limits. |
| Provincial Industrial Corridor Expansion | Addresses underpenetrated Thai markets in Rayong and Chonburi for manufacturing facility concrete repair demand. |
Study Parameters
The analysis maps cementitious mortars, polymer adhesives, CFRP laminates, and protective coatings, each validated through structural engineers, procurement officers at public infrastructure authorities, certified applicator contractors, and distribution channel partners. Primary fieldwork combined with secondary validation from customs trade records, BIS certification databases, MLIT bridge inspection disclosures, and Green Star product registry filings. Bottom-up project pipeline assessments triangulated against top-down public budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-use industry, application channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating infrastructure age profiles, seismic retrofitting mandate schedules, and sustainability certification adoption rates. Forecast inputs centered on bridge inventory condition assessments and urban renewal corridor investment pipelines.
The analysis sits within stated boundaries; outcomes outside sustained public infrastructure budget commitments and current regulatory certification pathways would require recalibration. Forecasts reflect assumptions regarding MLIT inspection cycle enforcement, BIS testing requirement stability, and petrochemical feedstock availability. Revision becomes warranted when carbon accounting threshold crossings or alternative strengthening technology cost parity disrupt specification-grade material demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Global Medical Rehabilitation Services Market