
 Global Neurorehabilitation Devices Market | 2026-2036
Global Neurorehabilitation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurorehabilitation Devices Market Foresight
The EU Green Deal is expanding procurement criteria for medical devices with lifecycle environmental assessments, which pushes rehabilitation centers toward durable, serviceable equipment. Medtronic leverages its neurostimulation R&D infrastructure across multiple therapeutic areas. Ekso Bionics anchors the robotic exoskeleton segment with specialized hardware for spinal cord injury gait training. Hocoma AG dominates European installations of balance and locomotion systems in inpatient settings.
Neurorehabilitation devices comprise electromechanical systems, neuroprosthetic implants, and sensory feedback interfaces engineered to restore or substitute motor, sensory, and cognitive functions compromised by neurological injury or disease. These systems typically integrate real-time biomechanical sensing with adaptive actuation algorithms operating at sub-100-millisecond latency to modulate therapeutic intervention. Robotic exoskeletons lead product-type revenue due to high unit value and institutional purchasing concentration, while brain-computer interface technology represents the fastest-expanding segment as non-invasive electroencephalography decoding achieves clinically viable throughput. Stroke rehabilitation generates the largest application volume, though spinal cord injury commands premium pricing per intervention cycle.
The FDA enforces Class II and Class III pathways for neurostimulation and implantable neuroprosthetics, requiring substantial equivalence or premarket approval with clinical trial endpoints. The EU MDR mandates notified-body conformity assessment for active implantable devices, extending certification timelines and favoring established manufacturers with quality management system maturity. EMA pharmacovigilance obligations for device-drug combination products add compliance layers for developers integrating drug delivery with neurorehabilitation hardware. Stakeholders must monitor reimbursement code expansions by Germany's Federal Joint Committee and comparable health technology assessment bodies, as these decisions determine accessible patient volumes and device procurement cycles.
Market Dynamics
Robotic gait trainers are rewriting capital allocation patterns across hospital procurement departments, forcing rehabilitation centers to consolidate vendor relationships and extend equipment lifecycle planning horizons.
Growth Catalysts
- Germany's Federal Joint Committee:Expanded reimbursement codes for exoskeleton-assisted walking therapy now cover outpatient rehabilitation cycles, accelerating patient access and institutional purchasing confidence.
- Stroke incidence demographics:Aging populations across OECD member states are expanding the addressable patient pool for motor recovery interventions, particularly in acute-to-subacute care transitions.
- Sub-100-millisecond latency algorithms:Real-time adaptive actuation in electromechanical systems enables closed-loop therapeutic modulation previously unattainable with open-loop neurostimulation protocols.
Market Restraints
- EU MDR certification timelines:Notified-body conformity assessments for active implantable devices now extend 18-36 months, freezing product pipelines for developers lacking established quality management system maturity.
- Premium sensor hardware costs:Force-sensitive resistors and inertial measurement units constitute 23-31% of robotic exoskeleton bill-of-materials, exposing manufacturers to semiconductor supply volatility.
- Non-invasive brain-computer interfaces:Consumer-grade electroencephalography headsets for wellness applications threaten to commoditize perception of clinical-grade neural decoding systems.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for electromechanical rehabilitation hardware, enabling price-competitive positioning against European incumbents.
- Wearable sensory feedback convergence:Integration of haptic actuators with textile-based electromyography sensors creates ambulatory rehabilitation modalities outside institutional settings.
- EU Green Deal procurement criteria:Lifecycle environmental assessments now weight rehabilitation equipment tenders, favoring modular designs with field-replaceable subassemblies over sealed disposable units.
Industry Challenges
- Cross-functional engineering talent:Device developers require simultaneous competence in biomechanical modeling, embedded systems, and clinical trial design—skill combinations concentrated in Zurich, Boston, and Singapore metropolitan clusters.
- FDA premarket approval endpoints:Class III neuroprosthetic pathways demand functional independence measure scores with 12-month follow-up periods, extending capital lockup before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurorehabilitation Devices Market |
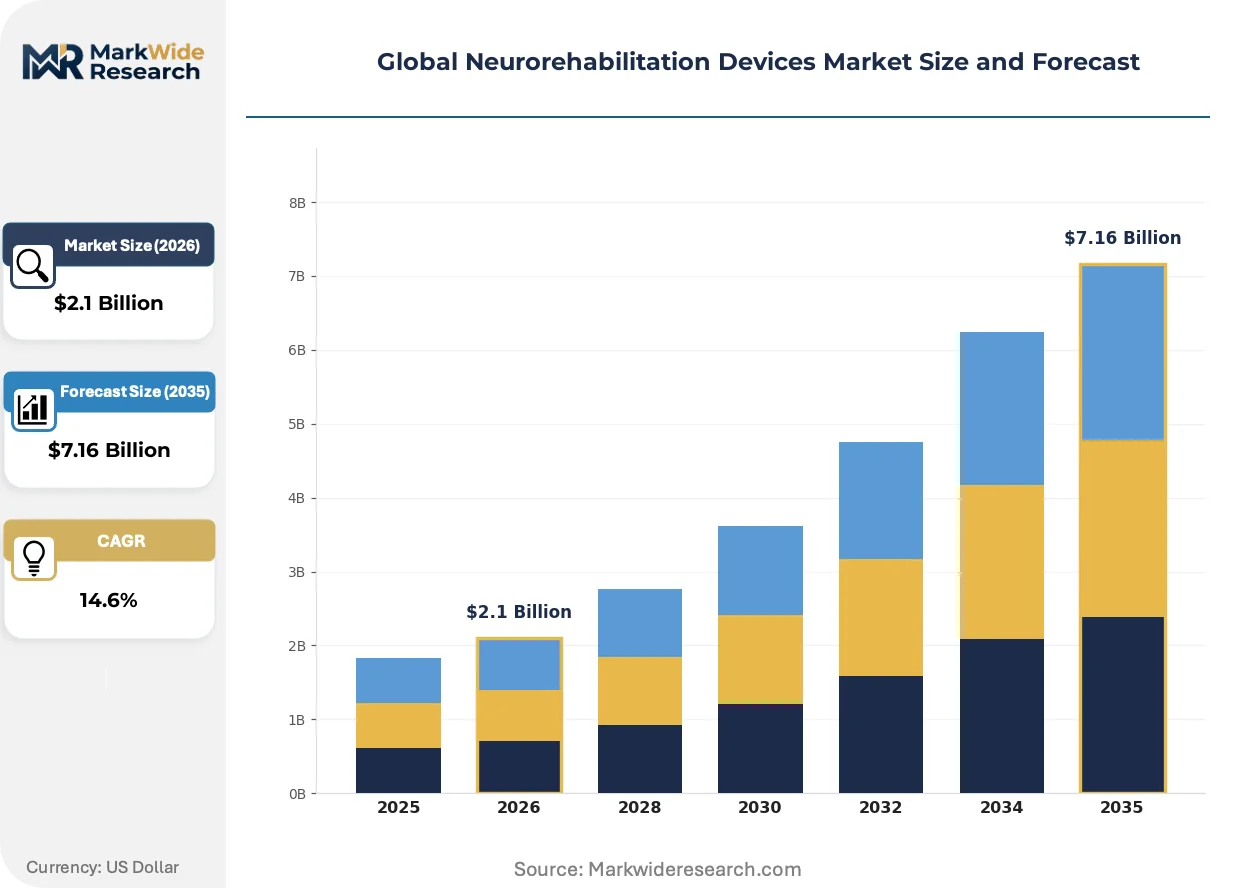
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Exoskeletons, Functional Electrical Stimulators, Virtual Reality Devices, Balance Trainers, Neuroprosthetics Technology: Brain-Computer Interface, Electromyography, Transcranial Magnetic Stimulation, Motion Sensors, Haptic Feedback Application: Stroke Rehabilitation, Traumatic Brain Injury, Spinal Cord Injury, Cerebral Palsy, Multiple Sclerosis End User: Rehabilitation Centers, Research Institutes, Home Care, Assisted Living Facilities, Outpatient Clinics |
| Companies Covered | Bionik Laboratories, Kinova Robotics, Medtronic, Tyromotion, ReWalk Robotics, Abbott Laboratories, Hocoma AG, Bioness, Ekso Bionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurorehabilitation Devices Market Shifts & Advancements
Non-invasive neural decoding is compressing the boundary between assistive and restorative rehabilitation modalities, enabling brain-computer interfaces to migrate from research environments into reimbursable clinical workflows.
Electroencephalography-based motor imagery training is rewriting therapeutic protocols for upper-limb paralysis. Academic medical centers in Pittsburgh and Heidelberg are deploying these systems in subacute stroke units, replacing conventional repetitive task practice with closed-loop neurofeedback that accelerates cortical reorganization timelines.
EMA pharmacovigilance obligations for device-drug combination products now extend to neurorehabilitation systems integrating local anesthetic delivery with implantable stimulators. Manufacturers must establish post-market surveillance infrastructure spanning multiple member states, disproportionately burdening mid-cap developers without existing European regulatory affairs capacity.
Hospital networks are consolidating rehabilitation equipment procurement through centralized value-analysis committees, displacing individual department purchasing autonomy. This concentration is most pronounced in Germany's university hospital clusters and Japan's regional healthcare associations, where multi-site framework agreements now govern 60-70% of robotic system acquisitions.
Global Neurorehabilitation Devices Market Segmentation
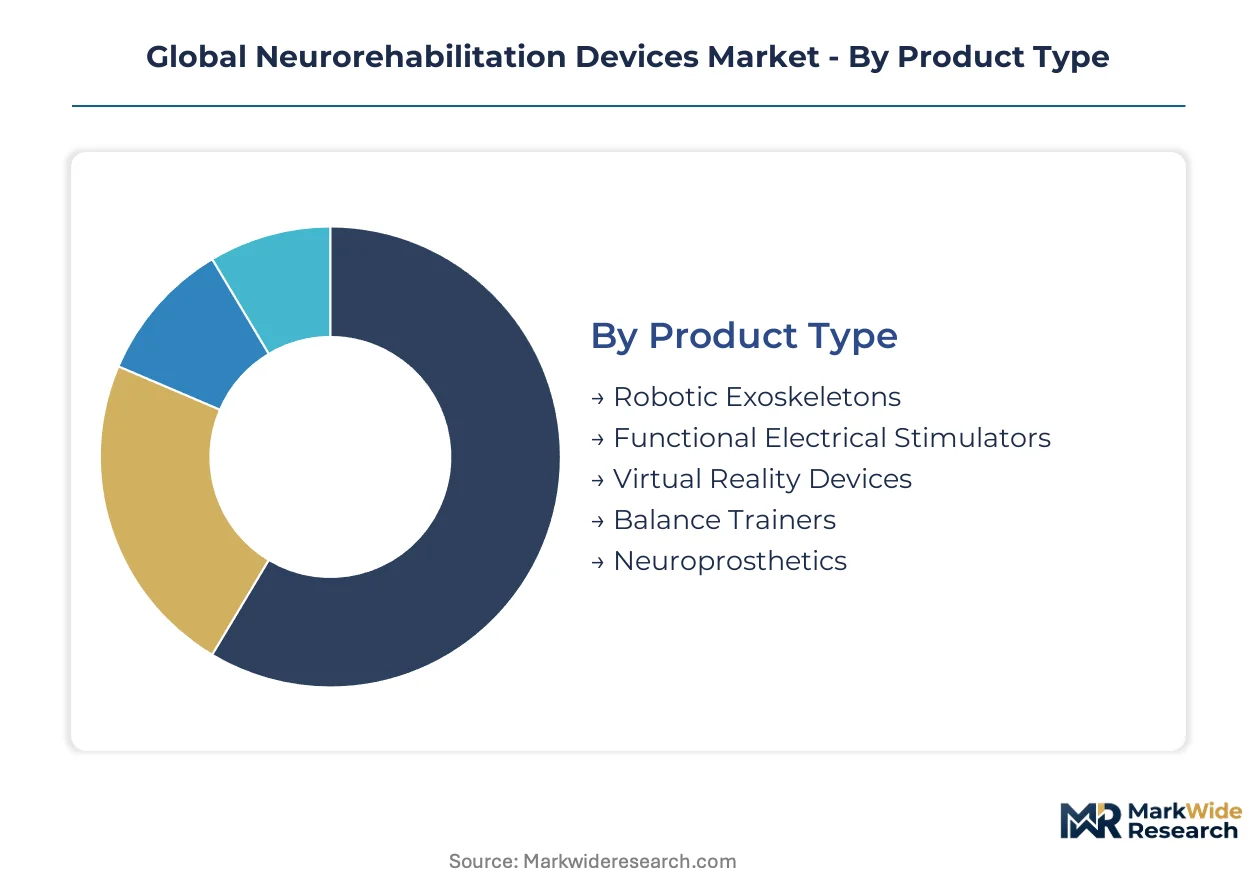
Segmentation in neurorehabilitation devices reveals how capital flows diverge between high-volume institutional purchasers and premium-priced specialized interventions. Understanding these splits enables vendors to align R&D investment with reimbursement realities across product categories.
Product Type:
Robotic exoskeletons command premium unit economics while functional electrical stimulators drive procedure volume in outpatient settings.
- Robotic Exoskeletons:Electromechanical wearable systems with adaptive gait algorithms and real-time force modulation. Hospital networks in Germany and Japan concentrate procurement through multi-site framework agreements, though 23-31% sensor hardware exposure creates supply volatility risks.
- Functional Electrical Stimulators:Implantable and surface electrode systems delivering targeted neuromuscular activation. Outpatient clinics across OECD member states are scaling purchases for subacute stroke transitions, accelerated by expanded reimbursement codes from Germany's Federal Joint Committee.
- Virtual Reality Devices:Immersive motor task environments with motion tracking and biofeedback integration.
- Balance Trainers:Sensor-equipped platforms for postural control rehabilitation in institutional settings.
- Neuroprosthetics:Implantable neural interface systems for sensory substitution or motor restoration.
Today's leader: Robotic Exoskeletons. Tomorrow's challenger: Neuroprosthetics.
Technology:
Non-invasive neural decoding is compressing development timelines while established sensing modalities retain installed-base dominance.
- Brain-Computer Interface:Electroencephalography decoding systems translating motor imagery into device control signals. Academic medical centers in Pittsburgh and Heidelberg are deploying these in reimbursable clinical workflows, displacing conventional repetitive task practice.
- Electromyography:Surface and intramuscular sensors capturing voluntary motor unit activation patterns. Rehabilitation centers in Boston and Singapore metropolitan clusters leverage this for closed-loop therapeutic modulation with sub-100-millisecond latency.
- Transcranial Magnetic Stimulation:Non-invasive cortical excitability modulation for neuroplasticity enhancement.
- Motion Sensors:Inertial measurement units and force-sensitive resistors for biomechanical tracking.
- Haptic Feedback:Tactile actuation systems providing sensory substitution or augmented proprioception.
Electromyography holds current volume leadership. Brain-Computer Interface is climbing the fastest as clinical-grade throughput achieves viability.
Application:
Stroke rehabilitation generates the largest addressable patient pool while spinal cord injury commands premium pricing per intervention cycle.
- Stroke Rehabilitation:Motor recovery interventions targeting hemiparesis, aphasia, and cognitive sequelae. Aging demographics across Germany, Japan, and the United States are expanding acute-to-subacute care transitions, with statutory health insurers driving access expansion.
- Spinal Cord Injury:Gait restoration and upper-limb function recovery for complete and incomplete lesions. Exoskeleton-assisted walking therapy in German rehabilitation centers achieves premium reimbursement positioning through Federal Joint Committee coding decisions.
- Traumatic Brain Injury:Cognitive-motor integration and behavioral regulation interventions.
- Cerebral Palsy:Pediatric gait training and spasticity management protocols.
- Multiple Sclerosis:Progressive disability mitigation and fatigue-resistant exercise modalities.
Stroke Rehabilitation dominates patient volume. Spinal Cord Injury maintains margin leadership through technology-intensive intervention requirements.
End User:
Institutional procurement concentration is displacing fragmented purchasing while home care modalities emerge at the margin.
- Rehabilitation Centers:Inpatient and outpatient facilities delivering intensive multidisciplinary therapy. Germany's university hospital clusters and Japan's regional healthcare associations now govern 60-70% of robotic system acquisitions through centralized value-analysis committees.
- Research Institutes:Academic medical centers and clinical trial sites advancing protocol development. Pittsburgh and Heidelberg deployments of brain-computer interface systems are establishing evidentiary foundations for reimbursement expansion.
- Home Care:Patient-directed rehabilitation with remote clinical oversight.
- Assisted Living Facilities:Residential care settings with embedded therapy services.
- Outpatient Clinics:Community-based rehabilitation with abbreviated intervention cycles.
Rehabilitation Centers anchor current revenue. Home Care represents the steepest expansion trajectory as wearable sensory feedback enables ambulatory modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurorehabilitation device manufacturing originated in Swiss and German precision engineering clusters during the 1990s, then expanded through Boston's medical technology corridor and Japan's robotics belt. Today's demand concentrates where aging demographics intersect with statutory reimbursement expansion and established rehabilitation infrastructure.
United States
FDA Class II and Class III pathways for neurostimulation systems drive clinical trial investment around Pittsburgh and Boston academic medical centers. The IRA's Medicare negotiation provisions pressure implantable device pricing, though CMS reimbursement codes for robotic gait training continue expanding. Massachusetts and Pennsylvania host the densest concentration of brain-computer interface research-to-commercialization pipelines.
Germany
Germany's Federal Joint Committee reimbursement decisions for exoskeleton-assisted walking therapy determine accessible patient volumes across the EU. The EU MDR's 18-36 month certification timelines favor established manufacturers with mature quality management systems. Bavaria and Baden-Württemberg anchor production of balance and locomotion systems for university hospital networks.
Japan
METI's robotics industry subsidies accelerate deployment of gait trainers in regional healthcare associations. PMDA's streamlined approval for designated medical devices reduces time-to-market for novel neurostimulation hardware. The Kansai corridor around Osaka concentrates manufacturing partnerships between rehabilitation equipment makers and precision motor suppliers.
India
The PLI scheme for medical devices reduces import duty exposure for electromechanical rehabilitation hardware, enabling domestic assembly cost advantages. CDSCO's evolving framework for active implantable devices creates regulatory navigation complexity for foreign entrants. Karnataka and Maharashtra are attracting contract manufacturing investments from European exoskeleton developers seeking tariff-efficient export platforms.
Switzerland
Swissmedic's alignment with EU MDR standards permits streamlined market access for neuroprosthetic developers. Zurich's metropolitan cluster concentrates cross-functional engineering talent spanning biomechanical modeling and embedded systems. The country's precision manufacturing heritage supports high-mix, low-volume production of sensor-integrated rehabilitation platforms.
Global Neurorehabilitation Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clinical evidence depth and regulatory pathway sophistication. The vendor base stratifies between diversified medical technology conglomerates with multi-therapeutic R&D infrastructure and specialized exoskeleton developers with concentrated gait-training expertise. Three archetypes dominate: established neurostimulation multinationals, robotic hardware specialists, and emerging brain-computer interface platforms. Competitive moves center on M&A for regulatory capability acquisition and strategic partnerships for distribution reach in concentrated hospital procurement systems.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories exemplify the multi-therapeutic R&D archetype, leveraging neurostimulation infrastructure across cardiac, pain management, and neurological applications. Ekso Bionics and ReWalk Robotics occupy positions within the specialized exoskeleton tier, while Hocoma AG represents the European-installed-base dominance model in balance and locomotion systems. These named entities anchor competitive positioning without constraining the full spectrum of market participation.
| Leading Market Players |
|---|
| Bionik Laboratories |
| Kinova Robotics |
| Medtronic |
| Tyromotion |
| ReWalk Robotics |
| Abbott Laboratories |
| Hocoma AG |
| Bioness |
| Ekso Bionics |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation through Germany's Federal Joint Committee reimbursement expansions is compressing vendor margins while forcing supply chain reconfiguration toward modular, serviceable hardware architectures that satisfy EU Green Deal lifecycle assessment criteria.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared neurostimulation systems from CE-marked electromechanical devices and unregulated wellness-grade alternatives. Price differentiation rests on clinical evidence depth and regulatory pathway sophistication rather than raw component specifications. Cost compression in the standard tier is intensifying because India's PLI scheme enables domestic assembly cost advantages against European incumbents. Outpatient clinics exhibit highest price sensitivity due to capital constraints, while university hospital networks prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Direct-to-institution channels handle concentrated demand from Germany's university hospital clusters and Japan's regional healthcare associations. Manufacturing draws from Swiss precision engineering heritage, German electromechanical component suppliers, and Taiwanese semiconductor foundries for force-sensitive resistors and inertial measurement units. Single-source vulnerability in sensor hardware creates exposure to semiconductor supply volatility. Distribution runs through specialized medical device distributors with GPO contracts and field service capabilities rather than generalist logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory milestones, with EU MDR certification timelines for active implantable devices creating durable competitive moats that accelerate demand concentration toward established quality management system holders.
For Market Incumbents: Anticipate reimbursement code expansions by preemptively investing in 12-month functional independence measure clinical trials that satisfy FDA Class III premarket approval endpoints. Consolidate vendor relationships with Germany's Federal Joint Committee to secure framework agreement positioning ahead of outpatient rehabilitation cycle expansions. Vertical integration into sensor hardware production mitigates semiconductor supply volatility exposure.
For New Entrants and Emerging Players: Capture India's PLI scheme manufacturing incentives to establish tariff-efficient export platforms serving European rehabilitation centers. India's domestic assembly cost advantages represent the most penetrable geography for price-competitive positioning against Hocoma AG and Ekso Bionics installations. Pursue CDSCO regulatory navigation partnerships with established European developers lacking Indian regulatory affairs capacity.
For Investors and Strategic Acquirers: Asymmetric upside sits with brain-computer interface platforms achieving clinical-grade electroencephalography decoding throughput. Long-term viability over the projection horizon favors developers with simultaneous competence in biomechanical modeling, embedded systems, and clinical trial design concentrated in Zurich, Boston, and Singapore metropolitan clusters. Watch for Federal Joint Committee coding decisions on non-invasive neural decoding as the inflection indicator for reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified-body conformity assessment for active implantable devices extends competitive moats for established manufacturers. |
| Hospital System Partnership | Multi-site framework agreements with Germany's university hospital clusters govern 60-70% of robotic system acquisitions. |
| Software Companion Development | Sub-100-millisecond latency adaptive actuation algorithms enable closed-loop therapeutic modulation previously unattainable. |
| Reimbursement Strategy | Federal Joint Committee coding decisions for exoskeleton-assisted walking therapy determine accessible patient volumes. |
| CE Marking Pathway | Swissmedic alignment with EU MDR standards permits streamlined market access for neuroprosthetic developers. |
Research Methodology
Bottom-up rehabilitation center procurement modeling reconciled against top-down electromechanical hardware production tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified-body certificates, hospital procurement databases, and CMS Medicare reimbursement data. Triangulation across stakeholder perspectives and regulatory documentation ensures segmentation alignment with institutional purchasing realities.
Historical trendline analysis of robotic exoskeleton installations and functional electrical stimulator procedure volumes established baseline growth patterns across the projection horizon. The analytical framework models product type, technology modality, application severity, and end-user setting segmentation dimensions. CAGRs derive from regression analysis against aging demographic trajectories, reimbursement expansion schedules, and regulatory pathway completion timelines. Forecast inputs include semiconductor supply volatility indices and Federal Joint Committee coding decision calendars.
EU MDR certification timeline extensions, semiconductor supply disruptions, and Federal Joint Committee reimbursement reversals are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market